
 Spin Filters Market | 2026-2036
Spin Filters Market Size, Share, and Industry Trends Forecast 2026-2036
Spin Filters Market Outlook
Centrifugal-membrane hybrid architectures is narrowing the performance gap between conventional depth filtration and high-purity membrane separation. Pall Corporation leverages its vertically integrated membrane manufacturing to control supply chains for biopharmaceutical grade spin filters. Thermo Fisher Scientific anchors its position through R&D intensity in single-use filtration technologies for cell culture applications. Donaldson Company competes on manufacturing scale in industrial air and liquid spin filtration for heavy equipment OEMs.
Spin filters are rotational separation devices that employ centrifugal force combined with porous or surface-modified media to remove particulates, droplets, or dissolved contaminants from fluid streams, typically operating at rotational speeds from hundreds to thousands of RPM depending on application severity. Their primary industrial purpose centers on achieving high-throughput purification without the fouling penalties associated with static membrane systems, particularly in processes handling high-solids-load feeds. Magnetic spin filtration leads in installed base across oil recovery and chemical processing sectors where ferrous contaminant removal dominates operational requirements. Nanotechnology-enabled surface coatings represent the fastest-expanding technology segment as pharmaceutical end users demand validated biofouling resistance for repeated sterilization cycles. Environmental end users occupy a mature, price-sensitive position where municipal water treatment procurement favors mechanical simplicity over advanced hybrid architectures.
EPA effluent limitation guidelines shape product design for U.S. environmental and manufacturing end users by mandating demonstrable contaminant removal efficiencies before discharge permitting. The EU REACH regulation and MDR framework for pharmaceutical equipment respectively constrain coating chemistry selections and validate materials of construction for patient-contact applications. FDA process validation requirements for sterile drug manufacturing create demand documentation burdens that favor established suppliers with prior regulatory submission histories. Stakeholders must monitor how tightening PFAS discharge rules across multiple jurisdictions redirect procurement toward coated or ceramic spin filter media resistant to aggressive cleaning chemistries.
Market Dynamics
Hybrid centrifugal-membrane architectures are compressing the historical performance gap between depth filtration and high-purity membrane separation, forcing incumbent suppliers to reconfigure R&D roadmaps and manufacturing footprints around integrated system platforms.
Growth Catalysts
- EU Water Framework Directive enforcement:Germany's chemical processing corridor has accelerated replacement of conventional separation systems with hybrid spin-membrane configurations for solvent recovery operations.
- Single-use bioprocessing expansion:Pharmaceutical manufacturers in North America and Europe are deploying spin filters for sterile filtration workflows to reduce cross-contamination risk between production batches.
- Nanotechnology surface coatings:Biofouling-resistant coatings validated for repeated sterilization cycles are expanding addressable demand in pharmaceutical sterile manufacturing applications.
Market Restraints
- High-purity membrane raw material concentration:Specialized polymer and ceramic membrane substrates concentrate among a limited supplier base in Germany and Japan, creating input cost volatility and supply security exposure.
- Regulatory documentation burdens:FDA process validation requirements for sterile drug manufacturing create demand documentation thresholds that favor established suppliers with prior regulatory submission histories, raising barriers for new entrants.
- Static membrane substitution in price-sensitive segments:Municipal water treatment procurement favors mechanical simplicity over advanced hybrid architectures, limiting spin filter penetration in environmental end-use applications.
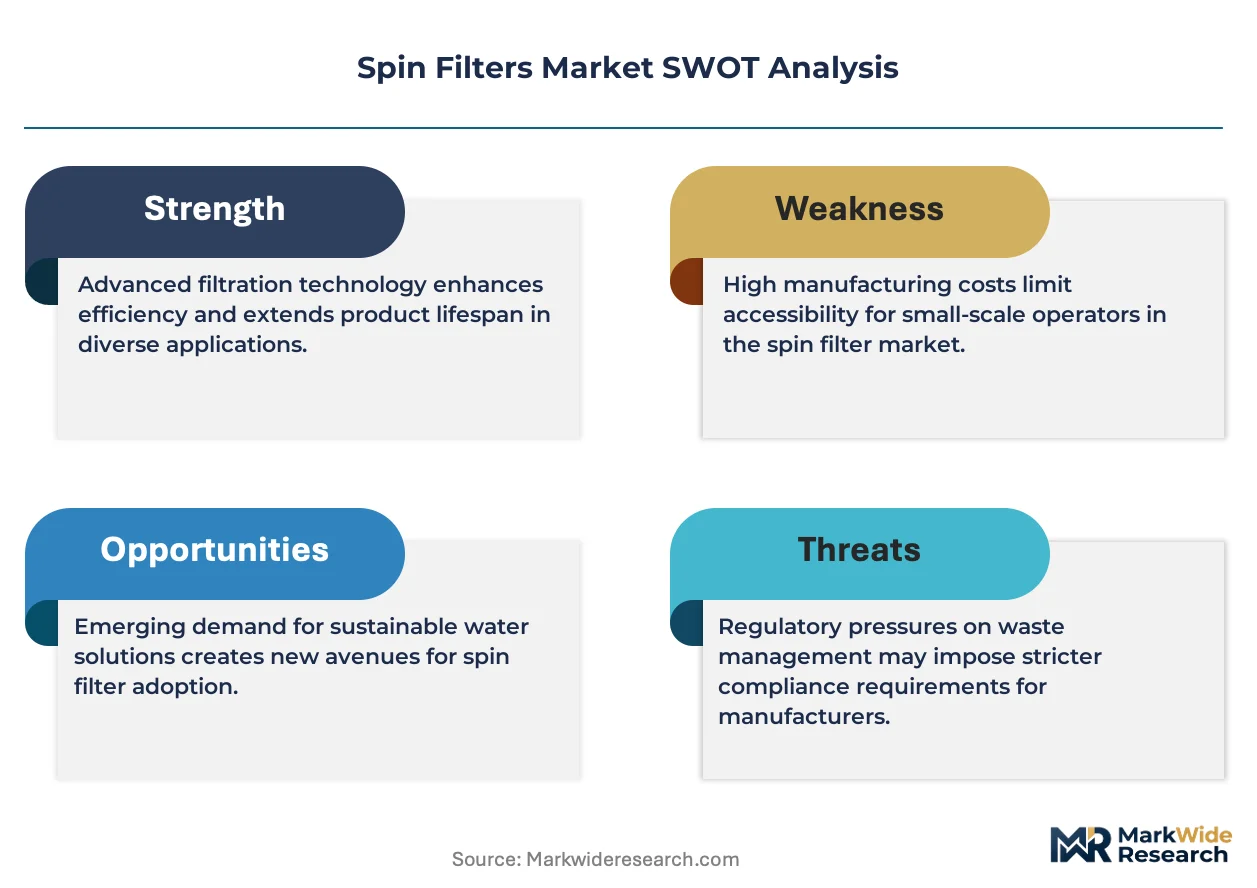
Strategic Opportunities
- PFAS discharge rule tightening:Multiple US state jurisdictions are redirecting procurement toward coated or ceramic spin filter media resistant to aggressive cleaning chemistries for industrial wastewater applications.
- Magnetic spin filtration expansion:Oil recovery operations in the Middle East present underpenetrated demand for ferrous contaminant removal systems with lower operational complexity than conventional separation trains.
- Cell culture media preparation:Emerging single-use filtration demand in contract manufacturing organizations is creating channel expansion opportunities bypassing traditional capital equipment sales cycles.
Industry Challenges
- Bioprocessing integration complexity:Spin filter deployment requires specialized field engineering to integrate with existing stainless steel infrastructure and automated process control systems without disrupting validated workflows.
- Cross-functional talent scarcity:The convergence of centrifugal mechanics, membrane science, and pharmaceutical process validation has created acute shortages of engineers capable of supporting hybrid system specification and commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spin Filters Market |
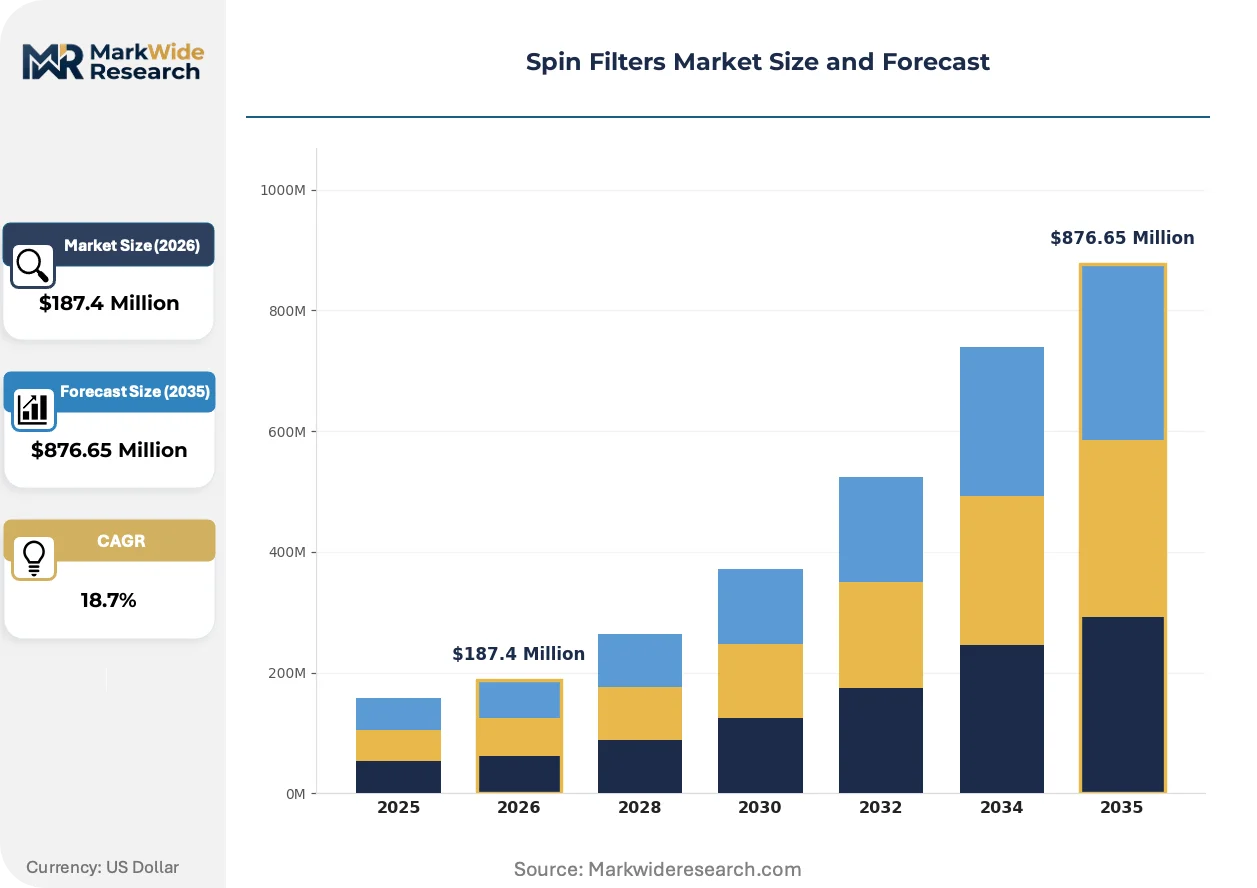
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic, Electrostatic, Hybrid, Mechanical Application: Water Treatment, Oil Recovery, Chemical Processing, Air Filtration End User: Manufacturing, Oil & Gas, Pharmaceutical, Environmental Technology: Nanotechnology, Membrane Separation, Surface Coating, Photocatalysis |
| Companies Covered | Pall Corporation, Thermo Fisher Scientific, Eaton Corporation, Donaldson Company, Parker Hannifin, SpinTek Filtration, MANN+HUMMEL, 3M, Entegris, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spin Filters Market Strategic Shifts
Active materials innovation and regulatory chemistry constraints are reshaping competitive positioning in separation technology, with surface engineering and modular architectures displacing incremental improvements in legacy formats.
Centrifugal-membrane hybrid architectures is hybridizing the functional boundaries between conventional depth filtration and high-purity membrane separation. Pharmaceutical sterile manufacturers are adopting these integrated platforms at accelerating pace to consolidate purification trains and reduce footprint requirements. This convergence is hybridizing supplier value propositions around system-level performance guarantees rather than discrete component specifications.
REACH regulation constraints on coating chemistry selections are forcing reformulation of surface-modified spin filter media across European pharmaceutical and chemical processing installations. Industrial consequences include extended validation timelines and materials qualification costs that compress margins on standard-grade product lines. German chemical processors and French pharmaceutical facilities are responding by consolidating procurement around suppliers with established ECHA registration dossiers and pre-qualified coating platforms.
Specification authority is migrating from plant engineering departments to centralized procurement functions with enterprise-level sustainability mandates. Traditional distributor channels serving regional industrial accounts are losing share to direct manufacturer relationships and digital specification platforms that consolidate technical documentation and regulatory compliance data. This pattern is most visible in North American biopharmaceutical manufacturing, where corporate sustainability offices now mandate supplier ESG disclosure as a gate to vendor qualification processes.
Spin Filters Market Segmentation
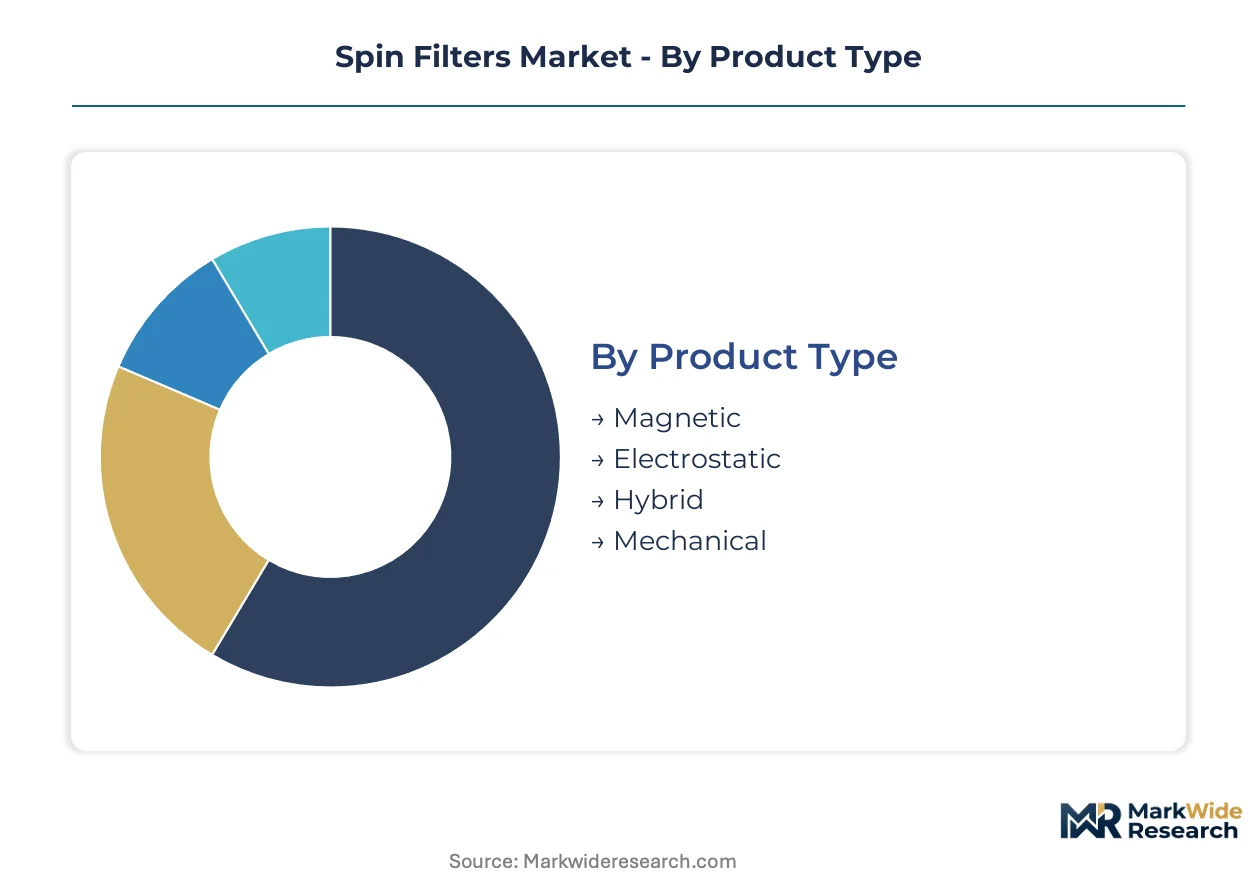
Spin filter deployment varies sharply across process conditions, regulatory exposure, and contamination profiles. Segmentation reveals how technology choices map to operational economics and compliance thresholds in distinct industrial workflows.
Product Type:
The use-case spectrum spans ferrous contaminant removal in heavy industry through precision hybrid systems for sterile manufacturing.
- Magnetic:Permanent magnet or electromagnet configurations extract ferromagnetic particles from lubricants and hydraulic fluids. Demand concentrates in oil recovery operations across the Middle East where wellhead fluids carry high iron sulfide loads and operational simplicity outweighs membrane complexity.
- Hybrid:Centrifugal-membrane architectures combine rotational separation with surface-modified media for high-purity output. German chemical processors at BASF and Bayer facilities deploy these for solvent recovery, driven by EU Water Framework Directive discharge mandates that exceed conventional system capabilities.
- Electrostatic:Charged field separation targets sub-micron aerosols and dielectric contaminants in compressed gas streams. Semiconductor fabrication facilities in Japan specify these for process gas conditioning.
- Mechanical:Pure centrifugal designs without active surface media serve coarse solids separation in mining slurry and construction dewatering. Municipal procurement in price-sensitive environmental segments favors this format for mechanical simplicity.
The dominant share belongs to Magnetic, while Hybrid is closing the gap fastest.
Application:
Volume concentration tracks industrial water intensity and discharge regulation severity across processing corridors.
- Chemical Processing:Solvent recovery and catalyst separation in continuous flow reactors demand corrosion-resistant spin filter materials. The Rhine-Ruhr chemical cluster in Germany has accelerated replacement of static separators with hybrid architectures to meet tightening effluent limits.
- Water Treatment:Municipal and industrial wastewater polishing employs spin filtration for suspended solids reduction prior to membrane bioreactors. Procurement patterns in US municipal markets favor mechanical simplicity over advanced coatings due to capital constraint protocols.
- Oil Recovery:Produced water treatment and drilling mud conditioning use magnetic and hybrid systems for ferrous contaminant control. Middle Eastern national oil companies are expanding deployment as field maturity increases water cut ratios.
- Air Filtration:Compressed air and process gas conditioning in pharmaceutical cleanrooms specifies electrostatic and hybrid spin filters for particulate and microbial control. FDA process validation requirements favor suppliers with prior regulatory submission histories.
Chemical Processing commands the largest installed base, though Water Treatment is expanding most quickly as discharge standards tighten across multiple jurisdictions.
End User:
Margin structures diverge between validated pharmaceutical supply and price-competitive environmental procurement.
- Pharmaceutical:Sterile drug manufacturing requires spin filters with validated biofouling resistance and documented materials of construction. North American and European manufacturers deploy single-use configurations to eliminate cross-contamination risk between production batches.
- Oil & Gas:Upstream and midstream operations prioritize magnetic separation for ferrous debris in hydrocarbon streams. Operational environments favor ruggedized mechanical designs over coating-dependent architectures.
- Manufacturing:General industrial process water and coolant recycling spans automotive, electronics, and metalworking sectors. Specification authority is migrating from plant engineering to centralized procurement with enterprise sustainability mandates.
- Environmental:Municipal wastewater and remediation applications represent mature, price-sensitive demand where procurement favors lowest lifecycle cost over technical sophistication. EPA effluent limitation guidelines shape product design for US environmental end users.
Pharmaceutical generates the highest margin pool, while Manufacturing offers the broadest volume foundation.
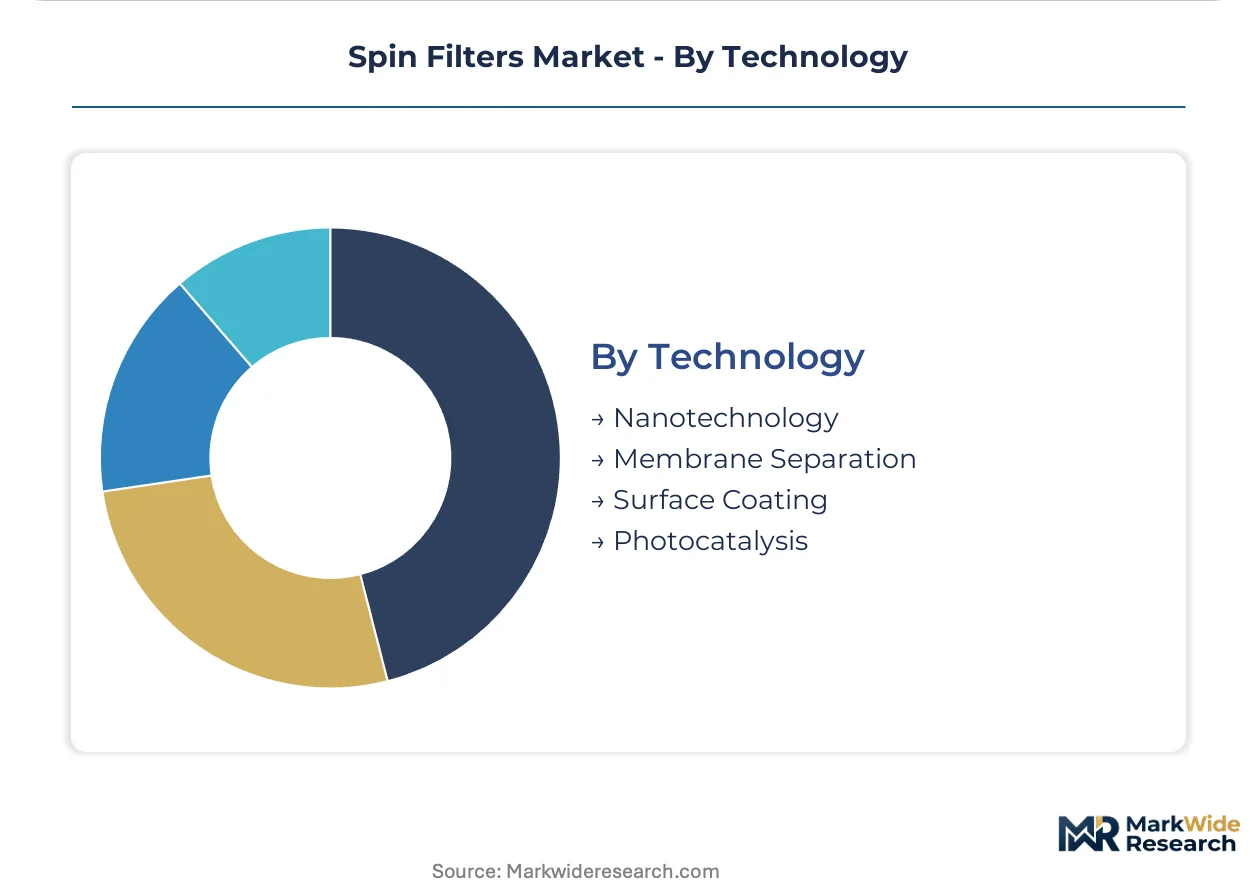
Technology:
Surface engineering intensity determines competitive differentiation and validation burden in regulated applications.
- Nanotechnology:Engineered surface coatings deliver biofouling resistance and chemical durability for repeated sterilization cycles. Pharmaceutical sterile manufacturers in France and Switzerland specify these for validated cleaning protocols under EU MDR frameworks.
- Membrane Separation:Porous polymer or ceramic substrates integrated with centrifugal force achieve high-purity separation without static fouling. REACH regulation constraints on coating chemistry selections force reformulation across European installations.
- Surface Coating:Functionalized layers modify wettability, charge, or catalytic activity for targeted contaminant binding. PFAS discharge rule tightening in multiple US states redirects procurement toward ceramic and coated media resistant to aggressive cleaning chemistries.
- Photocatalysis:UV-activated semiconductor surfaces degrade organic contaminants in advanced oxidation configurations. Pilot deployments in Japanese industrial water treatment test integration with spin filtration mechanics.
Membrane Separation anchors current revenue, yet Nanotechnology is gaining share fastest as pharmaceutical validation requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German spin filter exports supply pharmaceutical manufacturers across Switzerland and France, while Japanese ceramic membrane producers serve semiconductor fabrication demand in South Korea and Taiwan.
United States
Pharmaceutical sterile manufacturing in Massachusetts and North Carolina drives single-use spin filter procurement for cell culture applications. EPA effluent limitation guidelines mandate demonstrable contaminant removal efficiencies before discharge permitting for environmental end users. The Gulf Coast petrochemical corridor around Houston deploys hybrid spin-membrane systems for produced water treatment as field maturity increases water cut ratios.
Germany
BASF and Bayer facilities in the Rhine-Ruhr chemical cluster accelerate replacement of conventional separation systems with hybrid architectures. EU Water Framework Directive enforcement exceeds conventional system capabilities for solvent recovery operations. The country's specialized polymer and ceramic membrane substrate suppliers concentrate in Baden-Württemberg, creating input cost volatility exposure for downstream fabricators.
Japan
Semiconductor fabrication facilities in the Kansai region specify electrostatic spin filters for process gas conditioning and sub-micron aerosol removal. METI industrial water treatment pilots test photocatalytic oxidation integration with spin filtration mechanics. Osaka-based membrane technology developers supply ceramic substrates to pharmaceutical equipment manufacturers in Switzerland and France under REACH-compliant coating platforms.
Switzerland
Pharmaceutical sterile manufacturers in Basel and Geneva demand nanotechnology-enabled surface coatings with validated biofouling resistance for repeated sterilization cycles. Swissmedic and EU MDR frameworks constrain materials of construction for patient-contact applications. The country's precision engineering cluster supplies centrifugal mechanics expertise to hybrid system integrators serving French and German chemical processors.
India
Contract manufacturing organizations in Maharashtra and Gujarat create channel expansion opportunities for single-use filtration technologies bypassing traditional capital equipment sales cycles. CDSCO process validation requirements for sterile drug manufacturing favor suppliers with prior regulatory submission histories. The Mumbai-Pune pharmaceutical corridor integrates spin filters into biosimilar production workflows as export orientation intensifies.
Spin Filters Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered supply configurations. The market structure consolidates around vertically integrated membrane manufacturers and diversified filtration conglomerates with established regulatory submission histories. Three archetypes dominate: system integrators with pharmaceutical validation expertise, industrial-scale manufacturers serving heavy equipment OEMs, and ceramic substrate specialists controlling critical raw material supply. Dominant competitive moves include strategic partnerships for bioprocessing integration and geographic expansion into Middle Eastern oil recovery operations.
Among US-based diversified technology conglomerates, Pall Corporation and Thermo Fisher Scientific exemplify the pharmaceutical-validation archetype through captive membrane manufacturing and R&D intensity in single-use configurations. Donaldson Company anchors the industrial-scale manufacturing position with heavy equipment OEM relationships. German filtration specialists including MANN+HUMMEL occupy the European industrial vector with established ECHA registration dossiers and pre-qualified coating platforms serving chemical processing demand.
| Leading Market Players |
|---|
| Pall Corporation |
| Thermo Fisher Scientific |
| Eaton Corporation |
| Donaldson Company |
| Parker Hannifin |
| SpinTek Filtration |
| MANN+HUMMEL |
| 3M |
| Entegris |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's specialized polymer and ceramic membrane substrate suppliers concentrate upstream capacity, creating input cost volatility that compresses margins for downstream spin filter fabricators serving pharmaceutical and chemical processing demand across Europe and North America.
Pricing Analysis
Cost-plus contracts with polyether sulfide and ceramic powder indexation dominate procurement between German substrate specialists and hybrid system integrators. Three-tier pricing structure across pharmaceutical-grade validated systems, industrial process configurations, and mechanical-only units separates segments by certification burden and sterilization protocol complexity. Pricing pressure stems from REACH-driven coating reformulation costs that extend validation timelines for European pharmaceutical installations. Municipal water treatment buyers exhibit highest price sensitivity, while sterile drug manufacturers accept premium positioning for documented regulatory submission histories.
Supply Chain Analysis
Polyether sulfide resin, zirconia ceramic powder, and rare-earth magnetic feedstock draw from concentrated supply bases in Germany, Japan, and China. Specialized membrane substrate fabrication clusters in Baden-Württemberg and Osaka prefecture create single-source vulnerability for pharmaceutical-grade hybrid system manufacturers. Distribution runs through direct manufacturer relationships with biopharmaceutical OEMs and regional industrial distributors serving price-sensitive environmental accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers capable of integrating centrifugal mechanics, membrane science, and pharmaceutical process validation represent the critical capability gap constraining hybrid system deployment velocity across North American and European bioprocessing corridors.
For Market Incumbents: Harden regulatory dossier depth against emerging ceramic substrate specialists from Japan seeking European pharmaceutical qualification. Deepen backward integration into membrane coating platforms to capture margin compression from REACH-driven reformulation cycles. Prioritize captive supply of polyether sulfide substrates to reduce Baden-Württemberg supplier concentration risk. For New Entrants and Emerging Players: Pursue contract manufacturing organization channel expansion in Maharashtra and Gujarat where CDSCO validation requirements favor suppliers with prior regulatory submission histories. Target single-use filtration demand in biosimilar production workflows as Indian pharmaceutical export orientation intensifies. Lead with digital specification platforms that consolidate technical documentation and ESG disclosure data for centralized procurement functions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic substrate specialists with established ECHA registration dossiers and pre-qualified coating platforms serving EU pharmaceutical demand. Five-to-ten year viability hinges on nanotechnology surface coating validation for repeated sterilization cycles under tightening MDR frameworks. Monitor PFAS discharge rule adoption velocity across US state jurisdictions as inflection indicator for coated media demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Substrates | Captures margin from Baden-Württemberg supplier concentration and reduces REACH-driven input volatility. |
| Single-Use Bioprocessing Platform Launch | Addresses cross-contamination risk requirements from FDA process validation guidelines for cell culture applications. |
| Photocatalytic Oxidation Integration | Tests METI pilot configurations for advanced industrial water treatment in Japanese semiconductor fabrication corridors. |
| Middle East Oil Recovery Expansion | Deploys magnetic spin filtration for ferrous contaminant control as field maturity increases water cut ratios. |
| Digital Specification Platform Development | Consolidates regulatory compliance data for centralized procurement functions with enterprise sustainability mandates. |
Study Parameters
The analysis maps magnetic, hybrid, electrostatic, and mechanical spin filter architectures, each validated through interviews with bioprocessing engineers, pharmaceutical procurement directors, chemical plant maintenance managers, and membrane technology R&D leads. Secondary sources include EPA effluent limitation guidelines, ECHA REACH registration dossiers, FDA process validation guidance documents, and EU MDR technical documentation requirements. Bottom-up unit demand estimates triangulate against top-down industry spend patterns across pharmaceutical, oil and gas, manufacturing, and environmental end-use segments.
Fixed assumptions include continued enforcement of EU Water Framework Directive discharge standards and steady-state FDA process validation documentation burdens; variable parameters span PFAS discharge rule adoption velocity across US states and Middle Eastern oil field water cut trajectories. Modeled dimensions encompass product type, application, end user, and technology segments, with regional production hub clustering as an overlay. CAGRs derive from segment-level demand buildups validated against input cost elasticity and substitution threat assessments from static membrane technologies.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Japanese ceramic substrate specialists or accelerated REACH coating bans would shift outcomes. Cross-checking against ECHA registration database trends and EPA effluent guideline revision schedules is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
VCSEL Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
DNA Chromatography Chip Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
APAC Semiconductor Device for Industrial Applications Market
Semiconductor Devices
Multi-Chip Module (MCM) Market
Semiconductor Devices
Silicon Carbide Mosfets Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Global Gan Semiconductor Device Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
3D TSV Device Market
Semiconductor Devices
Global Zener Diode Market
Semiconductor Devices
Gan and Sic Power Semiconductor Market
Semiconductor Devices
Global Switched Capacitor Filter Market
Semiconductor Devices
IGCT Market
Semiconductor Devices
Home Appliance MCU Market