
 PVC-Free Cap Liners Market | 2026-2036
PVC-Free Cap Liners Market Size, Share, and Industry Trends Forecast 2026-2036
PVC-Free Cap Liners Market Analytics
ISO 15378 certification for primary packaging materials is bifurcating the competitive landscape into qualified pharmaceutical-grade suppliers and generalist converters. Selig Group leverages its European manufacturing base to sustain certification-intensive relationships with drug packaging buyers. Tekni-Plex, Inc. anchors North American supply through controlled polymer sourcing and in-house lamination capabilities.
PVC-free cap liners are multilayer sealing inserts composed of polyethylene, polypropylene, or non-woven substrates bonded with heat-activated or pressure-sensitive adhesives, engineered to prevent contamination, maintain headspace integrity, and eliminate plasticizer migration risks in sensitive contents. Foam liners dominate volume in cosmetics and household segments where cost sensitivity outweighs barrier performance requirements, while induction liners command premium positioning in pharmaceuticals due to hermetic seal reliability and tamper evidence. Polypropylene-based heat seal liners represent the fastest-expanding material-format pairing as converters optimize for broader chemical resistance and lower seal-initiation temperatures.
EMA pharmaceutical packaging guidelines and REACH Annex XVII PVC restrictions shape European product development timelines and raw material qualification protocols. FDA extractables and leachables testing requirements for container closure systems extend compliance burdens to U.S. suppliers serving generic and branded drug makers. Stakeholders must monitor evolving state-level packaging extended producer responsibility frameworks and polymer-specific disclosure mandates that could redefine cost structures and regional sourcing priorities.
Market Dynamics
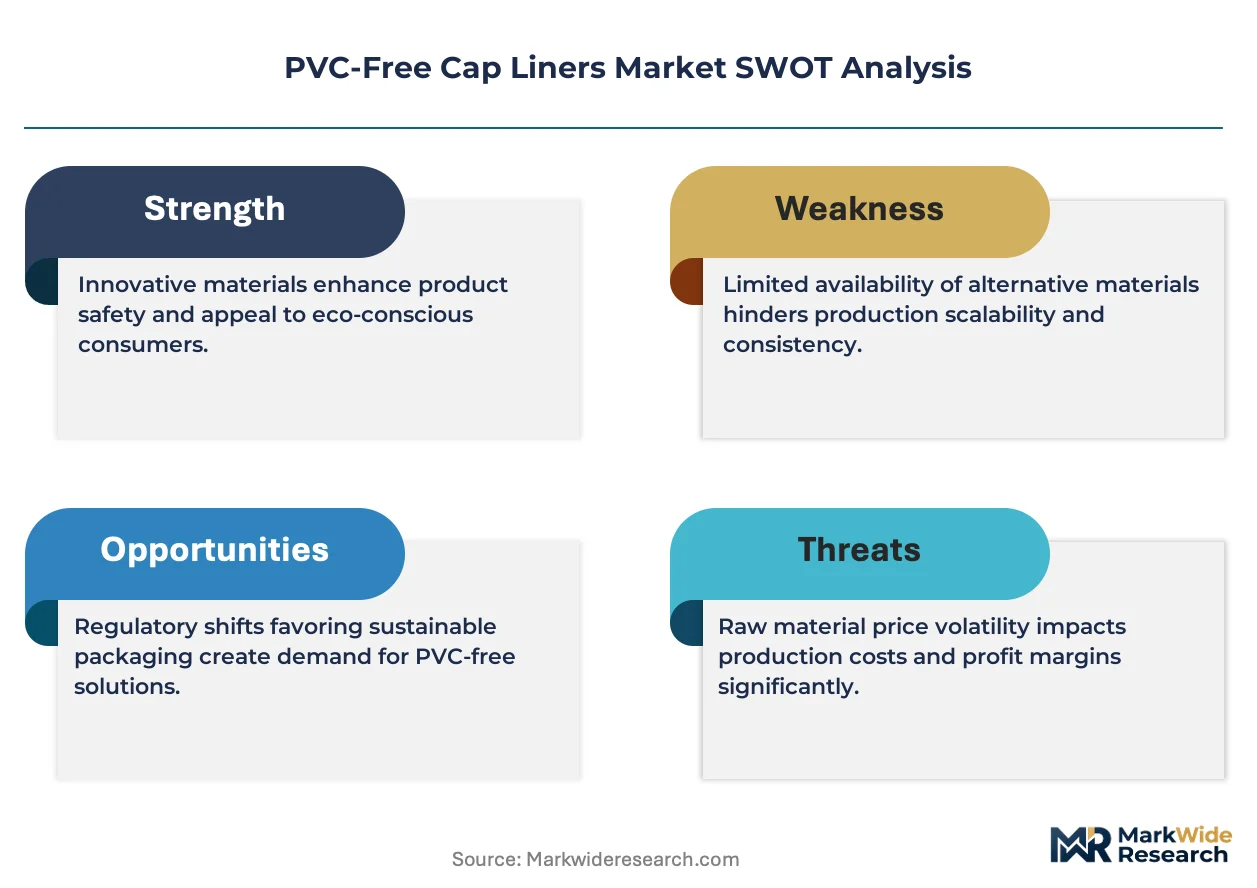
REACH Annex XVII restrictions on PVC additives are forcing pharmaceutical and cosmetics formulators to requalify entire container closure systems, converting specification inertia into active material substitution programs.
Growth Catalysts
- EMA pharmaceutical packaging guidelines:Updated stability testing protocols now explicitly screen for plasticizer migration, accelerating liner replacement cycles in European drug manufacturing.
- Induction sealing technology:Hermetic seal reliability and tamper-evident properties are displacing foam liners in parenteral and oral solid dose packaging.
- German converter concentration:Meyer Seals GmbH and specialized laminators near Frankfurt and Hamburg maintain ISO 15378-certified capacity that qualified buyers preferentially source.
Market Restraints
- Polyolefin resin price volatility:Ethylene and propylene feedstock fluctuations compress converter margins and complicate long-term contract pricing with pharmaceutical buyers.
- Limited qualified adhesive suppliers:Heat-activated and pressure-sensitive formulations meeting extractables-leachables thresholds concentrate among three European chemical specialists.
- Substitution from aluminum foil composites:Some cosmetics brands revert to full-aluminum seals where barrier performance outweighs sustainability positioning.
Strategic Opportunities
- Indian pharmaceutical exports:CDSCO alignment with ICH stability guidelines creates demand for REACH-compliant liner systems in formulations destined for European markets.
- Biologic drug containment:Cell and gene therapies requiring ultra-low extractable profiles favor polypropylene-based heat seal liners over conventional multilayer constructions.
- Direct converter relationships:Brand owners are bypassing distributors to secure dedicated lamination capacity and custom barrier specifications.
Industry Challenges
- ISO 15378 audit timelines:Eighteen-month certification cycles delay new supplier qualification and freeze specification changes mid-program.
- Legacy filling line compatibility:Induction sealing equipment retrofits require capital expenditure that mid-tier generics manufacturers defer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVC-Free Cap Liners Market |
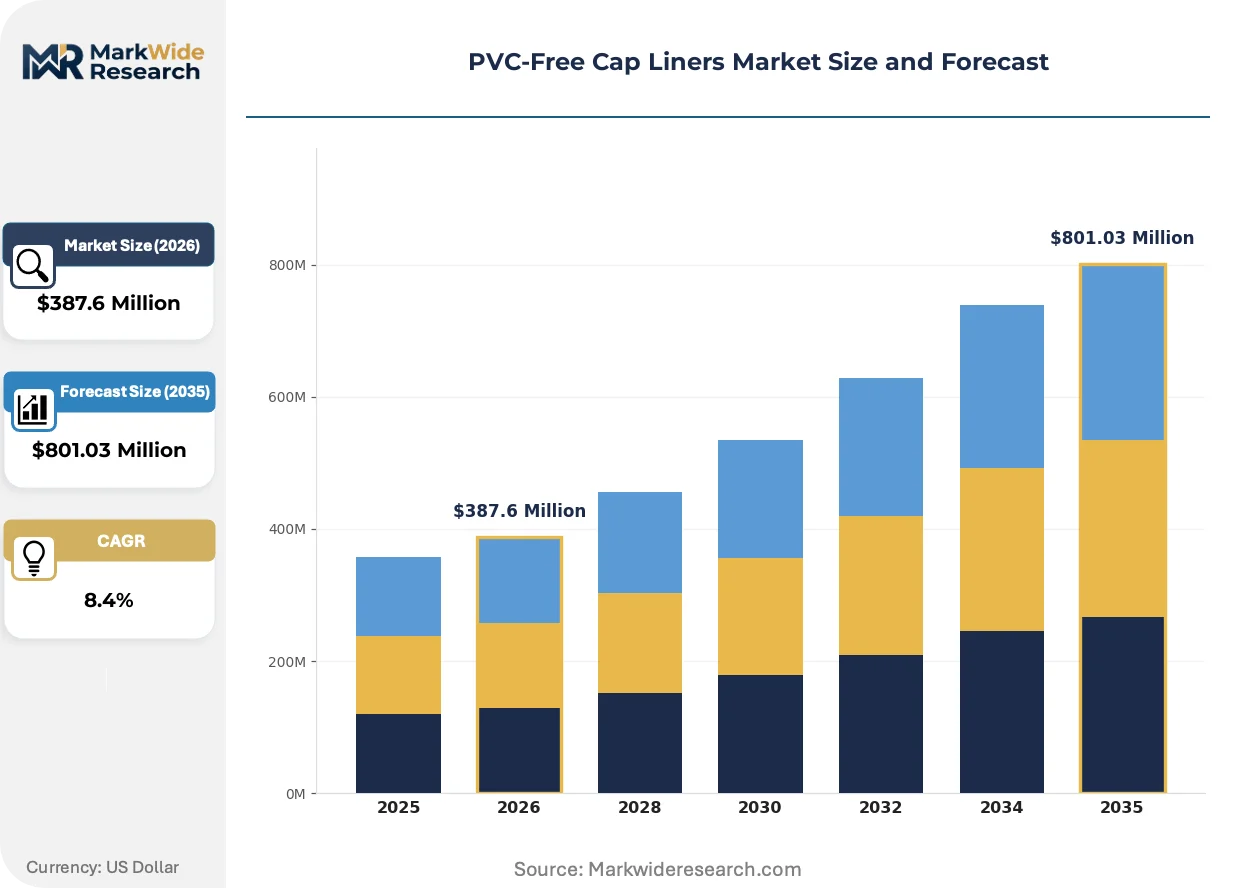
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $801.03 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Foam Liners, Adhesive Liners, Heat Seal Liners, Induction Liners End User: Pharmaceuticals, Cosmetics, Food & Beverage, Household Products Material: Polyethylene, Polypropylene, Non-Woven Fabrics, Paperboard Application: Sealing, Protection, Preservation, Containment |
| Companies Covered | The Cary Company, Meyer Seals GmbH, Selig Group, Berry Global, Inc., Bluemay Weston Limited, Tri-Sure Group B.V., Pres-On Corporation, Silgan Holdings Inc., Tekni-Plex, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVC-Free Cap Liners Market Evolving Landscape
Material science advances and regulatory stringency are compressing product development cycles while fragmenting the qualified supplier base into certification-tiered segments.
Polypropylene-based heat seal liners are fragmenting competitive positioning across the pharmaceutical packaging tier. These liners achieve lower seal-initiation temperatures than polyethylene alternatives while delivering broader chemical resistance against aggressive drug formulations. Generic drug manufacturers in Eastern Europe and contract packaging organizations in India are adopting them fastest, compressing demand for conventional foam-backed induction seals.
REACH Annex XVII restrictions on phthalate plasticizers are redirecting formulation investments throughout the European cosmetics and personal care sector. The regulation's concentration limits force brand owners to requalify entire packaging assemblies rather than substitute individual components. Color cosmetics and skin care segments with complex fragrance matrices are most affected, with German and French formulators accelerating liner replacement programs ahead of enforcement deadlines.
Specification consolidation among multinational pharmaceutical buyers is concentrating procurement authority at headquarters level. Regional manufacturing sites lose autonomy to qualify alternative liner suppliers, extending incumbent relationships and raising barriers for new entrants. This pattern is most visible in North American and Western European operations of top-20 drug makers, where global packaging engineering teams now mandate approved supplier lists across all continents.
PVC-Free Cap Liners Market Segmentation
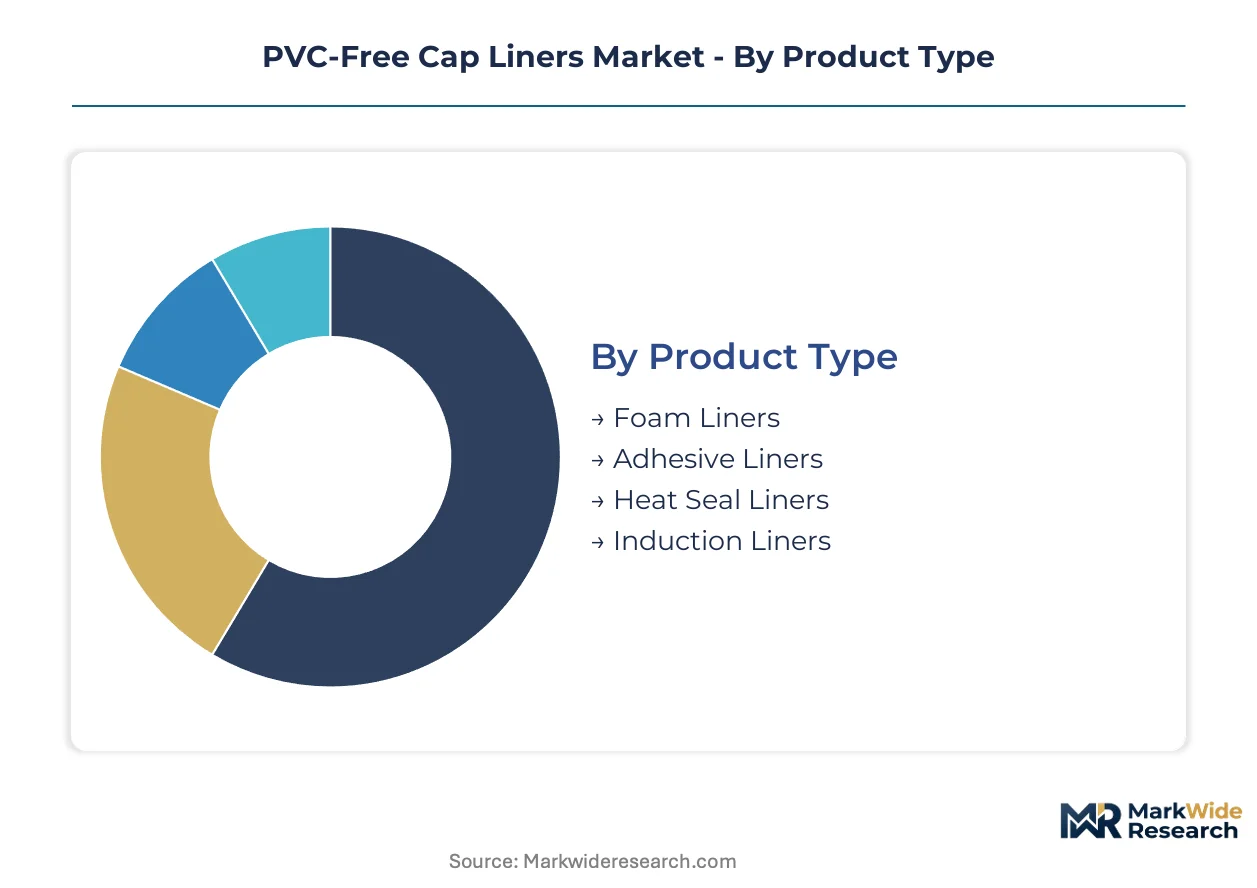
Segmentation in the PVC-Free Cap Liners Market reveals divergent substitution pressures across material-format pairings. Pharmaceutical buyers prioritize extractables-leachables compliance over unit economics, while cosmetics and household segments trade barrier performance for cost efficiency.
Product Type:
Foam liners face the most acute substitution threat as induction sealing technology penetrates parenteral packaging and tamper-evident applications.
- Foam Liners:Compressible polyethylene or polypropylene foam bonded to pressure-sensitive adhesive layers. Cosmetics and household product manufacturers in Germany and France drive volume where cost sensitivity outweighs hermetic seal requirements.
- Induction Liners:Multilayer aluminum-polypropylene composites activated by electromagnetic field sealing. Pharmaceutical packaging engineers in the United States and Switzerland specify these for oral solid dose and liquid formulations demanding zero headspace exchange.
- Heat Seal Liners:Polypropylene-based single-ply or coextruded films requiring thermal activation for bond formation.
- Adhesive Liners:Pressure-sensitive constructions relying on tackified elastomer coatings for room-temperature adhesion.
Foam liners anchor the volume base while induction liners gain share at the steepest rate.
End User:
Cost tier stratification separates certification-intensive pharmaceutical procurement from price-elastic household goods sourcing.
- Pharmaceuticals:Container closure systems for generic and branded drug products governed by FDA extractables-leachables protocols and EMA stability testing guidelines. CDSCO-aligned Indian exporters now specify REACH-compliant liners for European-bound formulations.
- Cosmetics:Skin care and color cosmetic packaging subject to REACH Annex XVII phthalate restrictions. German and French formulators accelerate requalification programs ahead of enforcement deadlines.
- Food & Beverage:Acidic and high-fat content applications requiring olefin-based barrier layers without plasticizer migration risks.
- Household Products:Cleaning and chemical formulations where cost-per-unit dominates specification decisions.
Pharmaceuticals command the premium tier while household products compress margins across all material formats.
Material:
Supply concentration among polyolefin resin producers shapes converter sourcing strategies and contract pricing structures.
- Polypropylene:Semi-crystalline thermoplastic delivering broader chemical resistance and lower seal-initiation temperatures than polyethylene alternatives. Generic drug manufacturers in Eastern Europe and Indian contract packaging organizations adopt this fastest for aggressive drug formulations.
- Polyethylene:Lower-density olefin preferred for foam extrusion and cost-sensitive applications. Cosmetics converters near Hamburg and Frankfurt maintain dedicated extrusion lines for LDPE foam sheet.
- Non-Woven Fabrics:Synthetic fiber matrices providing compressibility and liquid absorption in specialized containment roles.
- Paperboard:Cellulose-based substrates with polymer coatings for sustainability-positioned personal care brands.
Polyethylene anchors the volume base while polypropylene climbs the fastest on pharmaceutical qualification cycles.
Application:
Performance requirements fragment by containment criticality, from hermetic pharmaceutical seals to cosmetic freshness preservation.
- Sealing:Primary closure function creating mechanical barrier against external contamination. Induction and heat seal technologies dominate where hermetic integrity is non-negotiable.
- Protection:Cushioning and impact absorption for glass container shipments. Foam liners serve this function across cosmetics and fragrance distribution networks.
- Preservation:Headspace atmosphere maintenance preventing oxidation and moisture ingress. Oxygen-sensitive biologics favor polypropylene heat seal constructions.
- Containment:Leak prevention for aggressive or volatile contents including solvents and essential oil formulations.
Sealing applications anchor the volume base while preservation functions expand most quickly on biologic drug containment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European liner distribution, handling polyolefin resin imports and finished liner exports for pharmaceutical and cosmetics converters across northern Germany and into Central Europe.
United States
FDA extractables-leachables protocols drive specification rigor among generic and branded drug manufacturers. The agency's container closure system guidance forces requalification cycles that favor established liner suppliers with documented compliance histories. New Jersey and Pennsylvania host contract packaging clusters where induction sealing equipment retrofits accelerate PVC-free adoption.
Germany
REACH Annex XVII phthalate restrictions trigger packaging assembly requalification across cosmetics and personal care formulators. ECHA enforcement timelines concentrate replacement investment ahead of deadline clustering. Frankfurt and Hamburg converter zones maintain ISO 15378-certified lamination capacity that qualified pharmaceutical buyers preferentially source.
India
CDSCO alignment with ICH stability guidelines creates export compliance demand for REACH-certified liner systems. The regulator's pharmaceutical packaging standards redirect formulation investments toward barrier solutions acceptable in European destination markets. Maharashtra and Gujarat contract packaging organizations adopt polypropylene heat seal constructions fastest for aggressive generic drug formulations.
Switzerland
Swissmedic pharmaceutical packaging requirements reinforce zero-headspace seal specifications for parenteral and oral solid dose products. The regulator's stability testing protocols explicitly screen for plasticizer migration, compressing replacement timelines. Basel and Zurich pharmaceutical manufacturing clusters specify induction liners with hermetic reliability and tamper-evident properties.
China
NMPA pharmaceutical packaging standards and dual carbon policy frameworks redirect domestic converter investment toward polyolefin-based barrier systems. The regulator's extractables testing requirements for imported drug formulations align with FDA and EMA precedents. Yangtze River Delta chemical and packaging clusters expand heat seal liner capacity for export-oriented pharmaceutical customers.
PVC-Free Cap Liners Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage dimensions. The vendor base stratifies between multinational packaging conglomerates with integrated polymer sourcing and regional laminators with dedicated pharmaceutical-grade capacity. Three archetypes dominate: scale-driven resin-to-liner integrators, ISO 15378-certified European specialists, and Asia-Pacific contract converters serving export pharmaceutical demand. Competitive moves concentrate on backward integration into adhesive formulation and strategic partnerships to secure qualified raw material allocation.
Within the certification-intensive tier, Meyer Seals GmbH and Selig Group exemplify European pharmaceutical-grade positioning, while Tekni-Plex, Inc. anchors North American supply relationships through controlled polymer sourcing capabilities.
| Leading Market Players |
|---|
| The Cary Company |
| Meyer Seals GmbH |
| Selig Group |
| Berry Global, Inc. |
| Bluemay Weston Limited |
| Tri-Sure Group B.V. |
| Pres-On Corporation |
| Silgan Holdings Inc. |
| Tekni-Plex, Inc. |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts with polyolefin resin producers lock in both raw material allocation and price visibility for European pharmaceutical-grade liner converters serving REACH-regulated markets. These arrangements insulate certified suppliers from ethylene and propylene feedstock volatility while freezing specification relationships with drug packaging buyers through multi-year offtake agreements.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, industrial-certified, and general-purpose levels separates ISO 15378-compliant induction liners from foam-backed cosmetics alternatives. Certification grade and volume scale drive price differentiation, with pharmaceutical buyers accepting premium positioning for documented extractables-leachables compliance. Cost compression in cosmetics foam liners is intensifying as German and French converters compete for household product contracts. Household product manufacturers exhibit the highest price sensitivity, while biologic drug containment applications show the least.
Supply Chain Analysis
Adhesive formulation capability concentrates among three European chemical specialists near Frankfurt and Hamburg, creating single-source vulnerability for heat-activated and pressure-sensitive coatings meeting pharmaceutical thresholds. Raw material sourcing draws from Saudi ethylene crackers, Belgian polypropylene polymerization, and specialized German laminators. Distribution runs through converter-direct relationships that bypass traditional packaging distributors as brand owners secure dedicated lamination capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification fragmentation across pharmaceutical, cosmetics, and household segments creates multiple entry niches as regulatory deadlines force material requalification cycles. The divergence between certification-intensive drug packaging and price-elastic consumer goods opens distinct competitive arenas for differentiated positioning.
For Market Incumbents: Secure backward integration into adhesive formulation to eliminate dependence on the three European chemical specialists controlling qualified coating supply. Add dedicated polypropylene heat seal capacity in Hamburg and Frankfurt converter zones to capture biologic drug containment demand before mid-tier generics manufacturers complete induction sealing equipment retrofits.
For New Entrants and Emerging Players: Lead with CDSCO-aligned Indian contract packaging organizations as the most penetrable entry point, where REACH-compliant liner demand outpaces qualified local supply. Target polypropylene heat seal constructions for aggressive generic drug formulations as the fastest-adopting material-format pairing in Maharashtra and Gujarat clusters.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ISO 15378-certified European specialists with multi-year pharmaceutical supply agreements. Long-term viability rests on adhesive formulation capabilities and certification maintenance infrastructure. The inflection signal to monitor is EMA enforcement timing for updated stability testing protocols screening plasticizer migration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Formulation | Eliminates single-source dependency on three European chemical specialists serving REACH-regulated markets. |
| ISO 15378 Certification Investment | Unlocks multi-year supply relationships with top-20 drug makers consolidating procurement authority at headquarters level. |
| Polypropylene Heat Seal Capacity Expansion | Captures biologic drug containment demand requiring ultra-low extractable profiles and lower seal-initiation temperatures. |
| Direct Converter Relationship Development | Bypasses distributors to secure dedicated lamination capacity and custom barrier specifications for brand owners. |
| Indian Contract Packaging Partnership | Positions for CDSCO-aligned export demand as Indian pharmaceutical packaging standards converge with ICH guidelines. |
Research Methodology
The analysis maps foam liner, induction liner, heat seal liner, and adhesive liner sub-sectors, each validated through converter operations managers, pharmaceutical packaging engineers, cosmetics formulators, and raw material procurement leads. Primary interviews with German and Indian laminators, European chemical specialists, and drug packaging buyers combined with secondary validation against EMA guideline documents, FDA container closure system guidance, REACH Annex XVII restriction texts, and customs trade data for polyolefin resin flows. Bottom-up capacity modeling and top-down demand estimation triangulated volume outputs.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, end user industry, material substrate, and application function, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from fitted growth curves incorporating pharmaceutical qualification cycle timing, cosmetics requalification program acceleration, and household product cost sensitivity parameters.
Forecasts assume regulatory continuity in REACH enforcement timelines, FDA extractables-leachables protocols, and CDSCO alignment with ICH stability guidelines; material policy shifts would require re-modeling. Specific risk factors include polyolefin resin price volatility, ISO 15378 audit timeline delays, and state-level extended producer responsibility framework adoption. Practitioners should keep alternative scenarios live as EMA pharmaceutical packaging guideline revisions and Indian export compliance demand patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Caps and Closures
Aerosol Caps Market
Caps and Closures
Metal Closures Market
Caps and Closures
Twist Caps Market
Caps and Closures
Humidity Indicator Plugs Market
Caps and Closures
Cover Caps Market
Caps and Closures
IV Infusion Bottle Seals and Caps Market
Caps and Closures
Brazil Plastic Caps and Closures Market
Caps and Closures
Low Profile Compact System Closures Market
Caps and Closures
North America Plastic Caps and Closures Market
Caps and Closures
Sleeve Rubber Stoppers Market
Caps and Closures
Push Pull Closure Market
Caps and Closures
Screw Closure Market
Caps and Closures
Nigeria Plastic Caps and Closures Market
Caps and Closures
Side Pour Caps Market
Caps and Closures
Twist-Off Metal Caps Market
Caps and Closures
Clic Loc Closure Market