
 Inspection and Inventory Labels Market | 2026-2036
Inspection and Inventory Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Inspection and Inventory Labels Market Foresight
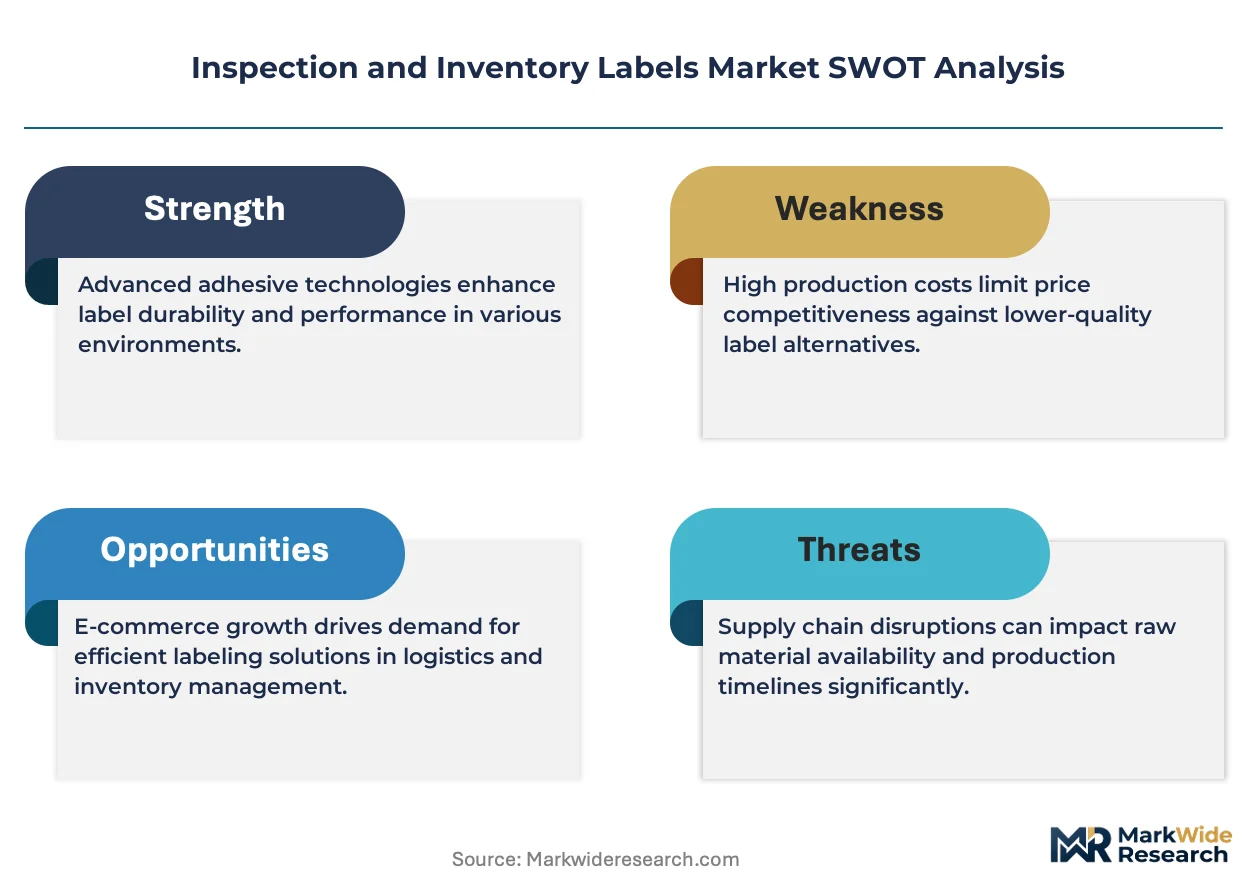
Polyester is pivoting toward vinyl in harsh-environment inventory applications where chemical resistance and outdoor durability outweigh cost considerations. Avery Dennison leverages its adhesive science portfolio to sustain premium positioning in pressure-sensitive formulations. Brady Corporation anchors its competitive stance through specialized safety and identification products for industrial end-users. Zebra Technologies dominates enterprise-grade RFID label systems, competing directly with Sato Holdings in automated warehouse deployments.
Inspection and inventory labels are adhesive-backed substrates engineered with specified tear strength, chemical resistance, and print receptivity to encode tracking data, withstand environmental exposure, and enable machine-readable identification throughout supply chains. Manufacturing processes encompass direct thermal coating, thermal transfer receptor layers, and inlay embedding for RFID functionality, with substrates selected against ISO 15415 print quality grades and ASTM D1000 adhesion standards for industrial durability. Pressure-sensitive labels occupy the largest volume share across logistics and retail verticals, while RFID labels represent the fastest-expanding segment as warehouse automation mandates real-time location tracking. Thermal transfer labels sustain margin concentration in healthcare and aerospace compliance applications where archival legibility spans decades.
The FDA enforces Unique Device Identification labeling for medical devices, compelling healthcare supply chains to upgrade from paper to synthetic substrates with verified scan persistence. REACH and RoHS frameworks in Europe restrict hazardous substances in adhesives and substrates, reshaping material sourcing for exporters serving EU manufacturing and retail channels. OSHA hazard communication standards in the United States mandate specific label durability and legibility for chemical containers, sustaining demand for self-laminating and vinyl constructions in industrial settings. Stakeholders must weigh synthetic material cost trajectories against regulatory compliance horizons when configuring regional product portfolios.
Market Dynamics
RFID inlay embedding is compressing inventory cycle times across pharmaceutical and automotive supply chains, forcing substrate suppliers to reconfigure coating lines for dual thermal-RFID compatibility.
Growth Catalysts
- FDA UDI Mandate:Medical device manufacturers must deploy synthetic labels with verified scan persistence, compelling healthcare supply chains to abandon paper substrates entirely.
- Cold-Chain Tracking:Pharmaceutical manufacturers in the United States are expanding label adoption for temperature-sensitive biologics distribution.
- Automated Warehouse Deployment:Real-time location tracking mandates from third-party logistics providers are accelerating RFID label integration in Midwest distribution hubs.
Market Restraints
- Petrochemical Feedstock Volatility:Polyester and vinyl substrate costs fluctuate with crude oil derivatives, squeezing converter margins on long-term supply contracts.
- Adhesive Supply Concentration:Pressure-sensitive adhesive production clusters in Germany and the United States, creating geographic vulnerability for Asian label converters.
- REACH Compliance Friction:European chemical restrictions on adhesive formulations force reformulation cycles that delay product launches by 12-18 months.
Strategic Opportunities
- India Pharmaceutical Export Channel:CDSCO labeling requirements for exported generics create demand for ISO 15415-compliant thermal transfer labels with decades-long archival legibility.
- EU Green Deal Incentives:Bio-based substrate development receives preferential treatment under circular economy procurement rules for public sector healthcare.
- RFID-NFC Convergence:Smartphone-readable inventory tags enable last-mile tracking without dedicated scanner infrastructure, opening small-fleet logistics adoption.
Industry Challenges
- ISO 15415 Certification Bottleneck:Third-party print quality verification labs face 6-month backlogs, delaying new product introductions for healthcare and aerospace suppliers.
- Legacy Warehouse Management Integration:ERP systems in established automotive supply chains require custom middleware development to ingest RFID data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inspection and Inventory Labels Market |
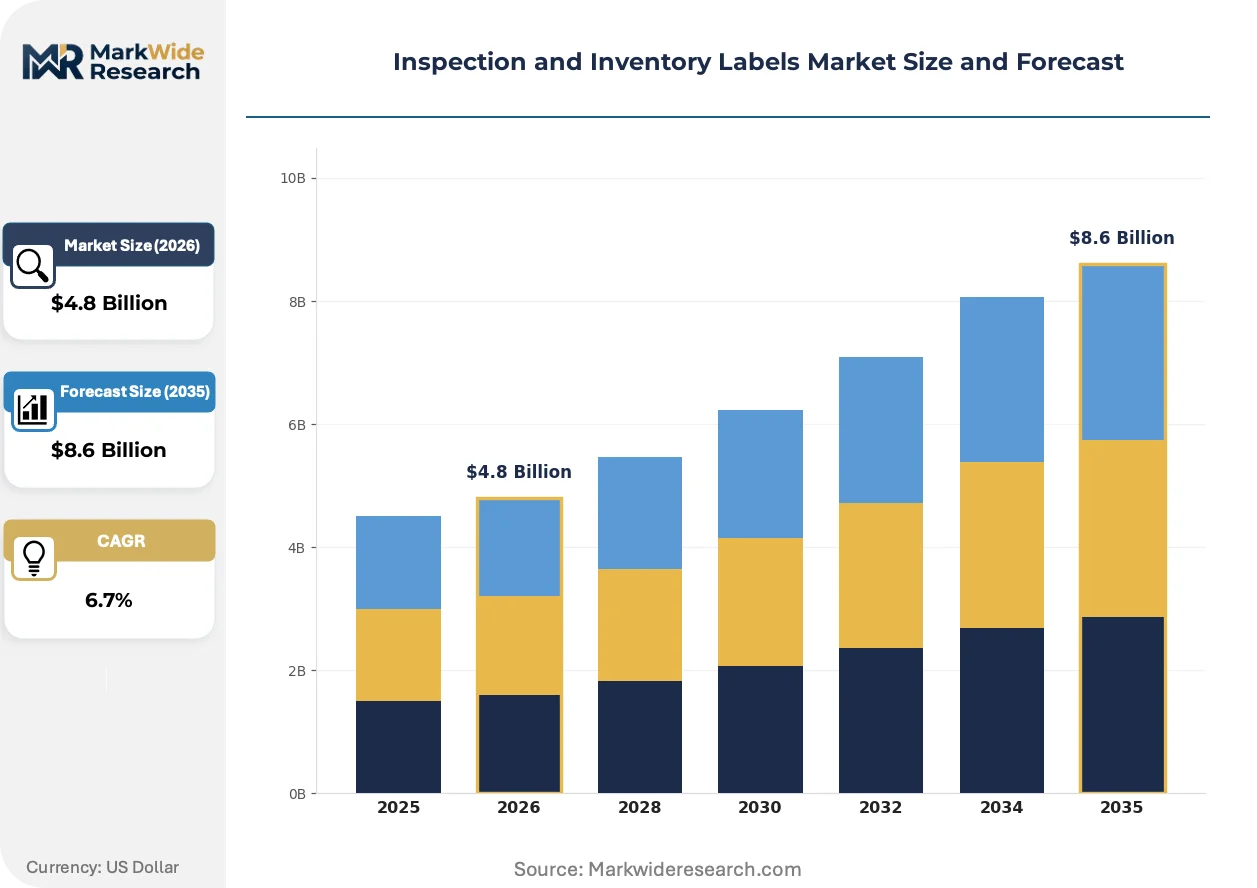
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure-Sensitive Labels, Self-Laminating Labels, RFID Labels, Thermal Transfer Labels Material: Vinyl, Polypropylene, Paper, Polyester Industry Vertical: Manufacturing, Retail, Healthcare, Logistics Application: Inventory Management, Quality Control, Asset Tracking, Compliance |
| Companies Covered | Brady Corporation, Honeywell International, Avery Dennison, Brother Industries, TSC Auto ID, Zebra Technologies, Sato Holdings, Seiko Epson, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inspection and Inventory Labels Market Shifts & Advancements
Active antenna design and sustainable substrate chemistry are compressing the technical and environmental performance gap between premium RFID systems and conventional barcode labels.
Dual-frequency RFID inlays combining UHF for warehouse range and NFC for consumer interaction are electrifying pharmaceutical authentication applications. European vaccine distributors are piloting these hybrid tags at scale. The convergence is compressing the addressable market for single-frequency legacy inlays.
REACH authorization requirements for certain adhesive plasticizers are forcing reformulation investments across European label converters. Manufacturers serving medical device exporters must now document full substance compliance across supply tiers. Healthcare label specifications in Germany and France are tightening faster than in North American markets.
Consolidated procurement by pharmaceutical third-party logistics providers is displacing fragmented buyer decision-making. Large distributors now mandate unified label specifications across multiple supplier tiers, eroding converter flexibility. This concentration is most visible in United States cold-chain networks serving regional hospital systems.
Inspection and Inventory Labels Market Segmentation
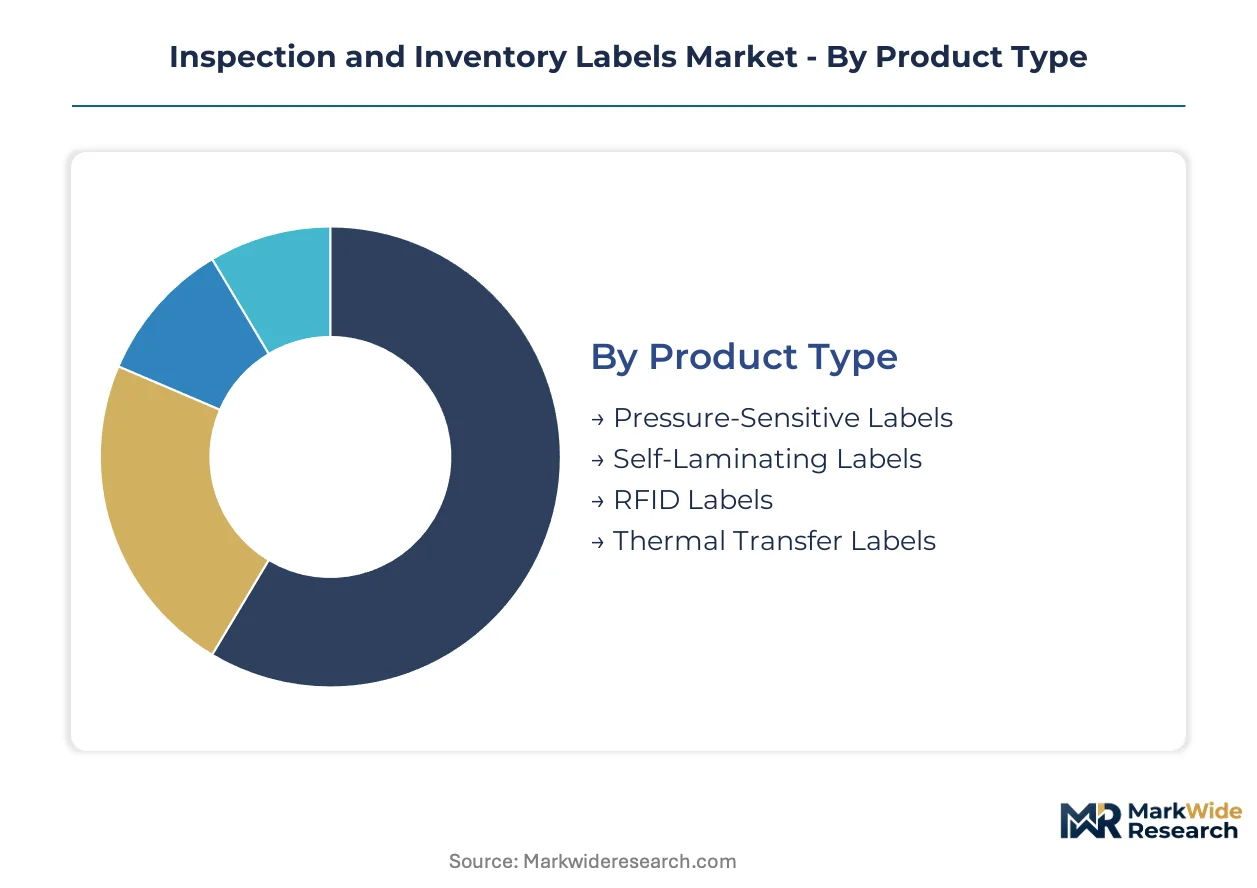
Label performance requirements diverge sharply across use cases. Substrate selection, adhesive chemistry, and encoding technology must align with environmental exposure, scan distance, and regulatory durability mandates.
Product Type:
Standalone barcode labels dominate legacy installations. Embedded RFID systems are displacing conventional formats in automated warehouse deployments.
- Pressure-Sensitive Labels:Acrylic or rubber-based adhesives bond to corrugated, metal, and plastic surfaces without heat activation. Logistics operators in the United States Midwest specify these for high-speed carton labeling where equipment retrofit costs prohibit RFID migration.
- RFID Labels:UHF inlays embedded between facestock and liner enable bulk scanning at 10-meter ranges. Pharmaceutical cold-chain distributors are mandating these for real-time location tracking of temperature-sensitive biologics.
- Thermal Transfer Labels:Wax-resin receptor coatings deliver archival legibility exceeding 20 years. Aerospace and healthcare compliance applications specify these for ISO 15415-grade print permanence.
- Self-Laminating Labels:Clear overlaminate film protects handwritten or printed data from chemical exposure and abrasion. OSHA hazard communication standards require these for chemical container identification in industrial settings.
Pressure-sensitive labels lead volumes today; RFID labels are gaining share fastest.
Material:
Cost tiers separate commodity paper from engineered synthetics. Performance specifications dictate substrate selection more than unit economics in regulated verticals.
- Polyester:High tensile strength and dimensional stability under thermal cycling. Medical device manufacturers specify PET for FDA UDI compliance where scan persistence must survive sterilization autoclaves.
- Vinyl:Flexible facestock conforms to curved surfaces and withstands outdoor UV exposure. Automotive parts suppliers specify vinyl for under-hood component tracking.
- Polypropylene:Cost-effective synthetic with moderate chemical resistance. Retail apparel tagging favors BOPP for its balance of print quality and yield efficiency.
- Paper:Uncoated and coated stocks serve short-lifecycle applications. E-commerce carton labeling consumes the largest paper volumes despite synthetic substitution pressure.
Paper leads volumes today; polyester is climbing the fastest.
Industry Vertical:
Customer procurement maturity varies. Healthcare mandates drive specification rigor; retail prioritizes unit cost minimization.
- Healthcare:FDA UDI and EMA MDR regulations mandate synthetic labels with verified scan persistence. Hospital systems now require RFID-enabled inventory for implantable device traceability.
- Logistics:Third-party distribution providers are consolidating label specifications across supplier tiers. Midwest United States hubs specify unified formats for automotive and pharmaceutical co-loading.
- Manufacturing:Work-in-process tracking and finished goods serialization consume pressure-sensitive and thermal transfer formats. Automotive OEMs specify chemical-resistant synthetics for component lineage documentation.
- Retail:High-volume carton and shelf-edge labeling dominates material consumption. Apparel RFID adoption is accelerating for omnichannel inventory accuracy.
Logistics leads volumes today; healthcare is expanding most quickly.
Application:
Functional requirements determine technology embedding depth. Compliance applications demand archival durability; inventory management prioritizes scan speed.
- Inventory Management:Cycle counting, receiving, and put-away operations specify barcode or RFID formats based on warehouse automation maturity. Real-time location systems are mandating UHF RFID in new greenfield builds.
- Compliance:Regulatory labeling for medical devices, chemicals, and food contact materials requires substrate-adhesive combinations with documented test data. FDA, OSHA, and REACH frameworks each specify distinct durability thresholds.
- Asset Tracking:Capital equipment and reusable container tagging favor ruggedized synthetics with permanent adhesives. Returnable packaging programs in automotive supply chains specify vinyl or polyester for multi-year lifecycle performance.
- Quality Control:Inspection status indicators and non-conformance tags require color-coded facestocks with immediate visual recognition. Manufacturing floor environments specify smudge-resistant thermal transfer or laser-printable synthetics.
Inventory management leads volumes today; compliance is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest distribution hubs in the United States anchor demand concentration for inspection and inventory labels, driven by automotive and pharmaceutical supply chain density. Regulatory mandates across multiple geographies are accelerating substrate upgrades from paper to synthetic materials. Industrial clusters in Germany, Japan, and India are emerging as secondary growth poles with distinct compliance requirements.
United States
FDA UDI enforcement and cold-chain pharmaceutical distribution drive synthetic label demand. OSHA hazard communication standards mandate durable vinyl constructions for chemical container tracking. Midwest distribution hubs serving automotive OEMs specify unified label formats across supplier tiers.
Germany
REACH authorization requirements for adhesive plasticizers force reformulation investments across converter networks. EMA MDR regulations tighten healthcare label specifications faster than North American markets. Industrial clusters in Baden-Württemberg and Bavaria concentrate automotive parts labeling demand.
China
NMPA medical device traceability rules and export compliance to EU REACH standards expand synthetic substrate adoption. Domestic e-commerce logistics consumes massive paper label volumes despite substitution pressure. Yangtze River Delta manufacturing hubs specify RFID-enabled inventory systems for automotive export supply chains.
Japan
METI industrial standards and PMDA pharmaceutical serialization mandates sustain thermal transfer label demand for archival compliance. Automotive OEMs in Aichi Prefecture specify chemical-resistant synthetics for component lineage documentation. Precision manufacturing clusters in Osaka-Kobe favor ISO 15415-grade print permanence specifications.
India
CDSCO labeling requirements for exported generics create demand for decades-long archival legibility. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat upgrade from paper to polyester substrates for cold-chain exports. DGFT trade documentation rules accelerate barcode standardization across export-oriented units.
Inspection and Inventory Labels Market Competitive Landscape
Global majors compete with regional champions across adhesive science portfolios and RFID system integration. The market structure shows tiered consolidation with premium specialists holding position in regulated healthcare verticals while volume players compete on logistics efficiency. Three archetypes dominate: adhesive science specialists, enterprise automation integrators, and diversified industrial conglomerates. M&A activity targets RFID inlay capabilities while capacity expansion concentrates in Asia-Pacific to serve pharmaceutical export channels.
Among diversified industrial conglomerates, 3M and Honeywell International exemplify scale-driven positioning across multiple substrate technologies. Avery Dennison occupies a position within the adhesive science specialist archetype, anchoring premium pressure-sensitive formulations. Zebra Technologies and Sato Holdings sit within the enterprise automation integrator tier, representing competitive positioning in RFID-enabled warehouse systems.
| Leading Market Players |
|---|
| Brady Corporation |
| Honeywell International |
| Avery Dennison |
| Brother Industries |
| TSC Auto ID |
| Zebra Technologies |
| Sato Holdings |
| Seiko Epson |
| 3M |
| Others |
Supply & Pricing Matrix
Crude oil derivative indices governing polyester and vinyl resin costs cascade through converter pricing tiers, compressing margins on long-term supply contracts while forcing rapid pass-through adjustments for spot buyers in automotive and pharmaceutical channels.
Pricing Analysis
Input-cost pass-through dominates label converter pricing, with petrochemical feedstock volatility transmitted directly to buyer invoices through quarterly adjustment clauses. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated thermal transfer substrates from commodity pressure-sensitive paper labels, with ISO 15415 certification commanding measurable premiums. Pricing pressure stems from consolidated procurement by third-party pharmaceutical logistics providers, who now mandate unified specifications across supplier tiers. Retail carton labeling exhibits highest price sensitivity, while healthcare compliance applications show inelastic demand due to regulatory substitution barriers.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs and pharmaceutical distributors mandate multi-supplier qualification for pressure-sensitive adhesives, compelling converters to maintain parallel relationships with German and US adhesive producers despite geographic concentration. Substrate supply concentrates in China, Germany, and the United States, with inlay embedding capacity clustering in Malaysia and Mexico for tariff-advantaged access to North American automotive channels. Raw material dependencies span petroleum-derived polyester resins, acrylic adhesive monomers, and copper-etched RFID antenna substrates. Single-source vulnerability persists in specialty thermal transfer receptor coatings, where qualified suppliers number fewer than five globally. Distribution runs through converter networks serving regional distribution hubs, with direct OEM relationships capturing premium healthcare and aerospace volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on substrate substitution economics favoring synthetics over paper, coupled with RFID integration premiums that outpace commodity label commoditization.
For Market Incumbents: Deploy adhesive science portfolio extensions to capture reformulation cycles triggered by REACH plasticizer restrictions. Brady Corporation and Avery Dennison should accelerate bio-based substrate development to preempt EU Green Deal procurement preferences. Capacity addition in India serves CDSCO-compliant export demand from Maharashtra and Gujarat pharmaceutical clusters. RFID inlay backward integration protects margin concentration as warehouse automation mandates proliferate. For New Entrants and Emerging Players: Third-party logistics providers represent the most penetrable channel partner type for RFID-native label specialists lacking legacy converter infrastructure. White-space targets include smartphone-readable NFC inventory tags for small-fleet logistics operators and bio-based polyester alternatives for European public healthcare procurement. Geographic entry should prioritize India pharmaceutical export corridors over saturated US Midwest distribution hubs. Go-to-market positioning centers on decades-long archival legibility guarantees for CDSCO and FDA UDI compliance applications. For Investors and Strategic Acquirers: Asymmetric upside sits with RFID inlay specialists possessing dual-frequency UHF-NFC capabilities and established pharmaceutical cold-chain validation. Long-term viability favors converters with demonstrated REACH documentation systems and multi-tier supplier audit capabilities. Acquisition target archetype: mid-cap specialists with ISO 15415 certification backlog clearance and embedded automotive OEM relationships. Signal to watch: FDA enforcement discretion tightening on Unique Device Identification scan persistence failures, which would accelerate synthetic substrate substitution.| Strategic Initiative | Industry Significance |
|---|---|
| RFID Inlay Backward Integration | Captures margin compression from third-party inlay suppliers serving pharmaceutical cold-chain mandates. |
| Bio-Based Substrate Development | Aligns product portfolios with EU Green Deal circular economy procurement rules for healthcare. |
| India Pharmaceutical Export Channel Expansion | Positions converters to serve CDSCO-compliant thermal transfer demand from Maharashtra and Gujarat clusters. |
| Dual-Frequency RFID-NFC Convergence | Enables smartphone-readable inventory tracking without dedicated scanner infrastructure for small-fleet adoption. |
| REACH Documentation System Investment | Accelerates product launch timelines by preempting 12-18 month reformulation delays from adhesive plasticizer restrictions. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with adhesive formulation scientists, pharmaceutical supply chain directors, automotive Tier 1 procurement managers, and RFID systems integration specialists with secondary validation. Primary inputs drew from FDA UDI guidance documents, ECHA REACH authorization lists, CDSCO labeling circulars, and ISO 15415 print quality standards. Secondary sources encompassed customs trade data for substrate resin flows, SEC filings from listed converters, and hospital GPO contract databases. Bottom-up volume builds across product types, materials, and industry verticals were triangulated against top-down macroeconomic drivers.
Segment-weighting approaches distributed value and volume across pressure-sensitive, RFID, thermal transfer, and self-laminating product categories, with further stratification by polyester, vinyl, polypropylene, and paper substrates. Industry-specific dimensions modeled included regulatory compliance tier, cold-chain exposure requirement, and warehouse automation maturity. CAGRs were derived from regression analysis against pharmaceutical distribution growth, automotive production forecasts, and RFID infrastructure deployment rates. Forecast inputs incorporated FDA enforcement trajectory, REACH reformulation cycle timing, and petrochemical feedstock price elasticity assumptions.
Revisions become necessary when regulatory enforcement timelines accelerate, adhesive raw material supply disruptions materialize, or warehouse automation adoption curves steepen beyond baseline assumptions. Deviation in FDA UDI audit intensity or ECHA plasticizer authorization withdrawals would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
United States Print Label Market
Labels
Variable Data Printing Labels Market
Labels
GHS Labels Market
Labels
Shipping Label Market
Labels
Non-Adhesive Tags Market
Labels
Syringe Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Global Pressure Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Industrial Label Printers Market
Labels
Global Automotive Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
Time Temperature Indicator Labels Market
Labels
Die Cut Labels Market
Labels
Hang Tags Market
Labels
BOPP Labels Market