
 Pre-Printed Liners Market | 2026-2036
Pre-Printed Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Printed Liners Market Outlook
Quick-service restaurants and meal-kit distributors are bifurcating demand away from traditional industrial packers. Mondi Group leverages integrated pulp-to-liner operations across Central European mills to secure substrate consistency for high-volume food contracts. DS Smith Plc anchors its position through circular-design R&D hubs in the UK and Benelux, converting post-consumer fiber into retail-ready pre-printed liners. Smurfit Kappa Group dominates Iberian and Latin American supply through regional corrugated-liner co-location, reducing logistics friction for export-bound food brands.
Pre-printed liners are protective or decorative substrates—typically kraft paper, coated paper, or extruded polymer films between 30–150 gsm—printed in roll or sheet form before lamination or insertion into primary packaging. They serve to carry brand graphics, moisture barriers, or abrasion resistance without requiring post-formation printing on finished containers. Paper liners lead volume in European food packaging due to fiber recyclability and composting infrastructure alignment, while vinyl and plastic variants retain share in graphic overlays and surface protection where chemical resistance and dimensional stability command margin premiums. Fabric-based liners occupy a niche in premium retail displays and event staging, where tactile quality justifies unit cost premiums over synthetic alternatives.
EMA guidelines on food-contact materials, REACH chemical restrictions on printing inks and coatings, and the EU Packaging and Packaging Waste Regulation collectively shape substrate selection and ink formulation across the value chain. BIS certification requirements in India and FDA food-contact notifications in the United States create divergent compliance portfolios for exporters serving multiple jurisdictions. Stakeholders must monitor how extended producer responsibility fee structures and emerging per-fluorinated substance bans recalibrate total cost of ownership across paper, plastic, and hybrid liner architectures.
Market Dynamics
Centralized retail consolidation across Germany and France is compressing liner procurement timelines while demanding certified fiber substrates that satisfy EU Packaging and Packaging Waste Regulation recyclability mandates. This structural pressure forces converters to pre-qualify substrates against multiple compliance frameworks before contract bidding.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets accelerate fiber-based liner substitution for plastic protective layers in food-contact applications.
- Meal-kit distributors:Branded unboxing experiences drive specification of pre-printed kraft liners with moisture barriers for chilled protein shipments.
- Centralized retail chains:Germany's discounter consolidation creates volume concentration that rewards liner suppliers with certified circular-design capabilities.
Market Restraints
- Pulp cost volatility:Kraft liner producers face margin compression from Nordic softwood pulp price swings that transfer unevenly through contract structures.
- REACH chemical restrictions:Ink formulation complexity for food-contact barriers extends R&D cycles and limits supplier pool for compliant coatings.
- Polymer film substitution:Vinyl liners retain graphic overlay share where dimensional stability and chemical resistance justify premium positioning.
Strategic Opportunities
- Extended producer responsibility fee structures:Emerging modulated fees based on recyclability performance create competitive advantage for fiber-based liner architectures.
- Quick-service restaurant chains:Drive-through packaging standardization across Iberian markets opens specification windows for pre-printed liners with integrated grease resistance.
- Post-consumer fiber conversion:Circular-design R&D hubs in Benelux demonstrate technical viability of retail-ready liners from recovered corrugated feedstock.
Industry Challenges
- Multi-jurisdiction certification timelines:Exporters serving EU, US, and Indian markets must sequence BIS, FDA, and EMA food-contact approvals with divergent testing protocols.
- Per-fluorinated substance bans:Anticipated restrictions on PFAS-based grease barriers force reformulation of existing liner specifications before performance parity is achieved.
- Legacy printing asset compatibility:Water-based ink transitions for fiber substrates require press modification investments that strain mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Printed Liners Market |
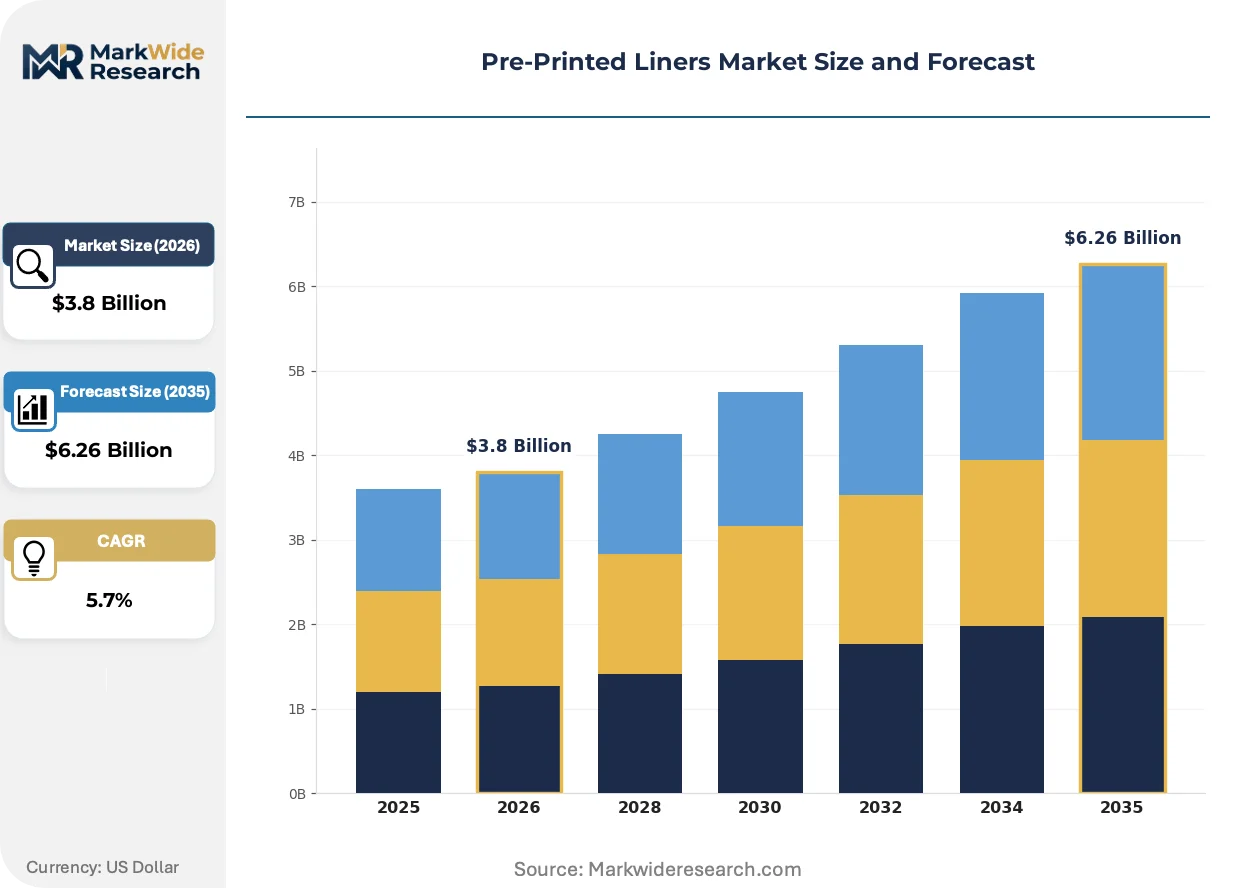
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Plastic, Vinyl, Fabric Application: Food Packaging, Retail Displays, Surface Protection, Graphic Overlays End User: Manufacturers, Retailers, Restaurants, Event Planners Distribution Channel: Online Sales, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Smurfit Kappa Group, Mondi Group, DS Smith Plc, International Paper Company, WestRock Company, Georgia-Pacific LLC, Oji Holdings Corporation, Nippon Paper Industries Co., Ltd., Stora Enso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Printed Liners Market Strategic Shifts
Pre-printed liner technology is fragmenting along substrate-performance lines as brand owners demand simultaneous shelf appeal and circularity compliance. Three developments are reshaping competitive positioning.
Water-based barrier coatings for kraft liners is bifurcating the food-contact segment. Quick-service restaurant chains in France and Germany are specifying these coatings for hot-hold packaging at accelerating pace. The technology is bifurcating procurement pools between converters with in-house formulation capability and those dependent on third-party supply.
REACH Annex XVII restrictions on specific phthalates and heavy metals in printing inks are tightening formulation standards across European converter operations. Industrial consequence includes accelerated qualification of bio-based pigment systems that maintain color fastness under migration testing. Small-format specialty food packers in Italy and Spain face disproportionate compliance burden relative to integrated multinational suppliers.
Direct mill-to-brand specification contracts are displacing traditional distributor-mediated liner procurement. German retail chains now contract liner supply eighteen months forward against fixed sustainability KPIs. This pattern concentrates most visibly in chilled ready-meal segments where shelf-ready format standardization reduces downstream packaging labor.
Pre-Printed Liners Market Segmentation
Pre-printed liner procurement splits sharply between domestic food-packaging volume and export-bound specialty formats. Substrate selection, certification requirements, and supply chain configuration vary dramatically across these divides, reshaping how converters organize production and inventory.
Product Type:
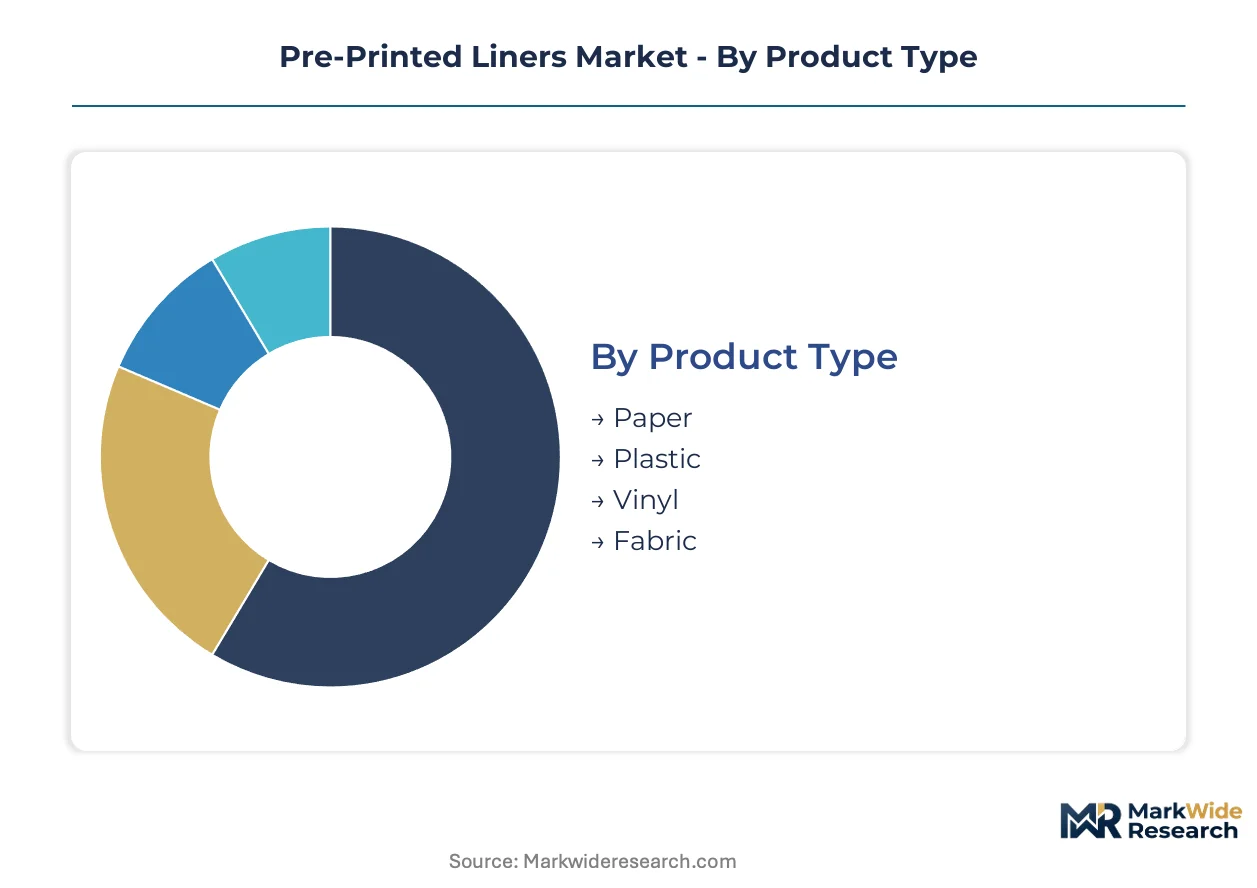
Paper liners dominate domestic European food packaging, while plastic and vinyl variants concentrate in export-led graphic overlay and protective applications. Fabric substrates serve niche premium segments with limited geographic spread.
- Paper:Kraft and coated paper substrates between 30-150 gsm carry brand graphics and moisture barriers for chilled ready-meals and quick-service packaging. German retail chains specify certified fiber grades against EU Packaging and Packaging Waste Regulation targets, compressing procurement timelines for compliant converters.
- Plastic:Extruded polymer films deliver dimensional stability and chemical resistance for industrial surface protection and graphic overlays. Demand clusters in Benelux export operations serving multi-jurisdiction clients requiring REACH-compliant barrier formulations.
- Vinyl:Rigid calendered sheets provide abrasion resistance and graphic fidelity for retail displays and event staging. Specifications concentrate in Iberian promotional markets and Latin American export channels where humidity tolerance commands premium positioning.
- Fabric:Woven and non-woven textile liners serve tactile premium retail displays and temporary event installations. Volume remains constrained to high-end French and Italian fashion packaging where unit cost premiums justify substrate selection.
Paper holds the largest share; momentum sits with plastic as export graphic overlay demand climbs.
Application:
Food packaging absorbs the majority of volume at standard margin tiers, while retail displays and graphic overlays operate at premium pricing with concentrated customer bases.
- Food Packaging:Shelf-ready formats for chilled proteins, ready-meals, and quick-service hot-hold containers. Meal-kit distributors in France and Germany specify pre-printed kraft liners with integrated grease resistance, driving water-based barrier coating adoption.
- Retail Displays:Point-of-sale liners for premium cosmetics, electronics, and fashion packaging. Italian and Spanish specialty packers face disproportionate REACH pigment compliance burdens relative to integrated multinational suppliers.
- Surface Protection:Industrial liners guarding finished goods during transit and assembly. Demand concentrates in German automotive component supply chains requiring abrasion-resistant kraft specifications.
- Graphic Overlays:Decorative printed layers laminated onto primary containers for brand differentiation. Vinyl and plastic substrates retain share here where chemical resistance and dimensional stability justify material premiums.
Food packaging commands volume concentration; retail displays are gaining share fastest among premium-positioned converters.
End User:
Manufacturers and retailers drive standardized high-volume procurement, while restaurants and event planners generate fragmented demand with customized specifications.
- Manufacturers:Industrial packers of consumer goods and food products sourcing liners at scale. Centralized retail consolidation across Germany compresses procurement timelines while mandating certified fiber substrates.
- Retailers:Supermarket chains and big-box stores specifying shelf-ready packaging formats. Direct mill-to-brand contracts now displace traditional distributor mediation, with German chains contracting eighteen months forward against fixed sustainability KPIs.
- Restaurants:Quick-service chains and meal-kit distributors requiring branded unboxing experiences. Drive-through standardization across Iberian markets opens specification windows for grease-resistant pre-printed liners.
- Event Planners:Temporary display and staging applications with short-run customization needs. Fabric-based liners occupy this niche where tactile quality overrides unit cost considerations.
Manufacturers hold the largest share; restaurants represent the steepest expansion trajectory as branded food-service packaging proliferates.
Distribution Channel:
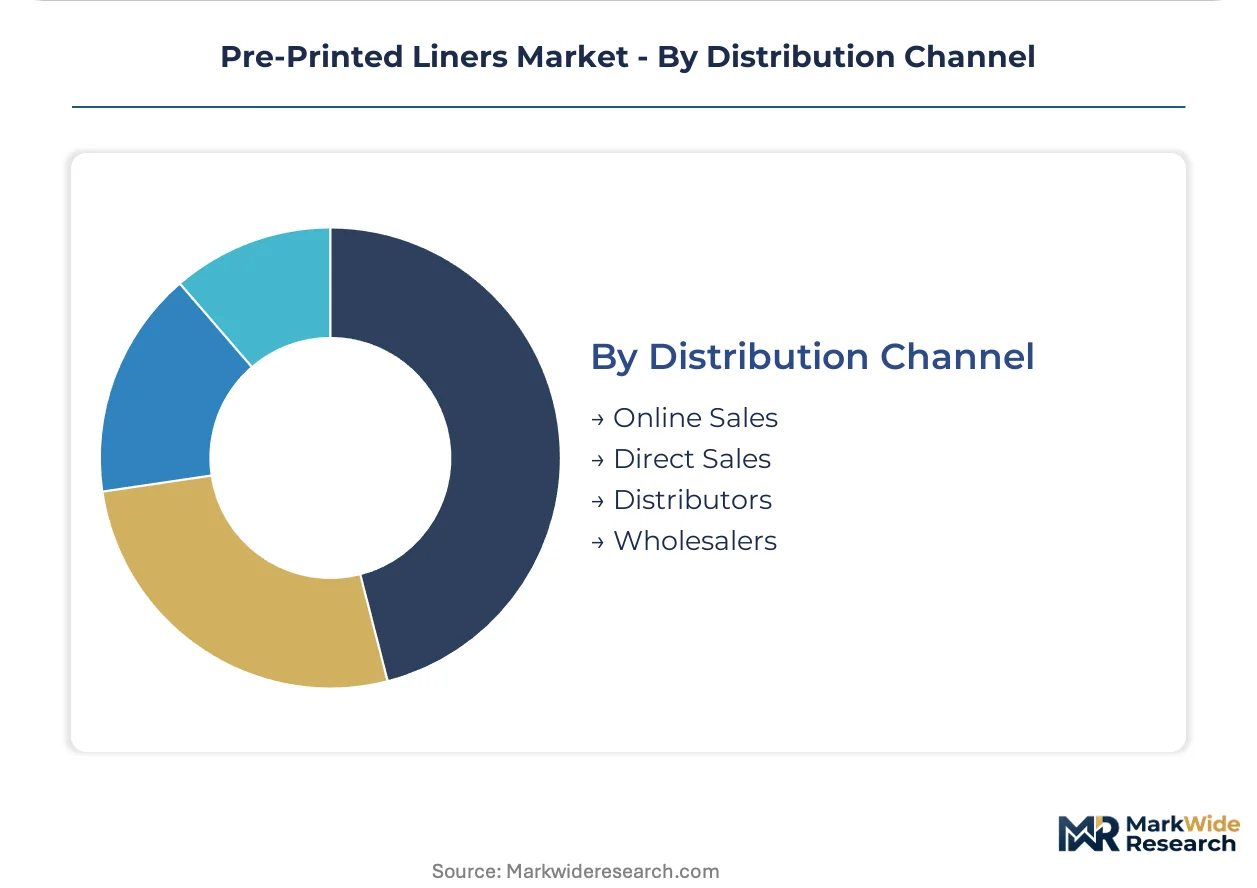
Direct sales capture standardized volume from large accounts, while distributor networks serve fragmented mid-market demand and online channels address small-batch requirements.
- Online Sales:Digital platforms enabling small-format specialty packers to source customized liner specifications. Italian and Spanish operators leverage these channels to bypass minimum order constraints from integrated suppliers.
- Direct Sales:Mill-to-brand contracts for high-volume food packaging and retail display accounts. German retail chain consolidation concentrates procurement power, rewarding suppliers with certified circular-design capabilities.
- Distributors:Regional stockists buffering inventory for mid-cap converters with variable demand patterns. Traditional distributor-mediated procurement is displacing toward direct relationships in chilled ready-meal segments.
- Wholesalers:Bulk resellers serving event planning and temporary display markets with commoditized paper and vinyl grades. Price sensitivity dominates purchasing criteria in this channel.
Direct sales hold the largest share; online channels are expanding most quickly among small-format specialty operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German liner converters supply shelf-ready formats to French and Benelux retail chains, creating a dense trade corridor that shapes substrate specification standards across Northern Europe.
Germany
Centralized discounter consolidation compresses procurement timelines for certified fiber substrates. The EU Packaging and Packaging Waste Regulation mandates recyclability targets that accelerate kraft liner substitution. The Rhine-Ruhr industrial cluster hosts integrated pulp-to-liner operations serving high-volume food contracts.
France
Meal-kit distributors drive specification of pre-printed kraft liners with integrated moisture barriers for chilled protein shipments. EMA guidelines on food-contact materials tighten ink formulation standards for quick-service packaging. The Paris Basin concentration of specialty food packers faces disproportionate REACH compliance burdens.
United Kingdom
Post-consumer fiber conversion R&D hubs demonstrate technical viability of retail-ready liners from recovered corrugated feedstock. Extended producer responsibility fee structures based on recyclability performance favor fiber architectures. The Midlands packaging belt anchors circular-design converter operations.
Spain
Drive-through standardization across Iberian markets opens specification windows for grease-resistant pre-printed liners. Vinyl substrates retain share in promotional display applications where humidity tolerance commands premium positioning. The Barcelona corridor concentrates export-bound graphic overlay production.
Italy
Small-format specialty food packers leverage online channels to bypass minimum order constraints from integrated suppliers. REACH Annex XVII restrictions on phthalates and heavy metals accelerate qualification of bio-based pigment systems. The Emilia-Romagna packaging district specializes in premium retail display formats.
Pre-Printed Liners Market Competitive Environment
Listed leaders compete with private specialists across substrate certification capabilities. The vendor base organizes around three tiers: integrated multinational suppliers with captive pulp operations, regional converters with circular-design R&D capabilities, and mid-cap specialists dependent on third-party substrate sourcing. Competitive moves concentrate on direct mill-to-brand contracting and water-based barrier coating qualification.
Within the integrated multinational tier, Smurfit Kappa Group and Mondi Group exemplify scale-driven positions. Smurfit Kappa occupies a position tied to Iberian and Latin American corrugated-liner co-location. Mondi represents the pulp-to-liner operational archetype across Central European mill networks. DS Smith Plc anchors the circular-design specialist archetype through UK and Benelux R&D hub configurations.
| Leading Market Players |
|---|
| Smurfit Kappa Group |
| Mondi Group |
| DS Smith Plc |
| International Paper Company |
| WestRock Company |
| Georgia-Pacific LLC |
| Oji Holdings Corporation |
| Nippon Paper Industries Co., Ltd. |
| Stora Enso Oyj |
| Others |
Value Chain & Pricing Dynamics
Eighteen-month forward contracting windows now standard among German retail chains compress margin recovery timelines while amplifying pricing power for certified fiber substrate suppliers. This lead-time compression concentrates procurement leverage with integrated pulp-to-liner operators who can guarantee substrate consistency against fixed sustainability KPIs.
Pricing Analysis
Water-based barrier coating technology versus conventional solvent-based formulations versus next-generation bio-based alternatives stratifies pricing across three performance tiers. Premium-mid-economy pricing differentiation separates converters with in-house formulation capability from commodity substrate resellers. Price differentiation hinges on REACH-compliant ink certification and volume scale commitments. Cost compression in standard kraft grades is intensifying because Nordic softwood pulp volatility transfers unevenly through contract structures. Small-format specialty packers in Italy and Spain exhibit highest price sensitivity due to minimum order constraints.
Supply Chain Analysis
Sweden and Finland anchor softwood pulp supply for kraft liner substrates, while Germany and France concentrate converter operations serving Northern European food packaging demand. Raw material inputs draw from Nordic bleached softwood pulp, post-consumer corrugated feedstock, and bio-based barrier coating formulations. Single-source vulnerability concentrates in centralized retail chain procurement where eighteen-month contracts lock suppliers to fixed specifications. Distribution runs through direct mill-to-brand contracts displacing traditional distributor mediation in chilled ready-meal segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-printed liner incumbents face substitution pressure from plastic film alternatives where dimensional stability and chemical resistance command premium positioning in graphic overlay applications.
For Market Incumbents: Secure water-based barrier coating formulation capability before REACH chemical restrictions tighten supplier pools for compliant food-contact specifications. Deepen backward integration into post-consumer fiber conversion to defend margin position against pulp cost volatility. Anchor capacity in Rhine-Ruhr and Benelux clusters where circular-design R&D hubs demonstrate technical viability of retail-ready liners from recovered corrugated feedstock. For New Entrants and Emerging Players: Small-format online channel penetration represents the most penetrable white-space where Italian and Spanish specialty packers bypass minimum order constraints from integrated multinational suppliers. Target meal-kit distributor segments requiring branded unboxing experiences with customized kraft liner specifications. Pursue certification-first go-to-market positioning against EMA food-contact guidelines to differentiate from commodity substrate resellers. For Investors and Strategic Acquirers: Long-term, this sits as a circular-economy infrastructure play because extended producer responsibility fee structures based on recyclability performance create sustained competitive advantage for fiber-based architectures. Acquisition targets should display integrated pulp-to-liner operations or captive post-consumer fiber conversion capability. Monitor per-fluorinated substance ban implementation timelines as inflection indicator for grease barrier reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Barrier Coating Qualification | REACH-compliant formulations bifurcate procurement pools between integrated converters and third-party dependent suppliers. |
| Post-Consumer Fiber Conversion Scale-Up | Benelux R&D hubs demonstrate retail-ready liner viability from recovered corrugated feedstock against EU recyclability mandates. |
| Direct Mill-to-Brand Contracting | German retail chain consolidation rewards suppliers with certified circular-design capabilities through eighteen-month forward agreements. |
| Bio-Based Pigment System Investment | REACH Annex XVII restrictions on phthalates accelerate qualification of color-fast alternatives for food-contact applications. |
| Multi-Jurisdiction Certification Sequencing | Exporters serving EU, US, and Indian markets must align EMA, FDA, and BIS approval timelines with divergent testing protocols. |
Study Parameters
A standing panel of converter operations managers, retail chain procurement directors, food packaging R&D leads, and regulatory compliance officers provided ongoing calibration against secondary validation from EU Packaging and Packaging Waste Regulation filings, ECHA REACH substance database, trade customs records for liner substrate flows, and pulp futures market data. Bottom-up volume estimates triangulated with top-down market sizing across substrate type and application segments.
Consistency checks validated volume and value outputs against external pulp price indices and converter capacity utilization benchmarks across the analysis window. Segmentation modeling incorporated substrate material, application end-use, geographic production cluster, and certification tier dimensions. CAGRs derived from regression analysis of historical procurement volume patterns and forward contract pipeline visibility, with pulp cost pass-through assumptions and regulatory implementation timelines as key forecast inputs.
Underlying assumptions cover EU recyclability mandate enforcement timelines, pulp price volatility bands, and barrier coating technology adoption curves, with deviation risk concentrated in per-fluorinated substance ban acceleration and centralized retail procurement consolidation pace. Recalibration cycles align with material shifts in EMA guideline revisions and extended producer responsibility fee structure implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Printing
Pre-Press for Packaging Market
Packaging Printing
Pigment Hot Stamping Foil Market
Packaging Printing
Pad Printing Machine Market
Packaging Printing
Label Printers Market
Packaging Printing
Stamping Foils Market
Packaging Printing
Thermal Transfer Overprinter Market
Packaging Printing
Flexographic Printing Market
Packaging Printing
Global Hot Foil Stamp Printing Machine Market
Packaging Printing
Global Thermal Transfer Ribbon Market
Packaging Printing
Electrophotography Printing for Packaging Market
Packaging Printing
Hot Foil Printing Machines Market
Packaging Printing
Lithographic Printing for Packaging Market
Packaging Printing
Rotogravure Printing Machine Market
Packaging Printing
Laser Coders Market
Packaging Printing
Digital Label Printing Market
Packaging Printing
Flex Banner Market