
 Stand Alone Label Applicator Market | 2026-2036
Stand Alone Label Applicator Market Size, Share, and Industry Trends Forecast 2026-2036
Stand Alone Label Applicator Market Analytics
Chinese OEM producers of pneumatic labeling machinery is broadening output capacity for fully automatic applicator systems. ProMach leverages integrated packaging automation platforms to serve multinational food processors. Herma GmbH anchors European demand through precision-engineered rotary wipe-on systems. Label-Aire specializes in vacuum-fed tamp-blow configurations for irregular pharmaceutical containers.
A stand alone label applicator is a self-contained machine that applies pressure-sensitive labels to products, containers, or packaging using pneumatic, electric, or servo-driven dispensing mechanisms with typical throughput rates of 20 to 1,500 labels per minute depending on configuration. Its primary commercial purpose is to automate product identification, traceability encoding, and brand communication without requiring integration into larger packaging lines. Fully automatic applicators capture the dominant margin pool due to pharmaceutical serialization mandates and high-volume beverage operations. Benchtop systems serve contract packagers and specialty cosmetics producers with low-volume, high-SKU flexibility. Portable applicators are gaining traction among third-party logistics providers for mobile inventory management in distributed warehouse networks.
FDA traceability rules under the Food Safety Modernization Act compel food manufacturers to upgrade legacy labeling equipment with lot-code and allergen declaration capabilities. The EU MDR and Falsified Medicines Directive enforce unit-level serialization that drives pharmaceutical demand for vision-verified applicator systems. ISO 9001 quality management and CE machinery directives shape product certification requirements for cross-border equipment sales. Stakeholders must weigh total cost of ownership against compliance latency when selecting between retrofit upgrades and greenfield automatic installations.
Market Dynamics
Pharmaceutical serialization mandates and food traceability regulations are forcing manufacturers to replace pneumatic legacy systems with vision-verified servo-driven applicators, compressing replacement cycles and elevating equipment specifications across high-volume packaging lines.
Growth Catalysts
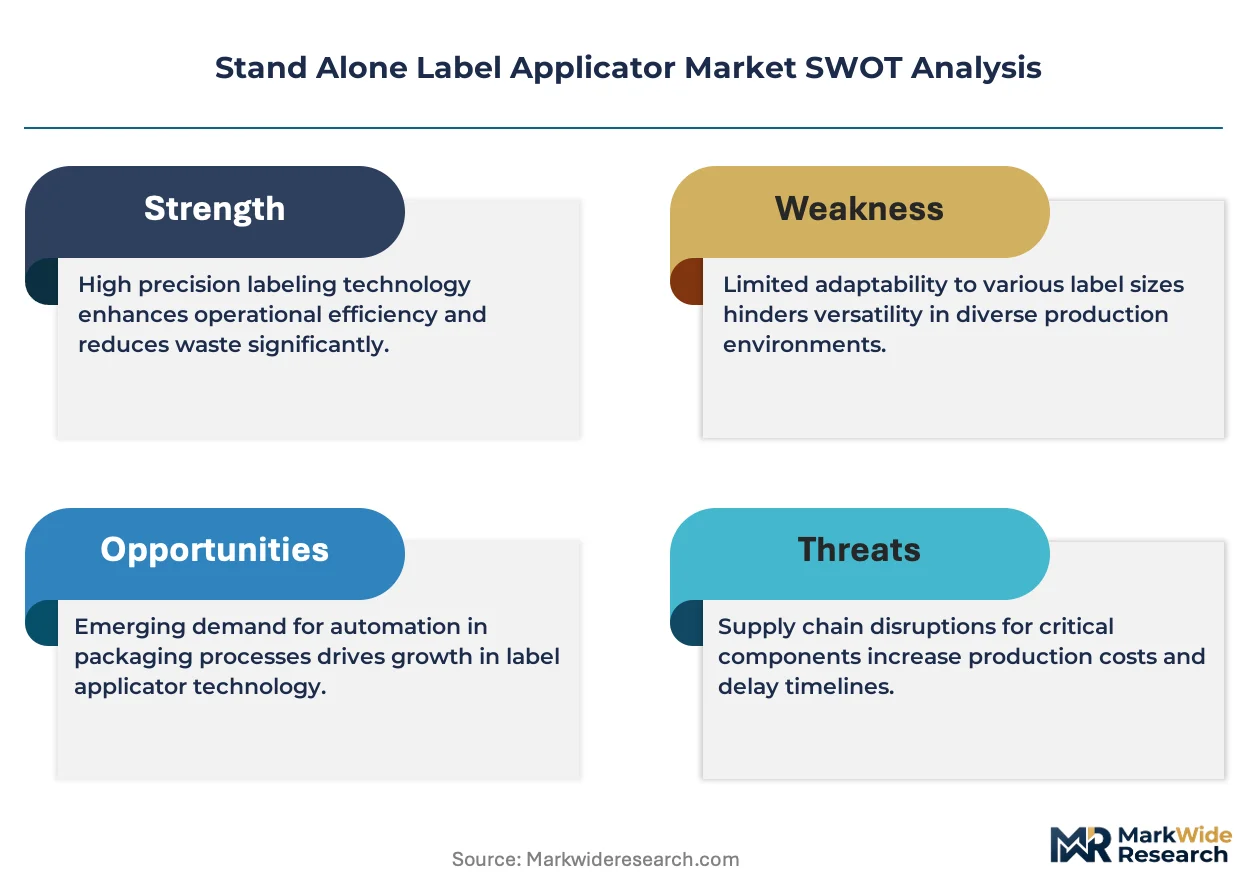
- FDA Food Safety Modernization Act traceability rules:Food manufacturers must upgrade labeling equipment with lot-code and allergen declaration capabilities, triggering systematic replacement of legacy pneumatic systems across US processing facilities.
- EU Falsified Medicines Directive serialization:Pharmaceutical manufacturers in Germany and neighboring markets are expanding automated labeling lines to comply with unit-level tracking requirements, driving demand for vision-integrated rotary systems.
- Servo-driven dispensing mechanisms:Precision-engineered motion control is displacing compressed-air systems in high-speed beverage operations, enabling throughput rates exceeding 1,000 labels per minute with reduced maintenance intervals.
Market Restraints
- Stainless steel and electronic component cost volatility:Input price swings for servo motors and food-grade alloys compress margins for mid-tier equipment producers, forcing selective material substitution or pricing adjustments.
- Supply concentration in Chinese pneumatic component manufacturing:Dependency on a limited geography for valves, cylinders, and regulators creates vulnerability to trade policy shifts and extended lead times for legacy system spare parts.
- Technical limitation in adhesive performance at temperature extremes:Pressure-sensitive label adhesion degrades in frozen supply chains and high-heat sterilization environments, restricting applicator deployment in certain pharmaceutical and food segments.
Strategic Opportunities
- Underpenetrated third-party logistics warehouse networks:Portable battery-powered applicators enable mobile inventory relabeling for distributed fulfillment centers, addressing SKU proliferation without fixed infrastructure investment.
- Convergence of machine vision and thermal transfer printing:Integrated inspection and encoding systems allow real-time defect rejection and variable data printing, creating premium positioning for applicator OEMs serving pharmaceutical serialization.
- EU Medical Device Regulation (MDR) unique device identification:The expanded mandate beyond pharmaceuticals to medical devices opens incremental demand for benchtop and semi-automatic systems in contract sterilization and packaging services.
Industry Challenges
- Servomechatronics and vision systems engineering talent scarcity:The specialized skill set combining motion control programming with optical inspection calibration is concentrated among a limited pool of automation engineers, constraining R&D velocity for smaller equipment builders.
- CE machinery directive and ISO 9001 certification timelines:Cross-border equipment sales require extensive documentation and third-party assessment, delaying market entry for novel applicator designs by 12-18 months.
- Integration complexity with existing packaging line PLCs:Retrofit projects demand custom communication protocols and mechanical interfacing, extending commissioning periods and elevating total project risk for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stand Alone Label Applicator Market |
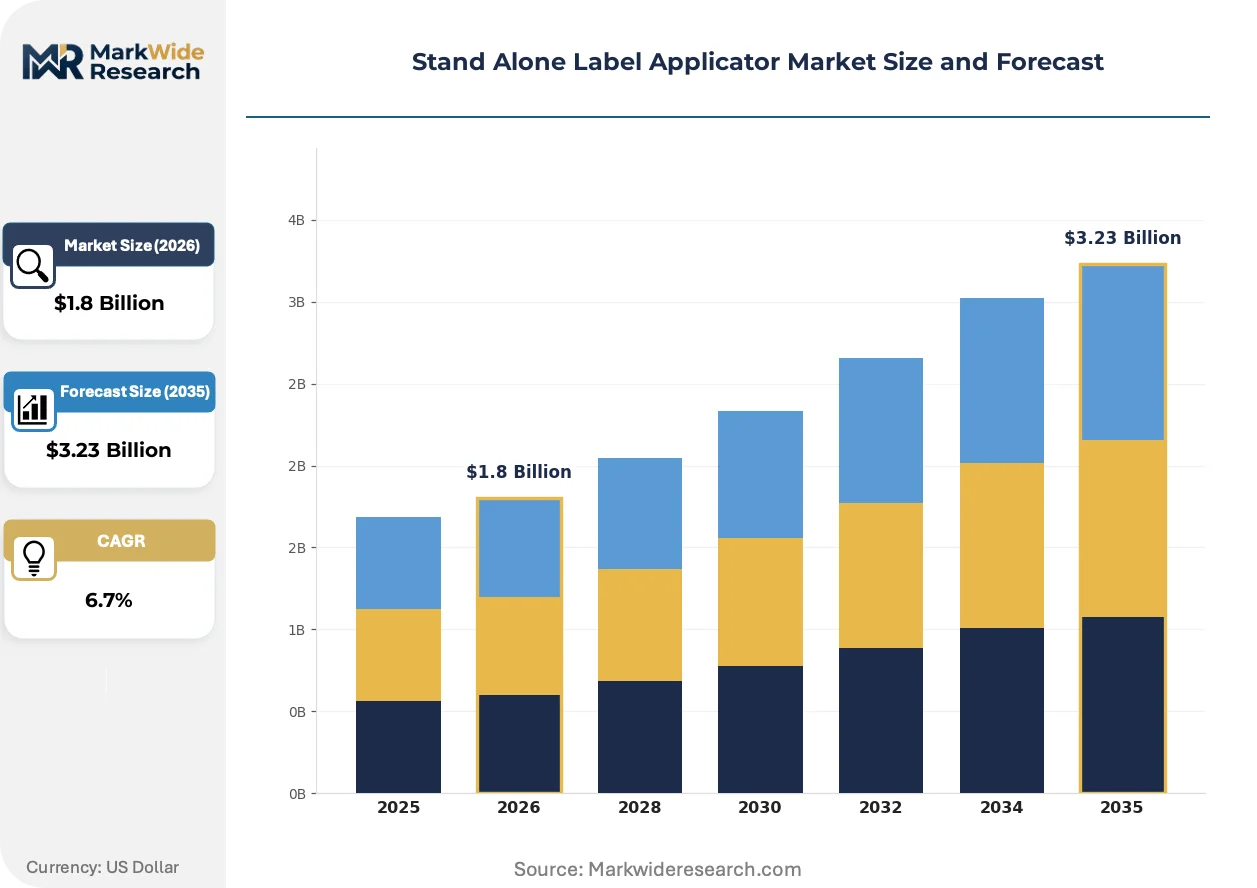
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benchtop Applicators, Semi-Automatic Applicators, Fully Automatic Applicators, Portable Applicators Industry Vertical: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Application: Packaging, Inventory Management, Regulatory Compliance, Brand Promotion End User: Manufacturers, Distributors, Retailers, Warehouses |
| Companies Covered | ProMach, Label-Aire, Quadrel Labeling Systems, CTM Labeling Systems, Videojet Technologies, Herma GmbH, Accraply, Weber Packaging Solutions, EPI Labelers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stand Alone Label Applicator Market Evolving Landscape
Automation architecture is converging around modular, data-native platforms that embed compliance verification directly into labeling operations, eliminating downstream inspection stations and enabling real-time supply chain traceability.
Servo-driven tamp-blow and wipe-on mechanisms are consolidating control of high-speed pharmaceutical and beverage lines. These systems deliver positional accuracy within 0.5 millimeters at sustained throughputs above 1,200 labels per minute. Major contract packagers and multinational food processors are standardizing on these platforms to reduce changeover downtime. The technology is consolidating market share previously fragmented across pneumatic, mechanical, and hybrid drive configurations.
REACH substance restrictions and EU MDR technical documentation requirements are elevating material traceability and chemical safety disclosures for labeling adhesives and substrates. Equipment suppliers must now validate that consumable pathways comply with restricted substance lists and support audit-ready documentation. Pharmaceutical and medical device manufacturers in Germany, France, and Italy are prioritizing applicator suppliers with integrated material certification databases.
Equipment-as-a-service and performance-based maintenance contracts are displacing traditional capital purchase models among mid-volume cosmetics and specialty food producers. Third-party logistics providers and regional contract packagers are adopting subscription pricing to preserve working capital and transfer obsolescence risk. This shift is most visible in the United States, where private-equity-backed packaging roll-ups favor operational expenditure structures that align costs with throughput volumes.
Stand Alone Label Applicator Market Segmentation
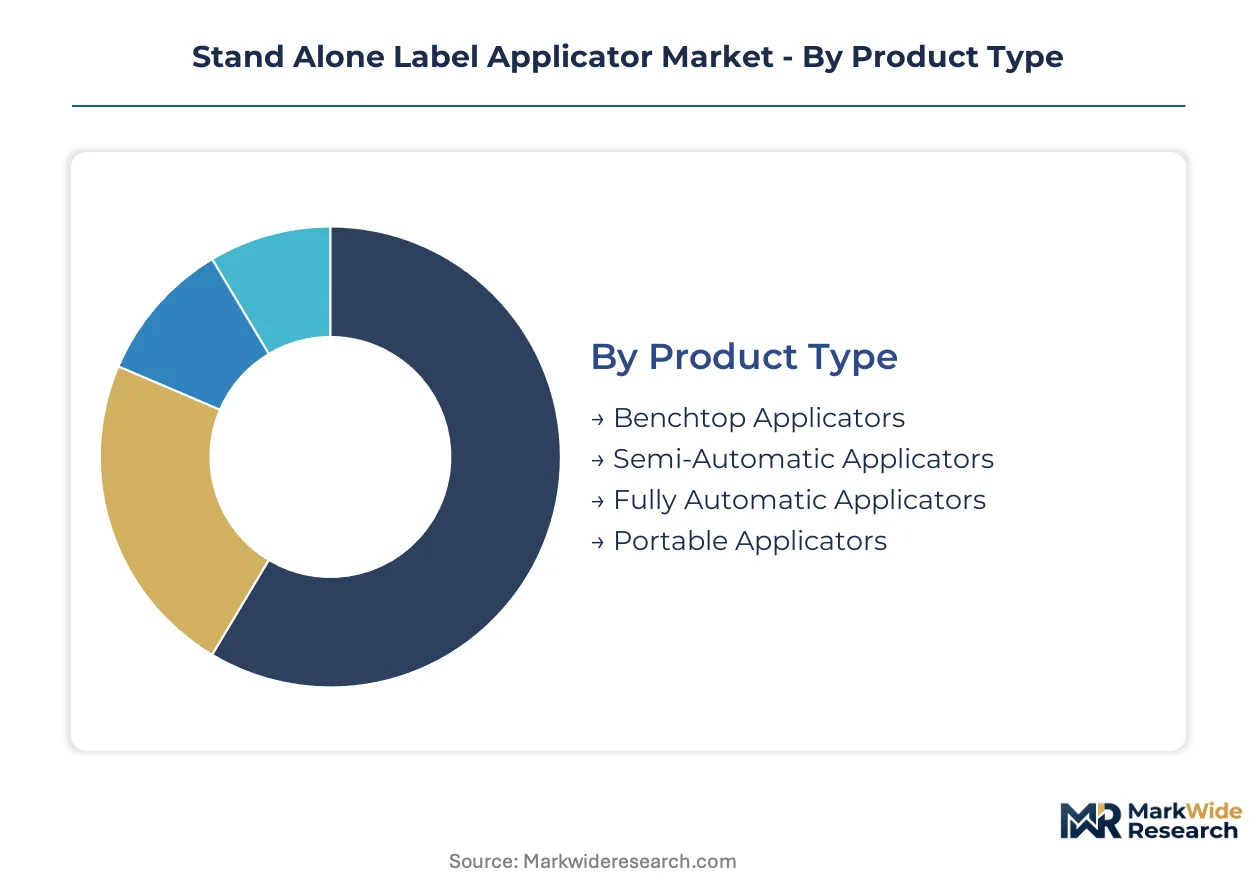
Equipment replacement cycles across pharmaceutical and food processing facilities create distinct demand profiles for each applicator configuration. Segmentation reveals how regulatory pressure and operational scale determine technology selection and margin capture.
Product Type:
Upgrade timelines diverge sharply between legacy pneumatic retrofits and greenfield servo installations, with compliance deadlines compressing procurement decisions.
- Fully Automatic Applicators:Vision-verified servo systems deliver positional accuracy within 0.5 millimeters at throughputs exceeding 1,200 labels per minute. Pharmaceutical manufacturers in Germany deploy these for EU Falsified Medicines Directive serialization, while US beverage processors adopt them to meet FDA Food Safety Modernization Act lot-code mandates.
- Benchtop Applicators:Compact units serve contract packagers and specialty cosmetics producers requiring rapid changeover between high-SKU batches. Demand clusters among mid-volume European cosmetics houses and North American craft food processors seeking serialization compliance without line-scale capital commitment.
- Semi-Automatic Applicators:Hybrid pneumatic-servo configurations bridge legacy infrastructure and precision requirements for mid-tier food manufacturers.
- Portable Applicators:Battery-powered mobile units enable third-party logistics providers to relabel inventory across distributed warehouse networks without fixed infrastructure.
Volume placements concentrate in fully automatic systems; the faster expansion belongs to portable applicators.
Industry Vertical:
Margin structures align with regulatory stringency, where serialization mandates command premium equipment specifications and extended service contracts.
- Pharmaceuticals:Unit-level tracking requirements under EU MDR and FDA DSCSA drive demand for vision-integrated rotary wipe-on systems with real-time defect rejection. German and Swiss manufacturers anchor this segment with validation documentation for cross-border equipment sales.
- Food & Beverage:Allergen declaration and lot-code traceability rules compel systematic replacement of legacy pneumatic applicators across US processing facilities. Major contract packagers standardize on servo-driven platforms to reduce changeover downtime between production runs.
- Cosmetics:High-SKU flexibility requirements favor benchtop and semi-automatic configurations for regional contract packagers.
- Electronics:ESD-safe labeling systems serve semiconductor and component manufacturers with precision placement for small-format devices.
Revenue concentration sits with pharmaceutical mandates; cosmetics applications are climbing the fastest as clean beauty labeling requirements proliferate.
Application:
Functional requirements determine integration complexity, with compliance encoding demanding higher specification than brand communication.
- Regulatory Compliance:Serialization and traceability encoding require thermal transfer printing with machine vision verification. FDA traceability rules and EU Falsified Medicines Directive enforcement elevate specifications for pharmaceutical and medical device labeling.
- Packaging:Primary and secondary container labeling dominates throughput volumes across beverage and food processing lines. Servo-driven wipe-on mechanisms consolidate share in high-speed operations previously fragmented across pneumatic configurations.
- Inventory Management:Variable data printing enables real-time SKU relabeling for third-party logistics networks and warehouse redistribution.
- Brand Promotion:Promotional and seasonal label applications favor flexible benchtop systems for short-run campaigns.
Equipment value pools in compliance encoding; inventory management applications show steepest expansion trajectory.
End User:
Capital deployment patterns separate integrated manufacturers from service providers, with ownership models shifting toward subscription structures.
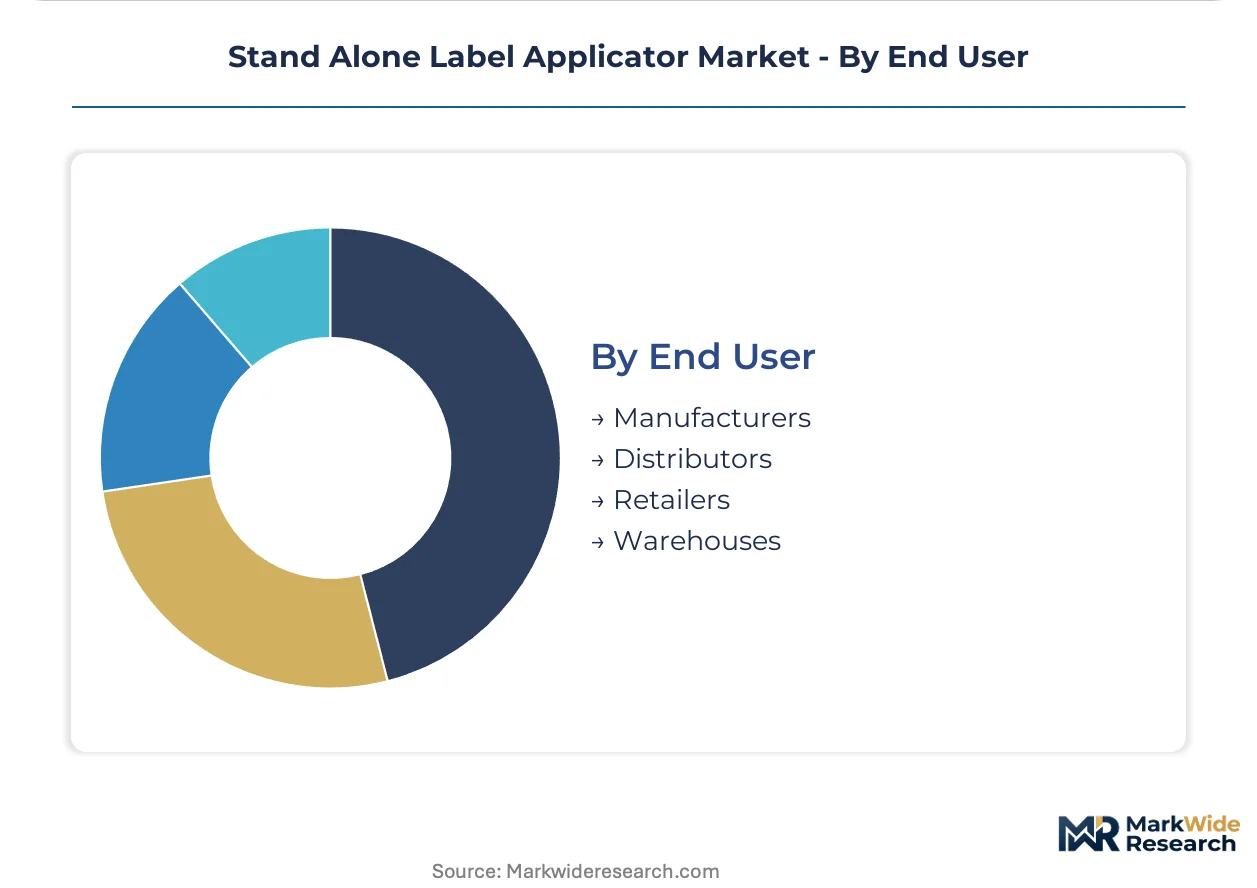
- Manufacturers:Multinational food processors and pharmaceutical houses drive demand for fully automatic systems with integrated packaging line PLCs. Equipment-as-a-service contracts are displacing traditional capital purchases among mid-volume producers.
- Warehouses:Distributed fulfillment centers adopt portable battery-powered applicators to address SKU proliferation without fixed infrastructure investment. Third-party logistics providers in the United States favor operational expenditure structures aligned with throughput volumes.
- Distributors:Regional redistribution networks require mobile relabeling capability for cross-dock operations and returns processing.
- Retailers:Private-label and seasonal relabeling demands favor flexible benchtop configurations for in-house packaging operations.
Procurement scale favors manufacturers; warehouse adoption is gaining share fastest as e-commerce fulfillment networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless steel feedstock from German Ruhr Valley mills and servo motor component clusters in Shenzhen anchor equipment supply chains for label applicator manufacturing across key demand markets.
United States
FDA Food Safety Modernization Act traceability mandates compel food processors to replace pneumatic legacy systems with servo-driven applicators. The agency's lot-code and allergen declaration requirements compress replacement cycles across Midwest meatpacking and California produce operations. Chicago-area contract packagers anchor demand for high-throughput rotary systems serving multinational beverage brands.
Germany
EU Falsified Medicines Directive serialization deadlines drive pharmaceutical manufacturers toward vision-verified applicator platforms. EMA enforcement of unit-level tracking elevates specifications for rotary wipe-on systems in Baden-Württemberg medical device corridors. Stuttgart precision engineering clusters supply servo-mechatronics to domestic OEMs serving Swiss and French pharmaceutical exporters.
China
Pneumatic component manufacturing concentrates in Zhejiang and Guangdong provinces, supplying valves and cylinders for cost-optimized benchtop systems. NMPA pharmaceutical packaging regulations increasingly align with international serialization standards, elevating domestic demand for vision-integrated platforms. Shenzhen electronics clusters feed servo motor supply chains for emerging fully automatic applicator producers.
Japan
METI industrial automation incentives support precision labeling equipment for semiconductor and electronics component manufacturers. PMDA pharmaceutical serialization requirements mirror EU and US standards, driving demand for high-accuracy tamp-blow configurations. Nagoya automotive supplier networks adopt portable applicators for just-in-time inventory relabeling across distributed component warehouses.
India
CDSCO pharmaceutical export compliance requirements push contract manufacturers toward serialization-capable labeling infrastructure. FSSAI food traceability regulations expand beyond metros into Gujarat and Maharashtra processing corridors. Mumbai-Pune industrial belts anchor demand for semi-automatic systems serving mid-volume cosmetics and specialty food producers.
Stand Alone Label Applicator Market Competitive Landscape
Global majors compete with regional champions across automation integration depth and regulatory compliance documentation capabilities. The vendor base stratifies between multinational packaging platforms with integrated line control and specialized applicator OEMs with precision dispensing expertise. Three archetypes dominate: full-line automation integrators, precision dispensing specialists, and pneumatic component fabricators serving cost-sensitive segments. M&A activity concentrates on vision system and motion control technology tuck-ins, while capacity expansion targets servo motor supply security and regional service network density.
Among German precision engineering houses, Herma GmbH and Weber Packaging Solutions occupy positions emphasizing rotary wipe-on accuracy for pharmaceutical serialization. ProMach represents the integrated platform archetype, anchoring multinational food processor relationships through packaging line automation breadth. Label-Aire exemplifies the specialized dispensing tier with vacuum-fed configurations for irregular container geometries. These three anchors illustrate how competitive positioning diverges between compliance depth, integration breadth, and application-specific engineering.
| Leading Market Players |
|---|
| ProMach |
| Label-Aire |
| Quadrel Labeling Systems |
| CTM Labeling Systems |
| Videojet Technologies |
| Herma GmbH |
| Accraply |
| Weber Packaging Solutions |
| EPI Labelers |
| Others |
Value Network & Pricing Analysis
Servo-driven dispensing mechanisms replacing pneumatic legacy systems simultaneously compress manufacturing cost curves and concentrate component sourcing among precision motion-control specialists. This technology transition elevates capital intensity for OEMs while fragmenting pricing power between integrated platform providers and specialized dispensing engineers.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium-tier suppliers from unbundled equipment-only transactions. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 certification grade and CE machinery directive compliance depth. Cost compression in mid-tier pneumatic retrofits is intensifying because Chinese valve and cylinder imports face tariff exposure. Contract packagers and regional cosmetics houses exhibit highest price sensitivity; pharmaceutical serialization mandates render German and Swiss OEM customers least sensitive to equipment premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from multinational food processors and pharmaceutical houses, while distributor networks serve mid-volume contract packagers. Component manufacturing concentrates in China for pneumatic valves and cylinders, Germany for precision servo-mechatronics, and Japan for high-accuracy motion controllers. Stainless steel feedstock draws from Ruhr Valley mills; electronic components feed from Shenzhen clusters. Single-source vulnerability in Chinese pneumatic component manufacturing creates exposure to trade policy shifts. Distribution runs through regional packaging automation integrators with local service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo motor and precision motion-control engineering talent scarcity props pricing power for incumbent OEMs with captive technical capabilities. Capacity bottlenecks in certified vision-system calibration constrain supply expansion.
For Market Incumbents: To counter emerging Chinese fully automatic applicator producers, anchor relationships through equipment-as-a-service contracts that transfer obsolescence risk. Deepen backward integration into servo motor supply chains to secure component availability against Shenzhen cluster concentration. Prioritize CE machinery directive and FDA validation documentation investments to maintain cross-border sales barriers. For New Entrants and Emerging Players: E-commerce-enabled direct sales channels bypass established distributor networks to reach mid-volume cosmetics and specialty food producers. Portable battery-powered applicators for third-party logistics warehouse networks represent the most penetrable white-space segment. Target subscription pricing models to align with private-equity-backed packaging roll-up preference for operational expenditure structures. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated packaging automation platforms seeking dispensing expertise tuck-ins. Five-to-ten year viability hinges on regulatory compliance documentation capabilities rather than commodity hardware manufacturing. Monitor NMPA alignment with international pharmaceutical serialization standards as inflection signal for Chinese domestic demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Vision System Integration | Machine vision convergence with thermal transfer printing enables real-time defect rejection for FDA DSCSA compliance. |
| Servo Motor Supply Security | Captive production of precision motion controllers reduces dependency on Shenzhen electronics cluster concentration. |
| Equipment-as-a-Service Launch | Subscription pricing transfers obsolescence risk for mid-volume cosmetics producers seeking working capital preservation. |
| Portable Applicator Development | Battery-powered mobile units address SKU proliferation across distributed third-party logistics fulfillment networks. |
| Regulatory Certification Investment | CE machinery directive and ISO 9001 documentation accelerates cross-border market entry for novel applicator designs. |
Research Methodology
Multi-period observation of equipment replacement cycle timing and regulatory compliance deadline clustering anchored the trend analysis, supplemented by interviews with packaging line engineers, pharmaceutical manufacturing directors, contract packager operations heads, and aftermarket service managers. Secondary validation drew from FDA Food Safety Modernization Act guidance documents, EMA Falsified Medicines Directive implementation reports, SEC filings of publicly traded packaging automation platforms, and customs trade data for pneumatic component imports. Bottom-up triangulation across applicator configuration demand profiles converged with top-down pharmaceutical and food processing capital expenditure tracking.
Input-output matrices modeled unit placements against regulatory mandate enforcement schedules across the projection horizon. Segmentation dimensions included automation level, industry vertical, application function, and end-user ownership model. CAGRs were derived from replacement cycle compression analysis and greenfield installation tracking. Forecast inputs incorporated servo motor cost curve trajectories and REACH substance restriction compliance cost burdens.
The model holds under stable regulatory enforcement timelines; deviation in FDA or EMA deadline extensions would shift equipment procurement phasing. Forecasts reflect base assumptions regarding stainless steel and electronic component cost volatility. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Freezer Label Market
Labels
GCC Labeling Market
Labels
BOPP Labels Market
Labels
Global Label Adhesive Market
Labels
Retro-Reflective Labels Market
Labels
Repositionable Labels Market
Labels
Water Dissolvable Labels Market
Labels
APAC on-Demand Color Labels Market
Labels
Global Pressure Labels Market
Labels
Shrink Sleeve Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
Tags Market
Labels
Global Waterproof Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Label Applicator Market
Labels
Polyester Labels Market