
 Global Automotive Labels Market | 2026-2036
Global Automotive Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Labels Market Analysis
Digital printing integration with RFID encoding is narrowing the gap between decorative branding and functional traceability in automotive label production. Avery Dennison Corporation leverages its materials science portfolio to anchor premium positions in pressure-sensitive adhesives for EV battery packs. 3M Company sustains technology leadership through specialized high-temperature substrates that withstand powertrain thermal cycling. SATO Holdings competes aggressively in Asia-Pacific assembly plant automation, where real-time label verification reduces recall liability.
Automotive labels are engineered identification and communication substrates, typically constructed from polyester or polypropylene films with silicone or acrylic adhesive layers, designed to withstand temperatures from minus forty to one hundred fifty degrees Celsius while retaining legibility under chemical exposure and UV degradation. Their primary purpose spans regulatory compliance marking, component traceability, brand identification, and safety warning communication across vehicle lifecycles. Pressure sensitive labels dominate value capture due to versatile application across curved interior surfaces and compatibility with automated dispensing equipment, while thermal transfer labels represent the fastest-expanding category as OEMs mandate machine-readable durability for under-hood and battery system identification. Shrink sleeves concentrate margin pools in exterior branding applications where three-hundred-sixty-degree graphic coverage and fuel-resistant properties command pricing premiums.
The EPA enforces emissions-related labeling permanence standards that directly shape adhesive specification requirements for under-hood applications in the United States. ECHA's REACH restrictions on hazardous substances, including specific phthalate plasticizers and heavy metal pigments, are forcing reformulation of vinyl-based labels across European supply chains. Japan's METI promotes JIS standard harmonization for QR-coded component traceability, creating compliance-driven replacement cycles. Stakeholders must monitor how battery passport regulations in multiple jurisdictions will expand data-carrying requirements beyond traditional barcode capacity into embedded memory solutions.
Market Dynamics
Electric vehicle battery passport mandates are forcing label manufacturers to embed machine-readable data carriers directly into thermal management substrates, compressing the traditional separation between identification and sensing functions.
Growth Catalysts
- EU Green Deal circularity requirements:REACH-compliant recyclable polyester substrates now command procurement preference across German automotive OEM supplier networks, accelerating substrate reformulation investments.
- Powertrain thermal cycling intensity:EV battery pack architectures expose labels to sustained temperatures above 120°C, expanding addressable demand for silicone adhesive laminates with ceramic filler reinforcement.
- Japan METI traceability harmonization:JIS-standard QR code mandates for component-level tracking are triggering replacement cycles across Toyota and Honda domestic supply chains.
Market Restraints
- Petrochemical feedstock volatility:Biaxially-oriented polypropylene film costs fluctuate with propylene monomer spot pricing, compressing margin predictability for pressure-sensitive label converters.
- Adhesive raw material concentration:Acrylic polymer supply clusters in the US Gulf Coast and Rotterdam-Antwerp corridor create geographic vulnerability to weather-related production interruptions.
- Vinyl substrate obsolescence:ECHA phthalate plasticizer restrictions are rendering legacy calendered PVC formulations non-compliant, forcing stranded inventory write-downs.
Strategic Opportunities
- India PLI scheme localization:Automotive component manufacturing incentives are attracting label converters to Gujarat and Tamil Nadu industrial corridors with 15-20 year supply agreements.
- RFID-inlay thermal lamination:Convergence of UHF antenna printing with high-temperature adhesive bonding enables battery passport data embedding without secondary attachment processes.
- US EPA emissions permanence standards:Under-hood label durability mandates are creating specification lock-in for suppliers demonstrating 10-year UV and chemical resistance certification.
Industry Challenges
- Multi-jurisdiction certification backlog:Simultaneous EPA, ECHA, and METI compliance testing stretches laboratory capacity, extending product launch timelines by 8-14 months.
- Legacy thermal transfer equipment incompatibility:Existing barcode printing infrastructure cannot handle RFID-encoded variable data, forcing capital-intensive production line reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Labels Market |
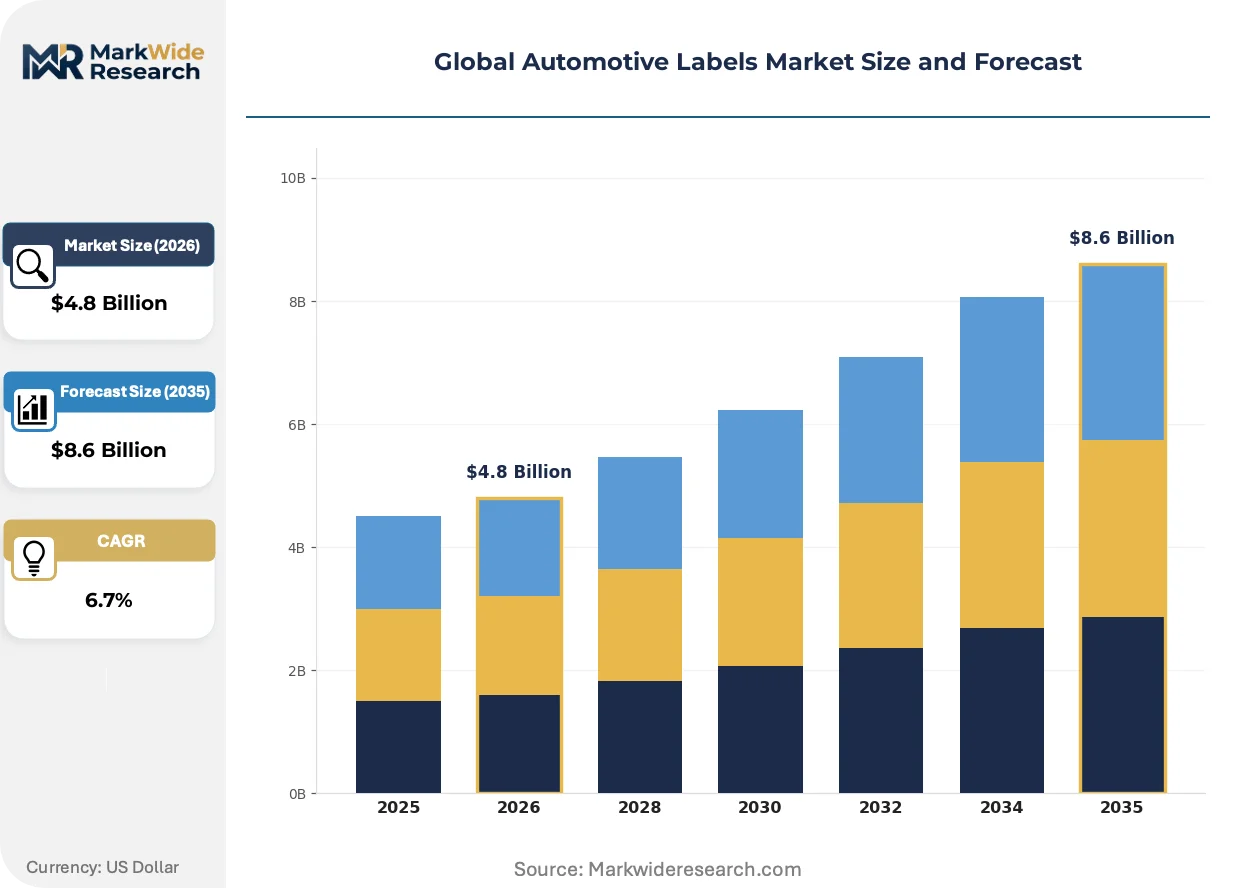
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Sensitive Labels, Shrink Sleeves, In-Mold Labels, Thermal Transfer Labels Application: Interior Branding, Exterior Branding, Safety Labels, Compliance Labels Material: Polyester, Vinyl, Polypropylene, Paper End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships |
| Companies Covered | 3M Company, Avery Dennison Corporation, Brady Corporation, Resource Label Group, CCL Industries, UPM Raflatac, Schreiner Group, SATO Holdings, Polyonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Labels Market Emerging Trajectories
Digital printing workflows are collapsing the traditional separation between short-run customization and high-volume efficiency, enabling label converters to serve EV battery prototype phases without dedicated tooling investments.
Laser-ablated variable data printing is rendering obsolete mechanical embossing and hot-stamp serialization methods in under-hood traceability applications. Tier-1 suppliers to BMW and Volkswagen are adopting this technology for battery module identification within 18-month qualification windows. The shift is compressing minimum order quantities from 50,000 to 500 units while maintaining ECHA-compliant substrate integrity.
REACH Annex XVII substance restrictions are forcing elimination of heavy metal pigments in exterior badge applications. European OEM procurement departments now require third-party certification of cobalt-free colorants for chrome-effect labels. Decorative label specialists are responding with vacuum metallized polyester alternatives that satisfy KBA type-approval durability testing.
Automotive OEMs are consolidating supplier panels from 12-15 regional converters to 3-4 strategic partners with full-service material science capabilities. This concentration is most visible in Germany, where Volkswagen Group and Mercedes-Benz have implemented tiered qualification frameworks that favor converters with in-house adhesive polymerization and RFID antenna design competencies.
Global Automotive Labels Market Segmentation
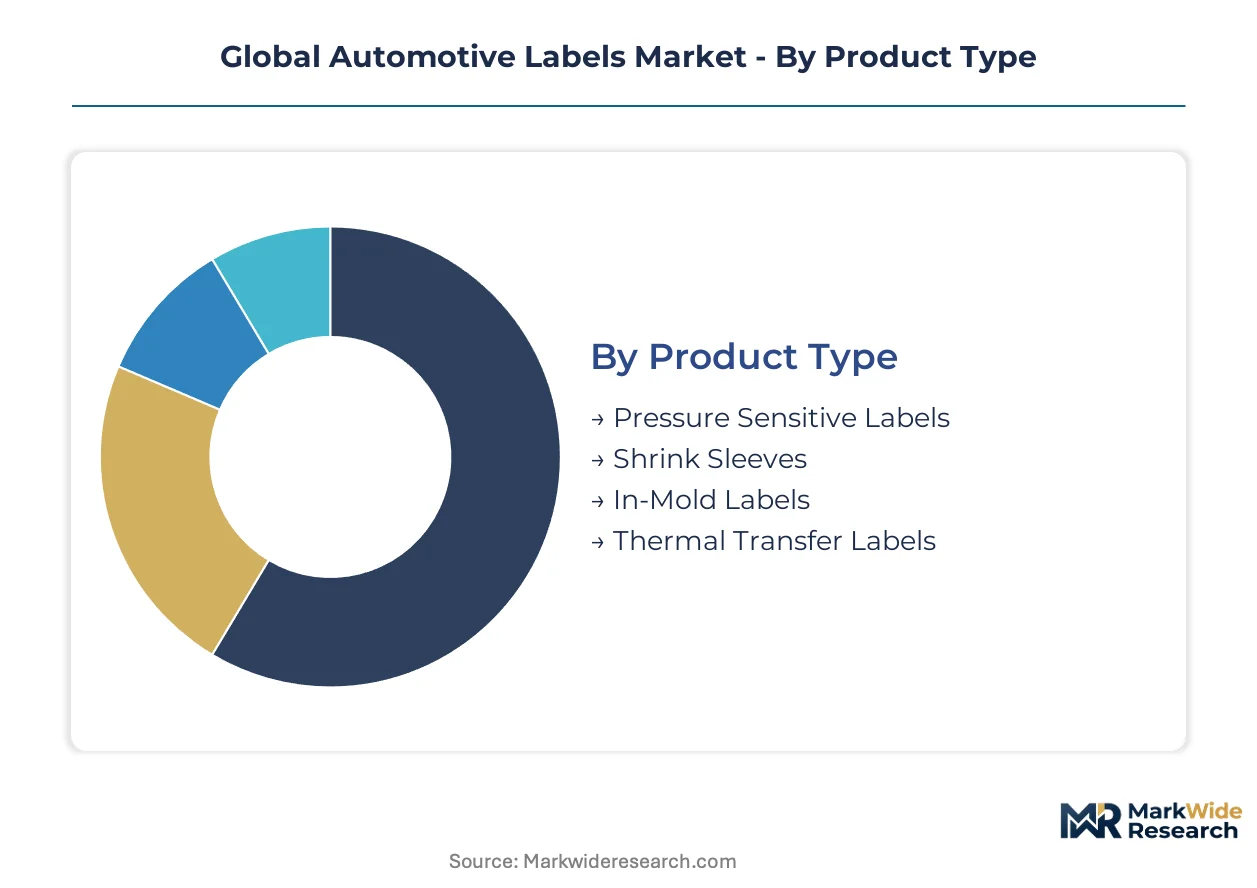
Automotive label segmentation reveals how substrate chemistry, application environment, and supply chain position create distinct margin architectures. Each dimension carries regulatory and thermal specification requirements that reshape procurement criteria across vehicle electrification cycles.
Product Type:
The use-case spectrum spans temporary protective films to permanent under-hood identification systems with radically different adhesive chemistry and durability requirements.
- Pressure Sensitive Labels:Acrylic or silicone adhesive laminates bond instantly to curved interior surfaces without heat activation. German OEM supplier networks now mandate REACH-compliant recyclable polyester backings for these labels across dashboard and door panel applications.
- Thermal Transfer Labels:Ribbons deposit resin or wax-resin ink onto receiving substrates, producing machine-readable barcodes that survive 150°C under-hood exposure. EV battery passport mandates in multiple jurisdictions are accelerating specification of these labels for module-level traceability.
- Shrink Sleeves:Polyolefin or PET-G films conform to irregular shapes through heat application, delivering 360-degree graphic coverage for fluid reservoir branding.
- In-Mold Labels:Pre-printed films fuse with injection-molded plastic during part formation, eliminating secondary labeling operations for climate control bezels and steering wheel badges.
The dominant share belongs to Pressure Sensitive Labels, while Thermal Transfer Labels are expanding most quickly through battery system compliance mandates.
Application:
Cost tier differentiation separates commodity interior markings from premium exterior badges with metallized finishes and extended warranty requirements.
- Interior Branding:Decorative appliques on instrument panels and center consoles prioritize soft-touch haptics and UV stability for 10-year cabin exposure.
- Exterior Branding:Chrome-effect emblems and model designation badges employ vacuum-metallized polyester with ECHA-compliant cobalt-free colorants to satisfy KBA type-approval durability testing.
- Safety Labels:Airbag deployment warnings and tire pressure specifications require ISO 3795 flammability-rated substrates with permanent adhesion to textured plastics.
- Compliance Labels:VIN plates, tire placards, and emissions certification tags must survive pressure washing and chemical exposure across vehicle operating life.
Interior Branding commands volume leadership, though Exterior Branding captures the steepest margin expansion through metallized premium finishes.
Material:
Volume concentration in polypropylene and polyester reflects thermal performance requirements that paper and legacy vinyl cannot satisfy.
- Polyester:Biaxially-oriented PET films with silicone adhesive layers withstand sustained 120°C exposure in EV battery compartments. EU Green Deal circularity requirements are accelerating recyclable substrate reformulation across German OEM supply chains.
- Polypropylene:Oriented PP films offer moisture resistance and conformability at lower cost, dominating under-hood warning labels where extreme temperatures are intermittent rather than continuous.
- Vinyl:Calendered PVC formulations face ECHA phthalate plasticizer restrictions that render legacy inventory non-compliant, forcing stranded asset write-downs across European converters.
- Paper:Uncoated and coated stocks survive only in temporary protective applications and shipping labels, excluded from permanent vehicle marking due to moisture sensitivity.
Polyester holds the technology leadership position, while Polypropylene gains share fastest through cost-optimized thermal transfer applications.
End User:
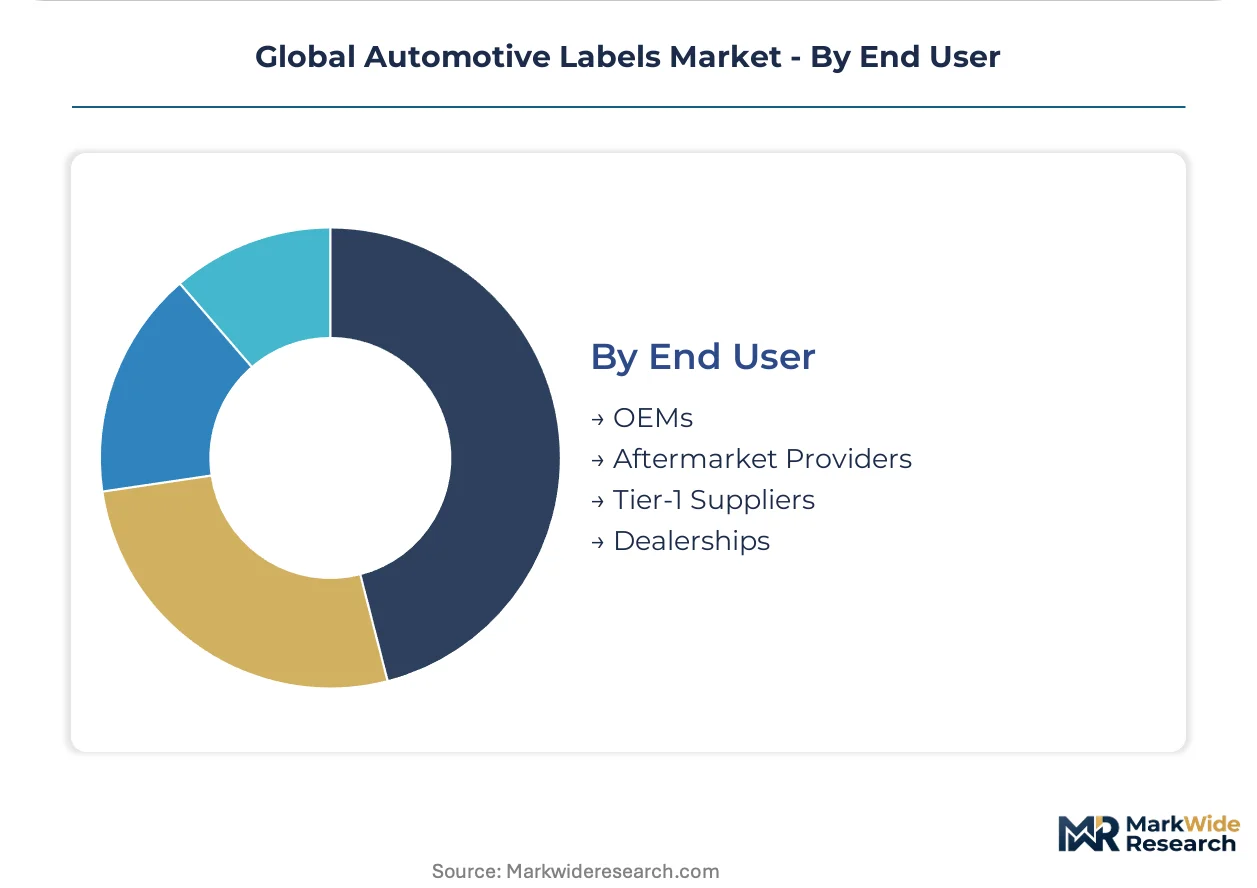
Customer type determines specification authority, with OEMs dictating substrate chemistry and Tier-1 suppliers managing label application automation.
- OEMs:Volkswagen Group and Mercedes-Benz enforce tiered qualification frameworks that favor converters with in-house adhesive polymerization and RFID antenna design competencies.
- Tier-1 Suppliers:Continental and Bosch procurement departments specify labels for integrated modules, requiring real-time verification systems that reduce recall liability.
- Aftermarket Providers:Replacement badge and decal suppliers compete on short-run digital printing flexibility without OEM durability certification requirements.
- Dealerships:Localized branding and compliance tag replacement generate fragmented demand with minimal technical specification barriers.
OEMs dominate specification control, yet Tier-1 Suppliers are capturing volume fastest through integrated module assembly contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive label exports supply battery passport compliance systems to EV assembly plants across Poland, Hungary, and the Czech Republic. This trade corridor channels REACH-certified substrate technology into Central European supplier networks.
United States
EPA emissions permanence standards dictate adhesive specifications for under-hood identification systems across Detroit Three supplier networks. The IRA domestic content bonuses accelerate reshoring of thermal transfer label production to Michigan and Ohio industrial corridors. Converter investments in Toledo and Flint target 10-year UV resistance certification for battery module traceability.
Germany
Volkswagen Group and Mercedes-Benz procurement departments enforce tiered qualification frameworks favoring converters with in-house adhesive polymerization capabilities. KBA type-approval durability testing mandates cobalt-free colorants for exterior chrome-effect badges. Stuttgart and Munich clusters concentrate vacuum-metallized polyester development for premium branding applications.
China
MIIT battery passport regulations expand data-carrying requirements beyond traditional barcode capacity into embedded memory solutions. Dual carbon goals accelerate demand for recyclable polyester substrates in Ningbo and Shenzhen converter facilities. Yangtze River Delta automotive clusters drive specification of silicone adhesive laminates for 120°C thermal management systems.
Japan
METI JIS-standard QR code mandates trigger replacement cycles across Toyota and Honda domestic supply chains. Component-level traceability requirements concentrate procurement authority in Nagoya and Tokyo industrial zones. Converter automation investments in Aichi Prefecture target real-time label verification for recall liability reduction.
India
PLI scheme automotive component manufacturing incentives attract label converters to Gujarat and Tamil Nadu with 15-20 year supply agreements. BIS standard harmonization for thermal transfer durability creates compliance-driven specification upgrades. Chennai and Ahmedabad industrial corridors concentrate pressure-sensitive adhesive investments for dashboard and door panel applications.
Global Automotive Labels Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The vendor base clusters around three strategic archetypes: materials science conglomerates with adhesive polymerization capabilities, precision printing specialists with RFID antenna design competencies, and regional converters with automated dispensing equipment integration. Dominant competitive moves include backward integration into substrate manufacturing and strategic partnerships for battery passport data embedding.
Among materials science conglomerates, 3M Company and Avery Dennison Corporation occupy positions exemplifying high-temperature substrate leadership. SATO Holdings represents the automation-integrated specialist archetype within Asia-Pacific assembly plant networks. These three anchors illustrate how competitive positioning separates adhesive formulation control from digital encoding capabilities.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Brady Corporation |
| Resource Label Group |
| CCL Industries |
| UPM Raflatac |
| Schreiner Group |
| SATO Holdings |
| Polyonics |
| Others |
Supply Flow & Price Mechanics
Stuttgart's vacuum-metallized polyester cluster channels REACH-compliant cobalt-free colorants into premium exterior badge supply chains, compressing margin pools for converters lacking in-house polymerization capabilities. Battery passport mandates across German OEM networks are reshaping procurement authority toward full-service material science providers.
Pricing Analysis
Cost-plus contracts with propylene monomer indexation dominate biaxially-oriented polypropylene film procurement, tethering converter margins to petrochemical spot volatility. Price differentiation separates REACH-certified recyclable polyester substrates from legacy vinyl formulations facing ECHA phthalate obsolescence. Pricing pressure stems from stranded inventory write-downs across European supply chains as regulatory deadlines accelerate. Aftermarket providers exhibit highest price sensitivity, while OEM qualification frameworks prioritize certification grade over unit cost.
Supply Chain Analysis
Contract manufacturing concentrates among Avery Dennison Corporation, 3M Company, and SATO Holdings facilities across Germany, China, and Japan. Raw material dependencies center on acrylic polymer supply clusters in the US Gulf Coast and Rotterdam-Antwerp corridor, plus ceramic filler-reinforced silicone adhesive laminates. Single-source vulnerability to weather-related production interruptions creates geographic risk concentration. Distribution runs through tiered supplier panels consolidated from 12-15 regional converters to 3-4 strategic partners with RFID antenna design competencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital printing workflows are displacing mechanical embossing methods, forcing incumbents to defend against technology substitution before equipment write-downs accelerate. Battery passport data embedding capabilities now separate viable suppliers from stranded asset risk.
For Market Incumbents: Entrench adhesive polymerization control through backward integration into silicone laminate production, securing thermal cycling certification above 120°C for EV battery compartments. Deepen RFID-inlay thermal lamination capabilities to capture battery passport specification lock-in as OEM panels consolidate. For New Entrants and Emerging Players: India PLI scheme automotive corridors in Gujarat and Tamil Nadu represent the most penetrable entry point, with 15-20 year supply agreements anchoring initial volume. Target digital printing flexibility for EV battery prototype phases, where minimum order quantities have collapsed from 50,000 to 500 units without dedicated tooling investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with converged materials science and digital encoding competencies. Long-term viability rests on qualification frameworks that privilege in-house adhesive formulation over pure-play printing assets. Watch METI JIS-standard QR code harmonization across Toyota and Honda supply chains as inflection signal for Asia-Pacific automation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Inlay Thermal Lamination | Enables battery passport compliance without secondary attachment processes for EV manufacturers. |
| Backward Integration into Adhesive Polymerization | Secures silicone laminate supply continuity against Rotterdam-Antwerp corridor weather disruptions. |
| Digital Printing Workflow Deployment | Collapses prototype phase tooling barriers while maintaining ECHA substrate integrity certification. |
| REACH-Compliant Substrate Reformulation | Preserves German OEM supplier qualification as vinyl formulations face Annex XVII obsolescence. |
| India PLI Localization Partnership | Locks 15-20 year supply agreements in Gujarat and Tamil Nadu automotive industrial corridors. |
Methodological Framework
The analysis maps pressure-sensitive, thermal transfer, shrink sleeve, and in-mold label sub-sectors, each validated through procurement directors at Volkswagen Group and Mercedes-Benz, technical R&D leads at Continental and Bosch, and aftermarket distribution specialists. Primary interviews with OEM platform engineers and Tier 1 supplier quality managers combined with secondary validation from EPA emissions permanence standards, ECHA REACH Annex XVII restrictions, and METI JIS harmonization directives. Bottom-up volume triangulation across vehicle production databases and top-down value reconciliation through customs and trade flow analysis anchored segment sizing.
Assumption-sets held battery passport regulatory adoption timelines and EV thermal management system specifications fixed while varying propylene monomer cost trajectories and acrylic polymer supply availability. Segmentation dimensions modeled include substrate chemistry, adhesive formulation, application environment, and OEM tier qualification status across the projection horizon. CAGRs derived from production volume elasticity to vehicle electrification cycles and content-per-vehicle expansion for traceability mandates.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, petrochemical feedstock pricing, or battery electric vehicle penetration rates would shift the trajectory. Cross-checking against IHS Markit vehicle registration data and OEM supplier disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Syringe Labels Market
Labels
Warning Labels and Stickers Market
Labels
GCC Labels and Release Liners Market
Labels
Self-Adhesive Labels Market
Labels
Domed Labels Market
Labels
Cut and Stack Labels Market
Labels
Repositionable Labels Market
Labels
Printable Tags Market
Labels
Global QR Code Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Canning Labels Market
Labels
United States Print Label Market
Labels
Hang Tags Market
Labels
Wet Glue Labeling Machines Market
Labels
Global Cryogenic Label Market
Labels
Global Pressure Labels Market