
 Strapping Supplies Market | 2026-2036
Strapping Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Strapping Supplies Market Analytics
The capital-intensity gap between automated and manual strapping system suppliers is collapsing as mid-tier producers acquire servo-controlled tensioning capabilities. Signode leverages its captive steel mill relationships to sustain vertical integration across high-tensile banding. Mosca competes through proprietary ultrasonic sealing technology that eliminates metal seals in food-grade logistics.
Strapping supplies encompass flexible binding materials—polypropylene, polyester, steel, and nylon—manufactured via extrusion, rolling, or drawing processes to achieve calibrated break strengths from 100 lb to 2,000 lb, serving unitization and pallet stabilization across freight networks. Polyester strapping leads value contribution due to its elongation recovery and corrosion resistance in export container environments. Steel strapping retains margin concentration in heavy-gauge construction and metal coil applications where creep resistance governs specification.
EPA hazardous material manifesting rules and OSHA load-securement standards shape product certification requirements in North American logistics, while REACH compliance in Europe restricts phthalate plasticizers in polypropylene formulations. Stakeholders must monitor evolving extended-producer-responsibility frameworks that could mandate recycled-content thresholds in strapping polymers, fundamentally altering raw-material sourcing economics and supplier qualification protocols.
Market Dynamics
Automated tensioning systems are compressing the performance gap between commodity and specification-grade strapping, forcing mid-tier suppliers to invest in servo-controlled precision or cede automotive and electronics bundling contracts to integrated producers.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled-content thresholds for polymer strapping are redirecting procurement toward post-industrial PET feedstocks in German automotive logistics.
- E-commerce fulfillment automation:Robotic palletizing lines in US distribution centers specify elongation-recovery polyester that maintains tension through temperature cycling in cross-country transit.
- Steel coil export bundling:Port authorities in Japan and South Korea enforce creep-resistant specification grades for ocean-container unitization, sustaining premium-grade steel strapping demand.
Market Restraints
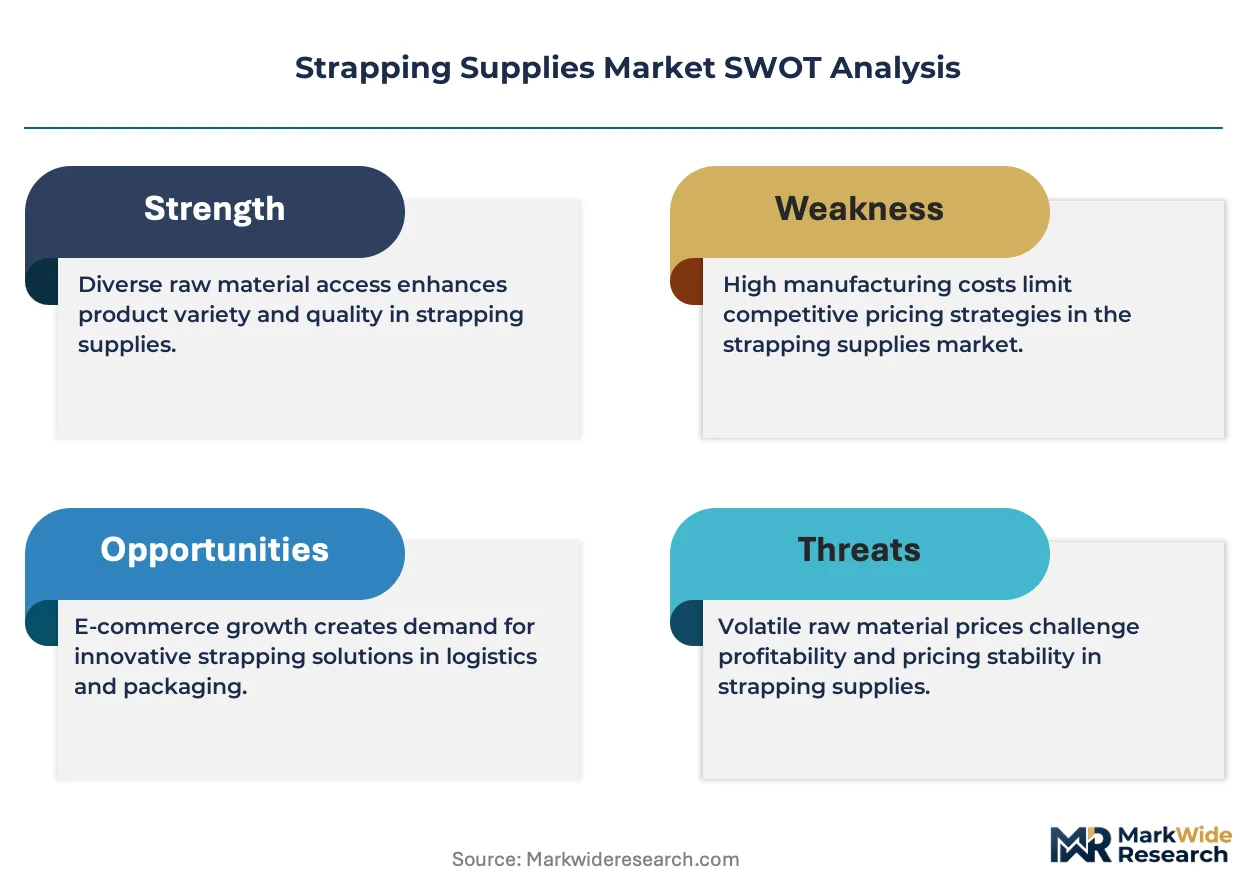
- Petrochemical feedstock volatility:PTA and MEG price swings compress polyester strapping margins for non-integrated extruders lacking long-term resin contracts.
- Galvanized steel supply concentration:High-tensile banding mills cluster in specific industrial corridors, exposing construction and metal-forming buyers to regional disruption risk.
- Ultrasonic sealing patent thickets:Proprietary friction-weld and ultrasonic technologies in food-grade logistics create licensing barriers for seal-equipment manufacturers.
Strategic Opportunities
- Indian cold-chain infrastructure:Temperature-stable polyester strapping penetrates pharmaceutical and perishable distribution networks as refrigerated warehousing expands.
- Brazilian agribusiness export corridors:Weather-resistant polymer grades capture pallet stabilization demand in soybean and coffee containerization.
- Extended-producer-responsibility frameworks:France and Italy advance packaging recovery mandates that reward closed-loop strapping collection and re-extrusion capabilities.
Industry Challenges
- Servo-controlled tensioning technician scarcity:Automated strapping line maintenance requires electromechanical specialists that vocational programs have not scaled to match equipment deployment rates.
- REACH compliance documentation:Phthalate-free polypropylene certification timelines delay EU market entry for reformulated products by 12-18 months.
- Legacy steel-to-polyester conversion complexity:Heavy-gauge applications in metal coil handling resist material substitution due to established load-securement protocols and insurer requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Strapping Supplies Market |
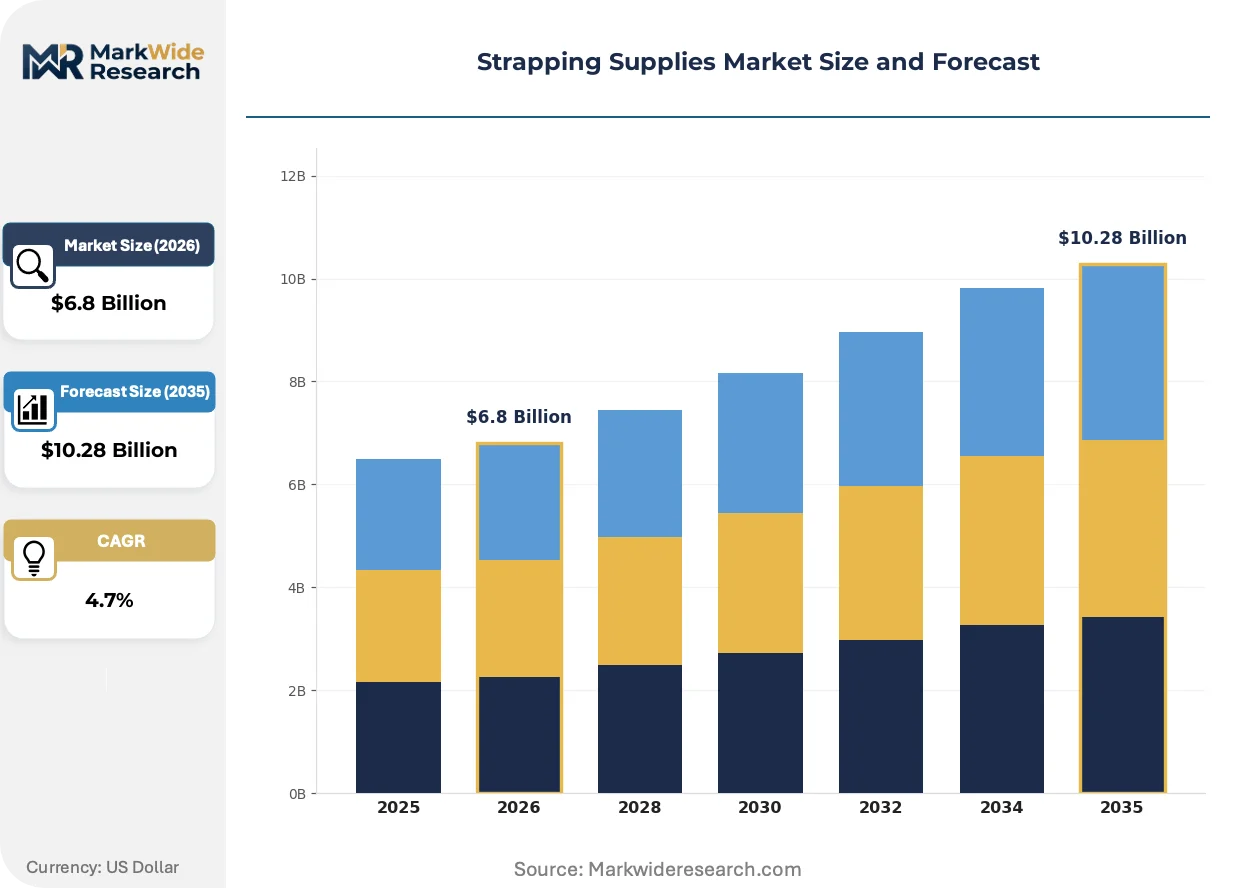
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyester, Steel, Nylon Application: Packaging, Logistics, Construction, Manufacturing End User: Retail, E-commerce, Automotive, Aerospace Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Signode, Mosca, FROMM, StraPack, Polychem, Teufelberger, Samuel, Son & Co., Cyklop, Titan Umreifungstechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Strapping Supplies Market Evolving Landscape
Digital tension monitoring and predictive seal-failure analytics are embedding intelligence into strapping systems, converting commodity binding into data-generating infrastructure for supply chain visibility platforms.
Ultrasonic sealing technology is decomposing the metal-seal dependency that has dominated food-grade and pharmaceutical logistics for decades. Major cold-chain distributors in Germany and the Netherlands are retrofitting existing arch-type machines with high-frequency weld heads. This shift is compressing seal-inventory carrying costs while eliminating ferrous contamination risk in automated sortation environments.
REACH restrictions on phthalate plasticizers are forcing polypropylene compounders to validate alternative flexibilizers for low-temperature performance. ECHA substance evaluation timelines have delayed three major reformulation submissions since 2023. European automotive tier-one suppliers are responding by dual-sourcing certified and non-certified grades to maintain production continuity during qualification windows.
Consolidated buying by third-party logistics operators is compressing supplier rosters and unbundling after-sales service from equipment procurement. Large US e-commerce fulfillment contractors now negotiate strapping consumables, maintenance, and predictive analytics as separate line items rather than bundled service agreements. This pattern is most visible in the Midwest distribution corridor, where regional 3PLs have adopted reverse-auction platforms for polyester coil sourcing.
Strapping Supplies Market Segmentation
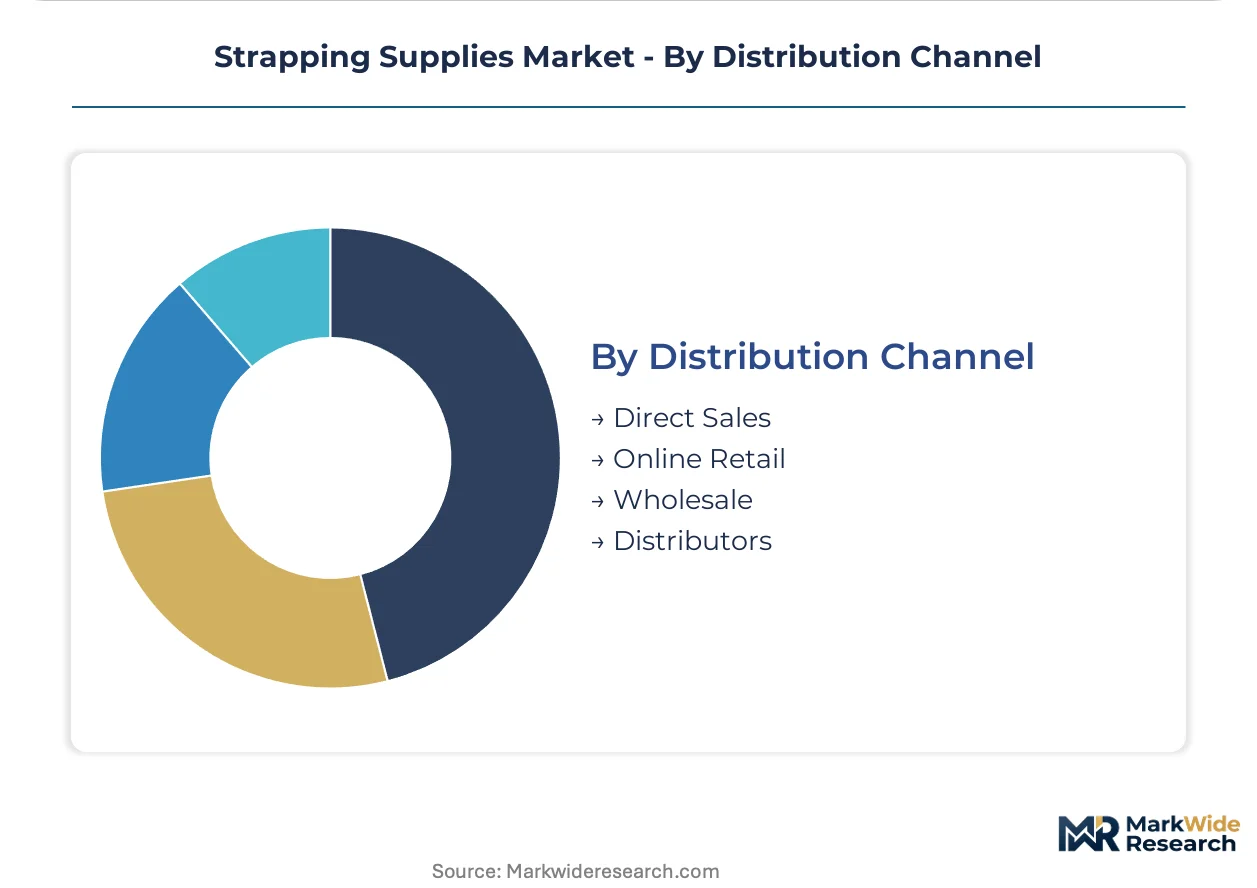
Strapping supplies flow through distinct procurement channels that mirror buyer sophistication. Specification-grade polyester and steel strapping move through direct mill relationships, while commodity polypropylene circulates via wholesale distributors serving fragmented end-users.
Product Type:
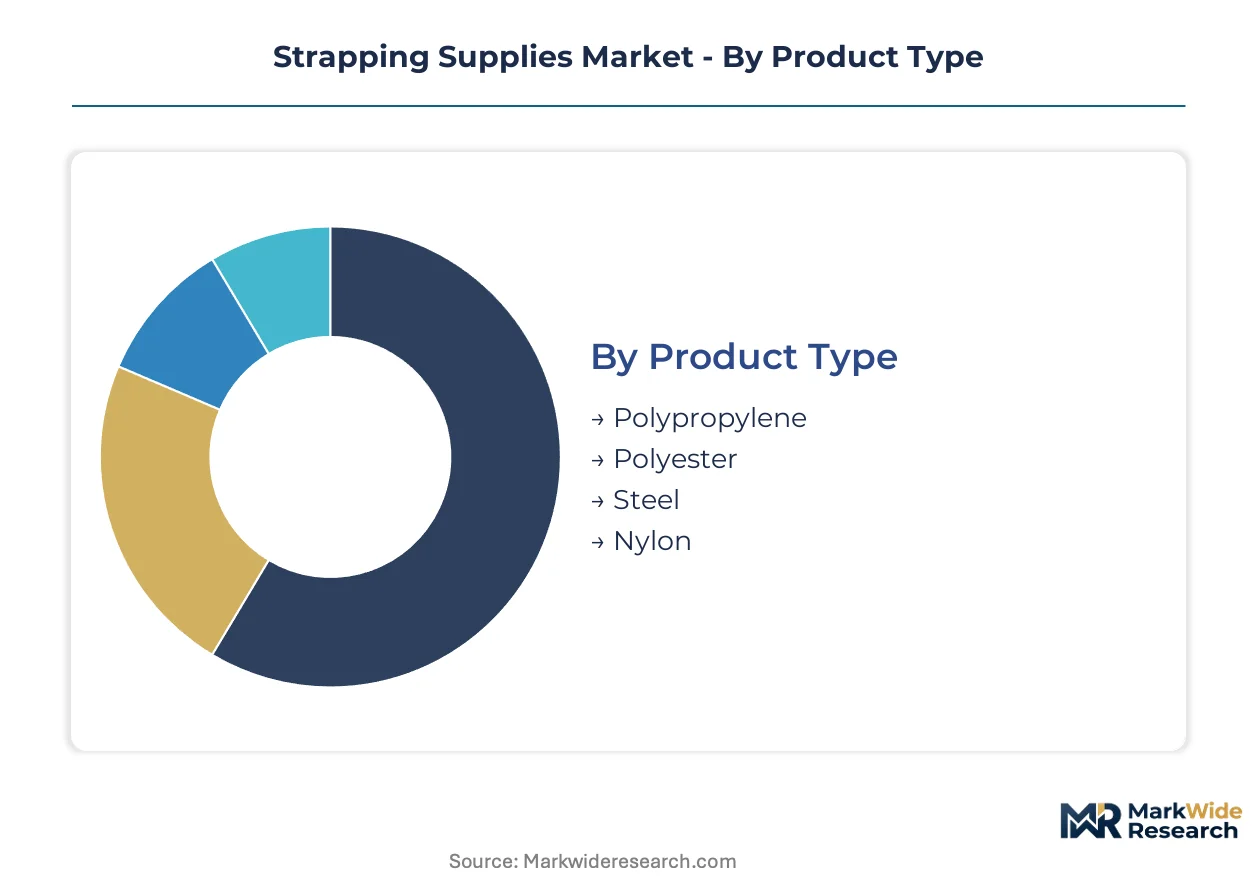
Channel mix varies sharply by material chemistry. Polyester and steel strapping concentrate in direct sales channels anchored by automotive OEMs and metal coil exporters, while polypropylene dominates wholesale and online retail serving smaller logistics operators.
- Polyester:Extruded polyethylene terephthalate delivers calibrated elongation recovery between 8% and 15% with break strengths spanning 600 lb to 2,000 lb. E-commerce fulfillment centers in the US Midwest specify this grade for automated palletizing lines that cycle through temperature extremes in cross-country transit. REACH-compliant formulations using post-industrial PET feedstocks are capturing procurement share in German automotive logistics.
- Steel:Cold-rolled and galvanized high-tensile banding achieves creep resistance critical for metal coil unitization in ocean containers. Port authorities in Japan enforce specification-grade certification for export bundling, sustaining premium-channel procurement through mill-direct relationships.
- Polypropylene:Lightweight extruded ribbon serving manual applications in retail packaging and light logistics.
- Nylon:High-tenacity synthetic for specialized moisture-resistant applications in cold-chain and marine environments.
By volume, polypropylene leads. By growth pace, polyester is ahead.
Application:
Margin structure diverges across use cases. Packaging applications tolerate commodity grades with thin distributor markups, while construction and manufacturing specifications command certified products with embedded technical service.
- Logistics:Automated distribution networks demand elongation-stable polyester that maintains tension through robotic handling and climate cycling. Third-party logistics operators in the US negotiate consumables, maintenance, and predictive analytics as unbundled line items rather than service packages.
- Manufacturing:Automotive and electronics bundling requires servo-controlled tension compatibility with documented break-strength certification. Mid-tier suppliers lacking precision extrusion capabilities are ceding these contracts to integrated producers with captive resin supply.
- Packaging:High-volume consumer goods unitization using commodity polypropylene through wholesale channels.
- Construction:Heavy-gauge steel banding for structural steel and concrete formwork with insurer-mandated load-securement protocols.
Packaging generates the highest shipment volumes. Logistics commands the steepest expansion trajectory as automation penetrates distribution networks.
End User:
Procurement sophistication stratifies sharply across buyer categories. Automotive and aerospace operations mandate specification-grade certification with full material traceability, while retail and e-commerce prioritize unit cost and availability.
- E-commerce:Fulfillment automation is accelerating specification-grade polyester consumption. Robotic palletizing lines require calibrated elongation recovery that prevents load shifting through temperature gradients. Large contractors now source coil stock through reverse-auction platforms separating equipment, consumables, and maintenance.
- Automotive:OEM bundling standards in Germany drive procurement of REACH-certified grades with documented phthalate-free formulations. Tier-one suppliers dual-source certified and transitional grades to maintain production continuity during ECHA qualification windows.
- Retail:Fragmented store-level purchasing through wholesale distributors with minimal technical specification.
- Aerospace:Niche demand for traceable high-performance strapping with full material certification.
Retail moves the most tonnage. E-commerce is climbing the fastest as fulfillment automation scales.
Distribution Channel:
Channel power is consolidating around large logistics operators with unbundled procurement capabilities. Direct sales relationships increasingly include predictive analytics and maintenance services as separate contractual elements.
- Direct Sales:Integrated producers serve automotive OEMs and metal coil exporters through mill-direct relationships with embedded technical service. Signode leverages captive steel mill relationships to sustain specification-grade supply chains.
- Distributors:Regional wholesale networks dominate polypropylene flow to fragmented retail and light manufacturing. Consolidated buying by third-party logistics operators is compressing supplier rosters and squeezing distributor margins.
- Online Retail:E-commerce coil sourcing platforms emerging in the US Midwest for commodity polyester grades.
- Wholesale:Traditional bulk purchasing for construction and manual packaging applications.
Distributors handle the greatest volume. Direct sales is gaining share fastest as specification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes specification-grade polyester and steel strapping at rates far exceeding other markets, while the United States drives volume through e-commerce fulfillment automation and India emerges as the fastest-expanding demand center for temperature-stable polymer grades.
Germany
Automotive OEM bundling standards and REACH-compliant phthalate-free formulations concentrate procurement power among tier-one suppliers. The EU Packaging and Packaging Waste Regulation mandates recycled-content thresholds that redirect sourcing toward post-industrial PET feedstocks. Stuttgart and Wolfsburg automotive clusters specify servo-controlled tension compatibility with full material traceability documentation.
United States
Robotic palletizing lines in Midwest distribution centers specify elongation-recovery polyester that maintains tension through cross-country temperature cycling. EPA hazardous material manifesting rules and OSHA load-securement standards shape product certification requirements for North American logistics. Chicago and Detroit distribution corridors adopt reverse-auction platforms for unbundled procurement of coil stock, equipment, and maintenance services.
Japan
Port authorities enforce creep-resistant specification grades for steel coil export bundling in ocean containers, sustaining premium-channel demand. METI industrial standards govern break-strength certification for metal-forming applications. Osaka and Nagoya metal-processing clusters maintain mill-direct relationships for high-tensile banding with documented creep resistance.
India
Refrigerated warehousing expansion in pharmaceutical and perishable distribution networks drives penetration of temperature-stable polyester strapping. BIS standards for packaging materials create compliance pathways for imported polymer grades. Maharashtra and Gujarat cold-chain infrastructure projects specify weather-resistant polymer grades for pallet stabilization in agribusiness export corridors.
Brazil
Soybean and coffee containerization demands weather-resistant polymer grades for pallet stabilization in agribusiness export corridors. ANVISA pharmaceutical packaging regulations influence material selection for cold-chain distribution networks. São Paulo and Paraná agricultural processing clusters concentrate procurement of specification-grade strapping for ocean-freight unitization.
Strapping Supplies Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper layer controlling captive resin supply and steel mill relationships while mid-tier players compete on servo-controlled precision capabilities. Market structure favors backward integration into raw material sourcing and forward integration into predictive maintenance services. Three archetypes dominate: steel-centric metal processors with mill relationships, polymer extruders with post-industrial PET recycling capabilities, and equipment-integrated consumables suppliers. Consolidation is accelerating through acquisition of ultrasonic sealing technology portfolios and expansion of regional re-extrusion facilities.
Among European-anchored industrial packaging groups, Signode and Mosca occupy positions at opposite ends of the technology spectrum. Signode exemplifies the steel-centric archetype through its sustained access to captive mill supply chains for high-tensile banding. Mosca represents the equipment-integrated tier, anchoring its competitive position in proprietary sealing technologies that eliminate metal components. FROMM and StraPack sit within the mid-tier polymer specialist category, competing on regional service density and reformulation agility as REACH compliance timelines compress.
| Leading Market Players |
|---|
| Signode |
| Mosca |
| FROMM |
| StraPack |
| Polychem |
| Teufelberger |
| Samuel, Son & Co. |
| Cyklop |
| Titan Umreifungstechnik |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German automotive OEMs and polyester extruders lock in both post-industrial PET feedstock access and price visibility across REACH qualification windows. These contracts insulate specification-grade procurement from PTA and MEG volatility while compressing spot-market participation for mid-tier compounders.
Pricing Analysis
After-sales service revenue from predictive maintenance contracts and ultrasonic seal-head replacement drives lifetime value for equipment-integrated suppliers. Three-tier pricing structure across specification-grade, certified-standard, and commodity-economy levels separates automotive bundling contracts from wholesale polypropylene flow. Cost compression in commodity polypropylene intensifies because reverse-auction platforms consolidate buyer power among Midwest 3PLs. Retail and light logistics segments exhibit highest price sensitivity, while automotive OEMs prioritize certification compliance over unit cost.
Supply Chain Analysis
Inventory carrying costs for metal seal stockpiles are collapsing as ultrasonic retrofit programs accelerate across German and Dutch cold-chain distributors. Raw material supply draws from German steel mills for high-tensile banding, US Gulf Coast petrochemical corridors for polyester resin, and Chinese extrusion capacity for commodity polypropylene. Single-source vulnerability concentrates in galvanized steel banding mills clustered in specific industrial corridors. Distribution runs through direct mill relationships for specification grades and regional wholesale networks for commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strapping supplies are entering a cyclical recovery phase as e-commerce fulfillment automation capital expenditure rebounds from prior-year compression. German automotive production schedules and US distribution center buildouts provide the demand-side anchor.
For Market Incumbents: Secure captive resin supply through backward integration into post-industrial PET recycling or long-term offtake with German chemical producers. Invest in servo-controlled tension certification to defend against emerging equipment-integrated entrants. Channel control through embedded predictive maintenance contracts protects margin position as 3PL procurement unbundling accelerates.
For New Entrants and Emerging Players: ECHA fast-track certification for phthalate-free polypropylene formulations opens procurement access to German automotive tier-one suppliers during dual-sourcing windows. Target Indian cold-chain infrastructure buildout for temperature-stable polyester penetration. Go-to-market through regional re-extrusion partnerships bypasses capital-intensive greenfield extrusion requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward polymer extruders with post-industrial PET recycling capabilities and established REACH documentation workflows. The five-to-ten year viability window favors suppliers with closed-loop collection infrastructure ahead of extended-producer-responsibility mandates. Watch for ultrasonic sealing patent expirations as inflection signal for equipment-integrated entry opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Recycling | Captures post-industrial feedstock streams ahead of EU recycled-content mandates affecting German automotive procurement. |
| Ultrasonic Sealing Patent Acquisition | Eliminates metal-seal inventory costs and ferrous contamination risk in automated pharmaceutical distribution. |
| Servo-Controlled Tension Certification | Qualifies suppliers for robotic palletizing lines at US Midwest e-commerce fulfillment centers. |
| Regional Re-Extrusion Facility Expansion | Reduces logistics costs and lead times for Brazilian agribusiness export corridor pallet stabilization. |
| Predictive Maintenance Platform Development | Converts commodity strapping into data-generating infrastructure for supply chain visibility platforms. |
Research Methodology
Desk research of trade customs databases, SEC filings from packaging equipment manufacturers, and EU regulatory submission portals preceded structured interviews with plant engineers at automotive OEMs, procurement leads at third-party logistics operators, technical R&D directors at polymer compounders, and aftermarket service heads at strapping equipment distributors. Bottom-up volume estimates from extruder capacity utilization and top-down validation from end-use consumption patterns were triangulated against channel shipment data.
Variance decomposition across material chemistry, application severity, and distribution channel structure shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, end-use industry, procurement channel sophistication, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating e-commerce fulfillment automation penetration rates and REACH compliance timeline impacts.
Decision-makers should treat outputs as directional under assumptions of sustained petrochemical feedstock availability and stable automotive production schedules; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Application Tapes Market
Tapes
Tape Dispenser Market
Tapes
Pre-Printed Tape Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Differential Tapes Market
Tapes
Masking Tape Market
Tapes
Self-Adhesive Tear Tape Market
Tapes
Filament Tapes Market
Tapes
Fine Line Striping Tape Market
Tapes
Carton Sealing Tape Market
Tapes
Nylon Cable Ties Market
Tapes
Acoustic Tape Market
Tapes
Foam Tape Market
Tapes
Labels, Tapes and Films Market
Tapes
Europe Packaging Tapes Market
Tapes
Lacing Tape Market