
 Pallet Jacks Market | 2026-2036
Pallet Jacks Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Jacks Market Outlook
Chinese material handling equipment manufacturing is realigning toward higher-capacity electric pallet jack output for export markets. Toyota Industries leverages its vertical integration into battery and drive motor production to control cost structures across Asia-Pacific supply chains. Jungheinrich sustains engineering intensity in walkie and rider pallet truck platforms for European intralogistics customers. Crown Equipment Corporation anchors North American demand through dense service networks and quick-ship parts availability.
A pallet jack is a wheeled trolley with hydraulic or electro-hydraulic lifting mechanism designed to raise palletized loads typically between three and eight inches for horizontal transport across warehouse floors. Standard manual units operate via a hand pump and release valve, while electric variants integrate DC drive motors, sealed lead-acid or lithium-ion battery packs, and electromagnetic braking systems for loads exceeding five thousand pounds in continuous duty cycles. Electric pallet jacks now dominate new fleet procurement in high-volume distribution centers where travel distances exceed four hundred feet per move, while manual units retain share in small retail backrooms and low-throughput manufacturing facilities where capital constraints limit powered equipment adoption. Heavy-duty capacity models capture margin pools in steel, automotive, and beverage handling applications where concentrated loads stress frame and hydraulic components beyond standard ratings.
OSHA workplace safety regulations and ANSI B56.1 industrial truck standards govern operator training, load stability testing, and braking performance requirements across United States facilities. The EPA and state-level air quality boards in California and New York are accelerating electric pallet jack substitution through emissions restrictions on propane and diesel indoor equipment. Stakeholders must monitor lithium-ion battery supply chain certification, charger infrastructure compatibility, and evolving state energy codes that will determine total cost of ownership parity between electric and manual platforms.
Market Dynamics
Fleet electrification pressure from OSHA safety mandates and state-level emissions restrictions is restructuring procurement patterns across warehouse operations, compressing replacement cycles for manual and internal-combustion units.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in the United States are expanding electric pallet jack fleets to handle SKU proliferation and same-day delivery windows.
- OSHA B56.1 compliance deadlines:Operator training mandates and load stability testing requirements are accelerating retirement of aging manual equipment in distribution centers.
- Lithium-ion chemistry maturation:Battery energy density improvements are extending duty cycles beyond eight hours, eliminating mid-shift battery swaps in high-throughput facilities.
Market Restraints
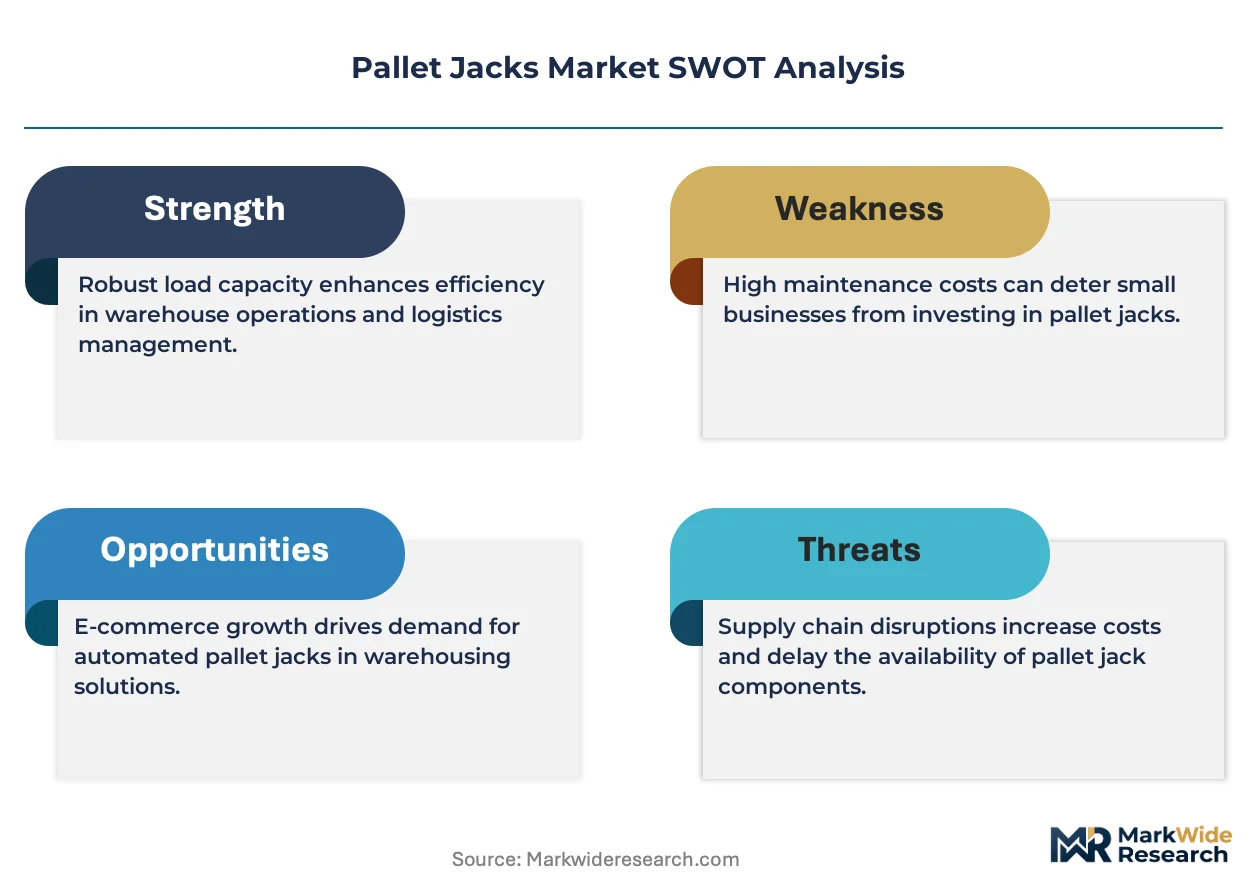
- Cobalt and lithium price volatility:Raw material cost swings in battery supply chains are compressing margins for electric model manufacturers.
- Charger infrastructure capital requirements:Facility electrical upgrades and fast-charger installations demand upfront investment that delays fleet conversion in budget-constrained operations.
- Manual unit residual durability:Extended service life of hand-pump pallet jacks in low-throughput retail backrooms slows replacement demand.
Strategic Opportunities
- India warehouse modernization:PLI scheme incentives for logistics infrastructure are creating first-time electric pallet jack demand in emerging distribution hubs.
- Food and beverage cold chain expansion:IP-rated electric units with corrosion-resistant components are penetrating refrigerated storage applications previously served by manual equipment.
- Telematics and fleet management convergence:Integration of IoT sensors with warehouse management systems enables predictive maintenance contracts and usage-based pricing models.
Industry Challenges
- Certified technician scarcity:EPA Section 608 and state electrical licensing requirements limit qualified service personnel availability for lithium-ion battery maintenance.
- Legacy WMS integration friction:Retrofitting electric fleet telematics into existing warehouse software architectures demands custom API development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Jacks Market |
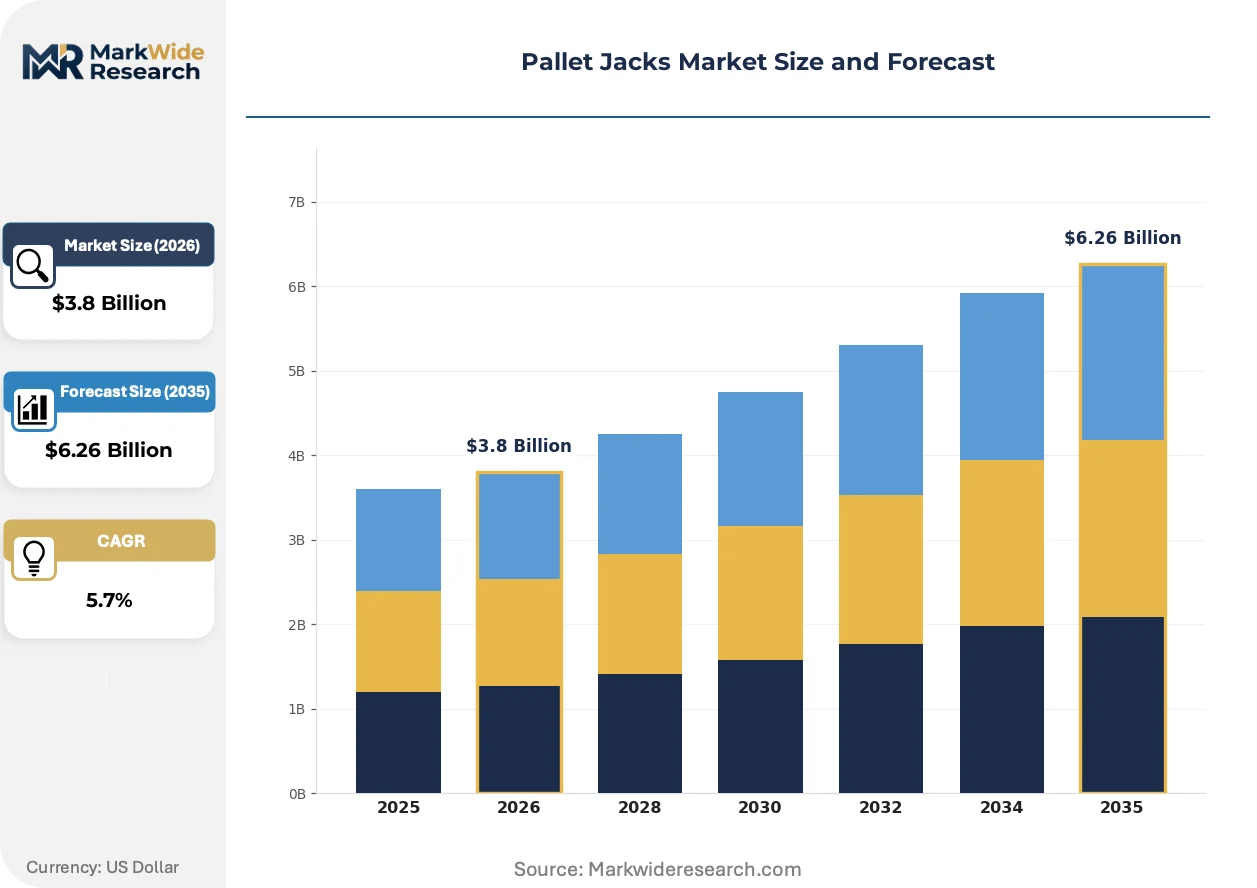
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pallet Jacks, Electric Pallet Jacks, Ride-On Pallet Jacks, High Lift Pallet Jacks End User: Warehouses, Manufacturing Facilities, Retail Stores, Distribution Centers Capacity: Standard Capacity, Heavy-Duty Capacity, Lightweight Capacity, Adjustable Capacity Power Source: Electric, Manual, Battery, Hybrid |
| Companies Covered | Toyota Industries, Jungheinrich, Crown Equipment Corporation, Hyster-Yale Materials Handling, STILL, EP Equipment, Hangcha Forklift, Godrej Material Handling, Ravas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Jacks Market Strategic Shifts
Electrification architecture, regulatory emissions enforcement, and procurement centralization are converging to reshape equipment specification standards and vendor selection criteria across material handling operations.
Lithium-ion battery systems with opportunity-charging capability are decentralizing fleet power management away from centralized battery rooms. High-volume distribution centers in Germany are adopting fast-charge protocols that enable continuous operation across extended shifts. This shift is decentralizing maintenance workflows and reducing dedicated floor space for battery swap infrastructure.
California Air Resources Board indoor emissions restrictions are forcing propane forklift phase-outs in favor of electric pallet jacks and walkie stackers. Facilities in Los Angeles and Central Valley logistics corridors face compliance deadlines that compress procurement timelines. Cold storage operators are responding with sealed lithium-ion configurations rated for sub-zero environments.
Consolidated procurement through national third-party logistics contracts is displacing decentralized site-level equipment purchasing. Amazon, DHL, and similar operators are standardizing on single-vendor fleet agreements with telematics integration requirements. This concentration is most visible in the United States, where regional distribution hub rollouts favor vendors with coast-to-coast service networks.
Pallet Jacks Market Segmentation
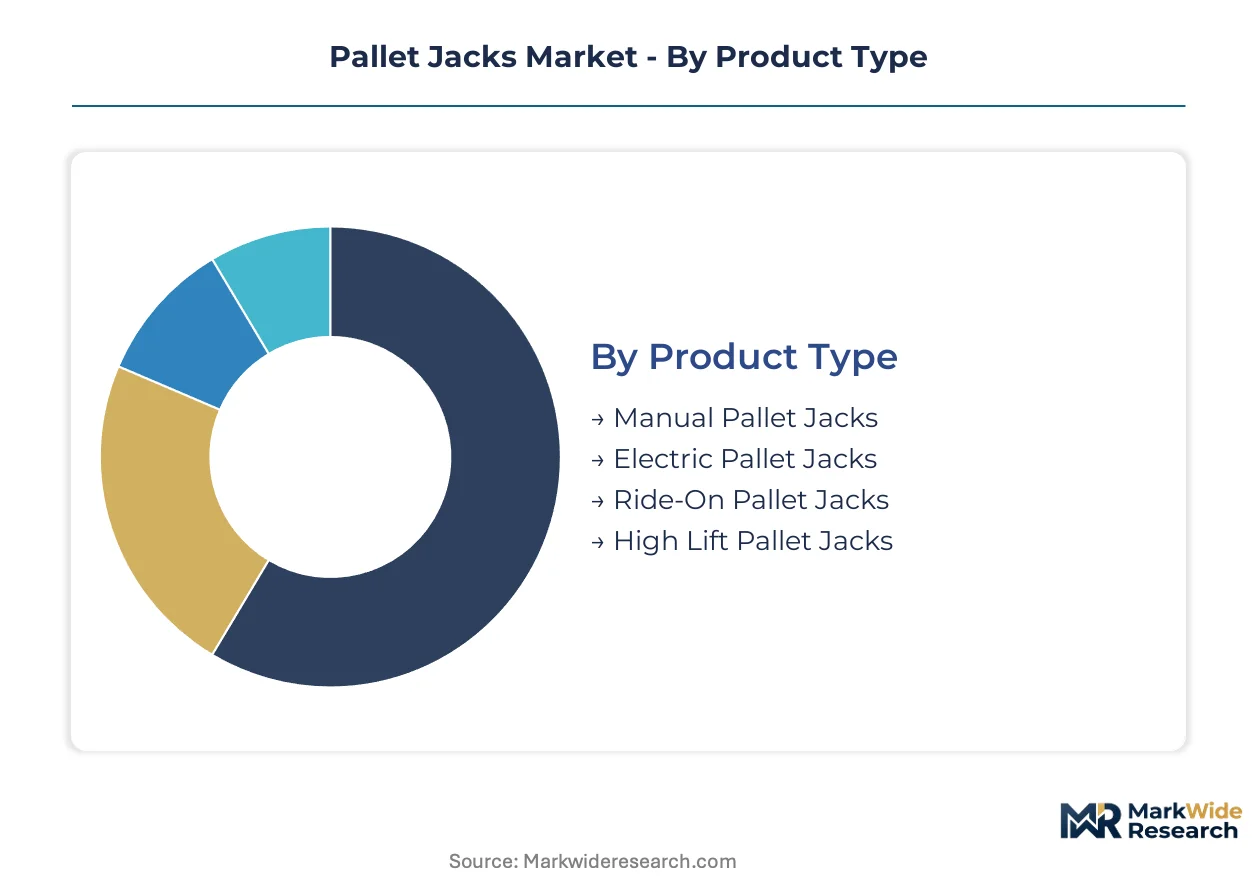
Pallet jack procurement decisions split sharply across operational intensity, load specifications, and facility electrification readiness. Certification requirements from OSHA, ANSI, and state energy boards create divergent compliance burdens that reshape segment economics and vendor selection criteria.
Product Type:
OSHA B56.1 operator training mandates and ANSI load stability testing requirements apply differentially across powered versus manual platforms, concentrating compliance costs in electric and ride-on categories.
- Manual Pallet Jacks:Hand-pump hydraulic units with release valve control dominate small retail backrooms and capital-constrained operations. Demand concentrates in independent grocery chains and light manufacturing facilities across the United States where travel distances stay below four hundred feet per move and OSHA powered-equipment training requirements are avoided entirely.
- Electric Pallet Jacks:DC drive motor platforms with sealed lead-acid or lithium-ion battery packs and electromagnetic braking systems handle loads exceeding five thousand pounds in continuous duty cycles. Distribution centers in Germany and the United States are retiring manual fleets for these units as EPA emissions restrictions and state-level air quality boards accelerate indoor equipment substitution.
- Ride-On Pallet Jacks:Operator-platform configurations reduce fatigue across extended horizontal transport routes in high-volume facilities.
- High Lift Pallet Jacks:Scissor-lift mechanisms elevate loads to ergonomic working heights for order picking and staging operations.
Manual pallet jacks sit at the top of the volume ranking, with electric pallet jacks climbing the fastest.
End User:
Facility scale and throughput velocity determine capital allocation patterns, with national third-party logistics operators centralizing procurement through single-vendor fleet agreements.
- Warehouses:Multi-shift operations with SKU proliferation drive specification toward lithium-ion electric units with opportunity-charging capability. Amazon and DHL standardization programs in the United States favor vendors with coast-to-coast service networks and telematics integration.
- Distribution Centers:Same-day delivery windows and e-commerce fulfillment density compress equipment replacement cycles. California Air Resources Board compliance deadlines in Los Angeles and Central Valley logistics corridors force propane forklift phase-outs in favor of electric pallet jacks and walkie stackers.
- Manufacturing Facilities:Production-line feed and work-in-progress transport favor durability over speed in equipment selection.
- Retail Stores:Backroom stock replenishment with intermittent use patterns sustain manual unit demand despite electrification pressure elsewhere.
Distribution centers command the highest equipment spend per facility, with warehouses expanding fleet size most aggressively.
Capacity:
Load concentration stress on frame and hydraulic components creates tiered margin structures, with heavy-duty specifications capturing premium pricing in concentrated-weight applications.
- Heavy-Duty Capacity:Reinforced frame construction and upgraded hydraulic systems handle concentrated loads in steel processing, automotive assembly, and beverage handling. German automotive clusters specify these units for engine block and transmission transport where standard ratings fail.
- Standard Capacity:Three-to-five-thousand-pound ratings serve general warehouse palletized goods movement. United States third-party logistics operators specify these for mixed-SKU fulfillment where load weights vary unpredictably.
- Lightweight Capacity:Aluminum-frame construction reduces operator effort in retail and light commercial applications.
- Adjustable Capacity:Modular fork width and length configurations accommodate non-standard pallet dimensions.
Standard capacity dominates unit shipments, with heavy-duty capacity yielding the highest margin per unit.
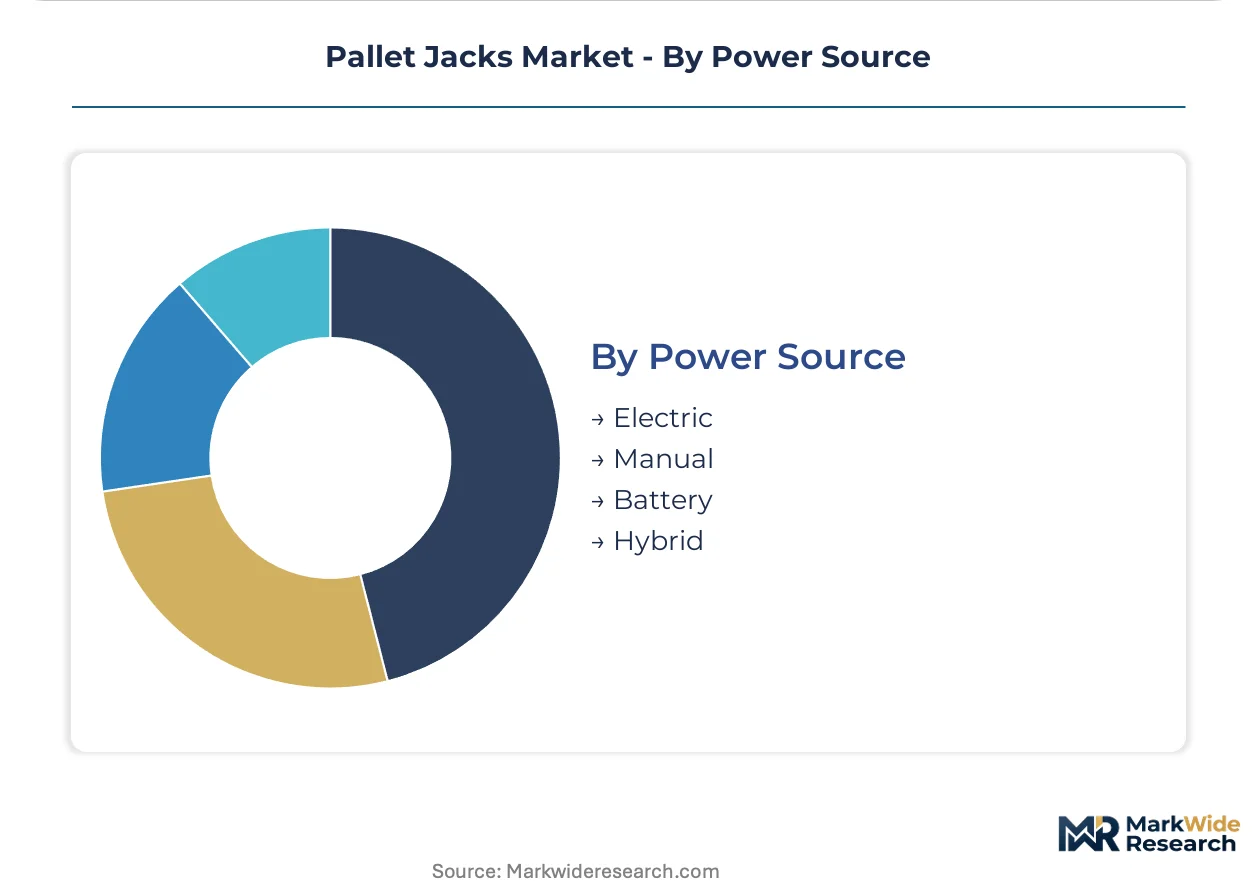
Power Source:
Battery chemistry maturation and charger infrastructure requirements segment total cost of ownership calculations across facility electrical upgrade budgets.
- Electric:Grid-connected or battery-powered DC motor systems with sealed lead-acid or lithium-ion configurations. Cold storage operators in California specify sealed lithium-ion variants rated for sub-zero environments as CARB restrictions eliminate propane alternatives.
- Battery:Cordless lithium-ion platforms with fast-charge protocols enable continuous operation across extended shifts in German high-throughput distribution centers.
- Manual:Zero electrical dependency sustains share in emerging markets and electrical infrastructure-constrained facilities.
- Hybrid:Dual-mode manual-electric operation provides backup capability during power interruptions.
Electric power sources anchor new fleet procurement, with battery configurations gaining share fastest as lithium-ion energy density extends duty cycles beyond eight hours.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials are redistributing pallet jack manufacturing capacity toward jurisdictions with streamlined certification pathways, while demand concentrates in markets enforcing stringent indoor emissions standards.
United States
Third-party logistics operators are scaling electric fleet procurement to meet same-day delivery commitments. OSHA B56.1 operator training mandates accelerate manual equipment retirement in distribution centers. California Air Resources Board restrictions in Los Angeles and Central Valley logistics corridors force propane forklift phase-outs ahead of compliance deadlines.
Germany
Automotive and logistics clusters require high-throughput material handling equipment for engine block and transmission transport. REACH chemical safety regulations govern battery component sourcing and end-of-life disposal protocols. Stuttgart and Wolfsburg manufacturing corridors specify heavy-duty capacity units where concentrated loads stress standard hydraulic ratings.
China
Material handling equipment manufacturing is realigning toward higher-capacity electric output for export markets. MIIT industrial standards and GB certification requirements shape domestic product specifications. Yangtze River Delta production bases supply lithium-ion powered units to European and North American warehouse operators.
India
PLI scheme incentives for logistics infrastructure are creating first-time electric pallet jack demand in emerging distribution hubs. BIS certification requirements and state-level warehouse modernization programs accelerate fleet conversion. Mumbai-Pune and Delhi-NCR logistics corridors deploy powered units for e-commerce fulfillment expansion.
Japan
Automotive assembly lines and precision manufacturing facilities specify ride-on configurations for extended horizontal transport routes. METI energy efficiency standards and JIS industrial truck specifications govern equipment procurement. Nagoya and Osaka industrial zones integrate telematics-enabled fleets with warehouse management systems.
Pallet Jacks Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue lithium-ion specialization and cold-chain adaptation. The vendor base stratifies across integrated multinationals with captive battery supply, regional fabricators serving price-sensitive procurement, and telematics specialists enabling fleet management convergence. Three archetypes dominate: vertically integrated industrial conglomerates, mid-scale regional equipment builders, and IoT-enabled service platform operators. Competitive intensity centers on M&A consolidation for service network density and strategic partnerships for charger infrastructure deployment.
Among Asia-Pacific-based producers, Toyota Industries exemplifies the integrated archetype through in-house production of battery and drive motor components. Jungheinrich AG represents engineering-intensive European positioning in walkie and rider platforms. Crown Equipment Corporation anchors North American demand fulfillment through dense service networks and quick-ship parts availability.
| Leading Market Players |
|---|
| Toyota Industries |
| Jungheinrich |
| Crown Equipment Corporation |
| Hyster-Yale Materials Handling |
| STILL |
| EP Equipment |
| Hangcha Forklift |
| Godrej Material Handling |
| Ravas |
| Others |
Value Chain & Pricing Dynamics
Certified lithium-ion battery technician pools in the Yangtze River Delta and Stuttgart manufacturing corridors create labor-cost differentials that widen pricing-tier spreads between premium European electric units and cost-optimized Chinese exports. This workforce concentration feeds into three-tier pricing structures where OEM-direct procurement, national distributor networks, and regional fabricators operate at distinct margin levels.
Pricing Analysis
Distributor margin layers in the United States compress as national third-party logistics operators consolidate procurement through direct OEM agreements with telematics bundling. Three-tier pricing structure across premium, standard, and economy levels separates ANSI-certified heavy-duty units for automotive clusters from basic manual models serving retail backrooms. Price differentiation hinges on lithium-ion battery energy density ratings and OSHA B56.1 compliance certification tiers. Cost compression in economy manual tiers is intensifying because extended service life slows replacement cycles. Small independent grocery chains exhibit highest price sensitivity, while German automotive logistics clusters show lowest sensitivity due to downtime cost exposure.
Supply Chain Analysis
Workforce availability constraints in battery cell manufacturing concentrate supply chain vulnerability in China, South Korea, and Japan where cathode active material processing requires specialized chemical engineering talent. Pallet jack production draws from lithium carbonate, steel frame forgings, and DC drive motor assemblies as core inputs. Single-source vulnerability in cobalt hydroxide refining creates procurement risk for European assemblers dependent on African feedstock. Distribution runs through OEM-direct channels for national fleet accounts and regional equipment dealers serving site-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where OSHA B56.1 operator training mandates and California Air Resources Board emissions deadlines mechanically accelerate equipment replacement demand regardless of macroeconomic conditions.
For Market Incumbents: Cement service network density as the primary defensive moat against telematics-enabled fleet management specialists entering from adjacent warehouse automation sectors. Capture lithium-ion battery maintenance certification scarcity through captive technician training programs. Prioritize backward integration into battery cell supply to defend margin position against raw material volatility. For New Entrants and Emerging Players: Cold-chain-rated lithium-ion configurations with IP-sealed sub-zero operation represent the most penetrable technology-first wedge into refrigerated distribution centers previously locked into manual equipment. Target India PLI scheme warehouse modernization corridors where first-time electric pallet jack demand lacks established vendor relationships. Deploy usage-based pricing with predictive maintenance contracts as the go-to-market angle. For Investors and Strategic Acquirers: Third-party logistics operators with national fleet standardization programs are the most active acquirer in this space, consolidating vendor relationships into single-source agreements. Long-term viability centers on telematics integration capability and coast-to-coast service infrastructure rather than manufacturing scale alone. Watch lithium-ion battery supply chain certification bottlenecks as the signal indicating margin compression or expansion windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Supply | Captive lithium-ion production insulates Toyota Industries from cobalt price swings across Asia-Pacific supply chains. |
| Telematics-Enabled Fleet Management Platform | IoT sensor integration with warehouse management systems enables Jungheinrich to capture recurring service revenue from German automotive clusters. |
| Fast-Charge Infrastructure Partnership | Charger deployment alliances reduce facility electrical upgrade friction for Crown Equipment Corporation's North American distribution center clients. |
| Cold-Chain IP Rating Certification | Sub-zero lithium-ion configurations open refrigerated storage segments previously served by manual equipment in California CARB compliance corridors. |
| Technician Training Program Scale-Up | EPA Section 608 certified personnel pipelines address service scarcity constraining lithium-ion fleet penetration in budget-constrained operations. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with warehouse operations directors, OEM procurement teams, aftermarket service heads, and facility maintenance managers with secondary validation against OSHA enforcement data, EPA emissions filings, customs trade records, and ANSI standards documentation. Bottom-up unit shipment modeling and top-down market sizing triangulated across product type, power source, capacity tier, and end-use facility scale dimensions.
Historical reference periods anchored volume and value projections across the modeling period, with analytical frameworks segmenting by manual versus electric propulsion architecture, battery chemistry configuration, load capacity rating, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle compression analysis and fleet electrification penetration curves incorporated lithium-ion energy density improvement trajectories and state-level emissions restriction timelines as industry-specific forecast inputs.
The model holds under steady regulatory enforcement intensity and cobalt supply continuity; deviation in OSHA inspection priority shifts or lithium export restriction triggers would shift replacement demand timing and regional procurement patterns. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Empty Fruit Bunch Pallets Market
Pallets Packaging
India Pallets Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Pallet Banding Machine Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Middle East Pallets Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Pallet Pooling Market