
 High Vacuum Filling Machine Market | 2026-2036
High Vacuum Filling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
High Vacuum Filling Machine Market Foresight
Closed-loop servo control of vacuum chambers is tilting equipment architecture toward real-time pressure modulation and reduced product degradation. Heinrich Frey Maschinenbau GmbH anchors its position through deep specialization in pharmaceutical-grade stainless steel construction. VEMAG Maschinenbau GmbH competes by extending its vacuum pump integration capabilities across multiple filling modalities. Multivac Group dominates thermoforming-vacuum hybrid lines for food applications with strong channel control in European processing plants.
High vacuum filling machines are electromechanical systems that evacuate air from product chambers before precise dose delivery, typically operating at residual pressures below 100 mbar to prevent oxidation and microbial ingress in sensitive formulations. Fully automatic configurations command the largest installed base while customized systems capture the highest margin pools in aseptic pharmaceutical lines. Piston filling technology leads in liquid packaging accuracy for high-viscosity pharmaceutical suspensions, whereas pump filling systems are displacing older overflow methods in cosmetics essential oil bottling due to tighter volume tolerance requirements.
FDA's Current Good Manufacturing Practice enforcements and the EU's MDR conformity obligations compel pharmaceutical and cosmetic manufacturers to validate vacuum integrity and batch traceability in filling operations. EMA's Annex 1 revisions on sterile manufacturing and REACH chemical containment mandates further tighten equipment material specifications and sealing performance benchmarks. Stakeholders must monitor how evolving cleanroom classification harmonization between FDA and EMA inspection protocols reshapes capital allocation priorities for vacuum filling infrastructure upgrades.
Market Dynamics
Closed-loop servo control of vacuum chambers is compressing equipment replacement cycles across pharmaceutical packaging lines. Real-time pressure modulation capabilities are rendering legacy pneumatic systems economically unviable for sterile injectable manufacturing.
Growth Catalysts
- EMA Annex 1 Revisions:Sterile manufacturing mandates for vacuum integrity validation are forcing pharmaceutical packaging lines to upgrade filling infrastructure ahead of inspection protocol harmonization.
- Stuttgart-Karlsruhe Engineering Cluster:Concentrated precision manufacturing capability in Germany's Baden-Württemberg region is shortening equipment procurement lead times for European sterile drug producers.
- F-Gas Regulation Phase-Down:EU restrictions on fluorinated greenhouse gases in industrial equipment are accelerating demand for sealed vacuum pump architectures with lower leakage profiles.
Market Restraints
- Stainless Steel Input Volatility:Pharmaceutical-grade 316L stainless steel price swings are compressing fabrication margins for equipment builders dependent on European mill supply.
- Specialized Component Concentration:Precision vacuum sensor and servo valve production concentrates in German and Swiss industrial corridors, creating single-source vulnerability.
- Regulatory Friction from MDR Transition:EU Medical Device Regulation conformity assessment bottlenecks are extending equipment certification timelines and freezing capital deployment.
Strategic Opportunities
- Biologics Aseptic Filling Expansion:mRNA vaccine and cell therapy manufacturing scale-up in Switzerland and Ireland is creating demand for customized isolator-integrated vacuum filling systems.
- Cosmetic Essential Oil Premiumization:Tighter volume tolerance requirements in French and Italian luxury fragrance bottling are opening displacement opportunities for pump-based vacuum systems against overflow methods.
- Cleanroom Classification Harmonization:Convergence between FDA and EMA inspection protocols is enabling equipment suppliers to design single-validation platforms for transatlantic pharmaceutical customers.
Industry Challenges
- Mechatronics Talent Scarcity:Shortage of engineers combining vacuum physics, servo control, and pharmaceutical process knowledge is constraining R&D throughput for equipment OEMs.
- Legacy System Integration Complexity:Retrofitting closed-loop vacuum modulation into existing filling lines requires extensive isolator requalification, extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Vacuum Filling Machine Market |
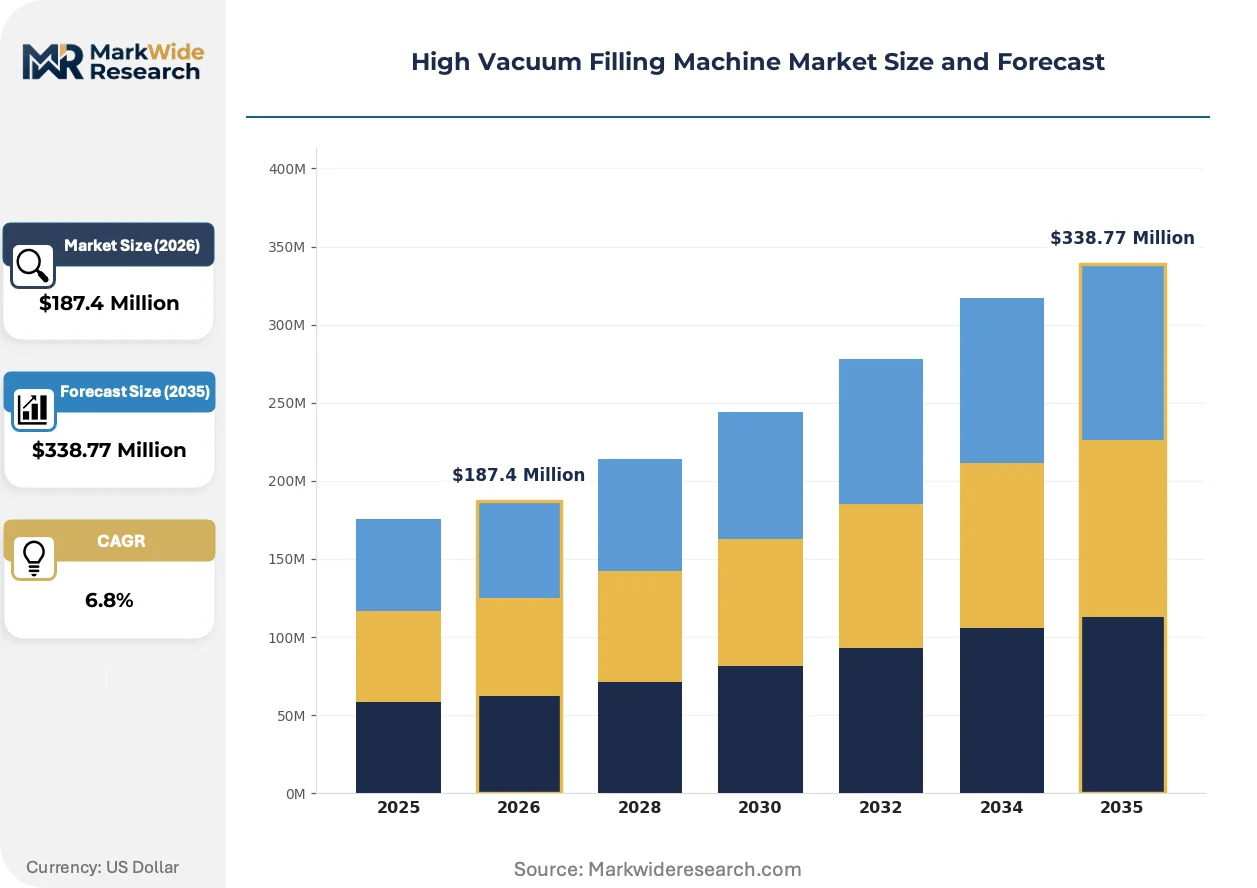
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Customized End User: Food & Beverage, Pharmaceutical, Cosmetics, Chemicals Technology: Piston Filling, Pump Filling, Overflow Filling, Pressure Filling Application: Liquid Packaging, Paste Packaging, Powder Packaging, Granule Packaging |
| Companies Covered | Tenco S.r.l., Heinrich Frey Maschinenbau GmbH, Accutek Packaging Equipment Companies, Inc., Technibag, FIMER S.r.l., Albert Handtmann Maschinenfabrik GmbH & Co. KG, Multivac Group, ULMA Packaging, S.Coop., VEMAG Maschinenbau GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Vacuum Filling Machine Market Shifts & Advancements
Equipment architecture is pivoting toward electromechanical integration that collapses the boundary between vacuum generation and dose precision. This convergence is compressing the functional gap between filling and containment systems.
Magnetically levitated turbomolecular pumps are replacing oil-sealed rotary vane architectures in high-throughput pharmaceutical lines. Sterile injectable manufacturers in Switzerland and Ireland are specifying these systems for protein formulation filling. Oil-free operation is rendering obsolete the contamination risk protocols that previously mandated extensive pump maintenance shutdowns.
REACH chemical containment mandates are tightening permissible leakage rates for vacuum chamber sealing materials. ECHA restrictions on perfluorinated compounds are forcing seal manufacturers toward fluorocarbon alternatives with shorter validated lifecycles. Pharmaceutical OEMs in Germany are responding by integrating predictive seal-wear monitoring into control system architectures.
Service contract unbundling is fragmenting the traditional equipment-plus-maintenance procurement model. Mid-sized cosmetic and nutraceutical producers in France and Italy are purchasing vacuum filling hardware without bundled field service, sourcing third-party maintenance from regional automation specialists. This pattern is most visible in essential oil and natural extract bottling operations where equipment utilization rates justify in-house technical staffing.
High Vacuum Filling Machine Market Segmentation
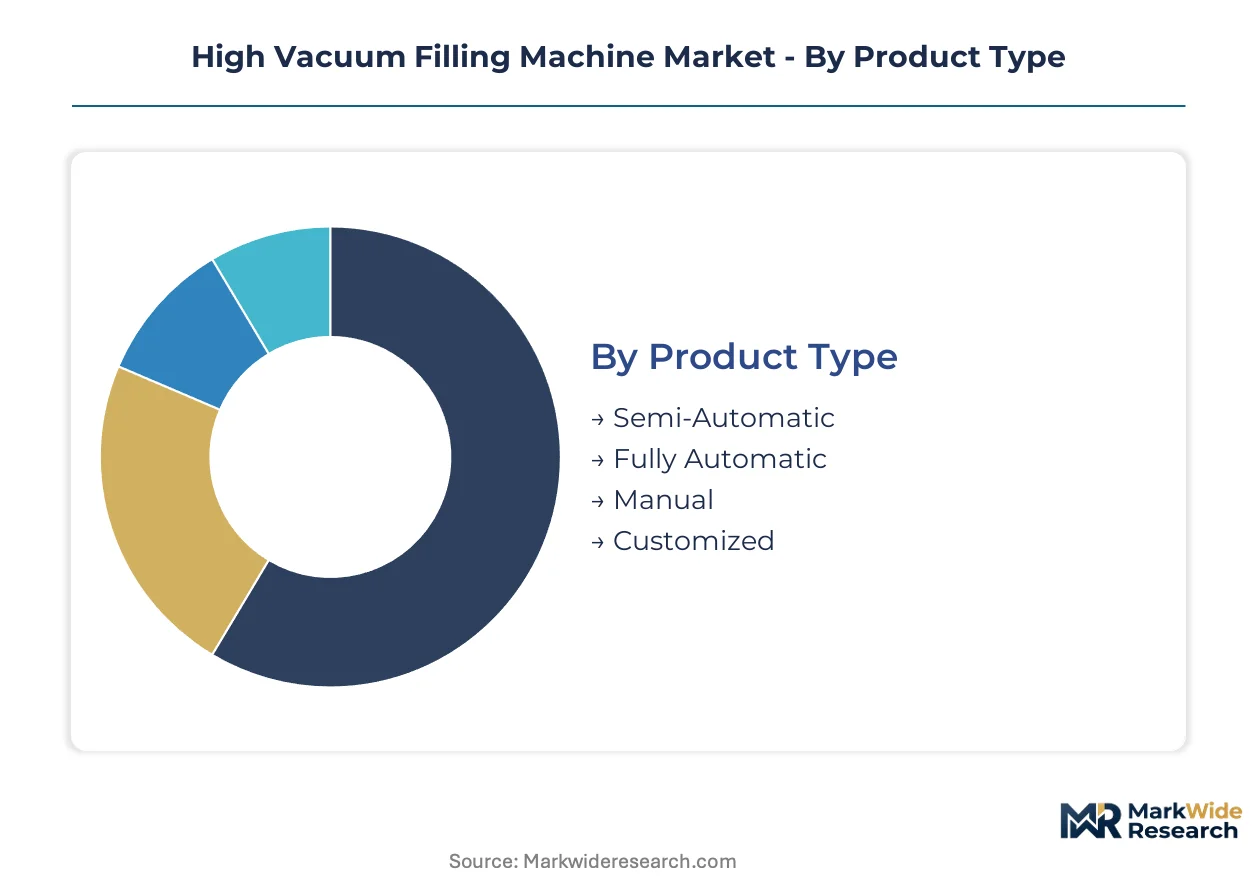
High vacuum filling equipment serves divergent process requirements across sterile pharmaceutical lines, precision cosmetic bottling, and oxygen-sensitive food packaging. Segmentation reveals how automation intensity, containment standards, and viscosity handling specifications reshape procurement priorities across end-use verticals.
Product Type:
Automation intensity defines capital deployment patterns, with cost tier and throughput requirements dictating equipment selection for batch versus continuous operations.
- Fully Automatic:Closed-loop servo architectures enable real-time vacuum modulation and batch traceability for sterile injectable manufacturing. Pharmaceutical producers in Germany's Baden-Württemberg corridor are specifying these systems ahead of EMA Annex 1 compliance deadlines.
- Customized:Isolator-integrated configurations address biologics aseptic filling requirements for mRNA vaccine and cell therapy production. Swiss and Irish manufacturing facilities are driving specification complexity for single-use containment interfaces.
- Semi-Automatic:Mid-scale cosmetic and nutraceutical producers in France and Italy favor these units for essential oil bottling with in-house technical staffing.
- Manual:Laboratory-scale R&D operations and specialty chemical formulation work utilize these systems for low-volume, high-flexibility filling protocols.
Fully automatic systems hold installed capacity. Customized configurations are rotating up the share rankings.
End User:
Application maturity and regulatory burden intensity segment demand, with containment-grade requirements separating pharmaceutical investment cycles from commodity packaging.
- Pharmaceutical:Sterile injectable and biologics manufacturers mandate vacuum integrity validation, stainless steel 316L construction, and isolator integration under FDA Current Good Manufacturing Practice and EMA Annex 1 obligations. mRNA scale-up in Switzerland and Ireland is accelerating specification for magnetically levitated turbomolecular pump architectures.
- Cosmetics:Premium fragrance and essential oil bottling in France and Italy is displacing overflow methods with pump-based vacuum systems to achieve tighter volume tolerances for luxury positioning.
- Food & Beverage:Oxygen-sensitive liquid and paste packaging for extended shelf-life applications utilizes thermoforming-vacuum hybrid lines with strong channel control in European processing plants.
- Chemicals:REACH chemical containment mandates and ECHA restrictions on perfluorinated compounds are forcing seal material transitions with shorter validated lifecycles.
Pharmaceutical dominates capital intensity. Cosmetics is expanding most quickly as premiumization drives equipment upgrades.
Technology:
Filling mechanism selection pivots on viscosity range, volume precision requirements, and compatibility with vacuum chamber integration.
- Piston Filling:Positive displacement systems achieve highest accuracy for high-viscosity pharmaceutical suspensions and pastes. Stainless steel piston construction meets pharmaceutical-grade surface finish requirements under MDR conformity obligations.
- Pump Filling:Peristaltic and gear pump architectures are gaining ground in cosmetics essential oil bottling due to tighter volume tolerance requirements and reduced product degradation risk.
- Overflow Filling:Level-fill precision for low-viscosity liquids remains cost-effective for non-sterile beverage applications but faces displacement in premium segments.
- Pressure Filling:Counter-pressure systems address carbonated liquid packaging where vacuum pre-evacuation combines with controlled pressure dosing.
Piston filling anchors pharmaceutical accuracy standards. Pump filling is climbing the fastest as cosmetics specifications tighten.
Application:
Physical state of the product determines chamber design, seal material selection, and cleaning validation protocols.
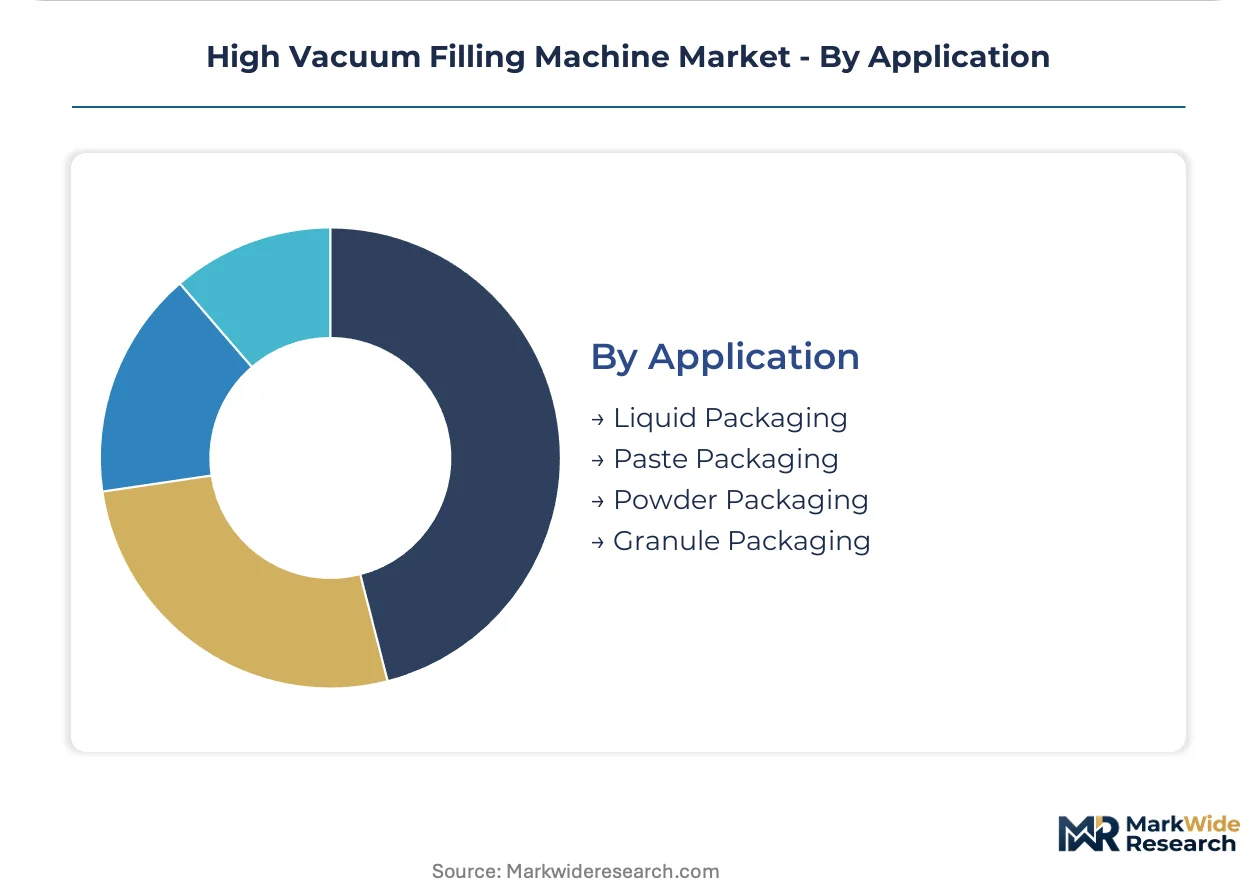
- Liquid Packaging:Sterile injectable solutions, essential oils, and oxygen-sensitive beverages constitute the largest addressable volume, with vacuum pre-evacuation preventing oxidation and microbial ingress below 100 mbar residual pressure.
- Paste Packaging:High-viscosity pharmaceutical suspensions and cosmetic creams require piston-based systems with heated jacketing for flow maintenance.
- Powder Packaging:Aseptic powder filling for lyophilized biologics demands specialized vacuum chamber geometries to prevent particle agglomeration and ensure dose uniformity.
- Granule Packaging:Nutraceutical and specialty chemical granule handling utilizes modified vacuum systems with vibration-assisted feed mechanisms.
Liquid packaging maintains capacity dominance. Paste packaging is gaining share fastest as high-viscosity biologics expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers with sterile injectable portfolios concentrate procurement authority in Germany's precision engineering corridor, while biologics scale-up in Switzerland and Ireland redirects specification complexity toward isolator-integrated systems.
Germany
EMA Annex 1 compliance deadlines and MDR conformity obligations drive replacement of legacy pneumatic filling infrastructure. The F-Gas Regulation phase-down restricts fluorinated greenhouse gas use in industrial vacuum equipment. Stuttgart and Karlsruhe anchor equipment fabrication clusters where Baden-Württemberg-based OEMs compress delivery lead times for European sterile drug producers.
Switzerland
mRNA vaccine manufacturing scale-up and cell therapy production expansion create demand for magnetically levitated turbomolecular pump architectures. Swissmedic sterile manufacturing guidelines mandate validated vacuum integrity protocols for protein formulation filling. Basel and Zurich pharmaceutical manufacturing zones specify oil-free pump systems to eliminate contamination risk shutdowns.
France
Premium fragrance and essential oil bottling operations displace overflow methods with pump-based vacuum systems for tighter volume tolerance. ANSM cosmetic product regulations enforce batch traceability requirements in luxury positioning segments. Grasse and Paris-region cosmetic manufacturing clusters source semi-automatic configurations with in-house technical staffing models.
Italy
Natural extract and nutraceutical bottling operations favor unbundled procurement of vacuum filling hardware without bundled field service. REACH chemical containment mandates and ECHA perfluorinated compound restrictions force seal material transitions. Florence and Milan processing corridors drive specification for predictive seal-wear monitoring integration.
Ireland
Biologics aseptic filling expansion for cell therapy manufacturing creates demand for customized isolator-integrated vacuum systems. EMA sterile manufacturing inspections enforce vacuum integrity validation ahead of protocol harmonization with FDA. Dublin and Cork pharmaceutical manufacturing zones concentrate specification authority for single-use containment interfaces.
High Vacuum Filling Machine Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. The vendor base organizes around three strategic archetypes: precision-engineering fabricators with pharmaceutical-grade stainless steel specialization, vacuum pump integration specialists spanning multiple filling modalities, and thermoforming-vacuum hybrid line providers with food processing channel dominance. Competitive moves concentrate on geographic expansion into Swiss and Irish biologics corridors and technology licensing for closed-loop servo control architectures.
Among German precision-engineering fabricators, Heinrich Frey Maschinenbau GmbH and VEMAG Maschinenbau GmbH occupy positions anchoring pharmaceutical-grade equipment supply. Multivac Group exemplifies the thermoforming-vacuum hybrid archetype with established channel control in European food processing installations. These three entities represent distinct competitive vectors: stainless steel construction depth, vacuum pump integration breadth, and hybrid line dominance respectively.
| Leading Market Players |
|---|
| Tenco S.r.l. |
| Heinrich Frey Maschinenbau GmbH |
| Accutek Packaging Equipment Companies, Inc. |
| Technibag |
| FIMER S.r.l. |
| Albert Handtmann Maschinenfabrik GmbH & Co. KG |
| Multivac Group |
| ULMA Packaging, S.Coop. |
| VEMAG Maschinenbau GmbH |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's container cost dynamics amplify pricing power for German precision fabricators while compressing margins for buyers dependent on Swiss and Irish biologics installations. Stainless steel 316L input volatility from European mills feeds directly into equipment cost-plus contracts, with downstream price differentiation widening between pharmaceutical-grade certified systems and semi-automatic cosmetic configurations.
Pricing Analysis
Cost-plus contracts with London Metal Exchange stainless steel indexation dominate equipment procurement between Baden-Württemberg OEMs and pharmaceutical buyers. Price differentiation separates FDA-validated isolator-integrated systems from CE-marked standard configurations, with volume scale and after-sales bundling as secondary tiering factors. Pricing pressure stems from unbundled service procurement among French and Italian cosmetic producers. Mid-scale essential oil bottlers exhibit highest price sensitivity; sterile injectable manufacturers in Switzerland and Ireland demonstrate lowest sensitivity due to regulatory compliance imperatives.
Supply Chain Analysis
Export-control restrictions on precision servo valves and magnetically levitated turbomolecular pump technology limit component flows from German and Swiss industrial corridors. Equipment fabrication draws from pharmaceutical-grade 316L stainless steel mills in Germany, vacuum sensor specialists in Switzerland, and seal manufacturers in Italy facing ECHA perfluorinated compound restrictions. Single-source vulnerability concentrates in precision vacuum sensor and servo valve production. Distribution runs through direct OEM relationships with pharmaceutical manufacturers and regional automation specialists serving cosmetic and nutraceutical segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent equipment OEMs face substitution pressure from modular, software-defined filling platforms that collapse hardware differentiation into configurable control architectures. Defense of market position requires strategic repositioning around irreplaceable process knowledge and regulatory validation depth.
For Market Incumbents: Entrench position through captive supply of pharmaceutical-grade stainless steel fabrication capacity in Baden-Württemberg and backward integration into predictive seal-wear monitoring software. The modular platform threat from industrial automation conglomerates demands counter-investment in isolator-integrated system architectures that resist disaggregation. Certification depth under FDA and EMA protocols remains the defensible moat. For New Entrants and Emerging Players: Pursue white-space opportunity in unbundled aftermarket service contracts for semi-automatic cosmetic installations across France and Italy. The essential oil bottling segment offers lowest barrier to entry due to reduced validation requirements and in-house technical staffing preferences. Go-to-market execution should anchor on regional automation specialist partnerships rather than direct pharmaceutical channel development. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineering fabricators with pharmaceutical-grade stainless steel specialization over vacuum pump integration generalists. Long-term viability rests on regulatory validation asset accumulation and isolator integration capability depth. The inflection signal to monitor is FDA-EMA cleanroom classification harmonization progress, which would compress validation cost burdens for transatlantic equipment platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Fabrication | Captive 316L supply secures margin control against European mill price volatility. |
| Isolator-Integrated System Development | mRNA and cell therapy scale-up in Switzerland and Ireland demands customized containment interfaces. |
| Predictive Seal-Wear Monitoring Integration | ECHA perfluorinated restrictions shorten seal lifecycles and create service contract expansion opportunity. |
| Regional Automation Specialist Partnership | Unbundled procurement patterns in France and Italy favor third-party maintenance channel access. |
| Magnetically Levitated Pump Architecture Licensing | Oil-free operation eliminates contamination risk protocols and extends addressable market into protein formulations. |
Research Methodology
Operator-level perspectives from pharmaceutical packaging line engineers, cosmetic production managers, vacuum pump maintenance directors, and OEM procurement specialists anchored the qualitative base. These primary insights combined with secondary validation from FDA warning letter databases, EMA inspection outcome reports, EU F-Gas Regulation implementation tracking, and REACH chemical restriction filings. Bottom-up equipment shipment analysis and top-down pharmaceutical capital expenditure triangulation structured market sizing.
Scenario-bracketing around EMA Annex 1 compliance deadline phasing and F-Gas Regulation phase-down intensity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include automation intensity, end-use vertical regulatory burden, filling technology viscosity range, and regional cleanroom classification convergence. CAGRs derived from equipment replacement cycle compression rates and biologics manufacturing capacity expansion trajectories. Forecast inputs incorporated stainless steel price index volatility and precision mechatronics talent availability constraints.
Sensitivities concentrate around EMA-FDA inspection protocol harmonization timing and REACH seal material restriction enforcement intensity. Forecasts reflect documented assumptions on regulatory compliance cost pass-through and biologics manufacturing scale-up commitment durability. Material shifts in fluorinated compound regulatory thresholds or sterile manufacturing validation requirement stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Powder Auger Fillers Market
Packaging Machinery
Precision Dispensing Machine Market
Packaging Machinery
Sliding Injection Molding Machine Market
Packaging Machinery
Horizontal Strapping Machine Market
Packaging Machinery
Stacking Machine Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Automatic Filling Machine Market
Packaging Machinery
EPS Pre-Expander Machines Market
Packaging Machinery
Packaging Machine Heaters Market
Packaging Machinery
Vial Capping Machines Market
Packaging Machinery
Cup Filling Machine Market
Packaging Machinery
Hand-Held Capping Machines Market
Packaging Machinery
Puffer Machines Market
Packaging Machinery
Aseptic Filling Machines Market
Packaging Machinery
Die Cutting Machine Market
Packaging Machinery
Tray and Sleeve Packing Machines Market