
 Foil Tapes Market | 2026-2036
Foil Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Foil Tapes Market Analysis
Asset-light leasing models for metallized film coating equipment is narrowing the capital barrier for mid-tier converters entering foil tape production. 3M leverages captive resin formulation technology to sustain margin control across adhesive-backed aluminum lines. Nitto Denko Corporation anchors its position through precision slitting capabilities that dominate Asian electronics supply chains. Saint-Gobain differentiates via ceramic-filled silicone adhesives engineered for aerospace thermal protection.
Foil tapes are pressure-sensitive adhesive strips laminated to metal foils, typically aluminum at 0.02–0.05 mm gauge, engineered for thermal conductivity, moisture barrier performance, and EMI shielding across industrial sealing and electrical insulation tasks. Acrylic adhesive formulations command the widest application footprint due to cost-positioning and ambient-temperature bonding reliability, while silicone chemistry captures premium thermal cycling segments in aerospace and under-hood automotive assembly. Copper foil variants with conductive acrylic systems are displacing traditional shielding gaskets in electronics manufacturing, concentrating margin pools in cleanroom-grade tape specifications.
The US Department of Energy's building efficiency mandates and the EPA's phasedown of high-GWP blowing agents are tightening thermal envelope standards that directly expand HVAC foil tape specification volumes. REACH compliance in Europe restricts solvent-based adhesive chemistries, pushing formulation shifts toward waterborne acrylic and hot-melt rubber systems that carry higher raw material conversion costs. China's GB standards for construction material flammability, enforced by SAMR, are elevating certified tape requirements in high-rise builds. Stakeholders must monitor adhesive chemistry transitions and regional certification reciprocity to avoid supply disqualification as specification authority fragments across national building codes.
Market Dynamics
Building efficiency mandates across Germany, the United States, and China are compressing thermal envelope specifications and accelerating specification-grade foil tape volumes in HVAC duct sealing and insulation applications.
Growth Catalysts
- US Department of Energy codes:Tightening thermal barrier requirements in commercial construction are expanding foil tape specification volumes for ductwork sealing and vapor barrier continuity.
- Automotive electrification:Battery pack thermal management systems are consuming ceramic-filled silicone foil tapes for cell-to-cell heat dissipation and fire containment layers.
- Copper foil substitution:Conductive acrylic copper tapes are displacing traditional EMI shielding gaskets in electronics manufacturing cleanrooms.
Market Restraints
- Aluminum ingot volatility:Raw material cost swings in primary aluminum are compressing converter margins and forcing inventory risk onto mid-tier producers.
- Slitting equipment concentration:Precision slitting capabilities for electronics-grade narrow widths concentrate in Japanese and Korean equipment suppliers, creating supply bottlenecks.
- REACH solvent restrictions:ECHA limitations on solvent-based adhesive chemistries are forcing costly formulation migrations toward waterborne acrylic systems with inferior green strength.
Strategic Opportunities
- India's construction acceleration:Urban high-rise building codes under BIS are elevating certified fire-rated tape requirements in HVAC and electrical sealing applications.
- Leasing-based coating capacity:Asset-light metallized film equipment models are lowering capital barriers for regional converters seeking tape production entry.
- GB standard enforcement:China's SAMR flammability certifications for construction materials are creating premium tape tiers for high-rise builds.
Industry Challenges
- Adhesive chemist scarcity:Formulation expertise for silicone-acrylic hybrid systems is concentrating at incumbent resin suppliers, constraining independent converter R&D.
- Multi-certification timelines:Simultaneous UL, FM, and GB compliance testing is extending product launch cycles by 8-14 months for cross-border specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foil Tapes Market |
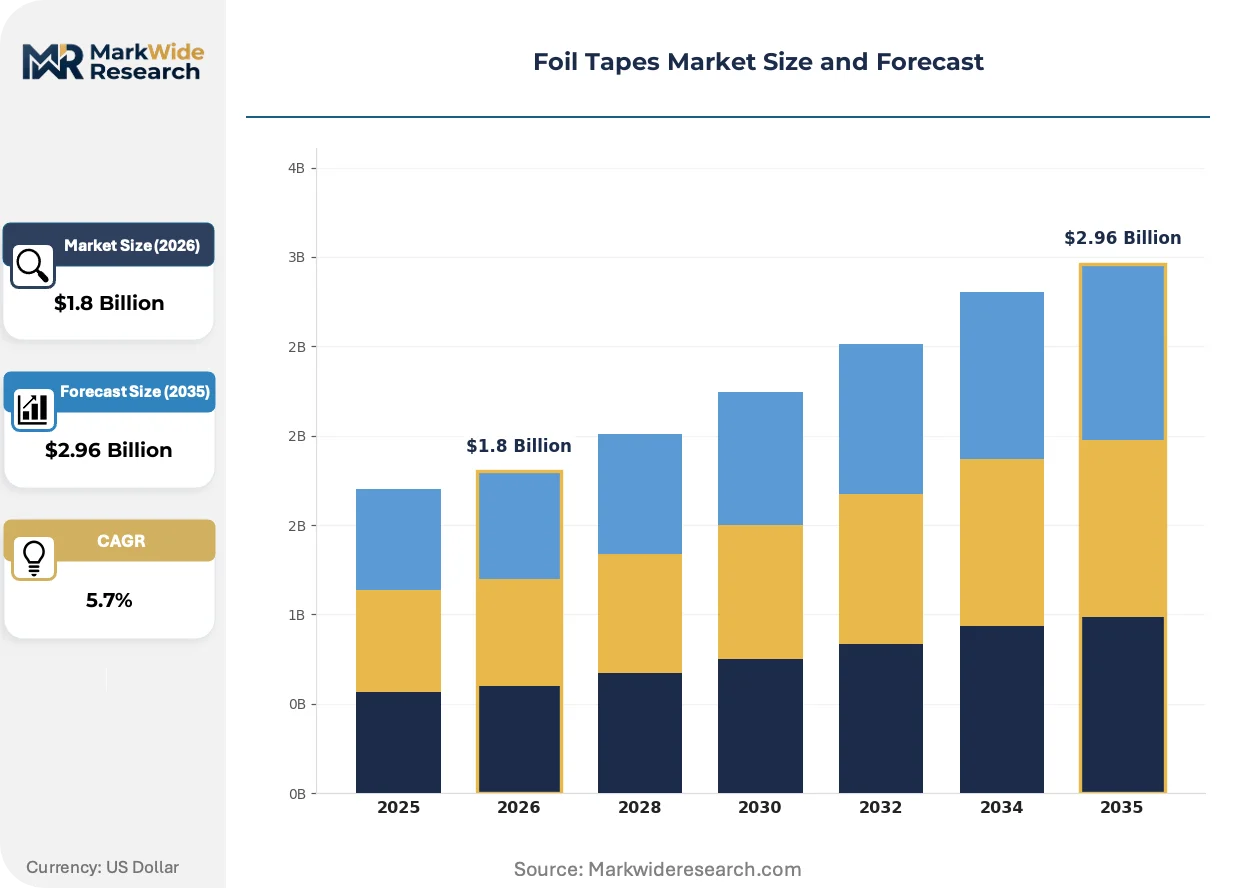
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum, Copper, Stainless Steel, Bimetal Application: HVAC, Electrical Insulation, Automotive, Packaging Adhesive Type: Acrylic, Rubber, Silicone, Hybrid End User: Construction, Electronics, Aerospace, Manufacturing |
| Companies Covered | Advance Tapes International, Nitto Denko Corporation, 3M, All Foils, Avery Dennison, Saint-Gobain, Shurtape Technologies, Nova Films & Foils, Scapa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foil Tapes Market Emerging Trajectories
Adhesive chemistry convergence and coating equipment democratization are compressing traditional barriers between commodity and specification-grade foil tape production tiers.
Nanoparticle-filled acrylic adhesives are collapsing the performance gap between standard HVAC tapes and aerospace-grade thermal cycling products. Tier-one HVAC contractors in Germany and the northeastern United States are specifying these formulations for high-velocity duct systems. The technology is collapsing the historical three-tier pricing structure into two distinct performance bands.
REACH restrictions on solvent-based systems are forcing waterborne acrylic and hot-melt rubber migrations across European converter operations. ECHA compliance deadlines are elevating raw material conversion costs by 15-25% for reformulated product lines. German industrial buyers are responding by consolidating purchase volumes toward vertically integrated suppliers with captive resin production.
Specification authority is fragmenting across national building codes rather than harmonizing under ISO standards. Procurement teams at multinational construction firms now maintain separate approved vendor lists for US DOE-compliant, REACH-certified, and GB-rated tape specifications. This pattern is most visible in Singapore and Dubai, where project portfolios span multiple regulatory jurisdictions simultaneously.
Foil Tapes Market Segmentation
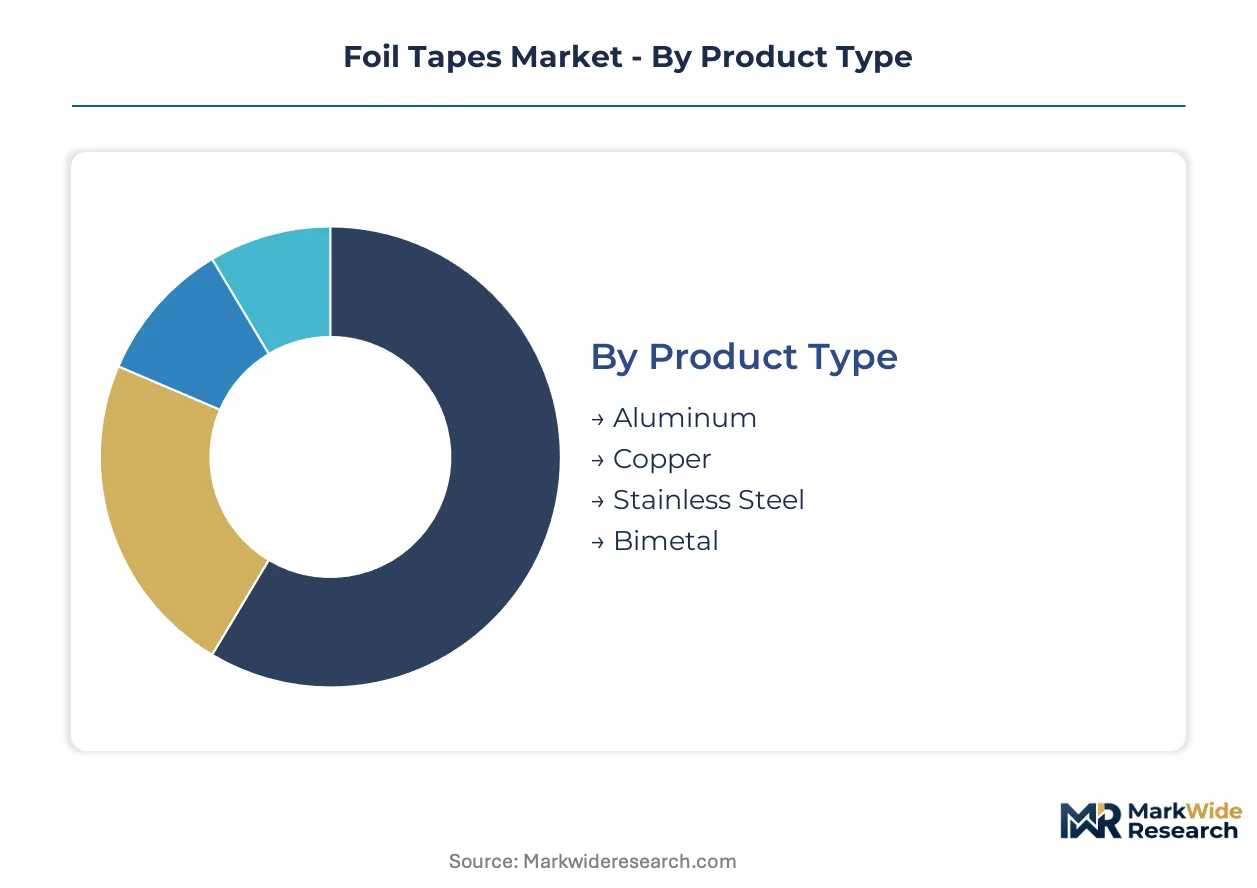
Foil tape segmentation reflects divergent performance requirements across thermal management, electrical shielding, and barrier applications. Specification authority fragments by end-use certification demands, forcing converters to maintain parallel product lines with chemistry and gauge variations.
Product Type:
Mature aluminum formats dominate volume flows while specialty metals capture premium specification tiers.
- Aluminum:Rolled foil at 0.02–0.05 mm gauge with acrylic or silicone adhesive systems serves HVAC duct sealing and vapor barrier continuity. US Department of Energy thermal envelope codes are accelerating specification-grade volumes in commercial construction.
- Copper:Electrodeposited or rolled copper foil with conductive acrylic adhesives delivers EMI shielding for electronics cleanrooms. The segment is displacing traditional metal gaskets in Asian semiconductor fabrication facilities.
- Stainless Steel:Austenitic grade foils withstand corrosive chemical environments in process manufacturing.
- Bimetal:Aluminum-copper laminates balance conductivity with cost in specialized electrical bonding applications.
Aluminum retains volume leadership; copper holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity construction sealing from certified industrial specifications.
- HVAC:Pressure-sensitive aluminum tapes seal ductwork joints and maintain vapor barrier integrity across thermal insulation systems. Germany's industrial manufacturing corridor concentrates demand for high-velocity duct specifications.
- Electrical Insulation:Dielectric-grade tapes with silicone adhesives isolate high-voltage windings and bus bars. REACH solvent restrictions are forcing waterborne acrylic migrations that elevate raw material conversion costs.
- Automotive:Ceramic-filled silicone foil tapes manage battery pack thermal runaway containment in electric vehicle assembly.
- Packaging:Metallized barrier tapes protect moisture-sensitive pharmaceuticals and electronics during transit.
HVAC maintains installed base dominance; automotive posts the most aggressive growth trajectory.
Adhesive Type:
Supply concentration in resin formulation expertise shapes competitive access to specification-grade chemistries.
- Acrylic:Waterborne and solvent-borne systems bond reliably at ambient temperatures across general industrial applications. ECHA compliance deadlines are accelerating European converter migration away from solvent-based platforms.
- Silicone:Addition-cure and condensation-cure systems withstand thermal cycling from -40°C to 200°C in aerospace and under-hood automotive assembly. Formulation expertise concentrates at incumbent resin suppliers, constraining independent converter R&D.
- Rubber:Natural and synthetic rubber hot-melt systems serve cost-sensitive packaging and temporary holding applications.
- Hybrid:Silicone-acrylic copolymers bridge performance gaps in emerging nanoparticle-filled formulations.
Acrylic commands volume leadership; hybrid systems are climbing the fastest on specification demand.
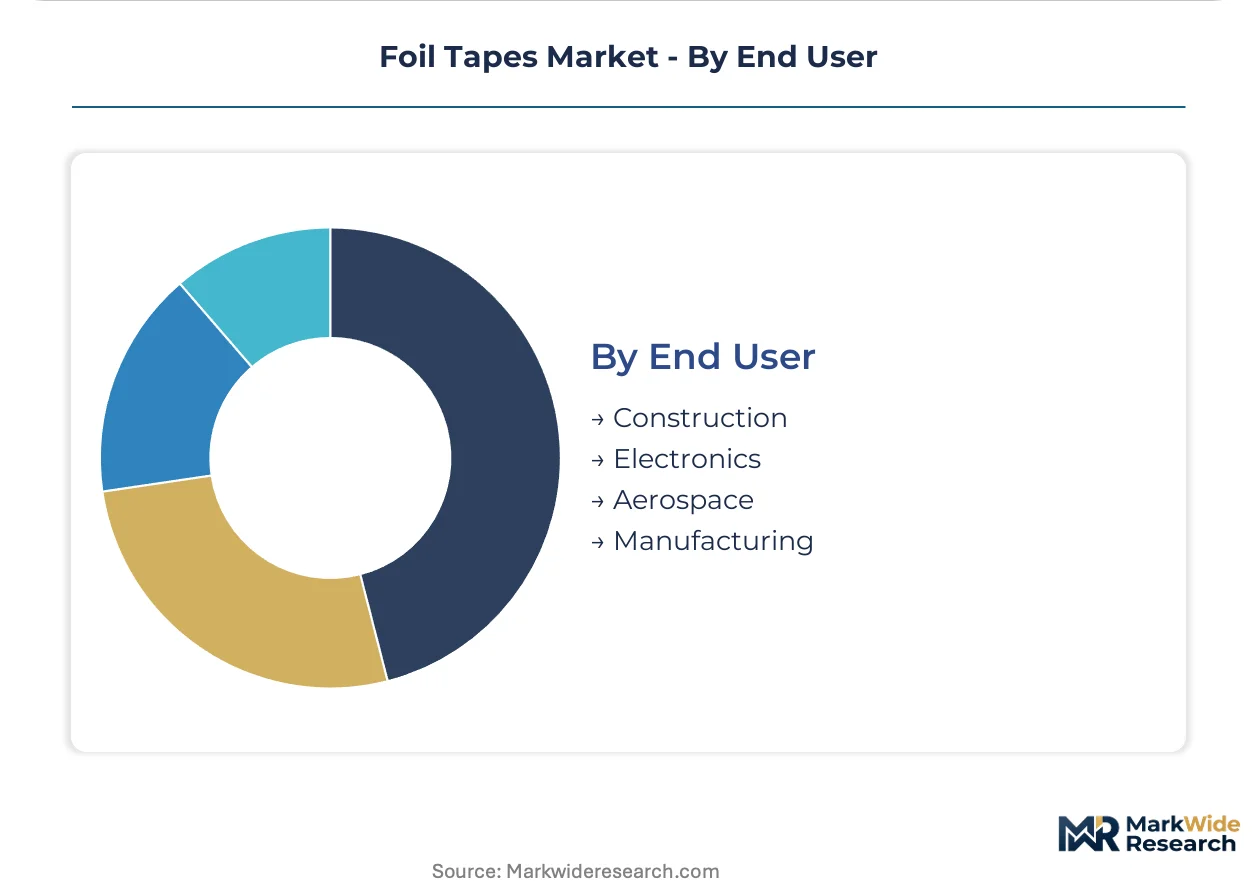
End User:
Customer type fragmentation drives parallel certification requirements that extend product development timelines.
- Construction:Building contractors specify fire-rated tapes for high-rise HVAC and electrical sealing under divergent national codes. China's SAMR enforces GB flammability certifications that create premium tape tiers.
- Electronics:Cleanroom-grade copper tapes with particle-controlled adhesives serve semiconductor and display manufacturing. Precision slitting capabilities for narrow widths concentrate in Japanese and Korean equipment suppliers.
- Aerospace:Ceramic-filled silicone systems meet FAA thermal protection specifications for engine nacelles and airframe insulation.
- Manufacturing:General industrial buyers consolidate volumes toward vertically integrated suppliers with captive resin production.
Construction retains volume leadership; electronics holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while converters in India's emerging construction belt absorb compressed margins from aluminum ingot volatility. Specification-grade tape premiums widen between REACH-compliant European supply and cost-optimized Asian production. Regional fragmentation in building codes is forcing parallel certification investments that reshape competitive returns.
United States
Commercial HVAC retrofit cycles and data center construction are accelerating foil tape consumption across thermal envelope applications. The US Department of Energy's building efficiency codes are tightening duct sealing specifications in high-velocity systems. The northeastern corridor from Boston to Washington concentrates demand for fire-rated electrical insulation tapes under evolving municipal amendments.
Germany
Industrial manufacturing clusters and precision engineering exports are sustaining premium tape specifications for cleanroom and process equipment sealing. ECHA's REACH solvent restrictions are forcing waterborne acrylic migrations that elevate converter raw material costs by 15-25%. The Ruhr industrial belt and Bavarian manufacturing corridor anchor European demand for ceramic-filled silicone aerospace grades.
China
High-rise urbanization and electric vehicle battery assembly are expanding foil tape specification volumes across thermal management and fire containment layers. SAMR's GB flammability certifications for construction materials are creating premium tape tiers for certified high-rise builds. The Yangtze River Delta and Pearl River Delta concentrate electronics-grade copper tape demand for semiconductor fabrication facilities.
India
Urban high-rise construction acceleration under BIS codes is elevating certified fire-rated tape requirements in HVAC and electrical sealing applications. The country's national building regulator is tightening flammability standards for commercial structures above 15 stories. Maharashtra and Gujarat industrial corridors are emerging as conversion hubs for domestic specification-grade supply.
Japan
Electronics manufacturing precision requirements and automotive thermal cycling applications are sustaining demand for narrow-width slitting capabilities. METI's industrial standards for high-performance materials are maintaining certification barriers for imported tape specifications. The Kanto region around Tokyo concentrates cleanroom-grade copper tape consumption for display and semiconductor production.
Foil Tapes Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in adhesive formulation and precision slitting equipment. The vendor base stratifies across three tiers: multinational conglomerates with captive resin production, regional converters leasing metallized film coating capacity, and narrow specialists in electronics-grade slitting. Two dominant competitive moves are reshaping positioning: backward integration into resin formulation by volume leaders, and asset-light equipment leasing partnerships that lower capital barriers for mid-tier entrants.
Among diversified materials conglomerates, 3M and Saint-Gobain exemplify the vertically integrated archetype with in-house adhesive chemistry control. Nitto Denko Corporation anchors the precision slitting specialist tier for Asian electronics supply chains. These three occupy positions that reflect divergent strategic bets on specification authority: formulation capture versus equipment capability concentration versus regional certification proximity.
| Leading Market Players |
|---|
| Advance Tapes International |
| Nitto Denko Corporation |
| 3M |
| All Foils |
| Avery Dennison |
| Saint-Gobain |
| Shurtape Technologies |
| Nova Films & Foils |
| Scapa Group |
| Others |
Supply Flow & Price Mechanics
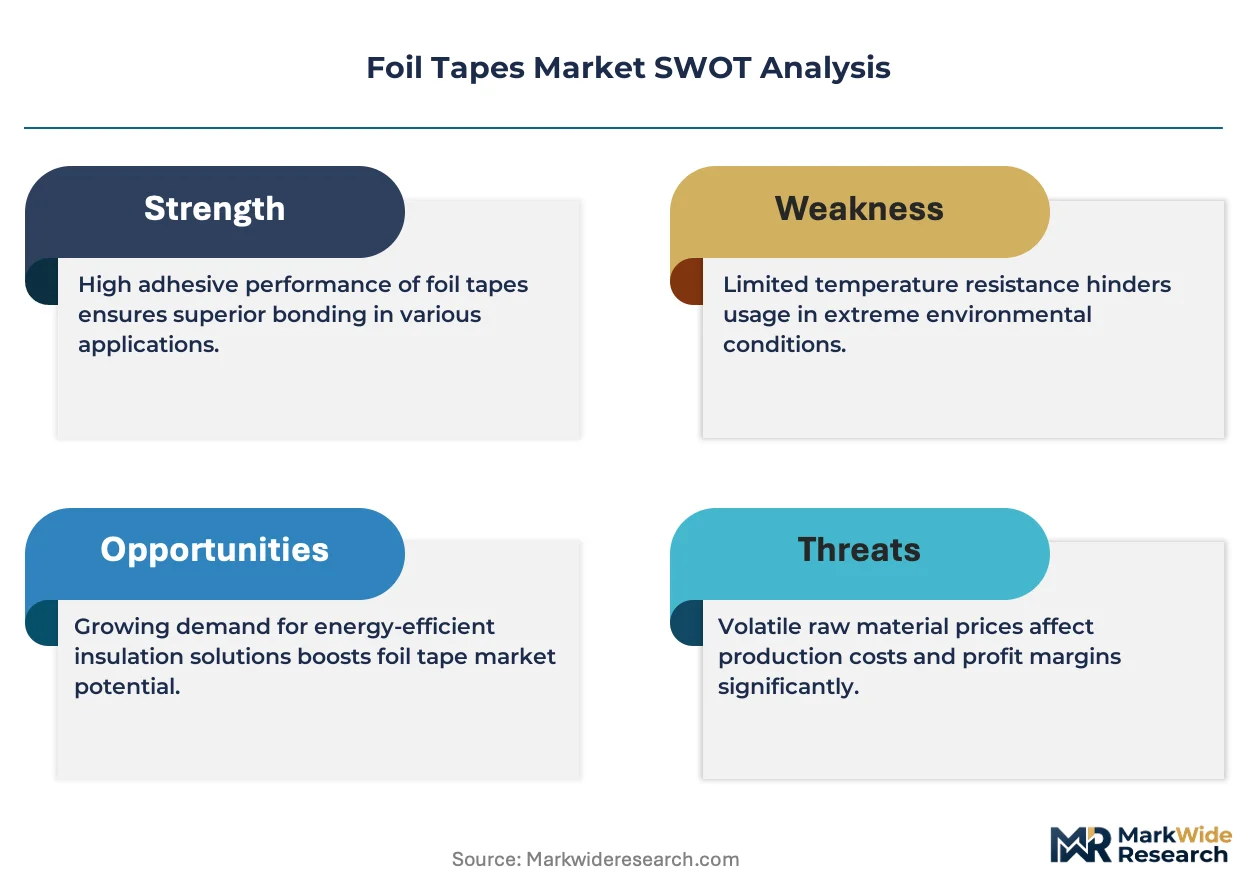
Overcapacity in Asian metallized film coating lines is compressing spot pricing for commodity aluminum tapes while tightening specification-grade premiums in German and US industrial corridors. Utilization rates below 70% in Chinese converter facilities are forcing asset-light leasing models that narrow capital barriers but erode margin buffers across mid-tier producers.
Pricing Analysis
Configured-to-order pricing for REACH-compliant silicone-acrylic hybrids commands 40-60% premiums over standard HVAC-grade acrylic tapes. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification complexity: UL/FM dual-rated tapes for US commercial construction, single-certified standard grades for residential HVAC, and uncertified economy rolls for temporary packaging holds. Cost compression in commodity aluminum tiers is intensifying because primary ingot volatility transfers inventory risk to converters without captive smelter relationships. General industrial buyers in manufacturing applications exhibit highest price sensitivity; aerospace contractors and semiconductor cleanroom operators demonstrate lowest sensitivity due to qualification lock-in costs.
Supply Chain Analysis
Extended payment terms from German automotive OEMs and Japanese electronics assemblers are stretching working capital cycles for mid-tier converters without supply-chain finance facilities. Raw material sourcing concentrates in China for primary aluminum foil, Japan for precision slitting equipment, and Germany for specialty silicone resin formulations. Converter operations draw from electrodeposited copper feedstock, ceramic filler compounds, and pressure-sensitive adhesive polymers. Single-source vulnerability sits with Japanese equipment suppliers controlling narrow-width slitting capabilities for electronics-grade specifications. Distribution runs through regional industrial distributors for construction applications and direct OEM supply agreements for automotive and aerospace tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against liquid gasket dispensation and spray-applied thermal barriers that threaten mechanical fastening applications. Incumbents must navigate displacement risk in electronics EMI shielding where conductive coatings erode tape specification volumes.
For Market Incumbents: Insulate specification-grade positioning through captive resin formulation investments that lock adhesive chemistry access against independent converter R&D constraints. Deepen backward integration into silicone-acrylic hybrid production to offset ECHA compliance cost elevations. Defend against Asian equipment-leasing entrants by accelerating multi-certification timelines that extend product launch cycles for cross-border specifications.
For New Entrants and Emerging Players: Pursue India's BIS-certified fire-rated tape segment where urban high-rise construction acceleration outpaces domestic converter capacity. Target asset-light metallized film equipment partnerships in Maharashtra and Gujarat industrial corridors to bypass capital-intensive coating line ownership. Angle through regional distributor relationships with Tier 2 HVAC contractors seeking certified alternatives to incumbent supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-leasing sub-segments as coating capacity democratization lowers entry barriers. Long-term viability favors vertically integrated suppliers with in-house resin production and established certification reciprocity across US DOE, REACH, and GB standards. Acquisition target archetype: mid-tier converters with installed slitting capabilities but lacking adhesive formulation control. Monitor aluminum ingot price volatility as inflection indicator for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Formulation | Captive silicone-acrylic production offsets ECHA solvent restriction compliance costs for European operations. |
| Multi-Certification Investment | Simultaneous UL, FM, and GB testing extends product launch cycles but locks cross-border specification access. |
| Asset-Light Equipment Leasing | Metallized film coating partnerships lower capital barriers for regional converters entering tape production. |
| Precision Slitting Capability Acquisition | Narrow-width electronics-grade slitting concentrates in Japanese suppliers, creating bottleneck control value. |
| Regional Distribution Partnership | Tier 2 HVAC contractor relationships in India's emerging construction belt accelerate certified product penetration. |
Methodological Framework
Desk research of customs trade data, SEC 10-K filings from diversified materials conglomerates, and ECHA regulatory submissions preceded structured interviews with adhesive R&D directors, HVAC procurement managers at Tier 1 contractors, electronics cleanroom operations heads, and metallized film equipment lessors. Secondary validation drew from SAMR GB standard enforcement notices, US Department of Energy building code amendments, and Japanese METI industrial material specifications. Bottom-up volume modeling triangulated against top-down construction spending and automotive production forecasts.
Assumptions held fixed include current REACH solvent restriction timelines, SAMR flammability certification enforcement intensity, and aluminum ingot price volatility bands observed across recent commodity cycles. Segmentation dimensions modeled encompass foil metal type, adhesive chemistry platform, end-use application, and regional regulatory cluster. CAGRs derived from regression against construction output indices, electric vehicle battery pack assembly rates, and semiconductor fabrication capacity expansion. Industry-specific inputs included HVAC ductwork specification rates and cleanroom-grade copper tape penetration curves.
Macroeconomic conditions sit as an overlay; deviation in construction spending cycles, automotive platform transition timing, or raw material commodity trajectories would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement continuity and certification reciprocity patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Carton Sealing Tape Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Carry Handle Tape Market
Tapes
Labels, Tapes and Films Market
Tapes
Global Non-Conductive Water Blocking Tape Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Sterilization Indicator Tape Market
Tapes
Aluminum Foil Tape Market
Tapes
Pouch Tapes Market
Tapes
Packaging Tape Printing Market
Tapes
Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Painting Masking Tapes Market
Tapes
Metal Foil Tapes Market
Tapes
Ultra High Bond (UHB) Tape Market
Tapes
Replica Tapes Market