
 Edge Band Tapes Market | 2026-2036
Edge Band Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Edge Band Tapes Market Analytics
Germany is reconfiguring European supply dynamics through advanced thermoplastic extrusion capacity additions near Cologne. REHAU leverages its polymer compounding heritage to sustain premium positioning across ABS edge banding grades. Doellken-Woodtape Inc. anchors North American availability through specialized distribution to carpentry workshops. Shanghai Fujuan Group Co., Ltd. dominates Asian volume tiers with integrated PVC resin-to-tape manufacturing.
Edge band tapes are narrow thermoplastic or resin-impregnated strips, typically 0.3 mm to 0.7 mm thick, applied to exposed substrate edges of particleboard or MDF via hot-melt adhesive activation to seal porous surfaces and prevent moisture ingress. PVC formulations currently occupy the largest material share due to cost-performance balance, though ABS segments are gaining traction among European modular kitchen providers seeking phthalate-free alternatives. Furniture manufacturing absorbs the majority of tape volumes, while interior decoration applications command higher per-meter margins through custom color matching and textured finishes.
ECHA REACH restrictions on plasticizer migration influence formulation choices across European tape converters, while China's GB standards for indoor air quality shape domestic PVC edge band specifications. The US EPA and OSHA guidelines govern volatile organic compound emissions during hot-melt application in carpentry workshops. Stakeholders must monitor evolving chemical compliance thresholds and assess backward integration into polymer compounding to secure margin control.
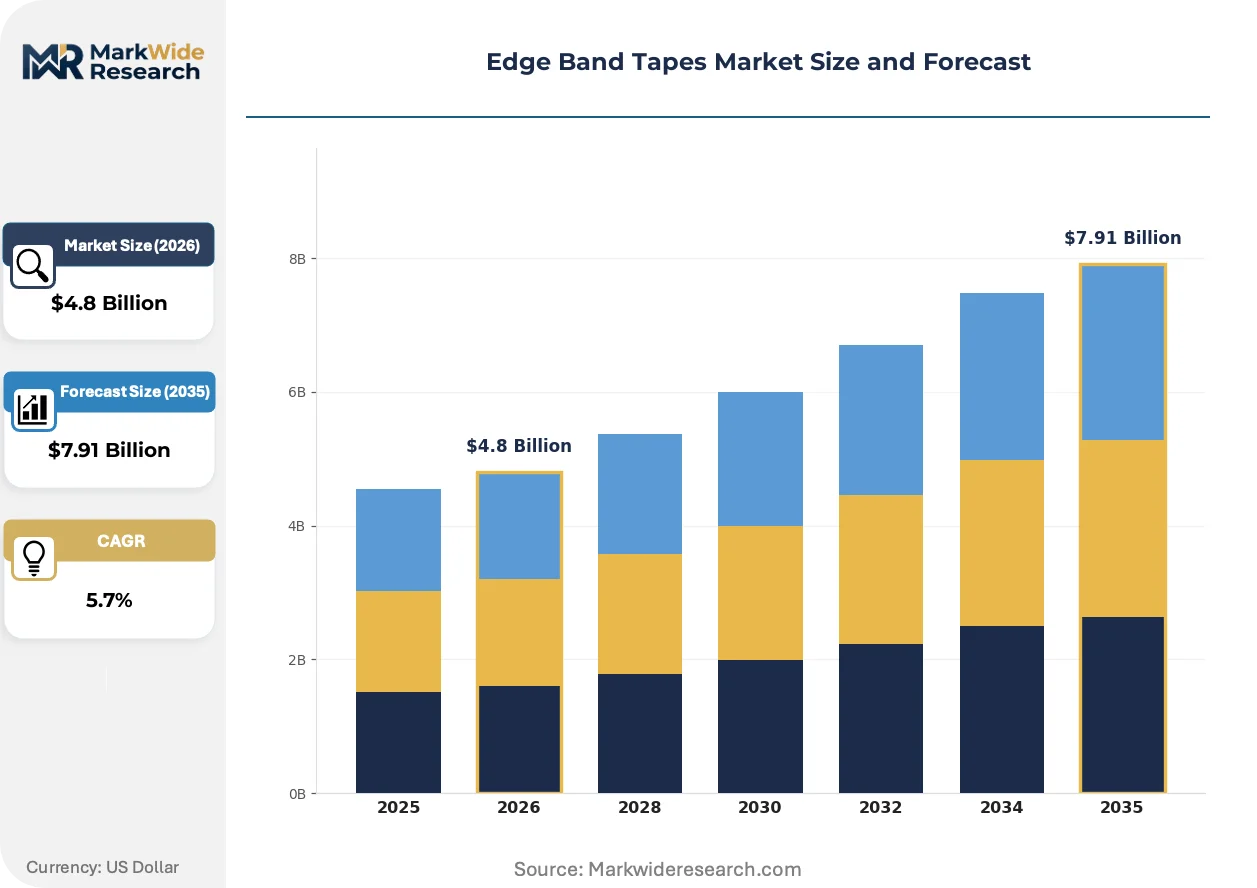
Market Dynamics
REACH plasticizer restrictions are forcing European converters to reformulate PVC edge band tapes toward phthalate-free alternatives, while China's Guangdong furniture clusters drive bulk ABS procurement that is reshaping material mix across Asian supply chains.
Growth Catalysts
- ECHA REACH compliance mandates:German modular kitchen providers are accelerating procurement of low-VOC edge banding materials, creating premium-grade demand pull across European extrusion capacity.
- Furniture manufacturing cluster concentration:China's Guangdong province sustains bulk consumption of ABS and PVC edge band tapes through integrated particleboard-to-finished-goods production ecosystems.
- Hot-melt adhesive activation systems:Automated edge banding machinery in North American carpentry workshops is compressing application cycle times and expanding addressable substrate thickness ranges.
Market Restraints
- Petrochemical input volatility:PVC resin and ABS polymer prices fluctuate with crude oil derivatives, squeezing converter margins on fixed-price furniture supply contracts.
- Supply concentration in Asian polymer compounding:Three integrated resin-to-tape manufacturers control majority Asian volume, creating procurement risk for European distributors lacking backward integration.
- Technical thickness limitations:Sub-0.3 mm thermoplastic tapes exhibit elevated cracking rates during high-speed application, constraining ultra-thin furniture design possibilities.
Strategic Opportunities
- Underpenetrated Indian organized furniture retail:India's BIS certification requirements for indoor air quality are creating first-mover advantage for phthalate-free ABS edge band suppliers establishing local compounding partnerships.
- Regulatory tailwind from EU Green Deal:Circular economy mandates for recyclable furniture components are accelerating R&D into mono-material edge band tapes compatible with post-consumer particleboard recycling streams.
- Direct-to-fabricator digital distribution:Specialized e-procurement platforms are disintermediating traditional distributor layers for small-batch custom color matching in European interior decoration segments.
Industry Challenges
- Colorimetric technician scarcity:Custom textured finish development requires specialized pigment dispersion expertise that furniture OEMs struggle to retain in-house.
- Multi-certification timeline compression:Simultaneous ECHA REACH, GB standards, and US EPA compliance documentation extends product launch cycles by 8-14 months for cross-regional tape suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edge Band Tapes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, ABS, Acrylic, Melamine, PP, PET Application: Furniture Manufacturing, Interior Decoration, Cabinet Making, Door Frames, Wall Panels, Countertops Thickness: 0.3 mm, 0.4 mm, 0.5 mm, 0.6 mm, 0.7 mm End User: Carpentry Workshops, Home Improvement Retailers, Interior Designers, Modular Kitchen Providers |
| Companies Covered | Doellken-Woodtape Inc., REHAU, E3 Panels, EdgeCo Incorporated, Veena Polymers, PRI Edgebanding, Shanghai Fujuan Group Co., Ltd., Mobelkant, Gdecor Industries India Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edge Band Tapes Market Evolving Landscape
Digital color matching systems are compressing specification cycles between furniture designers and tape converters, while regulatory fragmentation across three major economic zones forces parallel formulation tracks.
Laser-activated adhesive edge banding is virtualizing the traditional hot-melt application infrastructure. German kitchen manufacturers are piloting solvent-free bonding systems that eliminate pre-heating equipment footprints. This technology is virtualizing capital requirements for small-batch custom furniture producers, enabling distributed manufacturing models previously constrained by adhesive system economics.
ECHA REACH restrictions on plasticizer migration are tightening allowable thresholds for DEHP and DINP in finished furniture. European tape converters are reformulating toward citrate-based plasticizers or transitioning entirely to ABS grades. Modular kitchen providers in Germany and France face the most immediate compliance deadlines, with Q3 2025 inventory transitions already contracted.
Consolidated procurement by pan-European furniture retail chains is compressing supplier qualification timelines. Independent carpentry workshops are losing direct mill relationships as volume concentrates through centralized specification offices. This pattern is most visible in Benelux and Nordic markets where two retail groups control majority kitchen cabinet distribution, forcing tape converters to maintain dedicated key account technical service teams.
Edge Band Tapes Market Segmentation
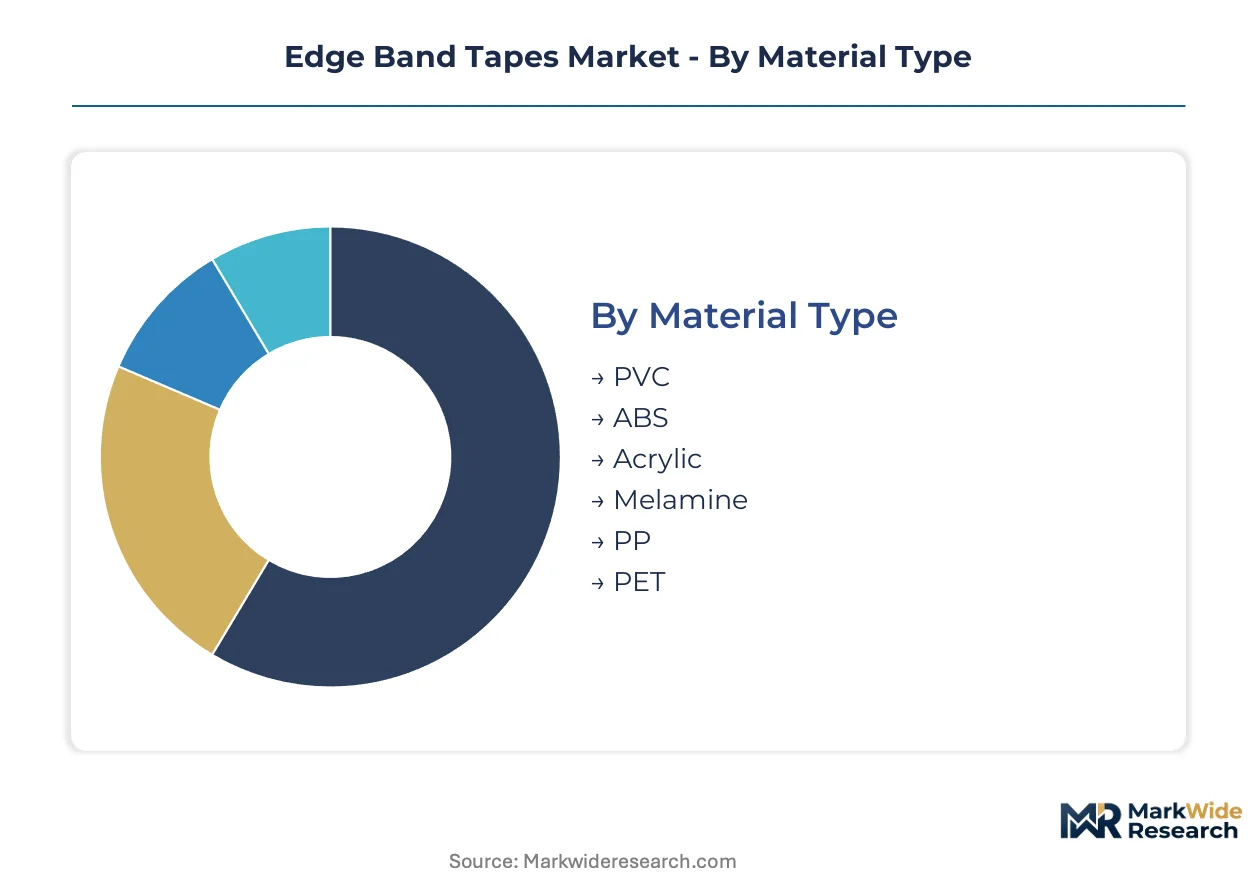
Edge band tape procurement patterns diverge sharply across material chemistry, end-use durability requirements, and fabrication scale. Specification decisions cascade from regulatory compliance thresholds through automated machinery compatibility to final aesthetic matching protocols.
Material Type:
Cost tier stratification separates commodity thermoplastics from engineering-grade alternatives with differentiated compliance profiles.
- PVC:Chlorinated thermoplastic formulations dominate volume tiers through cost-performance balance and broad color availability. Guangdong furniture clusters consume the majority of global PVC edge band output for particleboard sealing applications. Phthalate plasticizer restrictions under ECHA REACH are forcing European converters toward citrate-based alternatives or material transitions.
- ABS:Acrylonitrile-butadiene-styrene copolymer delivers superior impact resistance and phthalate-free compliance for premium kitchen cabinetry. German modular kitchen providers are accelerating ABS procurement ahead of Q3 2025 inventory transitions mandated by REACH plasticizer thresholds.
- Acrylic:High-clarity thermoplastic with UV stability for decorative exposed-edge applications requiring optical-grade finish.
- Melamine:Resin-impregnated paper substrate bonded to carrier film for heat-activated application in laminate-matched furniture systems.
- PP:Polypropylene grades offer chemical resistance for laboratory and healthcare furniture with aggressive cleaning protocols.
- PET:Polyester-based tapes align with mono-material recycling streams under EU Green Deal circular economy mandates.
PVC holds installed capacity across Asian compounding infrastructure. ABS is rotating up the share rankings among European specification offices.
Application:
Application segmentation maps directly to substrate exposure severity and moisture ingress risk profiles.
- Furniture Manufacturing:Bulk consumption segment absorbing majority of ABS and PVC tape volumes through automated edge banding machinery in particleboard-to-finished-goods ecosystems. China's integrated manufacturing clusters drive procurement scale with compressed specification cycles.
- Interior Decoration:Custom color matching and textured finish development command elevated per-meter margins through small-batch production runs. Digital colorimetric systems are compressing designer-to-converter specification timelines in European markets.
- Cabinet Making:Moisture-critical kitchen and bath applications requiring sub-0.4 mm thickness compatibility with high-speed application equipment.
- Door Frames:Structural edge sealing for engineered door cores with fire-rating compliance in commercial construction.
- Wall Panels:Large-surface cladding systems requiring continuous roll-fed tape application with minimal splice frequency.
- Countertops:High-wear horizontal surfaces demanding enhanced scratch resistance through modified acrylic or ABS topcoats.
Furniture Manufacturing anchors volume throughput. Interior Decoration is climbing the fastest in margin contribution per linear meter.
Thickness:
Thickness specification gates machinery compatibility and design minimalism possibilities across substrate categories.
- 0.3 mm:Ultra-thin profile enabling refined edge aesthetics in contemporary furniture design. Elevated cracking rates during high-speed application constrain adoption despite strong designer preference.
- 0.4 mm:Optimal balance of flexibility and durability for automated edge banding systems in North American carpentry workshops. Hot-melt adhesive activation achieves reliable bond strength without pre-heating equipment modification.
- 0.5 mm:Standard specification for general-purpose furniture with moderate wear exposure.
- 0.6 mm:Heavy-duty grade for commercial furniture and high-traffic interior applications.
- 0.7 mm:Maximum thickness for structural edge protection in industrial and laboratory furniture systems.
0.4 mm holds installed capacity across automated machinery fleets. 0.3 mm is gaining share fastest among European minimalist design studios.
End User:
Customer type segmentation reveals divergent procurement scale, technical service requirements, and specification authority concentration.
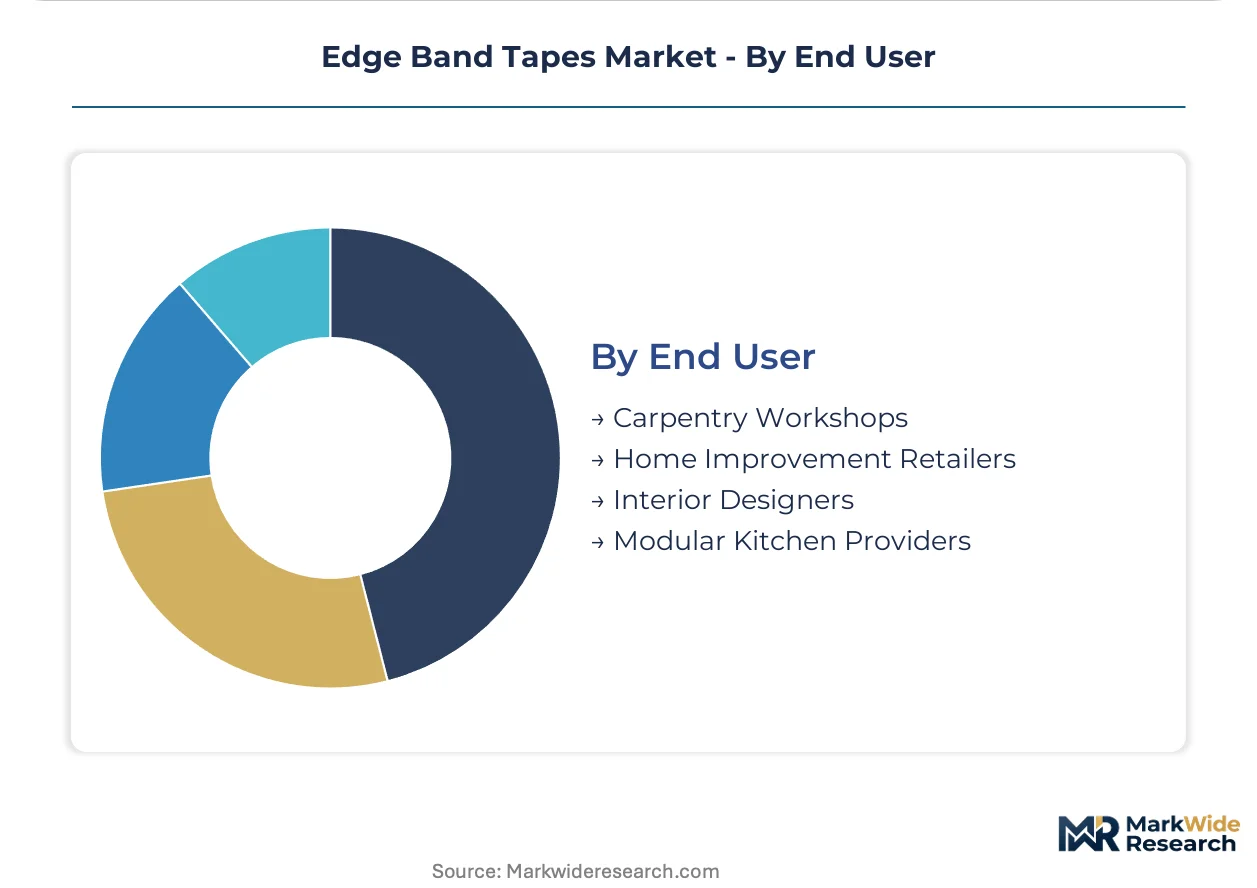
- Carpentry Workshops:Small-batch custom fabricators losing direct mill relationships as volume concentrates through pan-European retail chain procurement offices. E-procurement platforms are disintermediating traditional distributor layers for color-matched specialty orders.
- Modular Kitchen Providers:Consolidated specification authority driving centralized supplier qualification with dedicated technical service requirements. Benelux and Nordic markets exhibit highest concentration with two retail groups controlling majority distribution.
- Home Improvement Retailers:Big-box channels stocking standard-width rolls for DIY cabinet refacing and repair applications.
- Interior Designers:Specification influencers directing custom finish development through direct converter relationships for boutique residential projects.
Modular Kitchen Providers hold installed capacity through multi-year supply agreements. Carpentry Workshops are expanding share through digital distribution channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH mandates anchor European demand dynamics, while China's GB standards and US EPA guidelines create parallel compliance tracks that reshape procurement patterns across three dominant manufacturing geographies.
Germany
Modular kitchen providers in North Rhine-Westphalia and Bavaria are accelerating ABS procurement ahead of Q3 2025 REACH plasticizer thresholds. ECHA restrictions on DEHP and DINP migration are forcing wholesale formulation transitions across Cologne-area extrusion capacity. REHAU leverages its polymer compounding heritage near the Rhine-Ruhr industrial belt to sustain premium positioning.
China
Guangdong province furniture manufacturing clusters drive bulk consumption of ABS and PVC edge band tapes through integrated particleboard-to-finished-goods ecosystems. GB standards for indoor air quality shape domestic PVC specifications, particularly in Shenzhen and Dongguan export-processing zones. Shanghai Fujuan Group Co., Ltd. dominates Asian volume tiers with captive resin-to-tape manufacturing.
United States
North American carpentry workshops deploy automated edge banding machinery with hot-melt adhesive activation systems that compress application cycle times. EPA and OSHA guidelines govern VOC emissions during workshop fabrication, particularly in Southeast furniture manufacturing corridors. Doellken-Woodtape Inc. anchors regional availability through specialized distribution networks.
India
BIS certification requirements for indoor air quality are creating first-mover advantage for phthalate-free ABS suppliers establishing local compounding partnerships. Organized furniture retail penetration remains underdeveloped in Maharashtra and Gujarat industrial zones. Gdecor Industries India Private Limited exemplifies domestic specialists positioning for compliance-driven specification upgrades.
Edge Band Tapes Market Competitive Landscape
Capability concentration sits with integrated polymer compounders possessing resin-to-tape manufacturing control; scale advantage sits with high-volume Asian producers serving export furniture clusters. The vendor base stratifies across three tiers: European premium-grade specialists with REACH-compliant formulation expertise, Chinese integrated manufacturers with captive PVC resin supply, and regional distributors maintaining workshop-level technical service. Dominant competitive moves include backward integration into polymer compounding and dedicated key account technical service team deployment for pan-European retail chain qualification.
Among German-based compounders, REHAU represents the integrated premium-tier archetype with polymer heritage positioning. Chinese volume manufacturers include Shanghai Fujuan Group Co., Ltd., which exemplifies the resin-to-tape integrated model controlling Asian supply chains. North American distribution specialists such as Doellken-Woodtape Inc. occupy the regional availability anchor position for carpentry workshop procurement.
| Leading Market Players |
|---|
| Doellken-Woodtape Inc. |
| REHAU |
| E3 Panels |
| EdgeCo Incorporated |
| Veena Polymers |
| PRI Edgebanding |
| Shanghai Fujuan Group Co., Ltd. |
| Mobelkant |
| Gdecor Industries India Private Limited |
| Others |
Value Network & Pricing Analysis
Guangdong province's integrated resin-to-tape manufacturing clusters concentrate global PVC edge band capacity, translating captive polymer supply into pricing leverage over European distributors lacking backward integration. This geographic supply asymmetry compresses margins for converters dependent on spot resin markets while rewarding integrated Asian producers with cost-tier dominance.
Pricing Analysis
Asian-European price spreads widen during crude oil volatility cycles as Guangdong manufacturers absorb petrochemical input fluctuations through long-term resin offtake agreements. Three-tier pricing structure across premium REACH-compliant ABS, standard phthalate-free PVC, and economy-grade conventional PVC separates specification tiers. Cost compression in economy grades intensifies because fixed-price furniture contracts prevent pass-through of resin spikes. Modular kitchen providers exhibit lowest price sensitivity due to compliance-driven specification mandates, while independent carpentry workshops face acute margin pressure from distributor markups.
Supply Chain Analysis
Export-control regimes on advanced thermoplastic extrusion equipment limit technology transfer to emerging compounding facilities, constraining supply diversification outside established manufacturing corridors. Production gravity centers on China, Germany, and the United States, with raw material dependencies spanning PVC resin from ethylene crackers, ABS polymer from acrylonitrile-butadiene-styrene producers, and specialty pigment dispersions from chemical specialists. Single-source vulnerability concentrates in Asian polymer compounding where three integrated manufacturers control majority volume. Distribution runs through specialized technical distributors for workshop-level service and direct mill relationships for pan-European retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to residential construction permitting rebounds and kitchen renovation cycles. Furniture manufacturing output correlates directly with housing starts, creating predictable demand inflection points.
For Market Incumbents: Build formulation moats around REACH-compliant ABS grades ahead of Q3 plasticizer threshold enforcement. Secure backward integration into citrate-based plasticizer supply or transition capacity entirely to phthalate-free polymer streams. Laser-activated adhesive bonding technology threatens hot-melt equipment incumbents; pilot solvent-free bonding systems to virtualize capital requirements for distributed manufacturing partners.
For New Entrants and Emerging Players: Establish a beachhead in India's underpenetrated organized furniture retail through BIS-certified ABS compounding partnerships. Maharashtra and Gujarat industrial zones lack integrated resin-to-tape manufacturing, creating procurement gaps for compliant suppliers. Target modular kitchen providers with phthalate-free certification packages bundled with technical colorimetric support.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated compounders with resin supply control and REACH formulation expertise over pure-play distributors. Five-to-ten year viability hinges on circular economy mandate compliance for mono-material recycling compatibility. Watch for EU Green Deal recycling stream specifications as the inflection signal for premium-grade tape demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin pressure from crude oil derivative volatility. |
| REACH-Compliant Formulation Transition | Citrate-based plasticizer or ABS migration ahead of DEHP/DINP threshold deadlines secures European kitchen specification. |
| Laser-Activated Adhesive Pilot Programs | Solvent-free bonding virtualizes hot-melt equipment requirements for small-batch custom fabricators. |
| Direct-to-Fabricator Digital Distribution | E-procurement platforms disintermediate distributor layers for interior decoration color-matching orders. |
| Mono-Material Recycling Compatibility R&D | PET-grade development aligns with EU Green Deal circular economy mandates for post-consumer particleboard streams. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, polymer producer SEC filings, and ECHA regulatory submissions. Primary interviews engaged tape converter plant managers, modular kitchen procurement leads, furniture OEM technical directors, and distribution channel partners across Germany, China, and the United States. Secondary validation drew from customs/trade databases, REACH compliance registries, and industry association capacity surveys. Bottom-up volume modeling triangulated against top-down market sizing from polymer consumption trends.
Forecast inputs span material type segmentation across PVC, ABS, acrylic, melamine, PP, and PET grades; application segmentation through furniture manufacturing, interior decoration, cabinet making, and countertop sealing; and thickness specifications from 0.3 mm to 0.7 mm. End-user segmentation differentiates carpentry workshops, modular kitchen providers, and home improvement retailers. CAGRs derive from regression analysis of housing starts correlation, polymer price elasticity, and regulatory compliance adoption curves.
Sensitivities concentrate around ECHA plasticizer threshold revisions, crude oil derivative price spikes, and Chinese GB standard tightening for indoor air quality. Forecasts reflect documented assumptions on residential construction cycle timing and REACH enforcement adherence. Material shifts in EU circular economy recycling stream specifications or REACH plasticizer migration thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Aluminum Foil Tape Market
Tapes
Electronic Pressure Sensitive Tape Dispenser Market
Tapes
Global Construction Tape Market
Tapes
Asia-Pacific Packaging Tapes Market
Tapes
Hydrocolloid Tapes Market
Tapes
Paper Tapes Market
Tapes
Pipe Marking Tape Market
Tapes
Unsupported Single Coated Tape Market
Tapes
Double Coated Film Tapes Market
Tapes
Foam Tape Market
Tapes
Tabbing Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Thermal Release Tapes Market
Tapes
Correction Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Thermoplastic Tape Market