
 Global Seam Sealing Tapes Market | 2026-2036
Global Seam Sealing Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Seam Sealing Tapes Market Foresight
Direct-to-contractor channels is reconfiguring how seam sealing tapes reach end users in construction and marine sectors. Henkel leverages its adhesive chemistry portfolio to sustain technical leadership in polyurethane formulations. Bemis Associates anchors North American supply through specialized hot-melt coating capabilities for protective clothing applications. DingZing Advanced Materials competes on flexible manufacturing scale across Asia-Pacific industrial zones.
Seam sealing tapes are pressure-sensitive adhesive strips, typically 15-50mm wide, composed of synthetic rubber or acrylic polymers laminated to thermoplastic polyurethane or polyolefin backings, engineered to create watertight and airtight bonds at fabric or membrane joints. Their primary purpose is to prevent moisture ingress in critical barrier assemblies ranging from building wraps to immersion suits. Polyurethane tape commands the dominant value share due to superior hydrostatic resistance and compatibility with coated textiles, while silicone tape represents the fastest-expanding category driven by thermal stability requirements in HVAC duct sealing. Among end user industries, protective gear manufacturers concentrate margin pools through certification-dependent procurement and long qualification cycles.
FDA standards govern skin-contact applications in medical protective clothing, while REACH restricts phthalate and solvent content in European tape formulations, and China's GB standards mandate VOC thresholds in construction-grade adhesives. These frameworks elevate compliance costs but also consolidate demand around certified suppliers with documented material safety data. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation requirements and qualification timelines.
Market Dynamics
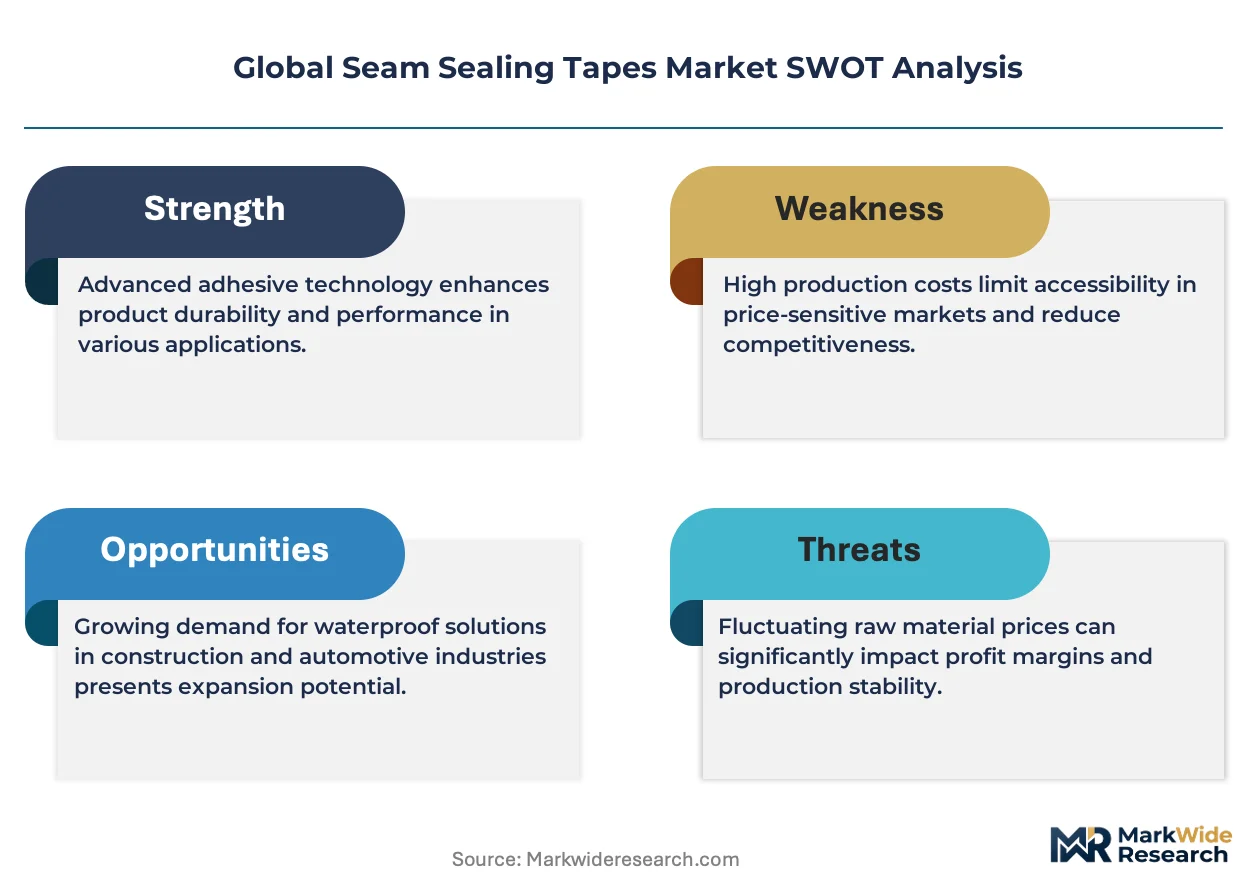
REACH compliance deadlines and China's evolving GB standards are forcing simultaneous reformulation across polyurethane adhesive portfolios, compressing supplier qualification timelines and consolidating procurement around certified compounders with documented material safety data.
Growth Catalysts
- Outdoor Apparel Expansion:Bonded seam construction is displacing stitched alternatives in waterproof performance wear, with manufacturers in Germany's Heidenheim technical textile cluster scaling automated tape application lines.
- REACH Chemical Restrictions:Phthalate and solvent limits in European tape formulations are elevating demand for compliant polyurethane systems with verified safety documentation.
- HVAC Thermal Stability Requirements:Silicone tape formulations are capturing specification share in duct sealing applications where temperature cycling exceeds polyurethane performance thresholds.
Market Restraints
- Petrochemical Input Volatility:Thermoplastic polyurethane resin prices fluctuate with crude oil derivatives, compressing margins for converters without long-term supply agreements.
- Specialized Coating Equipment Concentration:Hot-melt lamination lines require capital-intensive precision coating capabilities concentrated among a limited supplier base in North America and Western Europe.
- Acrylic Substitution in Cost-Sensitive Construction:Lower-performance acrylic tapes compete on price in building wrap applications where hydrostatic resistance requirements are minimal.
Strategic Opportunities
- Medical Protective Clothing Certification:FDA skin-contact standards create a qualified supplier moat for tape manufacturers with biocompatibility testing infrastructure.
- China's Dual Carbon Goals:VOC thresholds under GB standards and provincial emissions trading schemes favor water-based adhesive systems with lower solvent content.
- Direct-to-Contractor Distribution:Marine and construction sectors are bypassing traditional distributor layers through specialized technical sales channels with application engineering support.
Industry Challenges
- Adhesive Chemist Talent Scarcity:Formulation expertise in pressure-sensitive polyurethane systems remains concentrated among aging technical specialists with limited knowledge transfer pipelines.
- Multi-Jurisdiction Qualification Timelines:Simultaneous compliance with REACH, FDA, and GB standards extends product launch cycles by 18-24 months for global protective gear suppliers.
- Legacy Equipment Integration:Automated tape application systems in apparel manufacturing require retrofitting existing cut-and-sew lines with heat-sealing stations and precision tension controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Seam Sealing Tapes Market |
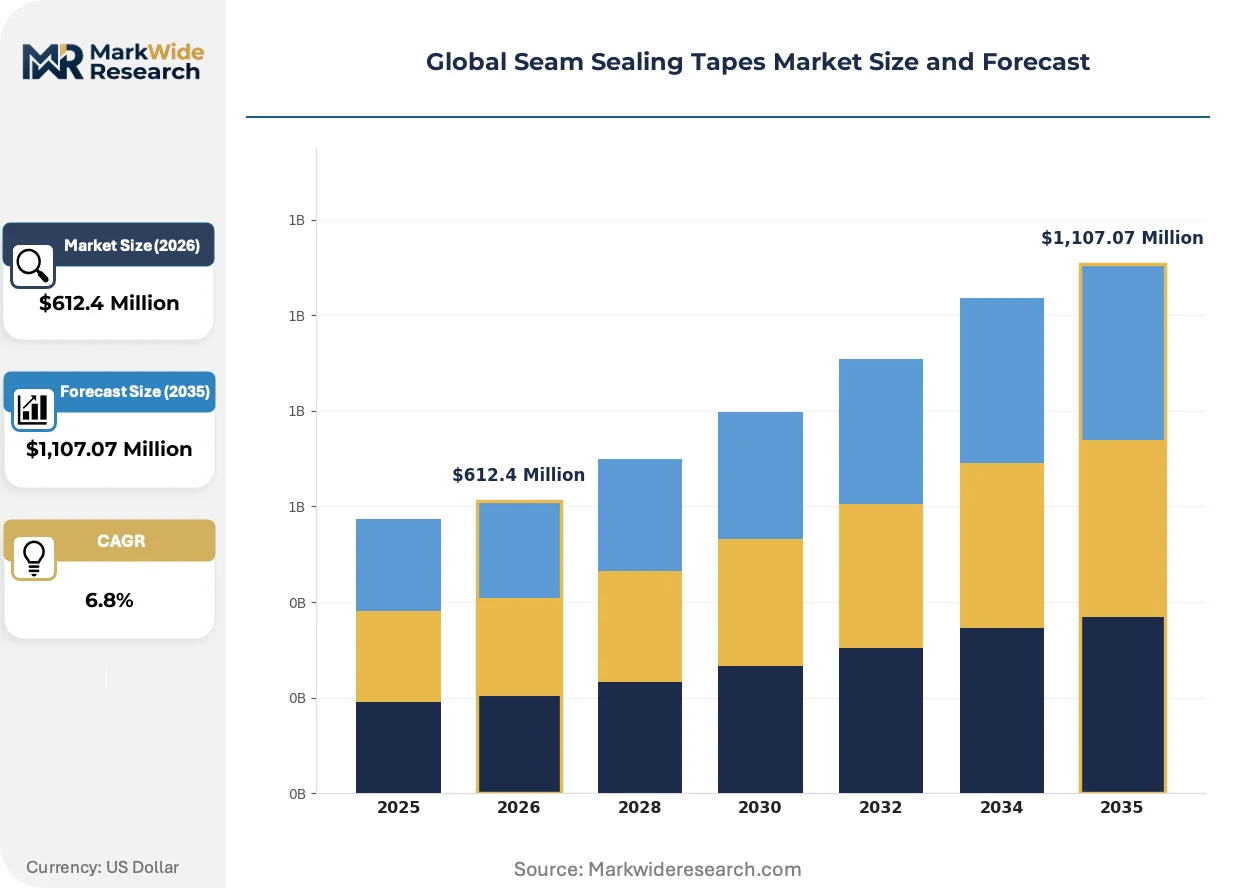
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Butyl Tape, Acrylic Tape, Rubberized Tape, Silicone Tape, Polyurethane Tape Application: Building Envelope, HVAC Systems, Protective Clothing, Automotive Components, Marine Equipment End User Industry: Construction Contractors, HVAC Technicians, Protective Gear Manufacturers, Vehicle Assemblers, Shipbuilders Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Specialty Retailers, Industrial Suppliers |
| Companies Covered | Henkel, Avery Dennison, 3M, Nitto Denko Corporation, Himel Corp, Bemis Associates, Sika AG, DingZing Advanced Materials, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Seam Sealing Tapes Market Shifts & Advancements
Digital specification platforms and predictive adhesion modeling are compressing the traditional trial-and-error product development cycle, while regulatory divergence between jurisdictions is fragmenting formulation strategies.
Reactive hot-melt polyurethane systems with moisture-cure functionality are virtualizing the conventional solvent-based coating process. Marine immersion suit manufacturers in Norway and commercial fishing gear producers in Japan are specifying these systems for seam durability under cyclic loading. This technology is virtualizing the capital requirements for new market entrants by eliminating solvent recovery infrastructure and emissions control investments.
China's GB standards for construction-grade adhesives now mandate VOC thresholds that exceed prior voluntary certification levels. Tape converters serving building envelope applications must reformulate or source compliant base polymers from certified compounders. Zhejiang province industrial zones are responding fastest due to proximity to domestic resin suppliers with water-based polyurethane capabilities.
Specification authority is migrating from brand marketing departments to technical procurement teams with materials engineering backgrounds. Outdoor apparel manufacturers now require documented hydrostatic resistance testing and accelerated aging data before supplier qualification. This shift is most visible in Germany's technical textile cluster and among Japanese workwear brands with stringent quality protocols.
Global Seam Sealing Tapes Market Segmentation
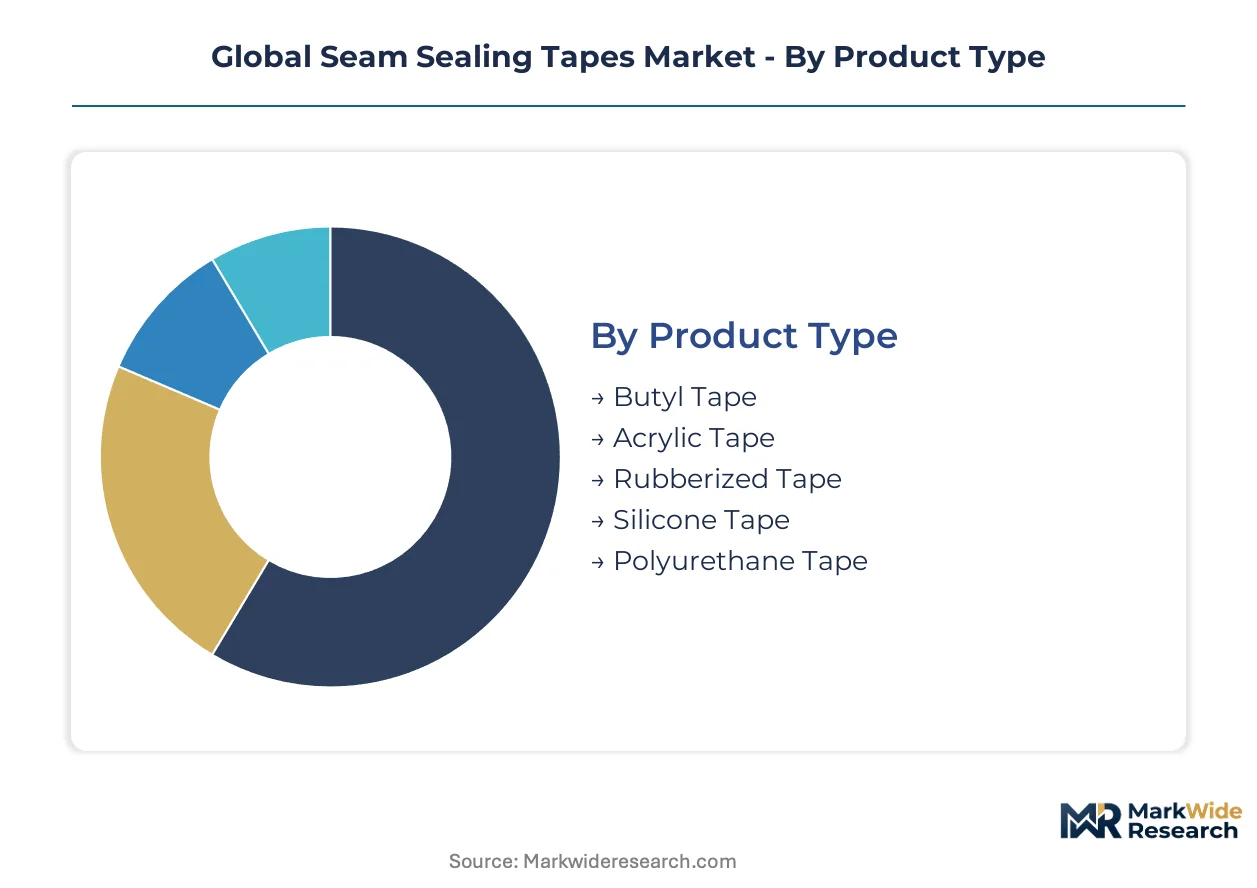
Seam sealing tape manufacturers configure product portfolios around distinct performance thresholds and application environments. Each segmentation axis reveals where margin pools concentrate and where commoditization pressures intensify.
Product Type:
Use-case spectrum spans temporary weatherproofing to permanent immersion-grade sealing, with chemistry selection determining hydrostatic resistance and thermal tolerance.
- Polyurethane Tape:Thermoplastic polyurethane backings laminated with pressure-sensitive adhesives deliver superior hydrostatic resistance for coated textiles. German technical textile manufacturers in the Heidenheim cluster specify these systems for bonded seam construction in waterproof performance apparel.
- Silicone Tape:Silicone polymer formulations withstand temperature cycling from -60°C to 200°C without adhesive degradation. HVAC duct sealing applications in Japan and the United States specify silicone tapes where polyurethane performance thresholds fail under thermal stress.
- Butyl Tape:Synthetic rubber compositions provide conformable sealing for irregular substrates in building envelope applications.
- Acrylic Tape:Lower-cost formulations compete on price in construction-grade moisture barriers with minimal hydrostatic requirements.
- Rubberized Tape:Natural and synthetic rubber blends serve general-purpose industrial sealing with moderate chemical resistance.
Established volume favors polyurethane systems; emerging adoption favors silicone formulations.
Application:
End-use environments impose divergent certification requirements and performance validation protocols.
- Protective Clothing:FDA skin-contact standards and REACH chemical restrictions govern tape selection for medical and industrial protective gear. Manufacturers face 18-24 month qualification cycles combining biocompatibility testing with material safety documentation.
- Building Envelope:China's GB standards mandate VOC thresholds for construction-grade adhesives that exceed prior voluntary levels. Zhejiang province tape converters reformulate with water-based polyurethane systems to maintain market access.
- HVAC Systems:Thermal stability requirements in duct sealing favor silicone formulations for high-temperature cycling environments.
- Marine Equipment:Immersion suit manufacturers in Norway and commercial fishing gear producers in Japan specify reactive hot-melt systems for seam durability under cyclic loading.
- Automotive Components:Interior and exterior sealing applications demand compatibility with varied substrate chemistries and assembly line heat-sealing equipment.
Certification-dependent procurement dominates protective clothing; cost-sensitive specification prevails in building envelope.
End User Industry:
Customer technical sophistication determines whether procurement prioritizes documented performance data or unit economics.
- Protective Gear Manufacturers:Long qualification cycles and certification dependencies create qualified supplier moats. Technical procurement teams with materials engineering backgrounds now control specification authority, demanding hydrostatic resistance testing and accelerated aging data.
- Construction Contractors:Direct-to-contractor distribution channels are bypassing traditional distributor layers in marine and building sectors. Application engineering support differentiates suppliers in this price-sensitive segment.
- HVAC Technicians:Field installation requirements favor tapes with immediate tack and conformability to irregular duct geometries.
- Vehicle Assemblers:OEM integration demands compatibility with automated tape application systems and existing assembly line heat-sealing stations.
- Shipbuilders:Marine classification society approvals govern tape selection for watertight bulkhead and deck sealing applications.
Technical procurement consolidation favors protective gear manufacturers; price transparency pressures construction contractors.
Distribution Channel:
Channel selection reflects the trade-off between technical support intensity and logistics cost minimization.
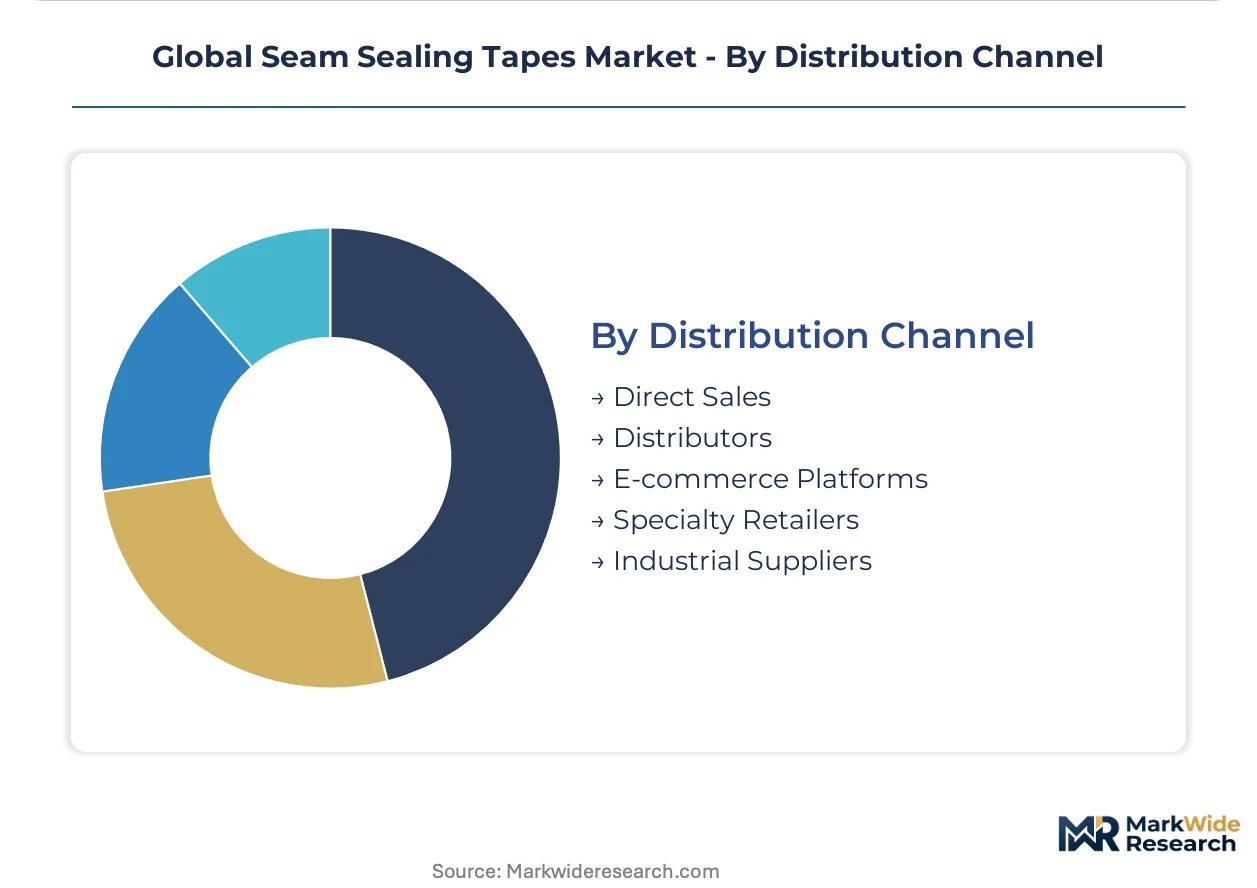
- Direct Sales:Specialized technical sales channels with application engineering support serve marine and construction sectors requiring heat-sealing parameter optimization. Henkel and Bemis Associates deploy direct teams for protective clothing and automotive accounts.
- Distributors:Traditional industrial distribution maintains position in geographic markets where localized inventory and credit terms outweigh technical service value.
- E-commerce Platforms:Standardized product configurations with published technical data sheets enable self-service procurement for maintenance and repair operations.
- Specialty Retailers:Outdoor apparel aftermarket sales concentrate in channels serving recreational users with consumer-packaged formats.
- Industrial Suppliers:Integrated MRO distributors compete on procurement consolidation for multi-site construction and manufacturing operations.
Technical complexity favors direct sales; standardization favors e-commerce penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance deadlines and China's evolving GB standards are forcing simultaneous reformulation across adhesive portfolios, compressing supplier qualification timelines and consolidating procurement around certified compounders with documented material safety data.
Germany
Technical textile manufacturers in the Heidenheim cluster drive bonded seam construction for waterproof performance apparel. ECHA's REACH restrictions on phthalate and solvent content elevate demand for compliant polyurethane systems with verified safety documentation. Stuttgart-based material suppliers coordinate automated tape application line deployments across the Baden-Württemberg industrial corridor.
China
Provincial emissions trading schemes and dual carbon goals favor water-based adhesive systems with lower solvent content. GB standards for construction-grade adhesives now mandate VOC thresholds exceeding prior voluntary certification levels. Zhejiang province tape converters reformulate fastest due to proximity to domestic resin suppliers with water-based polyurethane capabilities.
United States
Marine immersion suit manufacturers and commercial fishing gear producers specify reactive hot-melt systems for seam durability under cyclic loading. FDA skin-contact standards govern tape selection for medical protective clothing, creating qualified supplier moats. Minnesota-based converters serve HVAC duct sealing applications where thermal stability requirements favor silicone formulations.
Japan
Workwear brands with stringent quality protocols now require documented hydrostatic resistance testing and accelerated aging data before supplier qualification. METI industrial standards influence adhesive formulation requirements for protective gear exports. Osaka-area technical procurement teams with materials engineering backgrounds control specification authority for domestic apparel manufacturers.
Norway
Marine immersion suit manufacturers specify reactive hot-melt polyurethane systems with moisture-cure functionality for seam durability under North Sea conditions. EU regulatory alignment ensures REACH compliance for export-oriented production. Bergen-area producers coordinate with German technical textile clusters on bonded seam construction standards for commercial fishing gear.
Global Seam Sealing Tapes Market Competitive Landscape
On the supply side, the industry is consolidating around adhesive chemistry specialists with documented material safety data and certified polyurethane formulation capabilities. Three strategic archetypes dominate: diversified chemical conglomerates with pressure-sensitive adhesive portfolios, specialized tape converters with hot-melt coating capabilities, and regional compounders serving proximity markets with flexible manufacturing scale. Competitive moves center on vertical integration into base polymer supply and direct-to-contractor distribution channel expansion with application engineering support.
Among diversified chemical conglomerates, Henkel and Avery Dennison occupy positions anchored by broad adhesive chemistry portfolios and established protective clothing account relationships. Bemis Associates exemplifies the specialized converter archetype with concentrated North American hot-melt coating capabilities. DingZing Advanced Materials represents the Asia-Pacific regional compounder model with manufacturing scale across industrial zones in China and Taiwan. These three anchors illustrate how qualification-dependent procurement in medical and protective gear segments rewards suppliers with biocompatibility testing infrastructure and multi-jurisdiction compliance documentation.
| Leading Market Players |
|---|
| Henkel |
| Avery Dennison |
| 3M |
| Nitto Denko Corporation |
| Himel Corp |
| Bemis Associates |
| Sika AG |
| DingZing Advanced Materials |
| Toray Industries |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight volatility cascades through thermoplastic polyurethane resin costs, amplifying margin compression for converters without long-term supply agreements while concentrating procurement power among certified compounders with documented material safety data.
Pricing Analysis
Certification level (FDA/REACH/GB-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across premium, standard, and economy levels reflects qualification-dependent procurement in protective gear versus cost-sensitive construction specification. Price erosion runs through economy-tier acrylic tapes as Chinese converters compete on unit economics for building wrap applications. Construction contractors exhibit highest price sensitivity; medical protective clothing manufacturers prioritize biocompatibility documentation over per-meter cost.
Supply Chain Analysis
Extended payment terms from German automotive and marine OEMs strain working capital for Zhejiang province tape converters. Supply concentrates in Germany's Heidenheim technical textile cluster, China's Zhejiang industrial zones, and Minnesota-based coating operations. Base polymer sourcing draws from domestic Chinese resin suppliers, European petrochemical complexes, and Japanese specialty chemical producers. Single-source vulnerability looms for moisture-cure reactive hot-melt formulations where qualified compounders remain limited. Distribution runs through direct technical sales channels for protective clothing and marine applications, with traditional industrial distribution serving geographic markets requiring localized inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in pressure-sensitive polyurethane systems remains anchored among aging technical specialists with limited knowledge transfer pipelines, constraining supplier expansion and consolidating competitive advantage around incumbents with captive R&D talent.
For Market Incumbents: Harden qualification moats by deepening biocompatibility testing infrastructure for FDA skin-contact applications and securing backward integration into water-based polyurethane resin supply. Acrylic substitution in cost-sensitive construction segments threatens margin pools; respond with application engineering support that justifies premium positioning through documented hydrostatic resistance performance. For New Entrants and Emerging Players: Southeast Asian marine equipment manufacturing presents underpenetrated demand for reactive hot-melt systems with moisture-cure functionality. Bypass established distributor layers through direct-to-contractor channels with heat-sealing parameter optimization services, targeting Norwegian immersion suit producers and Japanese commercial fishing gear manufacturers seeking alternatives to incumbent supply. For Investors and Strategic Acquirers: REACH compliance deadlines reshaping the acquisition landscape favor targets with documented material safety data and multi-jurisdiction qualification experience. Five-to-ten year viability hinges on water-based adhesive capabilities aligned with China's dual carbon goals and provincial emissions trading schemes. Monitor GB standard evolution for construction-grade VOC thresholds as the signal for consolidation timing among Zhejiang province converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Polymer Supply | Captive sourcing of water-based polyurethane resins secures compliance with China's GB VOC mandates. |
| Biocompatibility Testing Infrastructure Investment | FDA skin-contact certification creates qualified supplier moats in medical protective clothing procurement. |
| Direct-to-Contractor Channel Expansion | Application engineering support differentiates suppliers in marine and construction sectors bypassing distributors. |
| Reactive Hot-Melt Coating Capacity Addition | Moisture-cure systems eliminate solvent recovery infrastructure for entrants targeting immersion-grade applications. |
| Multi-Jurisdiction Compliance Documentation | Simultaneous REACH, FDA, and GB qualification accelerates product launch cycles for global protective gear suppliers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA regulatory filings, Chinese GB standard documentation, customs trade data, and SEC disclosures from adhesive chemistry specialists. Primary interviews engaged technical procurement managers at German outdoor apparel manufacturers, plant engineers at Zhejiang province tape converters, R&D directors at polyurethane compounders, and marine classification society surveyors. Bottom-up segmentation analysis triangulates against top-down macroeconomic indicators across the analysis window.
Forecast inputs include adhesive chemistry substitution rates, regulatory compliance cost trajectories, and automated tape application line deployment schedules. Modeled dimensions span product type (polyurethane, silicone, butyl, acrylic), application environment (protective clothing, building envelope, HVAC, marine, automotive), and end-user technical sophistication. CAGRs derive from segment-level volume builds validated against regional production capacity and downstream demand indicators including Heidenheim cluster expansion plans and China's dual carbon implementation pace.
Practitioners should monitor petrochemical input volatility, REACH reformulation deadlines, and GB standard enforcement intensity for early signals of margin compression or qualification timeline extension. Forecasts reflect assumptions regarding continued bonded seam displacement of stitched alternatives and sustained regulatory divergence between jurisdictions. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Foam Tape Market
Tapes
Global Surface Protection Tapes Market
Tapes
Cable Wrapping Tapes Market
Tapes
Filmic Tapes Market
Tapes
Global Construction Tape Market
Tapes
Dicing Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Pouch Tapes Market
Tapes
Pre-Printed Tape Market
Tapes
Flatback Tapes Market
Tapes
Building and Construction Tapes Market
Tapes
Masking Tape Market
Tapes
Gummed Tapes Market
Tapes
Cloth Self-Adhesive Tapes Market
Tapes
Tear Tape Dispenser Market