
 Orbital Wrapping Machine Market | 2026-2036
Orbital Wrapping Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Orbital Wrapping Machine Market Insights
The EU Green Deal is consolidating demand for orbital wrapping machines that minimize stretch film consumption per pallet load. Lantech leverages servo-driven pre-stretch technology to reduce material waste. Robopac anchors its European position with ring-wrap systems designed for high-throughput distribution centers. Orion Packaging Systems LLC competes through modular turntable configurations that adapt to variable load dimensions.
An orbital wrapping machine rotates a dispensing arm or ring around a stationary load to apply tensioned stretch film, typically achieving 200-300% pre-stretch ratios to secure palletized goods for transport and storage. Fully automatic systems lead unit shipments as labor costs rise across logistics and warehousing applications, while rotary arm technology captures premium pricing due to its compatibility with unstable or lightweight loads. Semi-automatic configurations retain share among small and mid-sized packaging companies where throughput requirements remain moderate.
The EU F-Gas Regulation and REACH compliance frameworks govern film material composition and machinery energy efficiency across European installations. OSHA guidelines in the United States mandate guarding and emergency stop protocols that influence rotary arm design specifications. Germany's KBA and France's ANSM coordinate with ECHA on chemical safety assessments for adhesive-backed films used in cold storage applications. Stakeholders must monitor evolving extended producer responsibility schemes that could shift total cost of ownership calculations toward film-recovery integrated systems.
Market Dynamics
E-commerce fulfillment networks are driving capital deployment toward fully automatic orbital wrapping systems as labor availability tightens across warehousing clusters. The EU Green Deal's packaging waste directives are compressing acceptable film thicknesses, forcing equipment retrofits and accelerating replacement cycles in European installations.
Growth Catalysts
- EU F-Gas Regulation compliance:Cold storage operators in Germany and France are upgrading to machines with sealed film-dispensing systems to meet fluorinated gas containment standards.
- Stretch film chemistry advances:Metallocene-based films enable 300% pre-stretch ratios, reducing material consumption per pallet and justifying premium equipment pricing.
- Third-party logistics concentration:Consolidation among European 3PL providers is standardizing fleet specifications around rotary-arm configurations for mixed-load handling.
Market Restraints
- Steel and aluminum price volatility:Turntable and rotary arm fabrication costs fluctuate with commodity inputs, compressing margins for mid-tier equipment manufacturers.
- Technical limitation in lightweight load stability:Orbital wrapping generates centrifugal forces that destabilize loads below 15 kilograms, restricting adoption in electronics fulfillment.
- Substitution threat from shrink bundling:Heat-shrink systems capture applications where 360-degree wrap coverage is unnecessary, particularly in beverage distribution.
Strategic Opportunities
- India warehousing modernization:Cold chain infrastructure investments under the PLI scheme are creating first-time demand for automated wrapping in pharmaceutical distribution.
- Film-recovery integration:Extended producer responsibility frameworks in France and Italy are incentivizing equipment with built-in film collection and baling systems.
- Convergence of IoT sensors and predictive maintenance:Real-time tension monitoring and motor diagnostics enable service-contract monetization for equipment fleets.
Industry Challenges
- Mechatronics technician shortage:Servo-driven pre-stretch systems require specialized calibration expertise that remains scarce in regional service networks.
- CE marking timeline compression:Machinery Directive conformity assessments for modified rotary-arm designs now average 14 months, delaying product launches.
- Legacy WMS integration friction:Warehouse management system protocols from the 2000s lack API compatibility with modern wrapping machine control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Orbital Wrapping Machine Market |
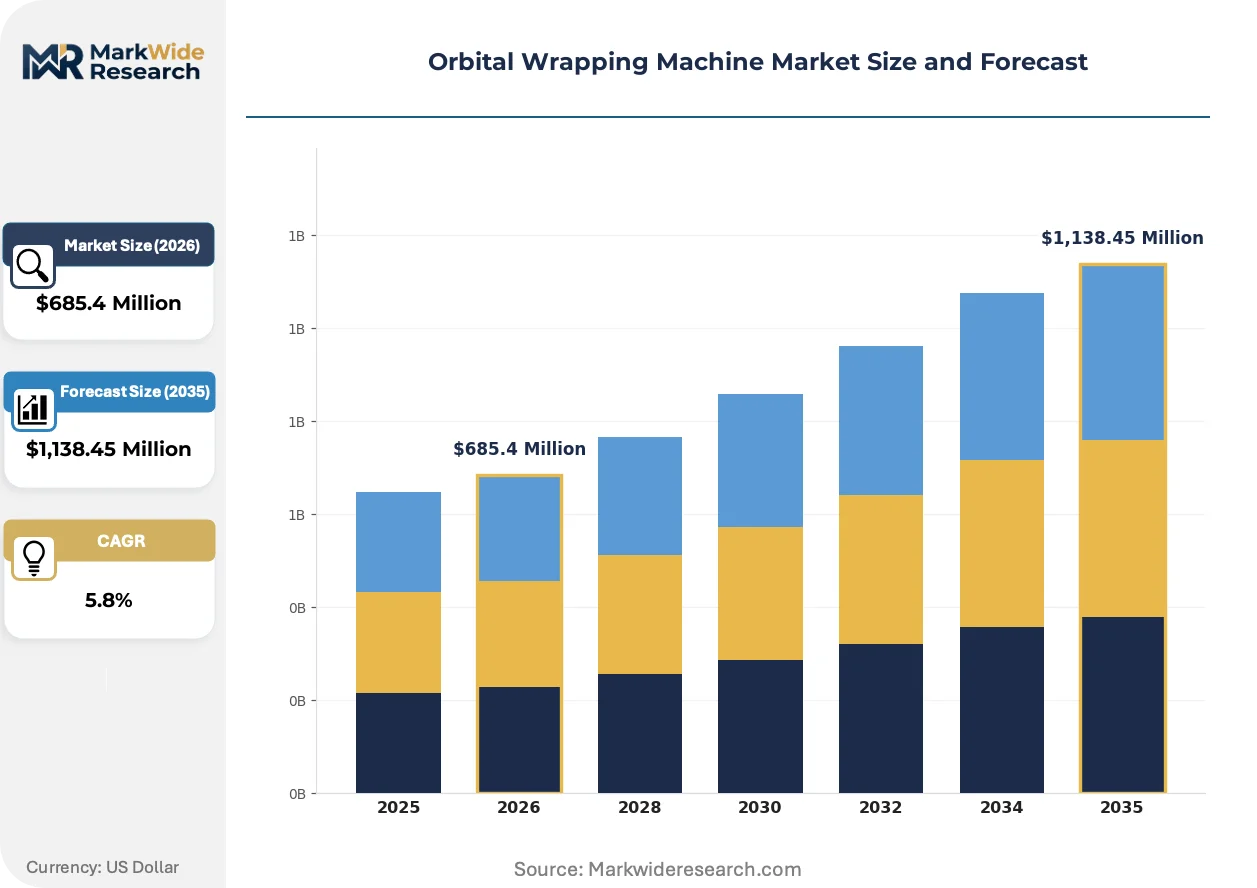
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semi-Automatic, Fully Automatic, Manual, Portable Technology: Rotary Arm, Ring Wrap, Turntable, Stretch Film Application: Logistics & Warehousing, Manufacturing Units, Export Packaging, Distribution Centers, Cold Storage End User: Third-Party Logistics Providers, Packaging Companies, E-Commerce Operators, Industrial Manufacturers |
| Companies Covered | Lantech, Orion Packaging Systems LLC, Robopac, Wulftec International, Movitec Wrapping Systems SL, Pieri, Messersì Packaging S.r.l., Reisopack, Sotemapack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Orbital Wrapping Machine Market Trends and Innovations
Servo-driven pre-stretch technology is compressing the performance gap between mid-tier and premium equipment tiers. Regulatory pressure on film waste is accelerating hardware-software convergence in European installations. Buyer procurement patterns are shifting from capital purchase to performance-based service agreements.
Brushless servo motors with integrated encoders are consolidating control precision in high-throughput rotary arm systems. German automotive parts distributors are adopting these configurations for just-in-sequence logistics. The technology is consolidating supplier power among motion-control specialists who can deliver sub-millimeter film tension accuracy.
REACH compliance for adhesive-backed stretch films is tightening chemical disclosure requirements across European cold storage networks. Machinery OEMs must now certify that film-contact surfaces do not leach restricted substances during temperature cycling. French pharmaceutical logistics operators are responding by specifying stainless-steel film paths and documented material traceability.
Fleet operators are unbundling equipment ownership from maintenance responsibility, contracting wrapping performance per pallet instead. Third-party logistics providers in the Netherlands and Belgium are leading this transition, replacing capex budgets with unit-cost accounting. Pharmaceutical distribution centers exhibit the strongest preference for outcome-based arrangements due to validation documentation requirements.
Orbital Wrapping Machine Market Segmentation
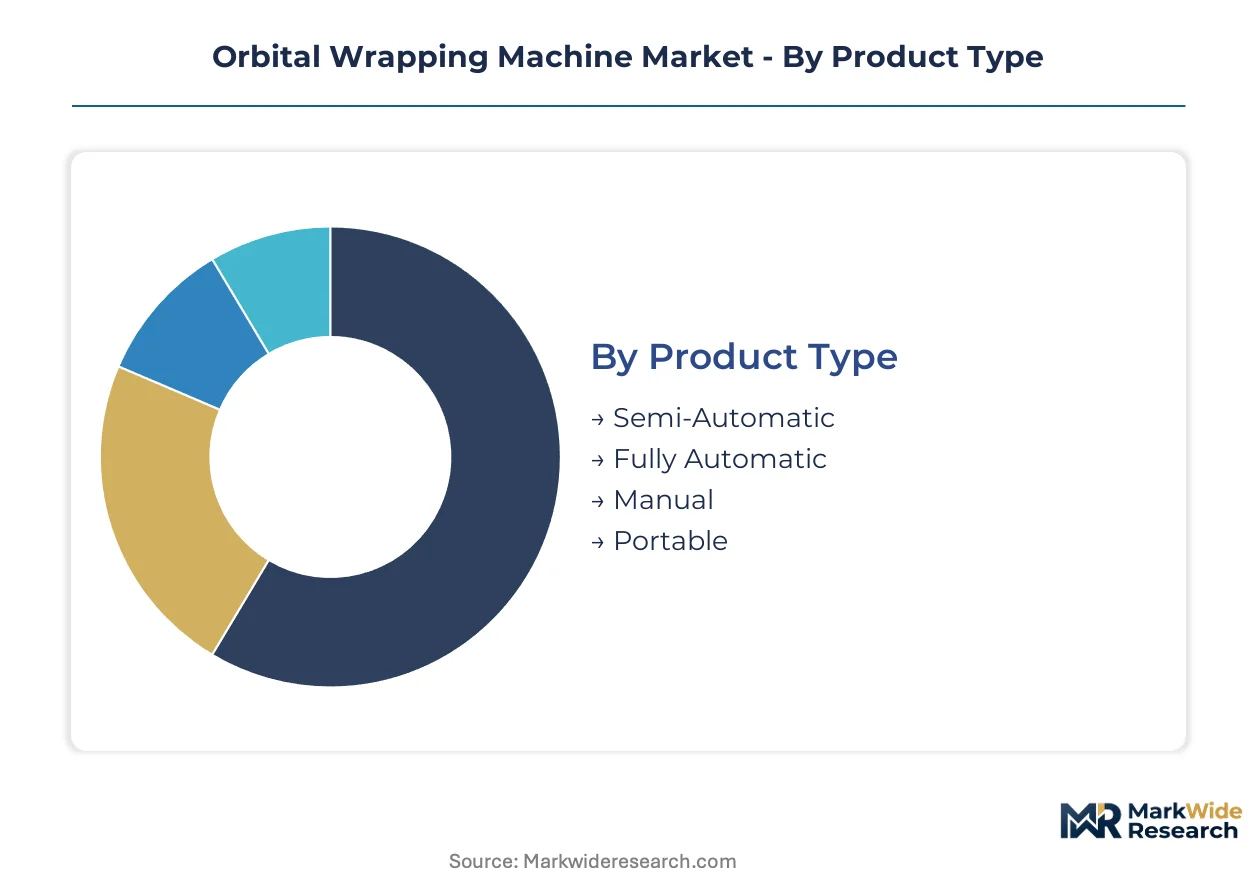
Segmentation in orbital wrapping machines reflects divergent capital intensity and integration requirements across logistics networks. Equipment specifications vary sharply between standalone warehouse installations and embedded production-line configurations. Understanding these divides clarifies procurement patterns and service-model opportunities.
Product Type:
Standalone systems dominate warehouse floors where pallet throughput justifies dedicated equipment, while embedded configurations integrate with conveyor networks in high-volume manufacturing environments.
- Fully Automatic:Servo-driven pre-stretch systems with automated film cutting and clamping eliminate operator intervention. Third-party logistics providers in the Netherlands and Belgium are standardizing fleet specifications around these configurations for 24-hour distribution operations.
- Semi-Automatic:Requires manual pallet placement and film attachment, with automated wrapping cycles. Packaging companies in Germany's industrial corridor favor these units where throughput remains below 40 pallets per hour and labor costs permit hybrid operation.
- Manual:Hand-cranked or push-type dispensers for low-volume applications. Small export packers in regional French logistics clusters use these for irregular shipment schedules.
- Portable:Mobile units with battery-powered film dispensing for field service and remote warehousing. Cold storage operators in India deploy these for pharmaceutical distribution where fixed infrastructure remains under development.
Volume placements concentrate in fully automatic systems; the faster expansion belongs to portable configurations.
Technology:
Cost tiers separate premium motion-control architectures from mechanical systems, with price differentials reflecting precision requirements and throughput specifications.
- Rotary Arm:The wrapping arm rotates around stationary loads, eliminating turntable weight constraints. German automotive parts distributors specify these for just-in-sequence logistics where unstable or lightweight loads exceed 15 kilograms.
- Turntable:Rotating platform designs with palletized loads turning beneath fixed film carriages. Manufacturing units in France's pharmaceutical corridors favor modular turntable configurations that adapt to variable load dimensions.
- Ring Wrap:Continuous ring systems achieving highest throughput for uniform pallet dimensions. High-throughput distribution centers in Belgium anchor European adoption of these configurations.
- Stretch Film:Film-dispensing subsystems integrated into broader packaging lines. E-commerce operators in German urban logistics clusters embed these within automated material handling systems.
Shipments concentrate in turntable designs; the steepest expansion trajectory belongs to rotary arm systems.
Application:
Geographic clustering shapes demand, with specific logistics corridors driving specification requirements and compliance burdens.
- Logistics & Warehousing:General-purpose pallet stabilization for storage and transport. E-commerce fulfillment networks across Germany and France are driving capital deployment toward fully automatic systems as labor availability tightens.
- Cold Storage:Temperature-controlled environments requiring sealed film-dispensing systems. Operators in Germany and France upgrade equipment to meet EU F-Gas Regulation compliance for fluorinated gas containment.
- Manufacturing Units:Production-line integration with conveyor systems. Industrial manufacturers in Germany's automotive belt specify rotary arm compatibility with just-in-sequence delivery protocols.
- Distribution Centers:Mixed-load handling with variable pallet dimensions. Third-party logistics consolidation across Europe is standardizing fleet specifications around adaptable configurations.
- Export Packaging:Heavy-duty wrapping for ocean and air freight. French pharmaceutical logistics operators specify stainless-steel film paths and REACH-compliant material traceability for temperature-cycling resilience.
Installed base concentrates in logistics and warehousing; the fastest share gain belongs to cold storage applications.
End User:
Customer type determines procurement modality, with capital purchase, leasing, and performance-based service agreements segmenting the buyer landscape.
- Third-Party Logistics Providers:Fleet operators unbundling equipment ownership from maintenance responsibility. Dutch and Belgian 3PLs are replacing capex budgets with unit-cost accounting and outcome-based wrapping performance contracts.
- E-Commerce Operators:Fulfillment network operators with high-throughput, variable-load requirements. These buyers are expanding fleet purchases of fully automatic systems across European warehousing clusters.
- Industrial Manufacturers:Production-integrated wrapping for outbound shipment preparation. German automotive and machinery producers specify equipment with API-compatible control architectures for warehouse management system integration.
- Packaging Companies:Service providers offering contract wrapping and equipment rental. Mid-sized packaging companies in regional French markets retain semi-automatic configurations where throughput requirements remain moderate.
Procurement volume concentrates among third-party logistics providers; the most rapid contract expansion belongs to e-commerce operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruhr industrial corridor warehouses anchor European demand for orbital wrapping systems, with Germany's logistics automation investments setting procurement standards that neighboring markets adopt.
Germany
Automotive parts distributors in Stuttgart and Munich specify rotary-arm configurations for just-in-sequence logistics. KBA coordinates with ECHA on chemical safety assessments for cold storage film applications. The Rhine-Ruhr logistics cluster drives fleet standardization among third-party logistics providers upgrading to fully automatic systems.
France
Pharmaceutical distribution centers in Lyon and Paris prioritize REACH-compliant stainless-steel film paths for temperature-cycling resilience. ANSM enforces chemical disclosure requirements for adhesive-backed stretch films. The Île-de-France warehousing corridor concentrates demand for sealed film-dispensing systems meeting EU F-Gas Regulation standards.
Netherlands
Rotterdam port logistics operators unbundle equipment ownership through performance-based wrapping contracts per pallet. The national extended producer responsibility framework incentivizes film-recovery integrated systems. Eindhoven distribution clusters lead European adoption of IoT-enabled predictive maintenance service agreements.
Belgium
Antwerp distribution centers anchor European adoption of ring-wrap systems for uniform pallet dimensions. The country's dense third-party logistics consolidation standardizes fleet specifications around high-throughput configurations. Flemish warehousing corridors exhibit the strongest preference for outcome-based equipment arrangements.
India
Cold chain infrastructure investments under the PLI scheme create first-time demand for automated wrapping in pharmaceutical distribution. BIS standards govern machinery safety certifications for imported equipment. Mumbai and Hyderabad logistics clusters deploy portable battery-powered units where fixed infrastructure remains under development.
Orbital Wrapping Machine Market Competitive Landscape
The competitive structure tilts toward specialized motion-control fabricators with servo-driven pre-stretch expertise. Mid-tier equipment manufacturers face margin compression from commodity input volatility. Two strategic archetypes dominate: precision-engineering specialists delivering sub-millimeter film tension accuracy, and systems integrators bundling hardware with predictive maintenance service contracts. Geographic expansion and technology licensing represent the dominant competitive moves as players seek access to India's warehousing modernization.
Among North American packaging equipment specialists, Lantech and Orion Packaging Systems LLC occupy positions within the precision-engineering tier, while Italian fabricator Robopac anchors the European ring-wrap systems segment. These three exemplify how regional engineering traditions shape competitive positioning—American servo-control expertise, Italian rotary-mechanism heritage—without any single player commanding cross-continental scale.
| Leading Market Players |
|---|
| Lantech |
| Orion Packaging Systems LLC |
| Robopac |
| Wulftec International |
| Movitec Wrapping Systems SL |
| Pieri |
| Messersì Packaging S.r.l. |
| Reisopack |
| Sotemapack |
| Others |
Pricing and Supply Chain Analysis
Steel and aluminum commodity benchmarks cascade through orbital wrapping machine fabrication, compressing margins for mid-tier manufacturers while concentrating pricing power among servo-control specialists with captive component sourcing. CE marking conformity assessments and extended producer responsibility schemes feed into total cost of ownership calculations, pushing buyers toward outcome-based service contracts that unbundle equipment from maintenance responsibility.
Pricing Analysis
Wrapping performance per pallet anchors value-based pricing for third-party logistics providers in the Netherlands and Belgium. Three-tier pricing structure across premium, standard, and economy levels separates servo-driven rotary arm systems with sub-millimeter tension accuracy from mechanical turntable configurations. Cost compression in mid-tier equipment is intensifying because steel and aluminum price volatility erodes fabrication margins. Small packaging companies in regional French markets exhibit highest price sensitivity, while pharmaceutical distribution centers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
CE marking and Machinery Directive conformity assessments gate European market access, stretching product launch timelines to fourteen months for modified rotary-arm designs. Component fabrication concentrates in Germany, Italy, and China, with brushless servo motors and integrated encoders drawing from motion-control specialists in Stuttgart and Turin. Supply chain risk centers on single-source vulnerability for precision film-dispensing subsystems. Distribution runs through OEM-direct channels for large fleet operators and specialized industrial distributors for mid-sized packaging companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Orbital wrapping machine manufacturing is consolidating around servo-driven pre-stretch specialists as commodity input volatility and mechatronics technician scarcity force undifferentiated mechanical fabricators toward exit or acquisition.
For Market Incumbents: Extend predictive maintenance service contracts to capture recurring revenue from Dutch and Belgian 3PL fleets transitioning from capex to unit-cost accounting. Deepen backward integration into brushless servo motor production to insulate margins from motion-control component pricing pressure. Threat substitution from heat-shrink bundling in beverage distribution demands continuous pre-stretch ratio improvement to justify premium positioning. For New Entrants and Emerging Players: Enter via portable battery-powered configurations for Indian pharmaceutical cold chain infrastructure under the PLI scheme, where fixed wrapping infrastructure remains underdeveloped. White-space concentrates in film-recovery integrated systems for French and Italian extended producer responsibility frameworks. Go-to-market leverage rests on leasing partnerships with regional packaging service providers lacking capital for fleet purchase. For Investors and Strategic Acquirers: The window for entry favors precision-engineering specialists with documented CE marking pathways and established ECHA chemical safety assessment capabilities. Long-term viability hinges on control architecture compatibility with legacy warehouse management system protocols. Signal to watch: API standardization announcements from major German automotive logistics operators that would devalue proprietary integration moats.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Servo Motor Production | Captive supply of brushless encoders insulates German fabricators from component price volatility. |
| Predictive Maintenance Service Contract Expansion | Real-time tension monitoring enables Dutch 3PLs to replace equipment ownership with per-pallet performance fees. |
| Film-Recovery System Integration | Built-in collection and baling aligns French installations with extended producer responsibility mandates. |
| CE Marking Pathway Acceleration | Reduced conformity assessment timelines unlock faster product launches for rotary-arm modifications. |
| India Market Entry via Portable Configurations | Battery-powered units address pharmaceutical distribution gaps where Mumbai cold chain infrastructure remains incomplete. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews covering maintenance directors at German automotive parts distributors, plant engineers in France's pharmaceutical corridors, procurement leads at Dutch third-party logistics providers, and aftermarket service heads at Italian ring-wrap specialists. ECHA chemical safety assessments, EU F-Gas Regulation compliance databases, and BIS machinery safety certifications supplemented bottom-up equipment shipment tracking with top-down market sizing validation.
Granularity-level modeling disaggregated volume and value across product type, technology architecture, application environment, and end-user procurement modality throughout the forecast period. CAGRs derived from logistic curve fitting to automation penetration rates in warehousing and manufacturing, calibrated against steel and aluminum price elasticity assumptions and labor cost trajectories in European logistics clusters. Industry-specific inputs incorporated REACH compliance timeline impacts on film material transitions and PLI scheme disbursement schedules for Indian cold chain infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt EU Green Deal packaging waste directive acceleration or sustained steel price volatility above historical bands. Forecasts reflect documented assumptions on automation substitution elasticities and regulatory compliance cost pass-through rates. A model refresh is warranted upon material change in Machinery Directive conformity assessment timelines or BIS certification reciprocity agreements affecting Indian market access.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Machinery
Piston Fillers Market
Packaging Machinery
Sanitizer Filling Machine Market
Packaging Machinery
Vacuum Sealing Machine Market
Packaging Machinery
Bundling Machine Market
Packaging Machinery
Rotary Sealers Market
Packaging Machinery
Tube Sealing Machines Market
Packaging Machinery
Paper Embossing Machine Market
Packaging Machinery
Corrugated Paper Machine Market
Packaging Machinery
Oil Packing Machine Market
Packaging Machinery
Pouch Packaging Machine Market
Packaging Machinery
Automatic Paper Cutter Market
Packaging Machinery
Automatic Banding Machine Market
Packaging Machinery
Tray Sealing Machines Market
Packaging Machinery
Tray Packing Machine Market
Packaging Machinery
Cling Wrap Machine Market
Packaging Machinery
Post Press Machine Market