
 Global Specialty Tapes Market | 2026-2036
Global Specialty Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Tapes Market Foresight
Buyer concentration in automotive manufacturing and electronics assembly is shifting as tier-one suppliers consolidate procurement across fewer adhesive vendors while aerospace primes fragment specifications by program. 3M Company leverages its polymer science portfolio to sustain dominance in high-temperature masking systems. Nitto Denko Corporation anchors Asian supply for optical bonding films used in display assembly. Avery Dennison Corporation differentiates through RFID-integrated tape platforms that extend traceability into retail packaging chains.
Specialty tapes are engineered adhesive laminates manufactured through solvent, hot melt, or UV-cure coating processes onto flexible backings including polyimide, polyester, or foam substrates, designed to perform under precise thermal, electrical, or mechanical stress conditions. Double-sided tapes command the largest value share in electronics assembly where die-bonding and component mounting require residue-free removability. Silicone adhesive technology leads aerospace and industrial equipment applications where sustained performance across temperature extremes defines specification compliance. Acrylic formulations compete aggressively in automotive manufacturing on cost-performance metrics for exterior trim attachment.
REACH in Europe, GB standards under SAMR in China, and FDA indirect food contact rules in the United States each constrain adhesive chemistry selection and migration testing protocols for tape products. ECHA substance of very high concern listings are forcing reformulation of legacy rubber-based adhesives across industrial equipment segments. Stakeholders must monitor evolving dual carbon goals from China's MEE and the EU Green Deal's embodied carbon tracking requirements to anticipate which adhesive platforms and backing materials will retain market access.
Market Dynamics
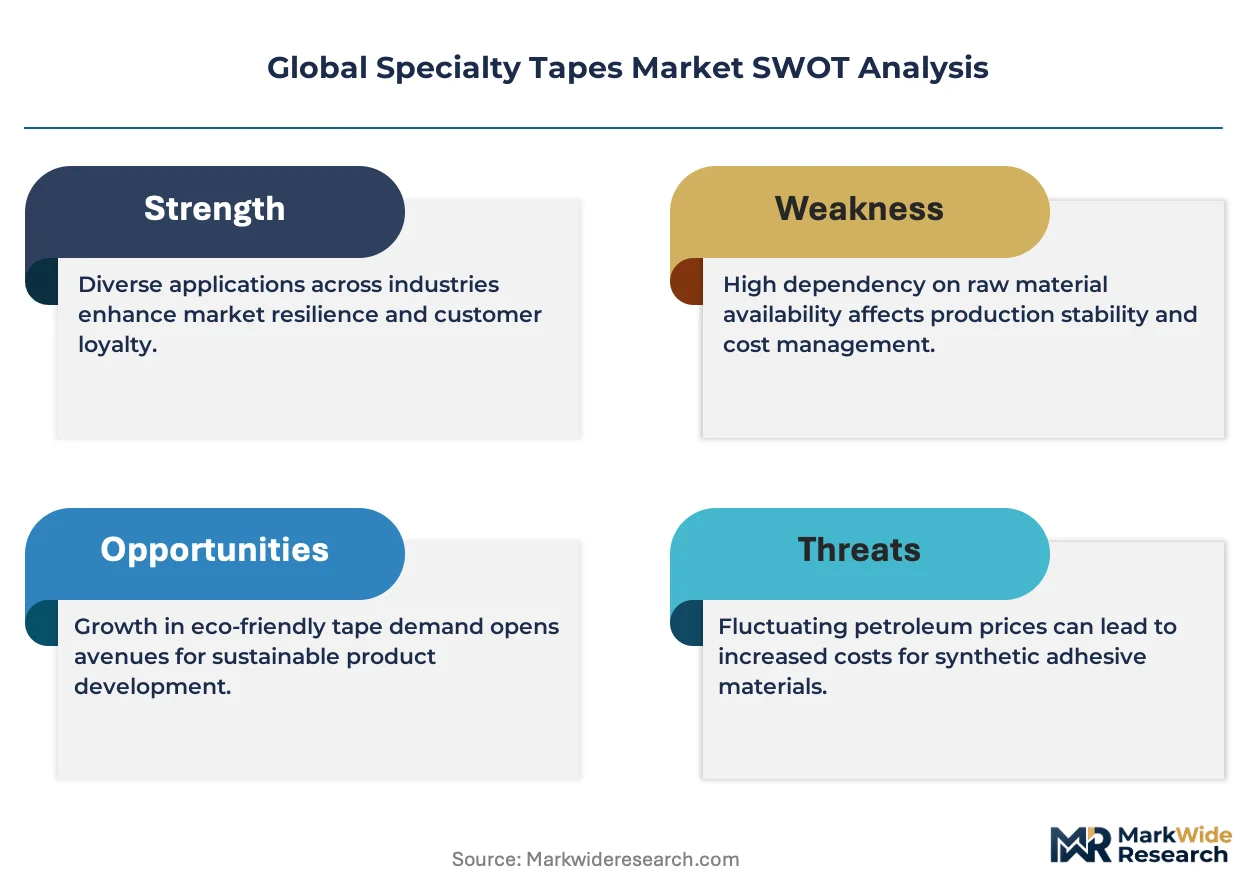
Adhesive chemistry disclosure mandates under REACH and China's evolving GB standards are forcing simultaneous reformulation across multiple substrate-backings, compressing product development cycles while fragmenting supplier qualification protocols.
Growth Catalysts
- Electronics miniaturization:Die-bonding and component mounting applications in display assembly are pulling demand for residue-free removable double-sided tapes. Smartphone and tablet manufacturers in South Korea and Japan are specifying thinner adhesive laminates.
- EU Green Deal embodied carbon tracking:Tape producers qualifying low-carbon backings and solvent-free coating processes are securing preferred supplier status with automotive OEMs pursuing Scope 3 reductions.
- SAMR GB standard harmonization:China's unified adhesive testing protocols are reducing cross-provincial regulatory friction, enabling faster nationwide rollout of industrial equipment tapes.
Market Restraints
- Petrochemical input volatility:Polyimide and polyester substrate costs fluctuate with aromatic feedstock pricing, squeezing margin stability for specialty tape converters.
- German supply concentration:Precision masking tape production clusters heavily in Baden-Württemberg, creating geographic single-point vulnerability for aerospace tier-one procurement.
- Acrylic adhesive temperature ceiling:Sustained performance above 150°C remains unattainable without silicone chemistry, limiting cost-competitive positioning in power electronics thermal management.
Strategic Opportunities
- India industrial corridor expansion:Gujarat and Tamil Nadu manufacturing zones lack qualified local tape converters, creating first-mover advantage for adhesive laminators establishing technical service presence.
- RFID-integrated packaging:Retail logistics chains in Germany and Japan are specifying tape platforms combining adhesion with item-level traceability.
- Battery pack assembly films:EV cell-to-cell bonding applications require flame-retardant pressure-sensitive adhesives with dielectric isolation properties.
Industry Challenges
- Polymer science talent scarcity:Formulation chemists with simultaneous expertise in UV-cure kinetics and regulatory migration testing command premium compensation, constraining R&D team scaling.
- Multi-jurisdiction certification lag:Simultaneous FDA indirect food contact, REACH SVHC screening, and GB standard compliance extends product launch timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Tapes Market |
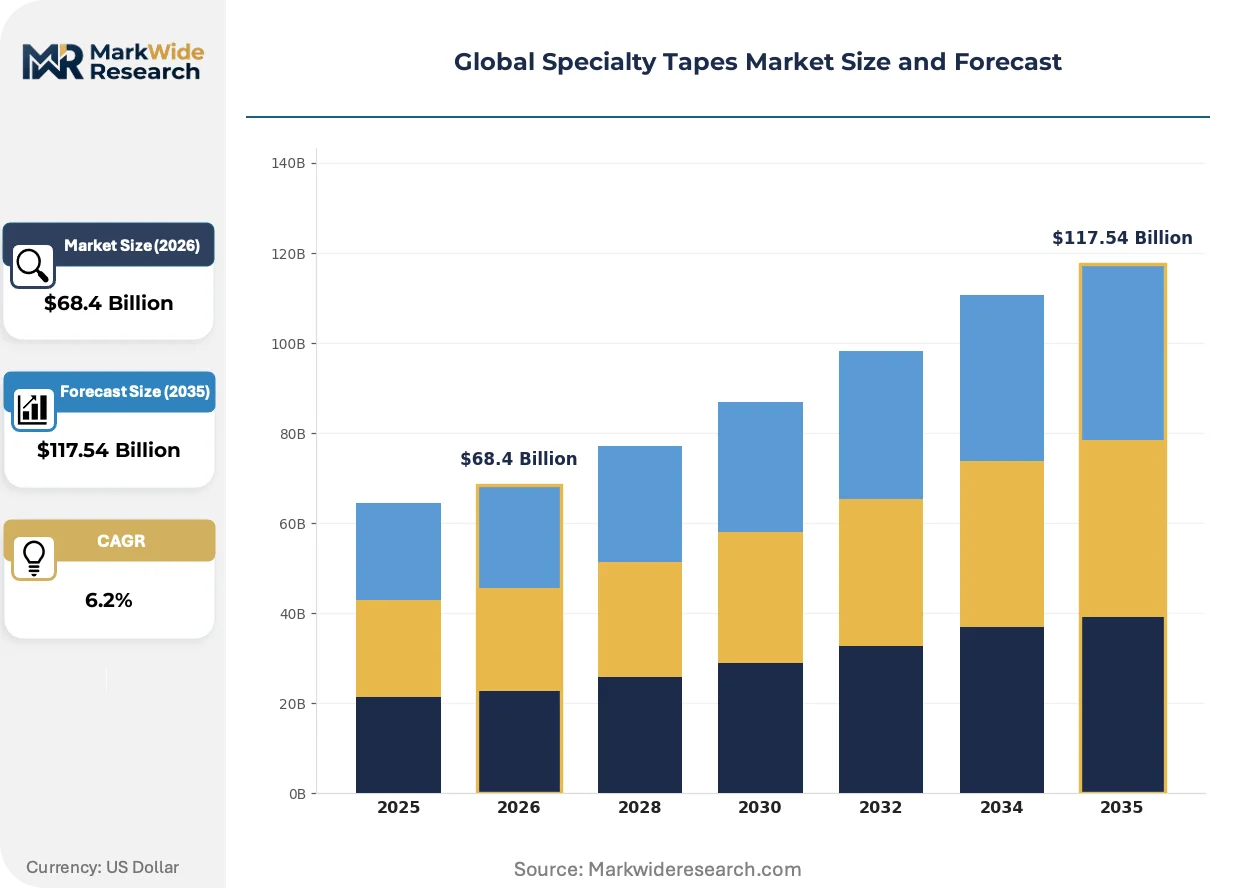
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided, Electrical, Masking, Filament, Transfer, Foam Application: Electronics Assembly, Packaging, Building & Construction, Aerospace, Signage, Automotive Manufacturing End User Industry: Consumer Electronics, Industrial Equipment, Infrastructure Development, Aircraft Manufacture, Retail Packaging, Vehicle Assembly Adhesive Technology: Acrylic, Rubber, Silicone, Hot Melt, Water-Based, UV Cure |
| Companies Covered | Lintec Corporation, Scapa Group PLC, 3M Company, Berry Global Inc., Intertape Polymer Group Inc., Nitto Denko Corporation, Avery Dennison Corporation, Saint-Gobain Performance Plastics, tesa SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Tapes Market Shifts & Advancements
Solvent-free coating technologies and digital printing integration are compressing the traditional tape value chain, enabling converters to bypass legacy film suppliers and deliver application-specific laminates directly to end-users.
UV-curable silicone adhesive systems are decentralizing high-temperature tape production by eliminating thermal drying ovens, reducing capital barriers for regional converters. Automotive aftermarket distributors in Mexico and Poland are adopting these platforms to serve localized masking tape demand. The technology is decentralizing supply geography away from established German and Japanese production hubs.
ECHA substance of very high concern listings are forcing rubber-based adhesive phase-outs across industrial equipment segments. Legacy formulations containing polycyclic aromatic hydrocarbons face mandatory substitution timelines. European machinery OEMs are accelerating acrylic and silicone platform qualification to maintain CE marking compliance.
Direct digital specification between automotive tier-one engineers and tape converters is compressing traditional distribution layers. Material data sheet exchange platforms are displacing regional distributor technical sales functions. This channel restructuring is most advanced in Germany where OEM consolidation has reduced qualified adhesive vendor lists to under twelve per commodity category.
Global Specialty Tapes Market Segmentation
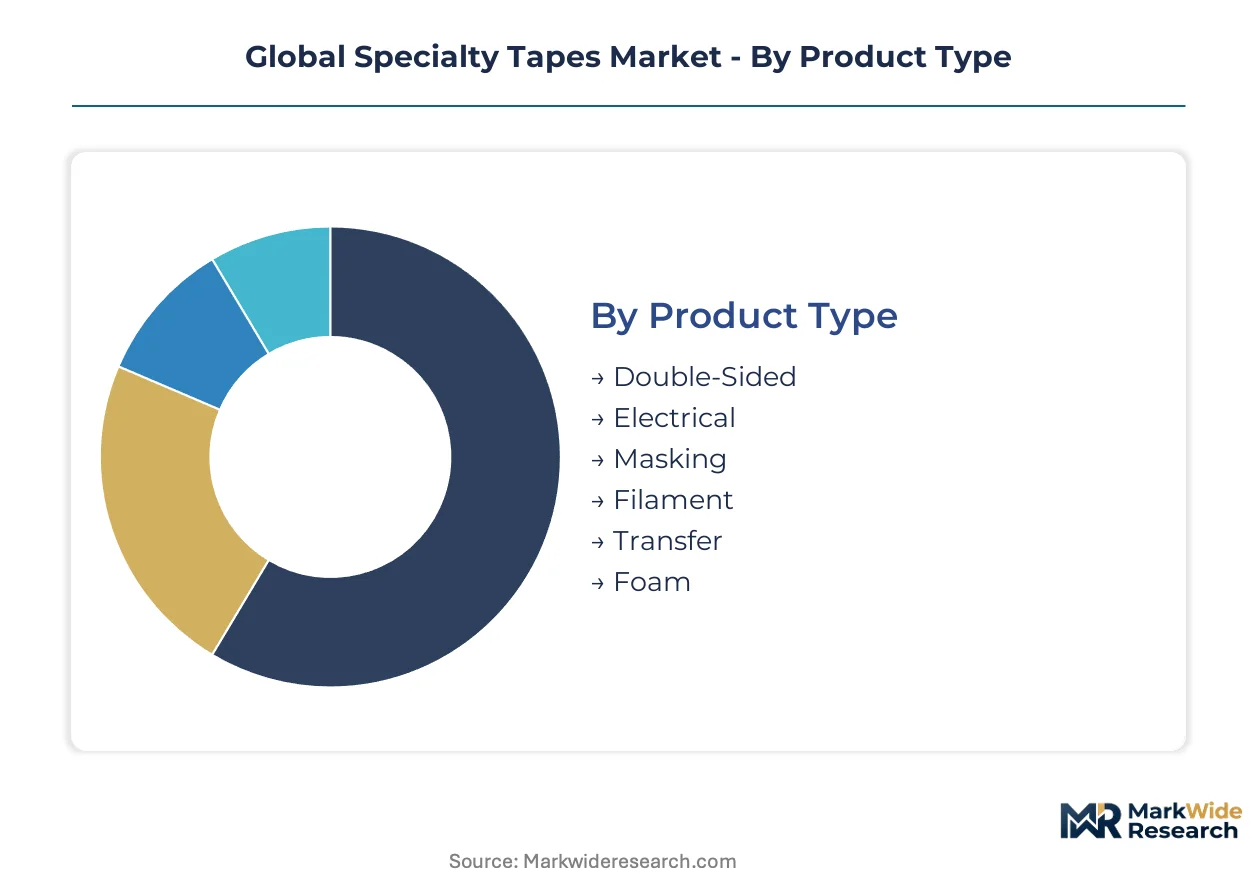
Specialty tape procurement splits along performance specifications versus cost thresholds, with adhesive chemistry and backing substrate choices determining qualification for temperature extremes, electrical isolation, or residue-free removability. Segment boundaries blur as automotive and electronics OEMs consolidate vendor lists around multi-application platforms.
Product Type:
Coating thickness and release liner engineering distinguish commercial grades from precision-specified laminates.
- Double-Sided:Carrier-free or tissue-supported adhesive sandwiches enable die-bonding and component mounting in South Korean display fabs. Thinner gauge specifications below 50 microns now dominate smartphone assembly lines in Japan.
- Electrical:Polyimide or polyester films with silicone or acrylic coatings provide dielectric isolation for transformer winding and motor slot insulation. IEC 60454 compliance separates qualified suppliers from commodity converters in German industrial equipment procurement.
- Masking:Crepe paper or polyimide backings with temperature-rated silicone adhesives protect surfaces during powder coating and anodizing cycles.
- Filament:Glass or synthetic fiber reinforcement delivers tensile strength for pallet unitizing and heavy-duty bundling in logistics operations.
- Transfer:Unsupported adhesive films eliminate carrier thickness for ultra-thin bonding gaps in microelectronics stacking applications.
- Foam:Closed-cell polyethylene or polyurethane substrates absorb vibration and fill surface irregularities in automotive trim attachment.
Mature deployment sits with Masking and Filament in industrial maintenance. Newer deployment is concentrated in Transfer and ultra-thin Double-Sided formats for semiconductor packaging.
Application:
Specification intensity varies sharply by end-use certification burden.
- Electronics Assembly:Cleanroom-compatible release systems and ionic purity testing define supplier qualification for wafer dicing and PCB masking. Japanese and South Korean contract manufacturers now specify lot-level traceability.
- Aerospace:Flame-retardant phenolic or silicone adhesives with FAR 25.853 compliance dominate interior panel bonding and surface protection. Boeing and Airbus tier-one audits limit qualified converters to under twenty globally.
- Packaging:Repulpable adhesives and FDA indirect food contact compliance drive selection for corrugated sealing and flexible food pouches.
- Building & Construction:Weather-resistant acrylic foams compete with mechanical fasteners for curtain wall glazing and HVAC duct sealing in humid climates.
- Signage:UV-stable face stocks and permanent or removable adhesive grades differentiate outdoor durability from indoor promotional applications.
- Automotive Manufacturing:Exterior trim attachment demands paint-compatible adhesives surviving e-coat bake cycles, while interior applications prioritize low-VOC emissions.
Volume concentration favors Packaging and Building & Construction. Margin expansion is steepest in Aerospace and Electronics Assembly where qualification barriers limit competition.
End User Industry:
Procurement sophistication separates specification-driven OEMs from price-sensitive maintenance operations.
- Consumer Electronics:Miniaturization roadmaps from Apple and Samsung suppliers drive sub-25-micron adhesive development with optical clarity requirements for display lamination.
- Aircraft Manufacture:Material qualification cycles extending 18-24 months lock in incumbent suppliers for airframe assembly and interior outfitting.
- Industrial Equipment:MRO procurement through distributors favors standard catalog items over custom laminates, compressing converter margins.
- Infrastructure Development:Civil engineering projects specify tapes for waterproofing membranes and bridge expansion joint sealing with 20-year durability warranties.
- Retail Packaging:RFID integration and sustainability scoring now accompany traditional adhesion performance in European grocery chain specifications.
- Vehicle Assembly:EV battery pack bonding requirements are pulling flame-retardant dielectric tapes into cell-to-cell and module-to-housing applications.
Specification authority rests with Consumer Electronics and Aircraft Manufacture. Fastest adoption velocity appears in Vehicle Assembly as electrification redraws thermal management requirements.
Adhesive Technology:
Cure chemistry determines capital equipment requirements and regulatory compliance pathways.
- Silicone:Platinum-catalyzed addition cure systems deliver sustained performance from -50°C to 260°C for aerospace engine compartment and power electronics applications. German automotive OEMs specify silicone for under-hood labeling surviving 1000-hour heat aging.
- Acrylic:Solvent and emulsion polymerizations dominate cost-sensitive automotive exterior trim and general industrial bonding where 150°C service ceilings suffice.
- Rubber:Natural and synthetic rubber-resin blends face ECHA SVHC-driven phase-out in European industrial equipment segments.
- Hot Melt:Block copolymer synthetic rubbers enable high-speed coating without solvent recovery, favored in packaging and disposable hygiene applications.
- Water-Based:Acrylic emulsions reduce VOC emissions for indoor air quality compliance in construction and signage markets.
- UV Cure:Cationic and free-radical photopolymerization eliminates thermal drying, enabling thin-coat precision and geographic production decentralization.
Installed capacity concentrates in Acrylic and Hot Melt. Technology migration is accelerating toward UV Cure and advanced Silicone platforms as energy costs and REACH compliance tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability along the US Gulf Coast and aromatic chemical clusters in Germany's Rhine-Ruhr corridor anchor specialty tape substrate supply chains. Manufacturing gravity follows precision electronics and automotive assembly concentrations across East Asia and Western Europe.
United States
EV battery pack assembly lines in Michigan and Tennessee are pulling flame-retardant dielectric tapes into cell-to-cell bonding applications. FDA indirect food contact rules constrain adhesive chemistry selection for packaging tapes used in domestic food processing. The Gulf Coast petrochemical corridor supplies polyester and polyimide substrates to converters serving aerospace primes in Seattle and Wichita.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg specify silicone-based masking tapes surviving 1000-hour under-hood heat aging cycles. REACH SVHC listings are forcing rubber-based adhesive phase-outs across industrial equipment segments in the Rhine-Ruhr manufacturing belt. Precision tape production clusters heavily in Baden-Württemberg, creating geographic concentration for aerospace tier-one procurement.
China
SAMR GB standard harmonization is reducing cross-provincial regulatory friction for industrial equipment tape rollouts across Guangdong and Jiangsu provinces. Dual carbon goals from MEE are pushing tape producers toward low-carbon backings and solvent-free coating processes. Display assembly fabs in Shenzhen and Suzhou specify sub-50-micron double-sided tapes for smartphone component mounting.
Japan
Optical bonding films for display lamination dominate procurement from contract manufacturers in the Kanto and Kansai regions. METI industrial standards guide adhesive migration testing protocols for electronics-grade tapes. Miniaturization roadmaps from consumer electronics brands in Tokyo and Osaka drive sub-25-micron adhesive development with optical clarity requirements.
South Korea
Smartphone and tablet manufacturers in Gyeonggi Province specify thinner adhesive laminates below 50 microns for die-bonding applications. MFDS chemical disclosure requirements align with REACH-equivalent screening for adhesive formulations. Display fabs in Suwon and Pyeongtaek concentrate demand for residue-free removable double-sided tapes in cleanroom environments.
Global Specialty Tapes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue UV-cure decentralization and RFID-integrated platforms. The vendor base stratifies across multinational polymer science portfolios, regional adhesive laminators, and specialized coating converters. Three archetypes dominate: diversified materials conglomerates with tape divisions, pure-play adhesive specialists, and captive converters serving single industry verticals. Competitive moves center on strategic partnerships for regulatory compliance acceleration and geographic expansion into underpenetrated industrial corridors.
Among diversified materials conglomerates, 3M Company and Saint-Gobain Performance Plastics exemplify scale-driven positioning across multiple adhesive technology platforms. Nitto Denko Corporation and tesa SE anchor regional supply concentration in East Asia and Western Europe respectively. Avery Dennison Corporation occupies a position bridging packaging-grade volume with specialty electronics qualification. These named entities represent archetype diversity rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Lintec Corporation |
| Scapa Group PLC |
| 3M Company |
| Berry Global Inc. |
| Intertape Polymer Group Inc. |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Saint-Gobain Performance Plastics |
| tesa SE |
| Others |
Supply & Pricing Matrix
Captive integration into solvent-free coating platforms anchors both supply security and margin protection for converters serving automotive OEMs with Scope 3 carbon commitments. This backward control over adhesive polymerization and backing substrate qualification creates pricing power that commodity laminators cannot replicate.
Pricing Analysis
Warranty bundling separates aerospace-grade tape pricing from industrial maintenance tiers, with 20-year durability guarantees commanding substantial premiums over standard catalog items. Three-tier pricing structure across premium, standard, and economy levels tracks certification intensity: IEC 60454-compliant electrical tapes and FAR 25.853-rated aerospace laminates sit at the premium tier, while general industrial masking tapes compete on volume scale. Cost compression in standard-grade acrylic foams is intensifying because petrochemical feedstock volatility squeezes converter margins. MRO procurement through distributors exhibits highest price sensitivity; aerospace tier-one buyers prioritize qualification security over unit cost.
Supply Chain Analysis
Domestic-content mandates in China's industrial equipment procurement are reshaping sourcing patterns, pushing multinational converters toward joint ventures in Jiangsu and Guangdong provinces. Raw material supply concentrates in Germany, Japan, and South Korea, where aromatic chemical clusters feed polyimide and polyester substrate production. Adhesive resin synthesis, release liner manufacturing, and precision coating equipment each draw from distinct geographic specialization. Single-source vulnerability in German Baden-Württemberg masking tape production creates geographic concentration risk for aerospace procurement. Distribution runs through regional adhesive laminators serving precision manufacturing clusters, with technical service proximity determining converter selection.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialty tape supply is tightening around qualified silicone adhesive capacity, with platinum-catalyzed addition cure systems facing 18-24 month qualification cycles that prop pricing for incumbent producers.
For Market Incumbents: Extend certification portfolios into EV battery pack bonding films before flame-retardant dielectric specifications harden. Acquire UV-cure coating capabilities in Mexico and Poland to capture automotive aftermarket decentralization. Lock in long-term polyimide substrate offtake from Rhine-Ruhr aromatic chemical producers to defend margin position against petrochemical volatility. For New Entrants and Emerging Players: Direct digital specification platforms offer a channel to bypass entrenched distributor relationships in Germany, where OEM consolidation has compressed qualified vendor lists. Target India industrial corridor expansion in Gujarat and Tamil Nadu, where qualified local tape converters remain scarce. Lead with RFID-integrated packaging platforms that combine adhesion with item-level traceability for retail logistics chains. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap adhesive specialists with captive silicone formulation expertise and established aerospace qualification. Long-term viability hinges on regulatory compliance acceleration capabilities across REACH, GB standards, and FDA indirect food contact rules. Watch ECHA SVHC listing velocity as the signal indicating which adhesive platforms face mandatory substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Resin Synthesis | Captive polymerization secures margin control against aromatic feedstock volatility from Rhine-Ruhr suppliers. |
| UV-Cure Coating Capacity Expansion | Elimination of thermal drying ovens reduces capital barriers for regional converters in Mexico and Poland. |
| RFID-Integrated Platform Development | Combining adhesion with item-level traceability captures German and Japanese retail logistics specifications. |
| EV Battery Pack Film Qualification | Flame-retardant dielectric tapes with cell-to-cell bonding certification secure automotive OEM preferred status. |
| Joint Venture Formation in China | Domestic production satisfies SAMR GB standard harmonization and dual carbon goals from MEE. |
Research Methodology
Independent corroboration across primary interviews with adhesive formulation chemists, aerospace tier-one procurement directors, and automotive OEM platform engineers underwrites the qualitative findings. Secondary validation drew from SEC filings of diversified materials conglomerates, ECHA SVHC substance listings, SAMR GB standard publications, and customs trade data tracking polyimide substrate flows. Bottom-up triangulation across converter capacity disclosures and top-down reconciliation against end-use demand from electronics assembly and automotive manufacturing produced convergent estimates.
Rate-of-change decomposition across adhesive technology platforms, backing substrate categories, and geographic regulatory clusters structured the analytical framework. Segmentation dimensions modeled include product type, application intensity, end-user industry sophistication, and adhesive cure chemistry. CAGRs were derived from elasticity-adjusted demand curves and capacity expansion schedules. Key inputs encompassed REACH compliance timelines, EV battery pack assembly forecasts, and UV-cure equipment deployment rates.
Inputs from primary fieldwork and published regulatory filings were available through the study window; gaps in real-time converter inventory data and confidential aerospace qualification timelines introduce uncertainty bands. Forecasts reflect assumptions about regulatory enforcement consistency and petrochemical feedstock price stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Tabletop Tape Dispensers Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Hot Melt Adhesive Tapes Market
Tapes
Coding Foils and Tapes Market
Tapes
Protective Films Tapes Market
Tapes
Labels, Tapes and Films Market
Tapes
Wing Walk Tapes Market
Tapes
Umbilical Tapes Market
Tapes
Freezer Tape Market
Tapes
Differential Tapes Market
Tapes
Dicing Tapes Market
Tapes
Self-Fusing Silicone Tapes Market
Tapes
Tape and Label Adhesives Market
Tapes
Kraft Paper Tapes Market
Tapes
Painting Masking Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market