
 Tabbing Tapes Market | 2026-2036
Tabbing Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Tabbing Tapes Market Analytics
Polyester film is restructuring tabbing tape economics as it displaces conventional PET substrates in high-temperature photovoltaic applications. 3M Company leverages proprietary adhesive formulations to sustain technology leadership in solar interconnect solutions. Nitto Denko Corporation anchors its position through backward integration into polymer film production, while Tesa SE competes via specialized high-temperature bonding platforms for European module assemblers.
Tabbing tapes are narrow adhesive strips engineered from polyimide or polyester carriers coated with electrically conductive or thermally stable adhesives, designed to interconnect photovoltaic cells and secure electronic components under thermal cycling stress. Specialty tape formulations incorporating silver-filled epoxies command premium positioning as solar module efficiency thresholds tighten. Foam-backed configurations are gaining fastest in automotive wire harness applications where vibration damping intersects with miniaturization trends, while paper-based variants occupy mature labeling segments with thinning margin pools.
FDA scrutiny of industrial adhesive volatiles, EPA guidelines on solvent-based coating emissions, and REACH substance restrictions are collectively elevating compliance costs and favoring waterborne acrylic platforms over solvent chemistries. China's GB standards for photovoltaic component durability are accelerating domestic certification requirements for imported tabbing materials. Stakeholders must monitor how adhesive platform transitions intersect with module recycling mandates to anticipate specification shifts before contract renewals.
Market Dynamics
Photovoltaic cell interconnect specifications are tightening as solar module efficiency benchmarks rise, forcing adhesive chemistry transitions and substrate material substitutions across the supply base.
Growth Catalysts
- Dual carbon targets in China:Domestic solar cell production expansion under GB standards is accelerating procurement of high-durability tabbing materials certified for 25-year module lifespans.
- REACH substance restrictions:European ECHA mandates on solvent-based coating emissions are redirecting formulation investment toward waterborne acrylic adhesive platforms.
- Silver-filled epoxy formulations:Specialty conductive adhesives are capturing premium positioning as photovoltaic efficiency thresholds tighten and cell-to-module power loss minimization becomes critical.
Market Restraints
- Polymer film supply concentration:Backward integration by Japanese and Korean film producers limits independent substrate sourcing options for European and North American tape converters.
- Copper and silver price volatility:Conductive filler materials constitute 35-45% of specialty tabbing tape input costs, compressing margins when commodity cycles spike.
- Fluorinated adhesive substitution:Emerging laser-welding and ribbon-bonding interconnect technologies threaten displacement in next-generation heterojunction cell architectures.
Strategic Opportunities
- India's PLI scheme for solar manufacturing:Domestic content requirements under the production-linked incentive program are creating captive demand for locally certified tabbing tape suppliers.
- Automotive wire harness miniaturization:Foam-backed vibration-damping configurations are penetrating electric vehicle power electronics where thermal cycling meets space constraints.
- EU Green Deal module recycling mandates:Adhesive platform separability requirements are opening specification windows for thermally reversible bonding chemistries.
Industry Challenges
- Multi-jurisdiction certification sequencing:Simultaneous UL, TUV, and BIS durability testing extends product qualification timelines to 18-24 months.
- Adhesive formulation talent scarcity:Cross-functional expertise spanning polymer chemistry, photovoltaic metallization, and thermal management is concentrated among a narrow specialist cohort.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tabbing Tapes Market |
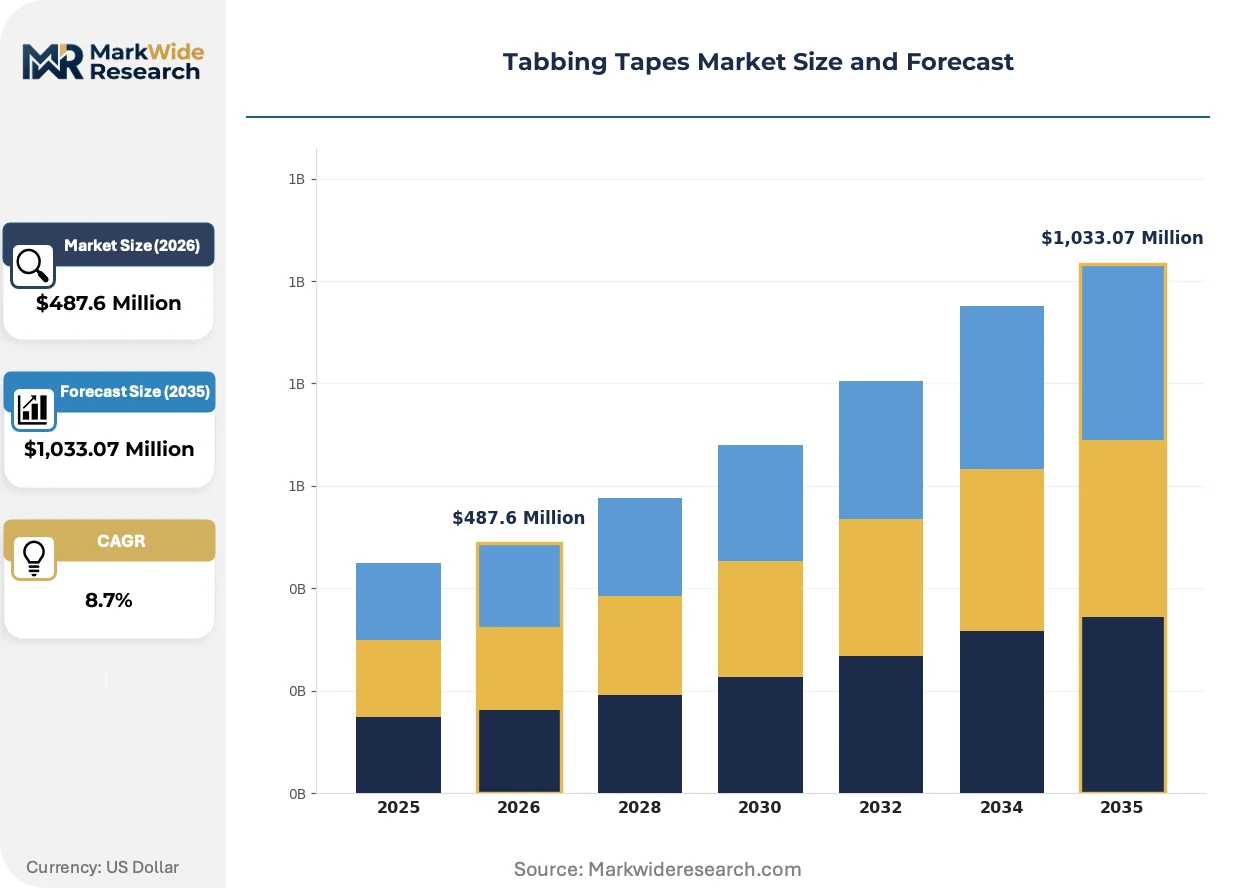
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tape, Adhesive Tape, Masking Tape, Specialty Tape Application: Packaging, Labeling, Automotive, Construction End User: Manufacturers, Retailers, Contractors, DIY Consumers Material: Paper, Plastic, Foam, Cloth |
| Companies Covered | 3M Company, Scapa Group, Nitto Denko Corporation, Avery Dennison Corporation, Tesa SE, Lohmann GmbH & Co. KG, Berry Global Inc., Lintec Corporation, Intertape Polymer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tabbing Tapes Market Evolving Landscape
Material science convergence with photovoltaic process engineering is redefining performance benchmarks and supplier selection criteria across cell interconnect applications.
Polyester film substrates with enhanced thermal stability are consolidating position in high-temperature photovoltaic assembly processes. Solar cell manufacturers in China and Southeast Asia are specifying these carriers for PERC and TOPCon cell architectures where processing temperatures exceed conventional PET limits. The shift is consolidating procurement around film suppliers capable of 150°C continuous operation certification.
REACH substance restrictions on volatile organic compound emissions are forcing coating line retrofits across European tape manufacturing facilities. Waterborne acrylic adhesive platforms are displacing solvent-based systems in module assembly applications, though thermal resistance trade-offs persist in desert-climate installations. German and Spanish module assemblers are prioritizing suppliers with verified low-VOC formulation portfolios.
Cell-to-module power loss minimization is reshaping buyer specifications toward ultra-low-resistance interconnect solutions. Tier-one solar manufacturers are qualifying silver-filled epoxy tabbing tapes with volume resistivity below 10^-4 ohm-cm, displacing conventional solder-coated copper ribbons in shingled cell designs. This specification tightening is most visible in Chinese and Vietnamese cell production facilities supplying European utility-scale projects.
Tabbing Tapes Market Segmentation
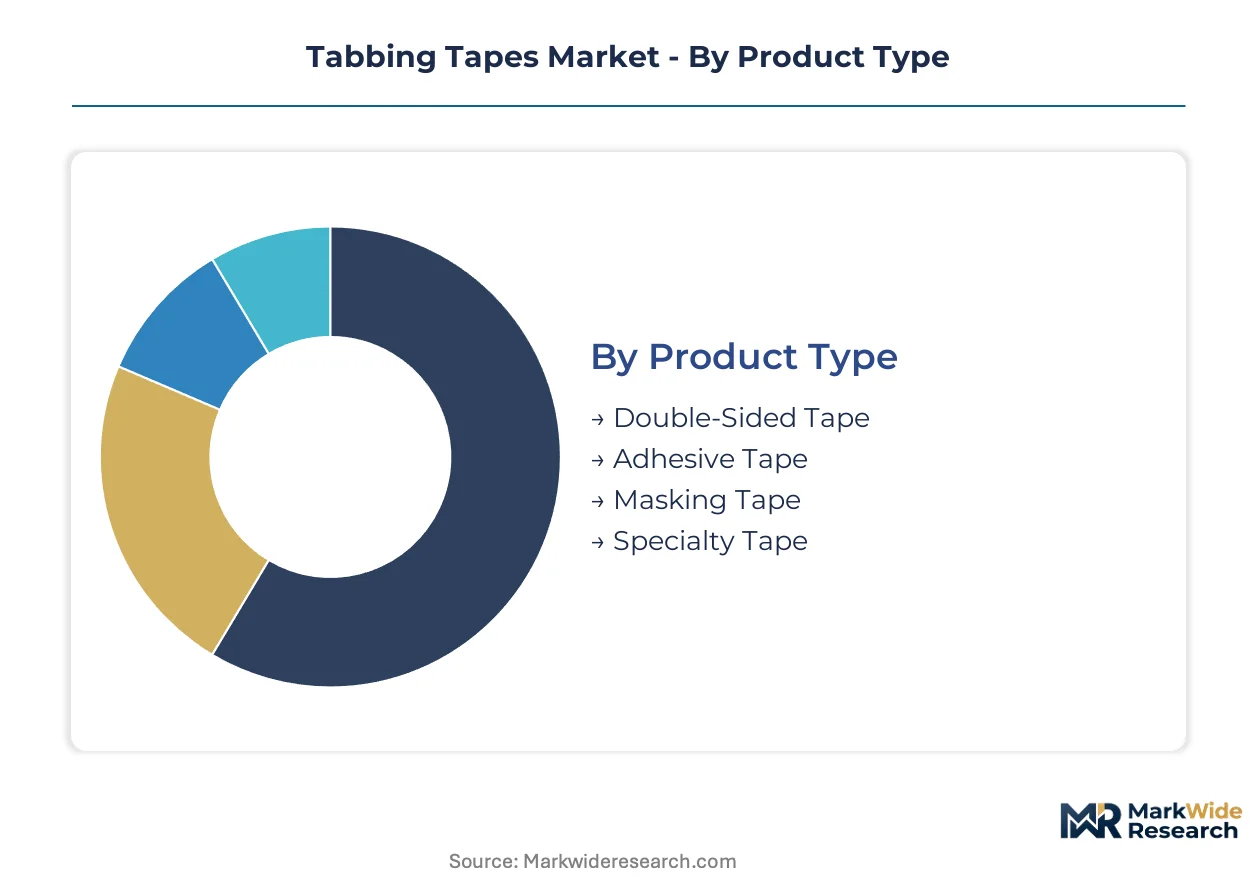
Segmentation in tabbing tapes reveals how adhesive chemistry and carrier substrates align with divergent thermal, electrical, and mechanical requirements across photovoltaic assembly, automotive harnessing, and industrial bonding. Product specifications vary sharply between solar cell interconnects demanding 25-year durability and temporary masking applications where removability dominates.
Product Type:
Upgrade cycles in photovoltaic module assembly are accelerating replacement of conventional interconnect methods with advanced adhesive solutions engineered for next-generation cell architectures.
- Double-Sided Tape:Carrier films coated with conductive or non-conductive adhesives on both faces enable cell-to-cell interconnection in shingled solar designs. Chinese PERC and TOPCon manufacturers specify these for automated stringing lines where soldering temperatures damage heterojunction cells.
- Adhesive Tape:Single-coated pressure-sensitive systems serve general-purpose bonding in wire harness wrapping and component mounting. European automotive suppliers qualify solvent-free acrylic formulations under REACH VOC restrictions for electric vehicle power electronics.
- Masking Tape:Crepe paper carriers with silicone or rubber adhesives protect surfaces during photovoltaic cell edge deletion and frame sealing operations. Temporary adhesion without residue defines procurement criteria.
- Specialty Tape:Silver-filled epoxy formulations with volume resistivity below 10^-4 ohm-cm command premium positioning for cell-to-module power loss minimization. These formulations integrate into Vietnamese and Malaysian facilities supplying European utility-scale projects.
Volume placements concentrate in adhesive tape for general industrial bonding; the faster expansion belongs to specialty tape as efficiency thresholds tighten.
Application:
Cost tier differentiation separates commodity packaging applications from specification-driven solar and automotive segments where certification requirements elevate pricing.
- Packaging:Acrylic and hot-melt adhesives on polypropylene carriers seal corrugated containers and flexible pouches. Demand concentrates in e-commerce fulfillment centers where throughput speed outweighs thermal performance.
- Labeling:Paper and film face stocks with permanent or removable adhesives serve logistics, healthcare, and consumer goods tracking. Mature margin pools characterize this segment as digital printing reduces substrate differentiation.
- Automotive:Foam-backed vibration-damping configurations penetrate electric vehicle power electronics where thermal cycling intersects with space constraints. German and Japanese OEMs specify these for battery management system wire routing.
- Construction:Cloth and film carriers with aggressive adhesives bond vapor barriers, insulation facings, and temporary surface protection. Building code compliance for fire resistance and outgassing limits material selection.
Revenue concentrates in automotive applications; construction represents the steepest expansion trajectory as green building standards proliferate.
End User:
Customer type determines whether procurement prioritizes volume pricing, technical specification depth, or shelf-ready availability through distribution channels.
- Manufacturers:Solar cell and module producers specify tabbing tapes through direct supplier qualification programs. Chinese photovoltaic manufacturers under GB standards drive demand for 25-year durability certification.
- Retailers:Big-box and specialty distributors stock consumer-grade adhesive tapes for DIY and light industrial applications. SKU breadth and packaging formats outweigh technical performance in purchasing decisions.
- Contractors:Installation firms in solar, electrical, and HVAC trades procure through wholesale channels with job-specific quantity flexibility. Regional availability and same-day delivery shape supplier relationships.
- DIY Consumers:Individual purchasers select pre-packaged assortments for home repair and craft applications. Price sensitivity and brand recognition dominate this lowest-margin segment.
Procurement volume concentrates with manufacturers; contractor channels are expanding most quickly as distributed solar installation scales.
Material:
Supply concentration in polymer film production constrains independent substrate sourcing for tape converters outside Asia-Pacific.
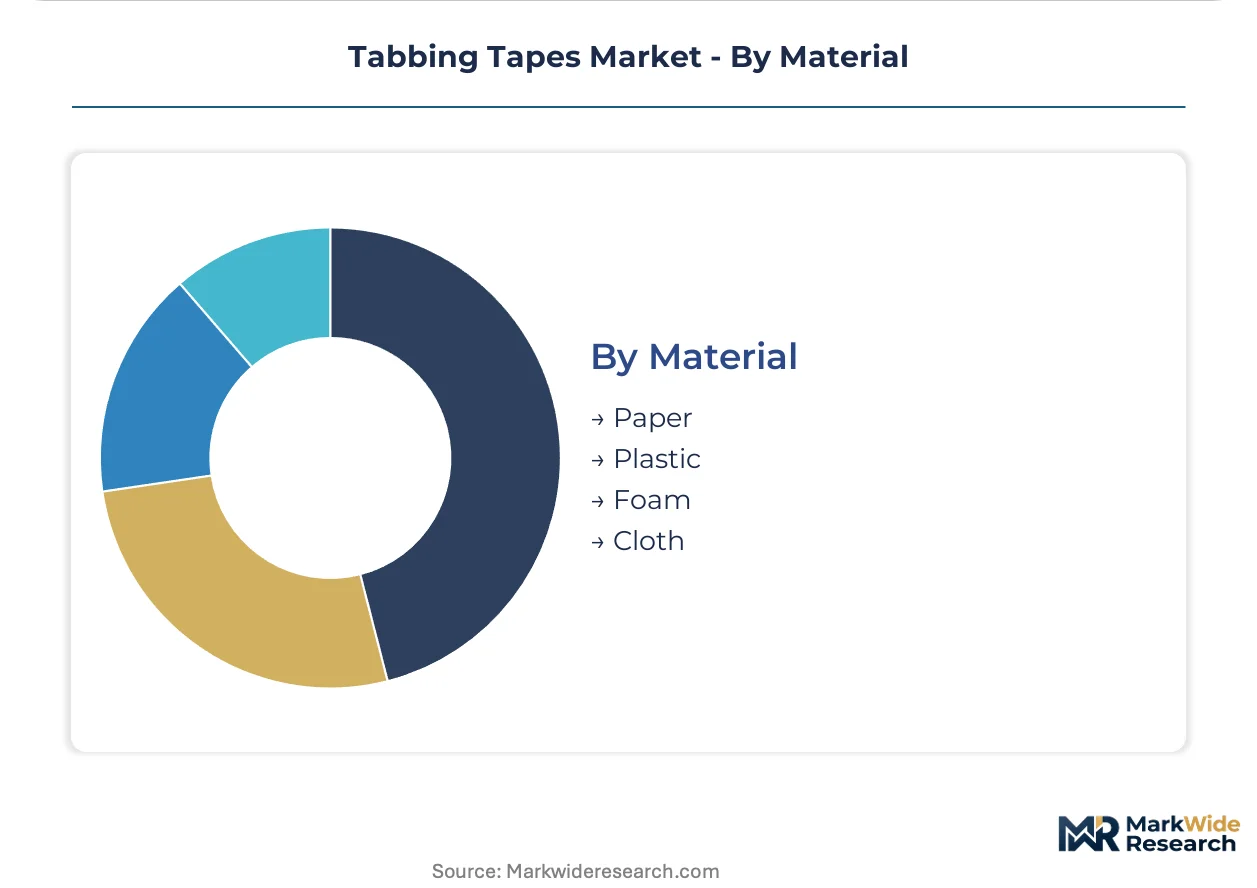
- Paper:Crepe and flatback kraft carriers serve masking, labeling, and temporary bonding where conformability and clean removal matter. Saturated and unsaturated grades separate premium from economy positioning.
- Plastic:Polyester and polyimide films dominate photovoltaic interconnect applications requiring 150°C continuous operation. Japanese and Korean producers control upstream supply through backward integration into polymer film manufacturing.
- Foam:Acrylic and polyethylene foam carriers provide vibration damping and gap filling in automotive and electronics assembly. Thickness and compression set specifications vary by end-use thermal exposure.
- Cloth:Woven cotton, rayon, and synthetic fabric backings deliver tensile strength for heavy-duty bundling and splicing. Construction and industrial maintenance applications specify these for abrasion resistance.
Plastic substrates capture the dominant revenue share; foam materials are gaining share fastest as electric vehicle production expands wire harness demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in China concentrate photovoltaic tape manufacturing capacity. Vietnam's industrial parks attract module assembly investment. India's production-linked incentive scheme reshapes procurement geography.
China
Domestic solar cell production expansion under GB standards drives 25-year durability certification requirements. The Ministry of Ecology and Environment enforces dual carbon targets that accelerate renewable component procurement. Hefei and Xian industrial clusters host automated stringing line installations for PERC and TOPCon cell architectures.
Germany
Utility-scale solar projects demand REACH-compliant adhesive formulations with verified low-VOC portfolios. ECHA substance restrictions redirect coating line investments toward waterborne acrylic platforms. Saxony-Anhalt and Brandenburg module assembly facilities specify thermally stable substrates for desert-climate installations.
United States
Domestic content requirements under the Inflation Reduction Act stimulate local tape converter qualification programs. EPA guidelines on solvent-based coating emissions elevate compliance costs for imported materials. Arizona and Texas photovoltaic manufacturing corridors expand procurement of high-temperature bonding solutions.
Vietnam
European utility-scale project supply contracts concentrate cell-to-module assembly investment. BIS-equivalent durability testing protocols extend product qualification timelines for export certification. Bac Ninh and Hai Phong industrial zones attract shingled cell design production for premium efficiency segments.
India
Production-linked incentive schemes for solar manufacturing create captive demand for locally certified tabbing materials. CEA grid connectivity standards mandate component traceability through domestic value chains. Gujarat and Rajasthan solar parks drive specification alignment with 25-year module lifespan requirements.
Tabbing Tapes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base concentrates around adhesive chemistry expertise and polymer film supply control. Three archetypes dominate: vertically integrated polymer producers, specialized coating converters, and diversified industrial tape portfolios. Capacity expansion and backward integration into film production represent the primary competitive vectors.
Among diversified industrial conglomerates, 3M Company and Nitto Denko Corporation exemplify technology leadership through proprietary formulation control. Tesa SE occupies a position within the European specialist tier, competing via high-temperature bonding platforms. These three anchors demonstrate how adhesive chemistry depth and substrate supply security determine competitive positioning in specification-driven photovoltaic segments.
| Leading Market Players |
|---|
| 3M Company |
| Scapa Group |
| Nitto Denko Corporation |
| Avery Dennison Corporation |
| Tesa SE |
| Lohmann GmbH & Co. KG |
| Berry Global Inc. |
| Lintec Corporation |
| Intertape Polymer Group |
| Others |
Value Network & Pricing Analysis
Silver and copper price indices cascade through tabbing tape manufacturing tiers, compressing margins for converters lacking captive filler supply while amplifying pricing power for backward-integrated Japanese and Korean polymer producers serving photovoltaic module assemblers.
Pricing Analysis
Short lead-time premiums command substantial markups as Chinese PERC and TOPCon manufacturers accelerate procurement cycles under GB standards certification deadlines. Three-tier pricing structure across premium, standard, and economy levels separates silver-filled epoxy formulations with sub-10^-4 ohm-cm resistivity from commodity acrylic adhesives and paper-based masking variants. Pricing pressure stems from copper and silver commodity volatility constituting 35-45% of specialty tape input costs. DIY retailers exhibit highest price sensitivity, while solar cell manufacturers under 25-year durability mandates absorb premium positioning for certified interconnect materials.
Supply Chain Analysis
Domestic content requirements under India's PLI scheme and the US Inflation Reduction Act are redirecting procurement toward locally qualified converters, fragmenting previously centralized supply relationships. Polymer film production concentrates in Japan, South Korea, and China, with Japanese and Korean producers maintaining upstream control over polyester and polyimide substrate manufacturing. Raw material dependencies span silver-filled epoxies, high-purity copper foils, and thermally stabilized carrier films. Single-source vulnerability in specialty adhesive formulation talent constrains European and North American converter expansion. Distribution runs through direct supplier qualification programs for solar manufacturers and wholesale channels serving contractor installation firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around adhesive chemistry expertise and polymer film supply security, with REACH compliance costs and multi-jurisdiction certification timelines forcing weaker converters into acquisition or exit.
For Market Incumbents: Lock in cell-to-module procurement relationships through captive supply of silver-filled epoxy formulations certified for 25-year GB standards durability. Expand backward integration into polyester film production to defend margin position against commodity filler volatility. Prioritize waterborne acrylic R&D investment ahead of ECHA solvent restriction enforcement.
For New Entrants and Emerging Players: Enter via India's PLI scheme domestic content requirements, where qualified local suppliers face limited competition for photovoltaic module assembly procurement. Target automotive wire harness miniaturization segments in German and Japanese electric vehicle supply chains, where foam-backed vibration-damping specifications outpace incumbent capacity. Lead with thermally reversible bonding chemistry platforms aligned with EU Green Deal module recycling mandates.
For Investors and Strategic Acquirers: The window for entry favors mid-cap coating converters with existing UL or TUV certification infrastructure and untapped polymer film supply relationships. Long-term viability hinges on adhesive formulation talent retention and qualification timeline compression. Watch for ECHA substance restriction expansion beyond solvent-based coatings as the signal for accelerated platform transition investment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Film Production | Captive polyester supply secures margin control against Japanese and Korean substrate concentration. |
| Waterborne Acrylic Formulation Transition | ECHA REACH compliance positions converters for European module assembler procurement under VOC restrictions. |
| Silver-Filled Epoxy Capacity Expansion | Sub-10^-4 ohm-cm resistivity certification captures premium positioning in Vietnamese shingled cell facilities. |
| Multi-Jurisdiction Qualification Investment | Simultaneous UL, TUV, and BIS testing compression accelerates procurement access across China, Europe, and India. |
| Thermally Reversible Bonding Chemistry Development | EU Green Deal adhesive separability requirements open specification windows ahead of contract renewal cycles. |
Research Methodology
Multi-period observation of photovoltaic module efficiency benchmarks, adhesive chemistry patent filings, and polymer film capacity announcements anchored the trend analysis, supplemented by interviews with solar cell procurement directors, tape converter plant managers, ECHA regulatory affairs specialists, and automotive wire harness engineers. Secondary validation drew from SEC 10-K filings of listed tape manufacturers, Chinese customs trade data on photovoltaic component imports, ECHA substance restriction documentation, and GB standards certification registries. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Input-output matrices modeled volume and value trajectories across adhesive chemistry type, carrier substrate material, end-use application, and regional regulatory cluster throughout the forecast period. CAGRs derived from segment-level growth rate synthesis applied to base-year market estimates. Forecast inputs incorporated solar cell production capacity expansion under China's dual carbon targets, India's PLI scheme implementation pace, and heterojunction cell architecture adoption curves affecting interconnect technology substitution risk.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt commodity price spikes, accelerated laser-welding interconnect substitution, or ECHA substance restriction scope expansion beyond solvent-based coatings. Forecasts reflect documented assumptions regarding certification timeline stability and polymer film supply concentration persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Adhesive Tapes Market
Tapes
Custom Printed Tape Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Lacing Tape Market
Tapes
Labels, Tapes and Films Market
Tapes
Sterilization Tape Market
Tapes
Thermal Transfer Tapes Market
Tapes
Twist Tube Market
Tapes
Mastic Tapes Market
Tapes
Cable Wrapping Tapes Market
Tapes
Seam Tapes Market
Tapes
Washi Tapes Market
Tapes
Tabletop Tape Dispensers Market
Tapes
Global Acrylic Foam Tapes Market
Tapes
Global Seam Sealing Tapes Market
Tapes
Plastic Adhesive Tapes Market