
 Packaging Tapes Market | 2026-2036
Packaging Tapes Market Size, Share, and Industry Trends Forecast 2026-2036
Packaging Tapes Market Outlook
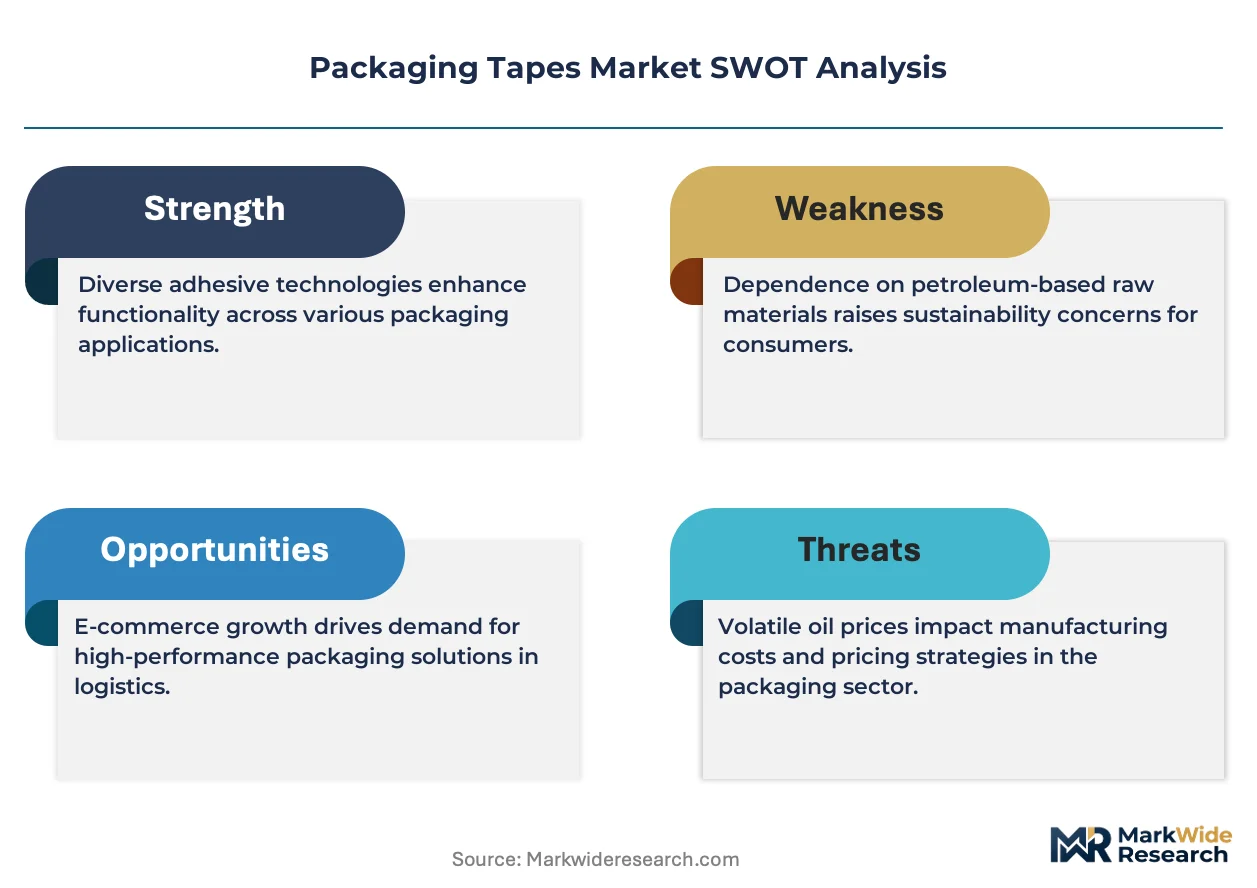
E-commerce buyer concentration is broadening as direct-to-consumer brands and third-party logistics providers fragment demand across smaller, more specialized procurement pools. 3M leverages its adhesive science portfolio to serve high-performance industrial sealing applications. Avery Dennison Corporation anchors North American label and tape demand through extensive distribution partnerships. Intertape Polymer Group Inc. specializes in water-activated and reinforced gummed tapes for sustainable packaging mandates.
Packaging tapes are pressure-sensitive or heat-activated adhesive films, typically 20-150 microns thick, applied to substrates including biaxially oriented polypropylene, PVC, or kraft paper for carton closure, pallet stabilization, and brand authentication. Their primary purpose is securing goods through distribution networks while withstanding temperature cycling, humidity exposure, and mechanical shear. Pressure sensitive adhesive tapes dominate volume due to instant tack and application speed, while water activated formulations gain share in corrugated recycling streams where repulpability matters. Hot melt adhesives sustain margin pools in automated case-sealing lines where high-speed coatability reduces downtime.
The EPA regulates volatile organic compound emissions from solvent-based adhesive coating operations, while OSHA sets workplace exposure limits for toluene and methyl ethyl ketone in tape manufacturing facilities. REACH restricts phthalate plasticizers in PVC tape backings, redirecting formulation investment toward bio-plasticizer alternatives. Stakeholders must monitor how California's SB 54 extended producer responsibility rules and emerging state-level packaging tariffs reshape material specifications and regional sourcing decisions.
Market Dynamics
E-commerce fulfillment networks are fragmenting procurement authority away from centralized packaging buyers toward thousands of direct-to-consumer brands and third-party logistics operators, each with specialized performance specifications and shorter contract cycles.
Growth Catalysts
- EU Green Deal compliance mandates:REACH chemical standards and extended producer responsibility frameworks are redirecting converter investment toward water-based adhesive formulations and bio-sourced backings.
- Automotive cold-chain logistics:Pharmaceutical distribution networks in Germany require temperature-stable tapes with validated adhesive performance across -20°C to +40°C cycling.
- Corrugated recycling stream optimization:Repulpability specifications from major paperboard mills are accelerating water-activated tape adoption over pressure-sensitive alternatives in closed-loop packaging systems.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene resin and synthetic rubber prices fluctuate with crude oil indices, compressing margin visibility for tape converters.
- Adhesive chemical supply concentration:Specialty tackifier resins and acrylic monomers concentrate among a handful of European and Asian chemical producers.
- Hot melt performance ceiling:Automated case-sealing lines above 150 packages per minute exceed the shear resistance of standard EVA-based hot melt formulations.
Strategic Opportunities
- India's PLI scheme for packaging:Domestic manufacturing incentives are creating localized supply capacity for export-oriented pharmaceutical and textile producers.
- Smart packaging integration:RFID-enabled and tamper-evident tape constructions converge with track-and-trace requirements in high-value electronics and luxury goods distribution.
- Direct procurement platforms:Specialized B2B marketplaces are disintermediating traditional distributor relationships for mid-volume e-commerce fulfillment operators.
Industry Challenges
- Adhesive formulation chemist scarcity:Deep expertise in bio-based polymer synthesis and regulatory-compliant solvent substitution commands premium compensation.
- Coating line reconfiguration costs:Transitioning from solvent-based to water-based adhesive systems requires capital-intensive drying oven modifications and speed adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packaging Tapes Market |
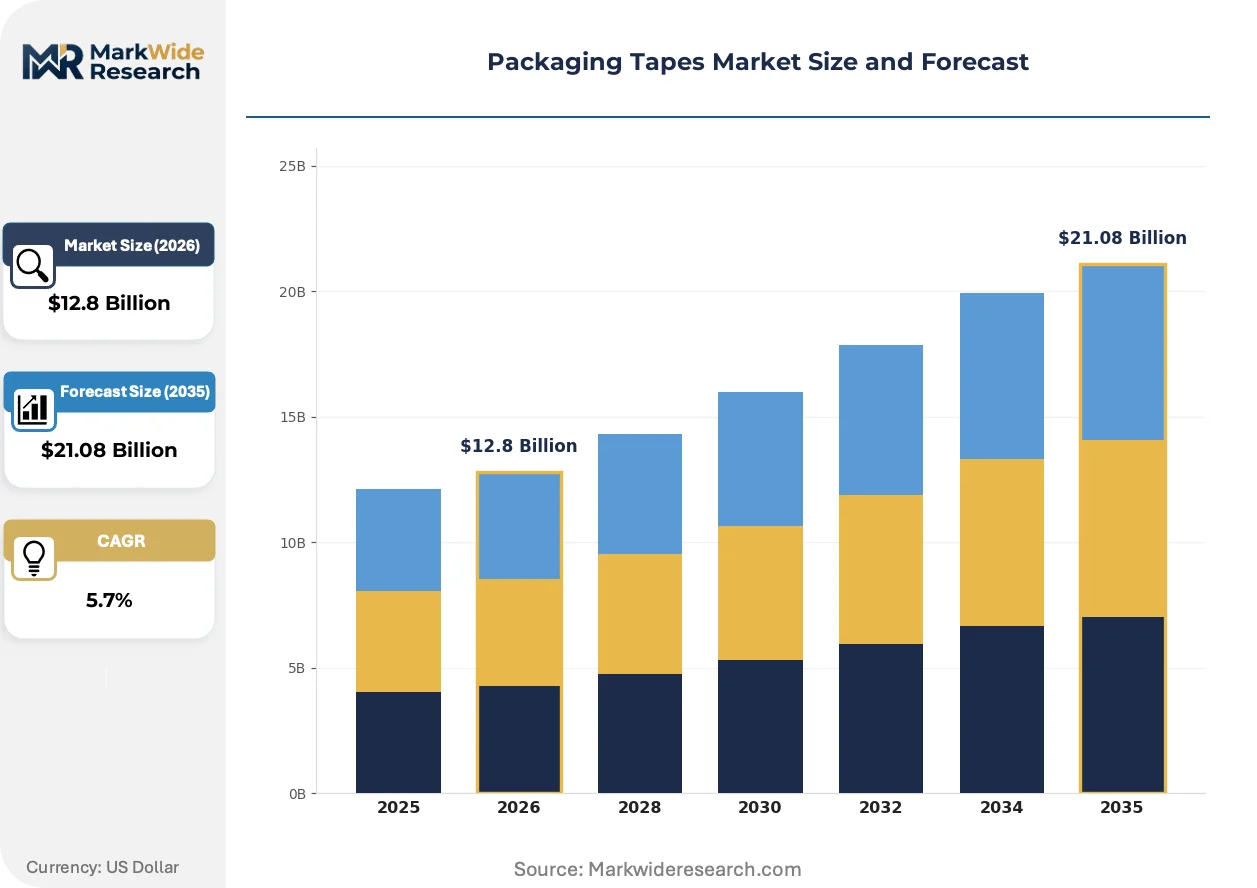
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cellophane, PVC, Paper, Cloth Adhesive Type: Hot Melt, Water Activated, Pressure Sensitive, Solvent Based End User: Retail, Manufacturing, E-Commerce, Logistics Thickness: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty |
| Companies Covered | tesa SE, Berry Global Inc., 3M, Saint-Gobain, Shurtape Technologies, LLC, Avery Dennison Corporation, Intertape Polymer Group Inc., Henkel AG & Co. KGaA, Nitto Denko Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packaging Tapes Market Strategic Shifts
Active innovation in packaging tapes centers on adhesive chemistry reformulation, regulatory-driven material substitution, and procurement model fragmentation that together reshape how converters compete for differentiated demand segments.
Water-activated gummed tape with reinforced fiberglass or synthetic yarn filaments is decentralizing carton sealing decisions away from traditional pressure-sensitive dominance in European corrugated recycling streams. Major e-commerce fulfillment operators in Germany and the Netherlands specify repulpable closures to meet mill gate requirements. This technology is decentralizing specification authority from packaging engineers toward sustainability compliance officers with distinct performance priorities.
REACH restrictions on phthalate plasticizers in PVC tape backings are forcing rapid migration toward bio-plasticizer alternatives derived from citrate and epoxidized vegetable oil chemistries. Tape converters serving medical device and food contact applications face accelerated recertification timelines. Specialty PVC backings for pharmaceutical cold-chain applications absorb the most intensive reformulation investment as ECHA scrutiny intensifies.
Fragmented procurement patterns among direct-to-consumer brands are compressing contract durations and multiplying SKU complexity for tape suppliers. Third-party logistics providers now specify custom-printed, color-coded, and performance-graded tapes within single fulfillment networks. This behavioral shift concentrates most acutely in German automotive parts export packaging, where individual suppliers demand branded authentication features on secondary packaging.
Packaging Tapes Market Segmentation
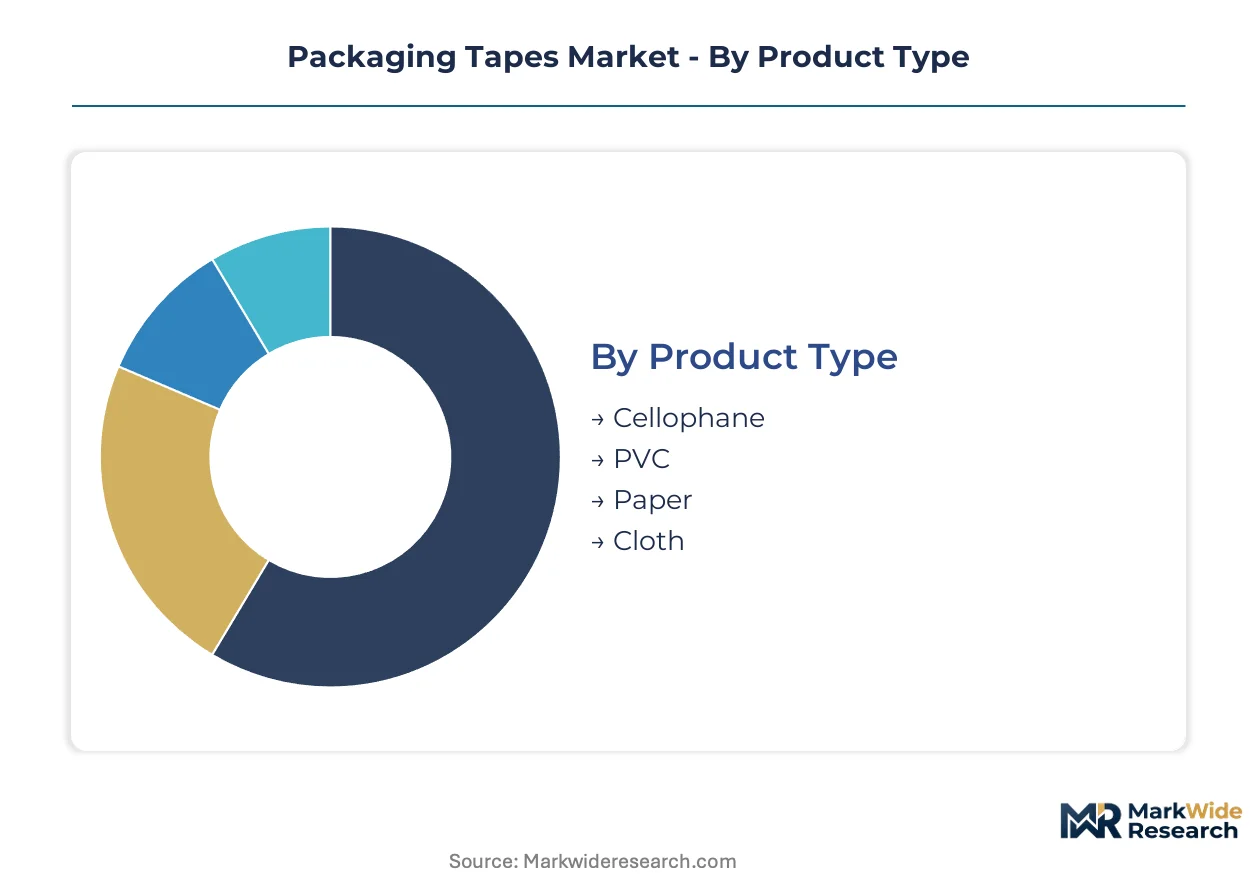
Packaging tape procurement splits across incompatible performance requirements and regulatory frameworks. Buyers optimize for line speed, recycling compatibility, or cold-chain validation depending on their distribution network architecture.
Product Type:
Substrate selection hinges on tensile strength needs and end-of-life disposal pathways.
- Cellophane:Regenerated cellulose film with high clarity and dead-fold characteristics suits gift packaging and food contact applications. European luxury goods distributors specify cellophane for premium unboxing experiences despite moisture sensitivity.
- PVC:Plasticized polyvinyl chloride delivers exceptional conformability to irregular surfaces and chemical resistance. REACH phthalate restrictions are forcing rapid bio-plasticizer migration in German medical device packaging.
- Paper:Kraft paper backings with reinforced filaments dominate corrugated recycling streams. Dutch e-commerce fulfillment networks specify repulpable closures to meet mill gate compliance.
- Cloth:Woven cotton or synthetic fabric substrates provide structural reinforcement for heavy pallet stabilization. Automotive parts export packaging in Germany absorbs volume for abrasion-resistant edge protection.
Cellophane leads on scale; paper leads on momentum.
Adhesive Type:
Application method and line speed requirements segment converter capabilities and capital investment profiles.
- Hot Melt:Ethylene-vinyl acetate formulations coat at speeds exceeding 150 meters per minute on automated case-sealing equipment. Temperature cycling limitations constrain pharmaceutical cold-chain adoption despite manufacturing throughput advantages.
- Water Activated:Starch or dextrin adhesives form permanent fiber bonds with corrugated board and repulp without contamination. Major paperboard mills in the Netherlands and Germany now mandate these closures for closed-loop packaging systems.
- Pressure Sensitive:Acrylic or synthetic rubber adhesives provide instant tack without activation equipment. E-commerce fulfillment fragmentation multiplies SKU complexity across thousands of direct-to-consumer brands with varying surface energy specifications.
- Solvent Based:Toluene or MEK-carried natural rubber delivers aggressive adhesion to low-surface-energy substrates. EPA volatile organic compound regulations and OSHA workplace exposure limits are accelerating line conversions to water-based alternatives.
Pressure sensitive dominates installed base; water activated climbs the fastest.
End User:
Procurement authority fragmentation reshapes contract structures and technical specification processes.
- Retail:Branded authentication and theft deterrence drive custom-printed tape specifications. German automotive parts suppliers demand color-coded identification on secondary packaging.
- Manufacturing:Automated case-sealing lines prioritize adhesive coatability and downtime minimization. Hot melt formulations sustain margin pools where speed exceeds shear resistance thresholds.
- E-Commerce:Direct-to-consumer brands fragment demand across specialized performance requirements. Third-party logistics operators now specify tamper-evident and RFID-enabled constructions for high-value electronics.
- Logistics:Pallet stabilization and load containment absorb heavy-duty reinforced constructions. Pharmaceutical distribution networks require validated adhesive performance across temperature cycling extremes.
Manufacturing leads on scale; e-commerce leads on momentum.
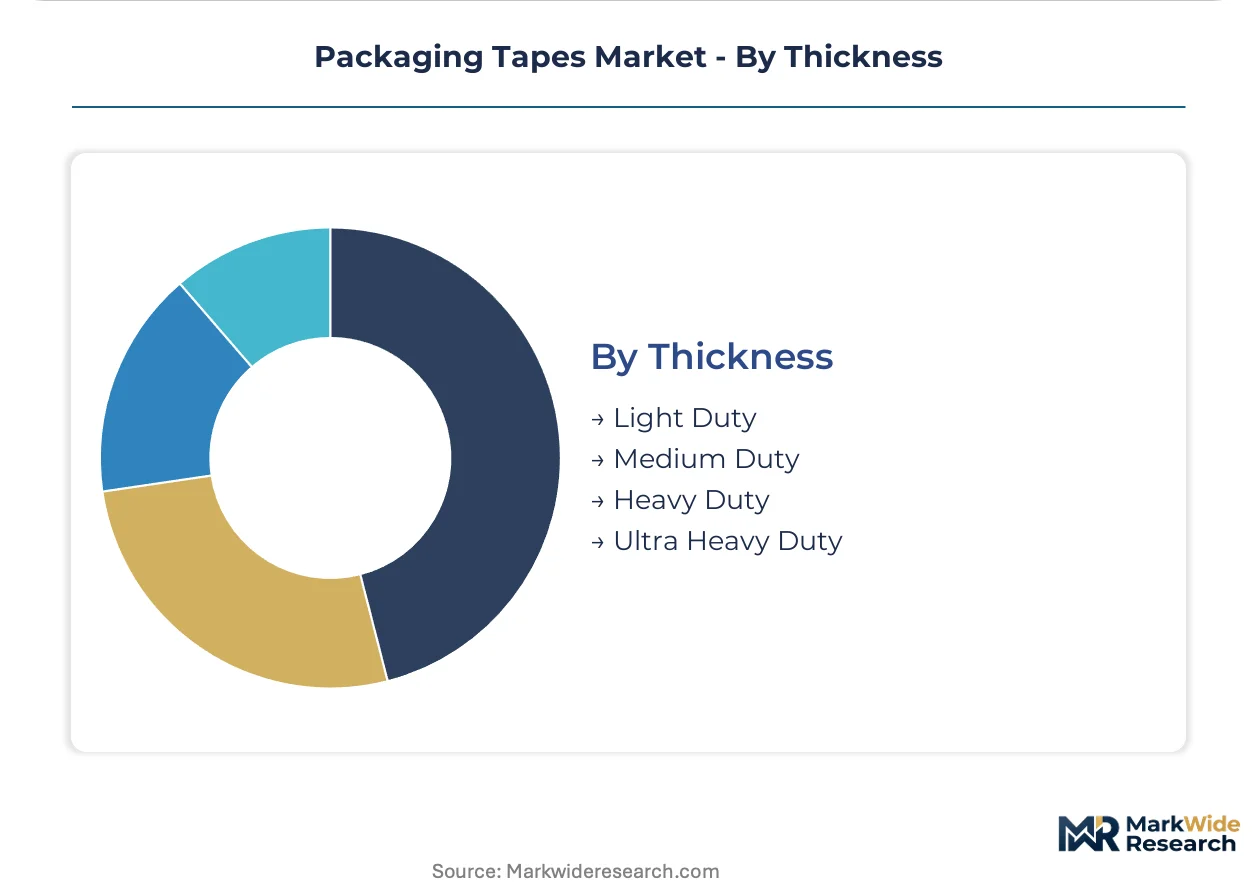
Thickness:
Mechanical load requirements and handling durability segment price bands and converter margin structures.
- Light Duty:Sub-40 micron constructions secure lightweight consumer goods with minimal handling stress. German pharmaceutical cold-chain packaging specifies these for secondary carton closure.
- Medium Duty:40-80 micron films balance tensile strength with cost efficiency for standard corrugated sealing. Retail distribution absorbs volume for general merchandise fulfillment.
- Heavy Duty:80-120 micron reinforced backings withstand pallet stacking and fork truck impacts. Automotive parts export packaging in Germany requires this grade for abrasion resistance.
- Ultra Heavy Duty:Exceeding 120 microns with fiberglass or synthetic yarn reinforcement for extreme load containment. Logistics operators deploy these for irregular freight stabilization.
Medium duty leads on scale; ultra heavy duty leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates specialized pharmaceutical and automotive packaging tape demand while the United States fragments procurement across thousands of e-commerce fulfillment operators. China scales manufacturing capacity for export-oriented converters. India builds domestic supply under industrial policy incentives. The Netherlands mandates closed-loop recycling compliance that reshapes adhesive specifications.
Germany
Automotive parts export packaging and pharmaceutical cold-chain logistics absorb temperature-stable tape grades validated across -20°C to +40°C cycling. ECHA scrutiny of phthalate plasticizers under REACH redirects converter investment toward citrate-derived bio-plasticizers. The Stuttgart automotive cluster and Frankfurt pharmaceutical distribution hubs specify custom-printed, color-coded authentication tapes for supplier traceability.
United States
EPA volatile organic compound regulations and OSHA workplace exposure limits for toluene and methyl ethyl ketone accelerate solvent-to-water-based adhesive line conversions. California's SB 54 extended producer responsibility rules reshape material specifications for corrugated recycling streams. The Chicago-Milwaukee industrial corridor and Dallas-Fort Worth logistics hub concentrate automated case-sealing equipment deployment for e-commerce fulfillment.
China
Dual carbon goals and MEE emissions standards pressure coating operations toward energy-efficient drying systems and reduced solvent throughput. The Yangtze River Delta and Pearl River Delta manufacturing belts supply biaxially oriented polypropylene substrates and synthetic rubber adhesives to regional converters. Shanghai and Shenzhen fulfillment centers drive volume for pressure-sensitive carton sealing applications.
India
The PLI scheme for packaging creates localized supply capacity serving export-oriented pharmaceutical and textile producers. BIS standards for adhesive performance and substrate specifications guide converter quality investments. The Maharashtra-Gujarat industrial corridor and Bangalore-Chennai pharmaceutical belt concentrate tape demand for secondary packaging and cold-chain distribution.
Netherlands
Major paperboard mills mandate repulpable water-activated tape closures for closed-loop corrugated recycling systems. EU Green Deal compliance frameworks redirect procurement toward starch-based adhesive formulations and kraft paper backings. The Rotterdam-Antwerp logistics cluster and Eindhoven e-commerce fulfillment networks specify gummed tape constructions that meet mill gate contamination thresholds.
Packaging Tapes Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across adhesive chemistry, substrate manufacturing, and distribution reach. The vendor base stratifies into three tiers: integrated material-science conglomerates with captive polymer supply, mid-scale converters with regional coating capacity, and niche specialists in sustainable or high-performance formulations. Consolidation pressure concentrates among solvent-dependent operators facing capital-intensive line reconfiguration costs. Dominant competitive moves include backward integration into tackifier resin supply and geographic expansion through distributor network acquisition.
Among diversified adhesive-science conglomerates, 3M and Henkel AG & Co. KGaA occupy positions spanning industrial, consumer, and medical tape applications through extensive patent portfolios. Tesa SE exemplifies the European pure-play specialist archetype with concentrated expertise in pressure-sensitive adhesive systems. Nitto Denko Corporation anchors Asia-Pacific supply relationships for electronics and automotive OEM specifications. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| tesa SE |
| Berry Global Inc. |
| 3M |
| Saint-Gobain |
| Shurtape Technologies, LLC |
| Avery Dennison Corporation |
| Intertape Polymer Group Inc. |
| Henkel AG & Co. KGaA |
| Nitto Denko Corporation |
| Others |
Value Chain & Pricing Dynamics
Polypropylene resin feedstock costs cascade through converter margin structures into three-tier pricing stratification across premium, standard, and economy tape grades, with German automotive and pharmaceutical buyers absorbing premium tiers while Asian export-oriented producers compete at compressed price floors.
Pricing Analysis
Capacity additions in China and India are reshaping price floors for standard-grade pressure-sensitive tapes, forcing European converters toward specialty formulations. Three-tier pricing separates pharmaceutical-validated cold-chain grades from general industrial sealing and commodity carton closure. Price differentiation hinges on REACH-compliant bio-plasticizer certification and volume scale commitments. Cost compression in commodity hot melt tapes is intensifying because of polypropylene resin volatility, with third-party logistics operators exhibiting highest price sensitivity and German automotive OEMs showing least.
Supply Chain Analysis
Freight cost inflation across Asia-Europe routes is redirecting regional sourcing decisions toward localized coating capacity. Supply concentrates in China, Germany, and the United States for biaxially oriented polypropylene substrates and synthetic rubber adhesive feedstocks. Raw material dependencies rest on petrochemical-derived polypropylene, specialty tackifier resins, and acrylic monomer supplies. Single-source vulnerability in European tackifier production creates structural risk. Distribution runs through converter-direct relationships with major e-commerce fulfillment operators and automotive tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Packaging tapes function as a regulatory compounder where EU Green Deal mandates and REACH chemical restrictions continuously reshape formulation investment and procurement specifications.
For Market Incumbents: Hedge solvent-based coating exposure by accelerating water-based line conversions before EPA enforcement intensifies. Secure captive supply of citrate-derived bio-plasticizers to defend margin position against feedstock volatility. Backward integration into tackifier resin production anchors cost visibility for pharmaceutical-grade PVC backing formulations. For New Entrants and Emerging Players: Capture fragmented direct-to-consumer brand demand through specialized B2B procurement platforms serving mid-volume e-commerce fulfillment operators. India's PLI scheme for packaging creates the most penetrable geographic entry point for export-oriented pharmaceutical and textile producers. Lead with water-activated gummed tape formulations aligned to Dutch and German mill gate repulpability requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where solvent-dependent operators face capital-intensive line reconfiguration costs and adhesive formulation chemist scarcity commands premium compensation. Long-term viability favors converters with demonstrated REACH compliance pathways and established automotive cold-chain validation credentials. Watch for inflection signals in California SB 54 extended producer responsibility enforcement triggering corrugated recycling specification shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Adhesive Line Conversion | EPA VOC regulations and REACH solvent restrictions mandate coating technology transition. |
| Bio-Plasticizer Supply Agreement | Citrate and epoxidized vegetable oil chemistries replace restricted phthalates in PVC backings. |
| Cold-Chain Validation Investment | German pharmaceutical distribution requires -20°C to +40°C adhesive performance certification. |
| Direct Procurement Platform Launch | B2B marketplaces disintermediate traditional distributors for e-commerce fulfillment operators. |
| RFID-Enabled Tape Development | Smart packaging integration meets track-and-trace requirements in high-value electronics distribution. |
Study Parameters
Multiple input streams — primary interviews with tape converter plant managers, adhesive formulation chemists, and automotive packaging engineers; secondary validation through customs trade data, EPA enforcement records, and ECHA substance restriction filings; plus SEC 10-K disclosures from diversified adhesive-science conglomerates — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across product type, adhesive chemistry, end-user industry, and regional regulatory cluster dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from modeled segment trajectories incorporating EU Green Deal compliance timelines, India's PLI scheme capacity buildout assumptions, and e-commerce fulfillment network expansion patterns.
Underlying measurement precision varies by segment; water-activated tape and pharmaceutical cold-chain grades carry tighter precision than commodity hot melt volumes. Forecasts reflect assumptions about regulatory enforcement intensity and petrochemical feedstock stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Edge Band Tapes Market
Tapes
Dicing Tapes Market
Tapes
Invisible Tapes Market
Tapes
Strapping Tapes Market
Tapes
Void Pattern Tamper-Evident Tapes Market
Tapes
Carbon Tapes Market
Tapes
Wing Walk Tapes Market
Tapes
Freezer Tape Market
Tapes
Removal Strips Market
Tapes
Paper Masking Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
UV Tapes Market
Tapes
Washi Tapes Market
Tapes
Splicing Tapes Market
Tapes
Filament Tapes Market
Tapes
Nylon Cable Ties Market