
 Security Tape Market | 2026-2036
Security Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Security Tape Market Outlook
Single-source resin procurement is rebalancing toward multi-source polymer agreements as supply volatility reshapes cost structures. 3M Company leverages its captive acrylic adhesive technology to sustain margin stability across polyester and PVC grades. Tesa SE anchors European automotive logistics with specialized tamper-evident formats. Avery Dennison Corporation differentiates through RFID-integrated security tape architectures for high-value parcel tracking.
Security tape denotes pressure-sensitive adhesive laminates engineered with controlled tensile strength, release liner compatibility, and visible fracture patterns upon removal, manufactured through solvent-based or hot-melt coating processes on oriented polyester or calendered PVC backings. The product serves to detect unauthorized access, deter pilferage, and maintain chain-of-custody documentation in transit and storage environments. Polyester security tape leads product type demand due to dimensional stability and printability for barcode serialization, while biodegradable formulations represent the fastest-growing segment as EU corporate sustainability commitments harden procurement specifications. Parcel sealing dominates application volume, though tamper-evident formats command superior unit margins from pharmaceutical and electronics end users.
FDA 21 CFR Part 11 and EU GDP guidelines shape pharmaceutical logistics tape requirements through audit trail and seal integrity mandates. REACH compliance and evolving EU Green Deal packaging thresholds are forcing substrate reformulation toward reduced solvent content and recyclable adhesive systems. California SB 54 extended producer responsibility rules add compliance layers for e-commerce shippers serving the US West Coast. Stakeholders must monitor how tightening extended producer responsibility frameworks in multiple jurisdictions will redistribute cost and certification burdens across the value chain.
Market Dynamics
E-commerce fulfillment networks are forcing rapid specification upgrades as tamper-evident sealing becomes a non-negotiable cost of customer retention rather than a discretionary logistics add-on.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Cross-border shippers must demonstrate material traceability, accelerating demand for certified tamper-evident formats that satisfy audit requirements.
- Pharmaceutical cold chain integrity:FDA 21 CFR Part 11 mandates create binding specifications for seal documentation in temperature-controlled distribution.
- Biodegradable substrate innovation:EU corporate sustainability commitments are hardening procurement specifications toward compostable adhesive systems.
Market Restraints
- Acrylic resin supply volatility:Petrochemical feedstock fluctuations compress margin stability for solvent-based coating operations.
- REACH compliance burden:ECHA substance restrictions force continuous reformulation cycles that extend product development timelines.
- Digital authentication substitution:Blockchain-based custody tracking and NFC-enabled smart packaging divert budget allocation from physical tamper-evidence.
Strategic Opportunities
- India e-commerce logistics:BIS certification requirements and DGFT import documentation rules create specification gaps that specialized security tape formats can fill.
- RFID-tape convergence:Electronics manufacturers in South Korea and Taiwan are piloting integrated RFID-antenna laminates for high-value component tracking.
- California SB 54 extended producer responsibility:West Coast e-commerce shippers face new compliance layers that favor recyclable adhesive systems with documented end-of-life pathways.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise in solvent-reduced and bio-based systems remains concentrated among a narrow cohort of specialists.
- Multi-jurisdiction certification timelines:Simultaneous FDA, EMA, and national regulator approvals for pharmaceutical-grade formats extend commercialization cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Security Tape Market |
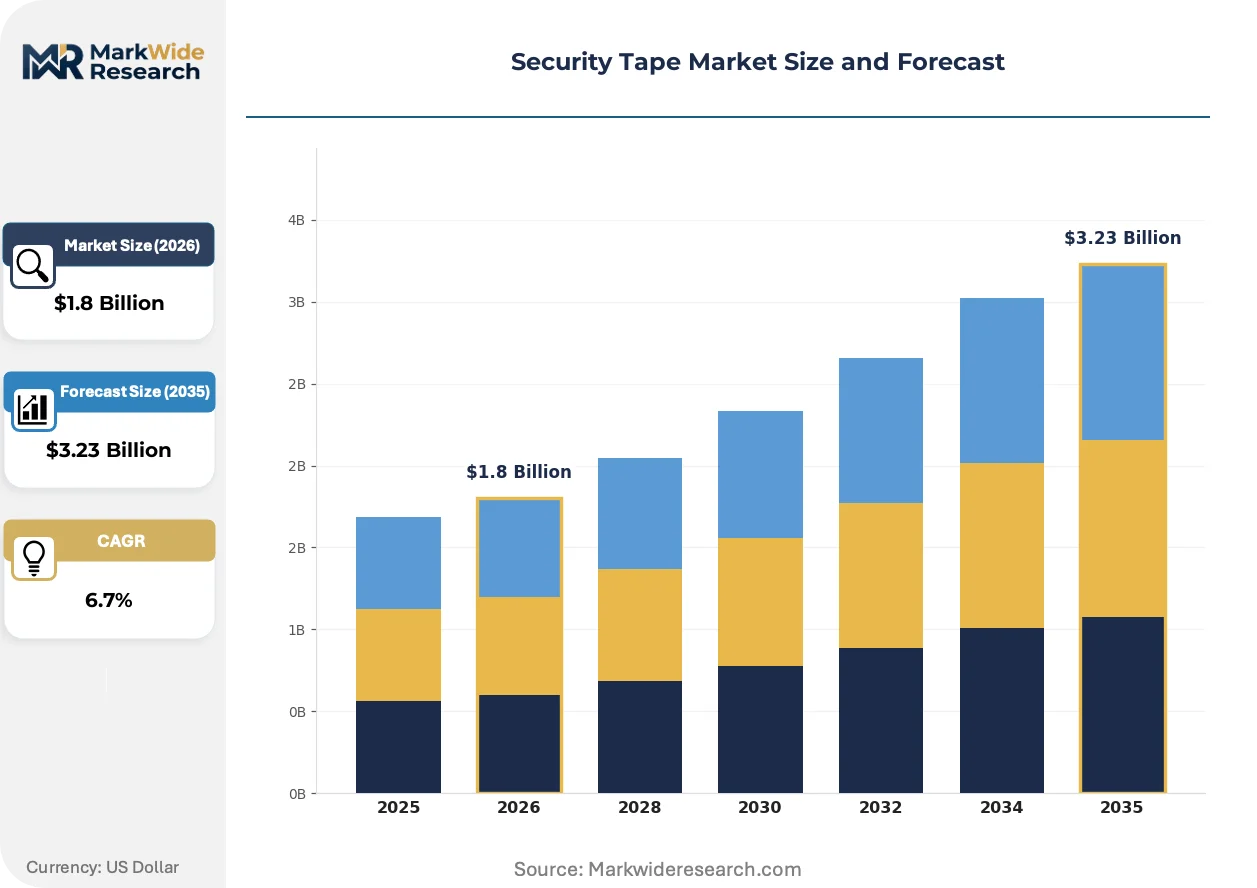
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyester, PVC, Paper, Biodegradable Application: Parcel Sealing, Tamper Evident, Surface Protection, Labeling End User: Retail, E-commerce, Logistics, Manufacturing Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | 3M Company, Avery Dennison Corporation, Tesa SE, Intertape Polymer Group, DS Smith plc, H.B. Fuller Company, Essentra Plc., Brady Corporation, Seal King, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Security Tape Market Strategic Shifts
Active material science breakthroughs are compressing the performance gap between conventional petrochemical substrates and next-generation bio-derived alternatives, while regulatory pressure accelerates specification convergence across previously siloed end-use verticals.
Micro-encapsulated indicator chemistry is converging with printable electronics to create visual tamper-evidence that also transmits digital authentication signals. Pharmaceutical distributors in Germany and the Netherlands are piloting these hybrid formats for high-value biologics shipments. The technology is converging with existing barcode infrastructure, reducing retrofit costs for legacy warehouse management systems.
REACH Annex XVII restrictions on persistent organic pollutants are forcing adhesive reformulation toward water-based and UV-curable systems. Coaters with captive solvent recovery infrastructure face stranded asset risk as ECHA consultation timelines compress. Automotive parts exporters in the Czech Republic and Slovakia are absorbing premium pricing for compliant formats to maintain EU market access.
Consolidated buying desks at major e-commerce platforms are compressing supplier qualification cycles and demanding volume-tiered performance guarantees. Third-party logistics providers in Poland and Hungary are displacing fragmented local tape distributors with direct polymer converter relationships. This concentration is most visible in the parcel sealing segment, where platform procurement teams now specify tamper-evidence as a service-level agreement metric rather than a materials purchase.
Security Tape Market Segmentation
Security tape procurement specifications diverge sharply across end-use verticals, with pharmaceutical and automotive logistics demanding FDA-validated formats while e-commerce fulfillment prioritizes cost-scalable tamper-evidence. Material selection and adhesive chemistry must align with jurisdiction-specific compliance burdens rather than performance alone.
Product Type:
FDA 21 CFR Part 11 and EU GDP guidelines impose distinct certification burdens: polyester and PVC grades for pharmaceutical cold chain, biodegradable formats for EU Green Deal procurement mandates.
- Polyester:Oriented polyethylene terephthalate backing delivers dimensional stability and thermal resistance for barcode serialization in automated sorting environments. German automotive parts exporters specify this grade for cross-border shipments to maintain EMA audit trail compliance. FDA-validated solvent-acrylic laminates dominate US pharmaceutical distribution.
- PVC:Calendered polyvinyl chloride offers conformability to irregular carton surfaces and tear-initiation predictability for visual tamper-evidence. Czech and Slovak automotive hubs absorb premium pricing for REACH-compliant formulations to preserve EU market access. ECHA Annex XVII restrictions on plasticizers force continuous reformulation cycles.
- Paper:Kraft and glassine backings serve short-cycle retail applications with minimal environmental exposure requirements.
- Biodegradable:Compostable adhesive systems from bio-derived feedstocks harden procurement specifications under EU corporate sustainability commitments.
Leading the category by volume: polyester. Growing fastest: biodegradable.
Application:
Margin structures stratify across application tiers, with tamper-evident formats commanding certification premiums while parcel sealing competes on throughput economics.
- Parcel Sealing:High-tack acrylic laminates engineered for corrugated fiberboard adhesion at line speeds exceeding 100 packages per minute. Consolidated buying desks at major e-commerce platforms specify this as a service-level agreement metric. Volume-tiered performance guarantees compress supplier qualification cycles.
- Tamper Evident:Controlled tensile strength and fracture-pattern engineering detect unauthorized access through visible substrate destruction. Pharmaceutical distributors in the Netherlands pilot micro-encapsulated indicator chemistry for high-value biologics. FDA and EMA dual approvals extend commercialization timelines.
- Surface Protection:Low-adhesion formulations for temporary guarding of finished goods during transit and warehouse handling.
- Labeling:Print-receptive topcoats compatible with thermal transfer and inkjet serialization systems.
Highest unit margins concentrate in tamper-evident. Parcel sealing generates largest absolute volume.
End User:
Procurement sophistication varies by end-user maturity, with logistics providers displacing fragmented distributors through direct polymer converter relationships.
- E-commerce:Fulfillment networks treat tamper-evident sealing as non-negotiable customer retention infrastructure. Third-party logistics providers in Poland and Hungary consolidate specification authority. California SB 54 extended producer responsibility rules favor recyclable adhesive systems.
- Logistics:Third-party carriers and freight forwarders specify chain-of-custody documentation formats for high-value cargo. BIS certification requirements in India create specification gaps for specialized security tape formats.
- Retail:In-store packaging and loss-prevention applications with lower compliance burden than pharmaceutical or electronics verticals.
- Manufacturing:Work-in-process protection and finished goods sealing across automotive, electronics, and consumer goods production.
Fastest volume expansion: e-commerce. Most stringent specification environment: logistics serving pharmaceutical verticals.
Distribution Channel:
Channel selection reflects order scale and technical support requirements, with wholesale maintaining dominance in industrial procurement.
- Wholesale:Polymer converters and industrial distributors serve high-volume accounts with formulation customization and technical field support. Direct relationships displace fragmented local tape distributors in Central European logistics corridors.
- Online:E-procurement platforms capture standard-grade parcel sealing volume from small and mid-sized shippers. Specification authority concentrates at platform buying desks rather than end-user procurement teams.
- Specialty Stores:Regional converters and packaging suppliers serving niche applications with short lead time requirements.
- Supermarkets:Consumer-format security tape for retail loss prevention and small-scale shipping needs.
Channel concentration: wholesale for industrial volume, online for fragmented e-commerce accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates security tape demand through its dense logistics corridor and automotive parts export volume. E-commerce fulfillment centers across multiple jurisdictions are accelerating specification upgrades for tamper-evident sealing solutions.
Germany
Automotive parts exporters and pharmaceutical cold chain operators drive specification intensity. EMA audit trail mandates and EU GDP guidelines bind seal documentation requirements. The Rhine-Ruhr logistics corridor anchors converter relationships for cross-border shipment compliance.
United States
FDA 21 CFR Part 11 compliance and California SB 54 extended producer responsibility rules reshape procurement specifications. West Coast e-commerce shippers face layered certification requirements for recyclable adhesive systems. The Pacific Northwest distribution cluster absorbs premium pricing for documented end-of-life pathways.
China
E-commerce platform consolidation and electronics manufacturing clusters generate volume demand for barcode-serializable formats. MIIT standards and GB compliance frameworks govern adhesive system specifications. The Yangtze River Delta logistics hub pilots RFID-integrated laminates for high-value component tracking.
India
BIS certification requirements and DGFT import documentation rules create specification gaps for specialized formats. E-commerce logistics expansion outpaces domestic converter capacity. Mumbai-Pune and Delhi-NCR corridors attract direct polymer relationships from third-party logistics providers.
Netherlands
Pharmaceutical distributors pilot micro-encapsulated indicator chemistry for high-value biologics shipments. REACH Annex XVII restrictions force continuous adhesive reformulation cycles. The Rotterdam-Antwerp port cluster serves as a compliance gateway for EU cross-border tamper-evident formats.
Security Tape Market Competitive Environment
Portfolio diversification dominates the current landscape as coating specialists extend format ranges to capture e-commerce platform procurement consolidation. The vendor base stratifies across three tiers: integrated polymer converters with captive adhesive technology, regional specialists in pharmaceutical-grade certification, and commodity coaters serving parcel sealing volume. Two archetypes anchor competitive positioning: technology licensors with proprietary indicator chemistry and scale operators with direct platform relationships. M&A activity and capacity expansion in biodegradable substrate lines represent the dominant competitive vectors.
Within the integrated technology tier, 3M Company and Avery Dennison Corporation exemplify divergent specialization paths. Tesa SE occupies a position anchored in European automotive logistics certification. These three entities represent the spectrum from captive adhesive chemistry to RFID-convergent architectures, with each archetype responding to distinct procurement authority concentrations across e-commerce platforms and pharmaceutical distributors.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Tesa SE |
| Intertape Polymer Group |
| DS Smith plc |
| H.B. Fuller Company |
| Essentra Plc. |
| Brady Corporation |
| Seal King |
| Others |
Value Chain & Pricing Dynamics
Captive adhesive technology integration anchors pricing power for security tape manufacturers, with 3M's solvent-acrylic laminates and Tesa's European automotive certifications demonstrating how in-house polymer chemistry sustains margin premiums against commodity coaters.
Pricing Analysis
Warranty-backed certification bundling separates pharmaceutical-grade formats from unbundled parcel sealing tiers, with FDA-validated polyester laminates commanding substantial premiums over standard corrugated adhesion products. Price differentiation rests on REACH compliance tier and volume scale, with e-commerce platform procurement teams extracting performance guarantees at throughput economics that compress mid-tier supplier margins. Pricing pressure intensifies in biodegradable substrate lines as EU Green Deal thresholds accelerate reformulation costs. Logistics providers serving pharmaceutical verticals exhibit lowest price sensitivity due to audit trail liability exposure, while small e-commerce shippers drive commoditization in standard parcel sealing.
Supply Chain Analysis
Domestic-content mandates in India and China's MIIT standards are reshaping sourcing patterns, with BIS certification requirements forcing local converter relationships for cross-border shipment compliance. Raw material supply concentrates in Germany, China, and the United States, with acrylic resin feedstocks and oriented polyester backings drawing from petrochemical corridors near the Rhine-Ruhr and Yangtze River Delta. Single-source vulnerability in solvent-based adhesive chemistries threatens coaters lacking captive recovery infrastructure. Distribution runs through wholesale polymer converters with technical field support, though e-procurement platforms capture fragmented e-commerce volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The security tape market functions as a vertical-integration race, with players pursuing captive adhesive technology to escape petrochemical feedstock volatility and sustain margin stability across regulatory reformulation cycles.
For Market Incumbents: Deepen solvent-reduced and bio-based formulation capabilities to preempt REACH Annex XVII restrictions that threaten stranded asset risk for conventional coaters. Extend direct platform relationships with consolidated e-commerce buying desks to defend against commodity displacement. Prioritize RFID-tape convergence R&D to counter blockchain-based custody tracking substitution threats in high-value electronics logistics.
For New Entrants and Emerging Players: Begin with biodegradable substrate specialization targeting EU corporate sustainability procurement mandates, where specification gaps favor agile reformulation specialists over legacy petrochemical coaters. Concentrate initial penetration on India's BIS certification-constrained logistics corridors, where domestic converter capacity lags e-commerce expansion. Pursue technical partnership routes with third-party logistics providers displacing fragmented distributors in Poland and Hungary.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialty pharmaceutical-grade certification assets, where FDA-EMA dual approval timelines create acquisition premiums for compliant format portfolios. Long-term viability favors coating specialists with demonstrated REACH reformulation agility and established automotive logistics relationships in Germany and the Czech Republic. Monitor ECHA consultation timelines as inflection signals for solvent-reduced system adoption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Adhesive Production | Captive solvent-acrylic technology insulates 3M and Avery Dennison from petrochemical feedstock volatility. |
| Biodegradable Substrate Capacity Expansion | EU Green Deal packaging thresholds harden procurement specifications toward compostable adhesive systems. |
| RFID-Tape Convergence Development | South Korean and Taiwanese electronics manufacturers pilot integrated antenna laminates for component tracking. |
| Pharmaceutical-Grade Certification Investment | FDA 21 CFR Part 11 and EMA dual approvals extend commercialization timelines but command substantial pricing premiums. |
| Direct Platform Relationship Establishment | Consolidated e-commerce buying desks at major platforms now specify tamper-evidence as service-level agreement metrics. |
Study Parameters
Multi-period observation of REACH reformulation timelines, ECHA consultation patterns, and e-commerce platform procurement consolidation anchored the trend analysis, supplemented by interviews with adhesive formulation chemists, polymer converter operations directors, third-party logistics procurement leads, and pharmaceutical distributor quality assurance managers. Secondary validation drew from EMA regulatory filings, EU Packaging and Packaging Waste Regulation drafts, customs trade data for acrylic resin movements, and SEC disclosures from integrated coating specialists. Bottom-up segment sizing triangulated against top-down market envelope checks.
The input-output matrix framed demand modeling across product type, application tier, end-user vertical, and regional regulatory cluster dimensions throughout the projection horizon. CAGRs derived from elasticity-adjusted volume trajectory analysis incorporating EU Green Deal implementation pace and pharmaceutical cold chain expansion indicators. Industry-specific forecast inputs included BIS certification queue lengths in India and MIIT standards evolution in China.
Underlying measurement precision varies by segment; biodegradable substrate forecasts carry tighter precision than emerging RFID-tape convergence estimates due to pilot-scale uncertainty. Forecasts reflect documented assumptions regarding regulatory implementation timelines and platform procurement consolidation velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Invisible Tapes Market
Tapes
Foam Tape Market
Tapes
Nano Tapes Market
Tapes
Nylon Cable Ties Market
Tapes
Flocking Tape Market
Tapes
Non Woven Water Blocking Tape Market
Tapes
Lacing Tape Market
Tapes
Raffia Tape Stretching Line Market
Tapes
Automotive Adhesive Tapes Market
Tapes
Medical Tapes Market
Tapes
Thermal Transfer Tapes Market
Tapes
Electrical Shielding Tape Market
Tapes
Gaffers Tape Market
Tapes
Tape Dispenser Market
Tapes
Tear Tape Dispenser Market
Tapes
PVC Tapes Market