
 Global Hereditary Cancer Testing Market | 2026-2036
Global Hereditary Cancer Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hereditary Cancer Testing Market Foresight
The price-performance gap between comprehensive multigene panels and single-site mutation assays is hardening into a durable market split. Myriad Genetics leverages its proprietary variant classification database to sustain premium positioning in hereditary risk assessment. Illumina competes by anchoring the upstream sequencing instrument layer, while Exact Sciences differentiates through integrated cancer screening platforms that bridge somatic and germline testing workflows.
Hereditary cancer testing identifies germline mutations associated with elevated malignancy risk through DNA analysis of blood or saliva specimens, employing next-generation sequencing, PCR amplification, and comparative hybridization techniques to detect pathogenic variants across susceptibility genes. The primary commercial purpose centers on stratifying individual and familial cancer probability to inform surveillance protocols, prophylactic interventions, and therapeutic selection. BRCA1/BRCA2 and Lynch syndrome panels occupy the mature revenue core, while PALB2 and TP53 testing represents the fastest-expanding category as evidence accumulates for pancreatic and Li-Fraumeni spectrum malignancies. Next-generation sequencing dominates technology deployment, though MLPA retains critical utility for large genomic rearrangement detection where short-read platforms underperform.
FDA oversight of laboratory-developed tests, combined with CMS reimbursement determinations and state-level genetic counselor licensing requirements, shapes market access and clinical adoption trajectories across the United States. EMA's In Vitro Diagnostic Regulation and GDPR constraints on genetic data processing create parallel compliance architectures in European markets. Stakeholders must monitor evolving payer evidence requirements for expanded gene panels and prepare for potential harmonization conflicts between FDA and international regulatory frameworks on variant interpretation standards.
Market Dynamics
The hereditary cancer testing market pivots on regulatory classification decisions that compress premarket timelines for multigene panels while fragmenting reimbursement pathways across commercial payers and government programs.
Growth Catalysts
- FDA Class II Device Pathway:The streamlined 510(k) clearance process for multigene panels accelerates commercial launch timelines and reduces regulatory capital requirements for test developers.
- BRCA and Lynch Syndrome Coverage Expansion:Commercial payers in the United States have broadened prior authorization criteria, removing age and family history restrictions that previously limited patient access.
- Next-Generation Sequencing Cost Curves:Declining per-base sequencing costs enable laboratories to offer expanded gene panels at price parity with legacy single-site assays.
Market Restraints
- Variant Interpretation Bottlenecks:Shortage of board-certified genetic counselors creates interpretation backlogs that extend report turnaround times beyond clinically actionable windows.
- Reimbursement Code Fragmentation:CMS maintains separate coding stacks for BRCA1/BRCA2 versus expanded panels, creating administrative friction that discourages comprehensive testing adoption.
- Large Genomic Rearrangement Detection Gaps:Short-read sequencing platforms underperform for exon-level deletions and duplications, forcing laboratories to maintain parallel MLPA workflows.
Strategic Opportunities
- Li-Fraumeni Syndrome Penetration:TP53 testing for pediatric and early-onset malignancies remains underutilized in Brazil and Mexico, where private laboratory networks are building capacity.
- Somatic-Germline Integration:Tumor-normal sequencing workflows are converging with hereditary risk assessment, enabling laboratories to capture both testing categories from single biopsy submissions.
- Direct-to-Consumer Channel Development:Telehealth-integrated genetic counseling platforms in Australia and Canada are opening access pathways outside traditional oncology clinic referrals.
Industry Challenges
- Cross-Border Data Transfer Constraints:GDPR Article 9 restrictions on genetic data processing complicate cloud-based variant classification for European laboratories using US-hosted databases.
- Laboratory Information System Integration:Legacy electronic health record architectures in community oncology practices lack structured fields for polygenic risk scores, forcing manual data entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hereditary Cancer Testing Market |
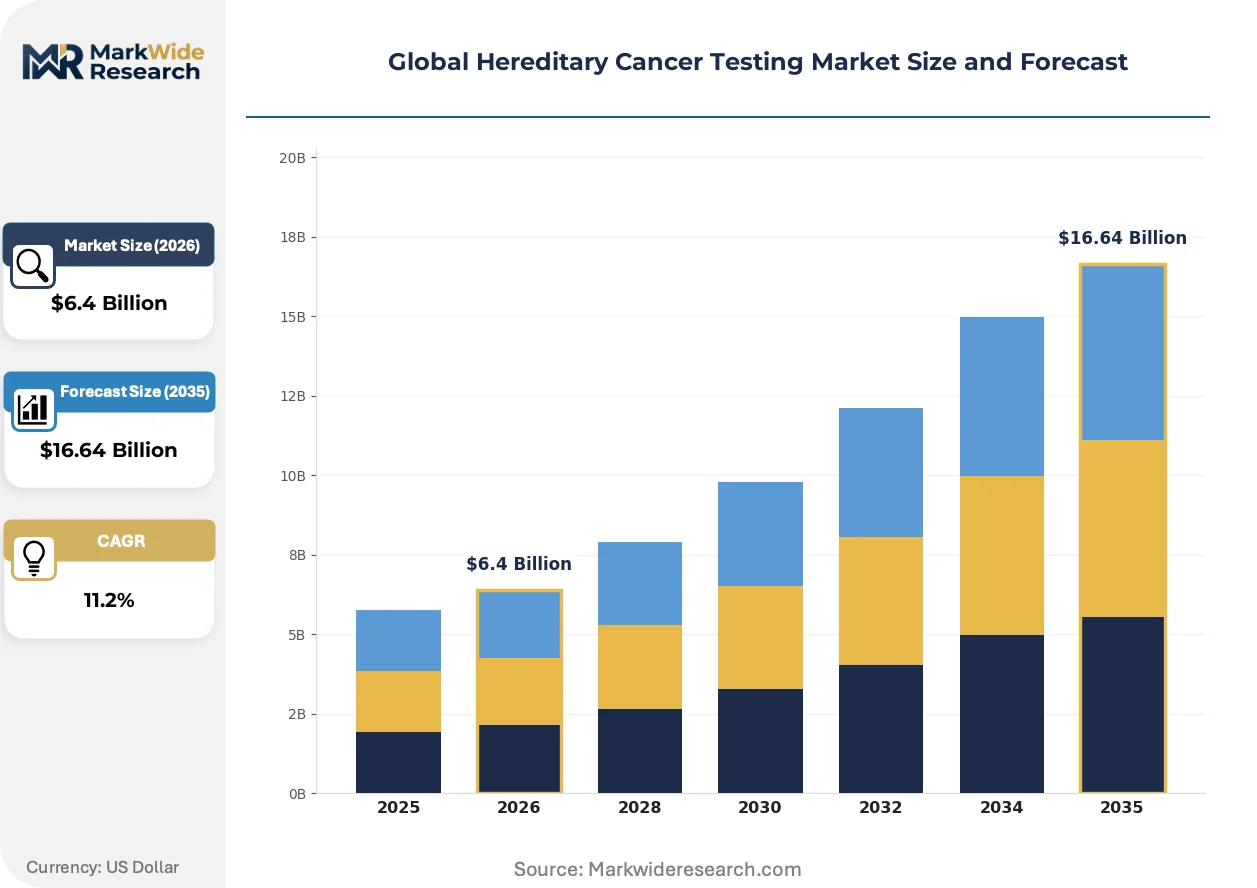
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $16.64 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: BRCA1/BRCA2, Lynch Syndrome, PALB2, TP53, CHEK2, ATM Technology: Next-Generation Sequencing, PCR, Microarray, Sanger Sequencing, MLPA, DNA Hybridization Use Case: Risk Assessment, Diagnosis, Prognosis, Treatment Planning, Familial Screening, Carrier Testing End User: Genetic Counselors, Oncology Clinics, Diagnostic Laboratories, Research Institutions, Specialty Clinics |
| Companies Covered | Thermo Fisher Scientific, Qiagen, Myriad Genetics, Guardant Health, Roche Diagnostics, Invitae Corporation, Quest Diagnostics, Exact Sciences, Illumina, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hereditary Cancer Testing Market Shifts & Advancements
Artificial intelligence is penetrating variant classification workflows while regulatory harmonization efforts accelerate across North Atlantic markets, compressing the gap between analytical validity and clinical utility evidence standards.
Long-read sequencing platforms from Pacific Biosciences and Oxford Nanopore are integrating into hereditary cancer workflows to resolve complex structural variants and pseudogene regions that confound short-read alignments. Reference laboratories in the United States and Germany are piloting these systems for BRCA1 and PMS2 analysis. This capability is integrating with existing NGS pipelines to eliminate confirmatory testing steps and reduce variant of uncertain significance rates.
EMA's In Vitro Diagnostic Regulation (IVDR) is reclassifying hereditary cancer tests from self-certified to notified body-reviewed devices, forcing manufacturers to generate clinical performance studies that many legacy assays lack. German and French laboratories are consolidating supplier relationships to reduce audit surface area. High-complexity reference laboratories with established quality management systems are capturing volume from smaller hospital labs that cannot absorb compliance costs.
Oncology practices are unbundling genetic counseling from testing procurement, contracting directly with telehealth platforms while maintaining specimen collection in-house. This disintermediation pressures traditional laboratory sales organizations that bundled pre-test counseling with technical services. The shift is most visible in the United States, where commercial payer contracts increasingly require independent genetic counseling documentation prior to authorizing high-risk panel testing.
Global Hereditary Cancer Testing Market Segmentation
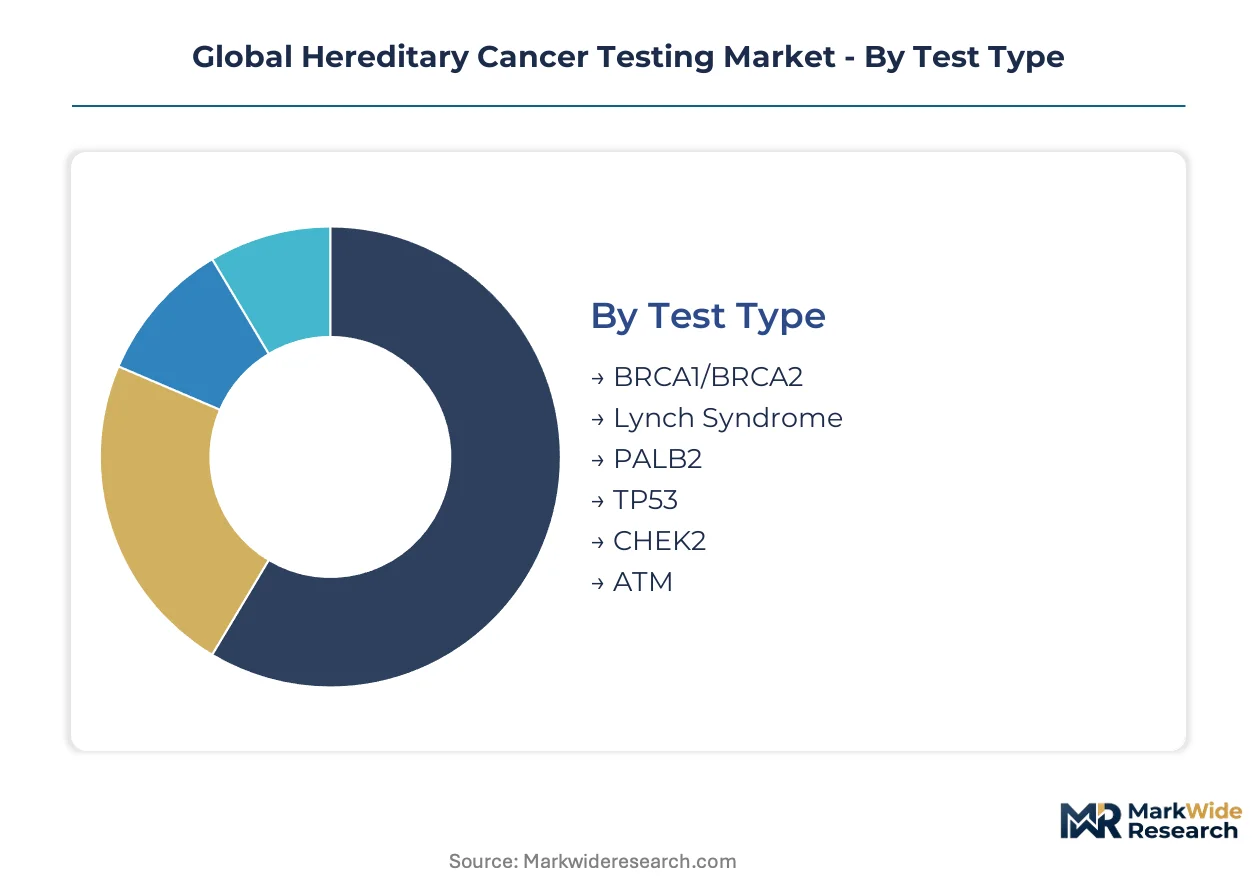
Test portfolios in hereditary cancer diagnostics stratify sharply between mature, high-volume assays and emerging gene targets where evidence accumulation lags reimbursement expansion. Technology choices and end-user channel selection further fragment competitive positioning across laboratory networks and clinical settings.
Test Type:
Volume concentration anchors the revenue base while premium positioning shifts toward underpenetrated gene targets with expanding clinical utility evidence.
- BRCA1/BRCA2:Dual-gene panels detect pathogenic variants in breast and ovarian cancer susceptibility genes through targeted NGS or Sanger confirmation. United States commercial payers have eliminated prior authorization barriers for patients with personal or family history of breast, ovarian, pancreatic, or prostate malignancies. Mature deployment sits with BRCA1/BRCA2. Newer deployment is concentrated in PALB2.
- Lynch Syndrome:Mismatch repair gene panels (MLH1, MSH2, MSH6, PMS2, EPCAM) identify hereditary colorectal and endometrial cancer risk through microsatellite instability correlation. Diagnostic laboratories in Germany and France are consolidating Lynch syndrome testing with tumor immunohistochemistry reflex protocols to capture both somatic screening and germline confirmation from single patient encounters.
- PALB2:Partner and localizer of BRCA2 gene testing is gaining traction for pancreatic cancer risk stratification and breast cancer susceptibility beyond BRCA-negative families.
- TP53:Li-Fraumeni syndrome detection remains concentrated in pediatric oncology and early-onset sarcoma cohorts with limited penetration in Latin American private laboratory networks.
- CHEK2:Moderate-risk breast cancer susceptibility gene with variable penetrance estimates complicating clinical actionability thresholds for prophylactic intervention decisions.
- ATM:Ataxia telangiectasia mutated gene testing for breast cancer risk shows heterogenous payer coverage with emerging evidence for pancreatic malignancy association.
Clinical utility evidence accumulation for PALB2 and TP53 is outpacing reimbursement harmonization, creating a deployment gap between academic medical centers and community oncology practices.
Technology:
Platform selection hinges on analytical resolution requirements for variant classes ranging from single nucleotide substitutions to complex structural rearrangements.
- Next-Generation Sequencing:Massively parallel sequencing of targeted gene panels or exome-scale libraries dominates hereditary cancer test volumes through Illumina and Thermo Fisher instrument placements. United States reference laboratories are deploying NGS for panels exceeding 100 genes while maintaining parallel workflows for copy number variant confirmation. Mature deployment sits with Next-Generation Sequencing. Newer deployment is concentrated in long-read sequencing integration.
- PCR:Polymerase chain reaction amplification with Sanger sequencing confirmation retains critical utility for single-site familial variant tracking and low-complexity targeted analysis in resource-constrained settings.
- Microarray:Comparative genomic hybridization platforms detect large genomic rearrangements and exon-level deletions with standardized probe coverage across susceptibility gene regions.
- Sanger Sequencing:First-generation capillary electrophoresis remains the gold standard for variant confirmation and targeted analysis of specific mutation sites with established clinical significance.
- MLPA:Multiplex ligation-dependent probe amplification provides cost-effective large rearrangement detection where short-read NGS platforms exhibit reduced sensitivity for exon-level copy number changes.
- DNA Hybridization:Solid-phase or bead-based capture methods enable targeted enrichment of coding regions and splice sites prior to downstream sequencing analysis.
Short-read NGS limitations for pseudogene discrimination and complex structural variants are driving pilot deployments of Pacific Biosciences and Oxford Nanopore platforms in German and United States reference laboratories.
Use Case:
Clinical application stratification reflects the progression from asymptomatic risk quantification through therapeutic decision support in active malignancy management.
- Risk Assessment:Germline testing of unaffected individuals with family history criteria quantifies lifetime malignancy probability to inform surveillance intensity and prophylactic surgery timing. Oncology clinics in Australia are integrating risk assessment into routine new patient workflows for breast and colorectal cancer screening programs.
- Diagnosis:Testing in suspected hereditary cancer syndrome contexts confirms molecular diagnosis to satisfy clinical criteria and enable cascade screening of at-risk relatives.
- Prognosis:Germline variant status informs natural history expectations and second primary cancer risk in patients with established hereditary syndromes.
- Treatment Planning:BRCA1/2 and PALB2 status directs PARP inhibitor eligibility and platinum chemotherapy sensitivity predictions in ovarian and pancreatic cancer protocols.
- Familial Screening:Cascade testing of first-degree relatives following proband identification captures at-risk individuals prior to malignancy development.
- Carrier Testing:Preconception or prenatal analysis for hereditary cancer syndromes remains limited by variable penetrance and age of onset complicating reproductive counseling.
Treatment planning applications are expanding fastest as tumor-germline integration protocols capture therapeutic biomarker information from single specimen submissions.
End User:
Channel structure is fragmenting as telehealth platforms disintermediate traditional laboratory sales organizations from pre-test counseling and specimen logistics.
- Genetic Counselors:Board-certified specialists provide pre-test risk assessment and post-test variant interpretation across academic medical centers and independent telehealth platforms. United States commercial payer contracts increasingly mandate independent genetic counselor documentation prior to authorizing high-risk panel testing.
- Oncology Clinics:Community and academic oncology practices are unbundling testing procurement from counseling services, contracting directly with reference laboratories while maintaining in-house specimen collection.
- Diagnostic Laboratories:High-complexity CLIA-certified laboratories with established quality management systems are consolidating volume from smaller hospital labs unable to absorb IVDR compliance costs.
- Research Institutions:Academic medical centers with biobanking infrastructure contribute variant classification data to ClinGen and other curation consortia in exchange for research use of de-identified specimens.
- Specialty Clinics:Gynecologic oncology, gastroenterology, and dermatology subspecialty practices maintain targeted testing protocols for syndrome-specific patient populations.
Telehealth-integrated genetic counseling platforms in Canada and Australia are opening access pathways outside traditional oncology clinic referral networks, pressuring legacy laboratory distribution models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston anchors the global hereditary cancer testing ecosystem through its concentration of academic medical centers, reference laboratories, and precision medicine startups that have shaped clinical adoption patterns worldwide.
United States
Commercial payer coverage expansion for BRCA and Lynch syndrome testing drives volume concentration in oncology clinics across California and Texas. FDA's Class II device pathway for multigene panels accelerates premarket timelines for test developers. The Research Triangle in North Carolina hosts expanding laboratory capacity for next-generation sequencing workflows.
Germany
EMA's In Vitro Diagnostic Regulation forces clinical performance studies for legacy hereditary cancer assays, consolidating volume toward high-complexity reference laboratories. The country's national pharmaceutical regulator enforces notified body review requirements that smaller hospital labs cannot absorb. Munich and Heidelberg cluster academic medical centers piloting Pacific Biosciences long-read platforms for complex structural variant resolution.
United Kingdom
National Health Service genomic medicine service expansion standardizes hereditary cancer testing protocols across England's regional genetics networks. GDPR Article 9 restrictions complicate cloud-based variant classification for laboratories using US-hosted databases. London concentrates private laboratory networks building telehealth-integrated genetic counseling platforms.
Australia
Medicare reimbursement for risk assessment testing integrates germline analysis into routine breast and colorectal cancer screening programs. The country's therapeutic goods regulator aligns with international frameworks on variant interpretation standards. Sydney and Melbourne host diagnostic laboratories developing direct-to-consumer access pathways outside traditional oncology referrals.
Brazil
Private laboratory networks in São Paulo build TP53 testing capacity for Li-Fraumeni syndrome detection amid underpenetrated pediatric oncology markets. ANVISA oversight of in vitro diagnostics shapes import pathways for sequencing instruments and reagent kits. The Southeast region concentrates demand from early-onset malignancy cohorts with limited access to cascade screening protocols.
Global Hereditary Cancer Testing Market Competitive Landscape
Premium-margin players sit above commodity-margin players across variant interpretation capability and proprietary database depth. The vendor base stratifies between integrated instrument-reagent providers, specialized reference laboratories, and hybrid screening platform developers. Three archetypes dominate: upstream sequencing infrastructure owners, downstream clinical testing service providers, and integrated cancer screening platform operators. Consolidation pressure favors laboratories with established quality management systems, while technology licensing agreements reshape competitive boundaries between instrument and assay developers.
Within the integrated platform tier, Myriad Genetics and Exact Sciences exemplify divergent strategies for bridging germline risk assessment with somatic tumor profiling. Thermo Fisher Scientific anchors the upstream reagent and instrument layer. Illumina occupies a position across sequencing infrastructure deployment. These three companies represent the spectrum from specialized clinical testing services through comprehensive technology enablement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Qiagen |
| Myriad Genetics |
| Guardant Health |
| Roche Diagnostics |
| Invitae Corporation |
| Quest Diagnostics |
| Exact Sciences |
| Illumina |
| Others |
Supply & Pricing Matrix
Captive integration of variant classification databases with laboratory information systems anchors pricing power for high-complexity reference laboratories while forcing smaller competitors into commodity reagent and instrument resale positions. Myriad Genetics and Exact Sciences leverage proprietary data assets to sustain premium positioning against Illumina's upstream instrument control and Thermo Fisher's reagent bundling strategies.
Pricing Analysis
Outcome-based pricing anchors hereditary cancer testing reimbursement, with commercial payers in the United States tying authorization to genetic counselor documentation and clinical utility evidence thresholds. Price differentiation rests on proprietary database depth and FDA classification tier, with Class II 510(k) cleared panels commanding premium positioning over laboratory-developed tests. Pricing pressure stems from CMS coding fragmentation that discourages comprehensive panel adoption in favor of single-site assays. Community oncology clinics exhibit highest price sensitivity, while academic medical centers prioritize analytical validity and turnaround time over per-test cost.
Supply Chain Analysis
Direct-to-laboratory channels handle instrument and reagent procurement for high-throughput reference laboratories, while distribution runs through specialty distributors for smaller hospital labs lacking direct manufacturer relationships. Sequencing instrument supply concentrates in the United States, China, and Germany, with Illumina and Thermo Fisher dominating placements. Reagent dependencies include library preparation kits, target capture probes, and variant interpretation software licenses. Single-source vulnerability for next-generation sequencing consumables creates procurement risk for European laboratories navigating IVDR compliance timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA's In Vitro Diagnostic Regulation forces consolidation toward laboratories with established quality management systems and notified body relationships, eliminating smaller hospital labs from competitive participation.
For Market Incumbents: Hedge against margin compression from telehealth-integrated genetic counseling platforms by acquiring or partnering with independent counseling services to maintain bundled value propositions. Invest in long-read sequencing integration to eliminate confirmatory testing steps and reduce variant of uncertain significance rates that erode clinical confidence.
For New Entrants and Emerging Players: The premium-economy price-point gap in TP53 and PALB2 testing creates white-space opportunity in Latin American private laboratory networks where Li-Fraumeni syndrome penetration remains underdeveloped. Target direct-to-consumer channels in Australia and Canada where telehealth platforms have opened access pathways outside traditional oncology referrals, using Medicare reimbursement alignment as market entry leverage.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays where somatic-germline integration capabilities command strategic premiums. Laboratories with FDA Class II cleared multigene panels and established payer contracts represent the most defensible acquisition targets. Watch for IVDR compliance cost absorption as the inflection indicator separating viable regional players from distressed assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-read Sequencing Integration | Pacific Biosciences and Oxford Nanopore platforms resolve structural variants that confound short-read alignments in BRCA1 and PMS2 analysis. |
| Telehealth Genetic Counseling Partnership | Independent counseling documentation satisfies United States commercial payer prior authorization requirements for high-risk panel testing. |
| IVDR Compliance Investment | Notified body-reviewed clinical performance studies enable continued market access for legacy hereditary cancer assays in Germany and France. |
| Somatic-Germline Workflow Convergence | Tumor-normal sequencing protocols capture therapeutic biomarker information and hereditary risk assessment from single specimen submissions. |
| Direct-to-Consumer Channel Development | Medicare-reimbursed risk assessment testing in Australia opens access pathways outside traditional oncology clinic referral networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with laboratory directors, genetic counselors, payer access specialists, and biomedical engineers at reference laboratories and academic medical centers. FDA 510(k) clearances, EMA IVDR submissions, CMS reimbursement determinations, and hospital procurement databases provided validation points. Bottom-up test volume estimates triangulated against top-down market value reconstructions across the analysis window.
Reconciliation of test volume, pricing, and reimbursement data streams shaped the analytical framework, with segmentation modeled across test type, technology platform, clinical use case, and end-user channel. CAGRs derived from logistic adoption curves for next-generation sequencing penetration and payer coverage expansion trajectories. Forecast inputs incorporated laboratory capacity buildout timelines, regulatory classification decisions, and genetic counselor workforce growth projections.
Inputs from FDA, EMA, and national payers were available through the study window; gaps in real-time laboratory pricing data and proprietary variant classification database valuations introduce uncertainty bands around competitive positioning assessments. Forecasts reflect assumptions on regulatory harmonization progress and reimbursement code consolidation that could shift with policy momentum. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Gene Sequencing Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Next-Generation Sequencing for Non-Invasive Prenatal Testing Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Microbiome Sequencing Outsourcing Services Market
Genomics
Animal Genetics Market
Genomics
Sequencing Electrophoresis Systems Market
Genomics
North America Genetic Testing Market
Genomics
Japan Next Generation Sequencing Market
Genomics
Next Generation Molecular Assay Market
Genomics
North America DNA Sequencing Products Market
Genomics
Glycan Sequencing Market