
 Asia-Pacific Whole Exome Sequencing Market | 2026-2036
Asia-Pacific Whole Exome Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Whole Exome Sequencing Market Outlook
Platform licensing revenue is narrowing as instrument manufacturers bundle analytics software with sequencing hardware. Illumina, Inc. leverages its installed base of NovaSeq systems to lock in consumable pull-through across Japanese research consortia. BGI Genomics anchors its position through captive manufacturing of sequencing reagents at Shenzhen facilities. MGI Tech Co., Ltd. competes aggressively on instrument pricing to displace legacy vendors in Australian hospital tenders.
Whole exome sequencing captures protein-coding regions comprising approximately one percent of the human genome, utilizing targeted hybridization or amplicon-based enrichment followed by next-generation sequencing readout at 100x mean coverage depth to identify pathogenic variants for diagnostic and research applications. Kits and reagents command the largest product type margin pool due to recurring consumable demand tied to instrument installed bases. Next-generation sequencing dominates the technology dimension while pharmacogenomics represents the fastest-growing application segment as healthcare systems integrate preemptive genotyping into drug prescribing workflows.
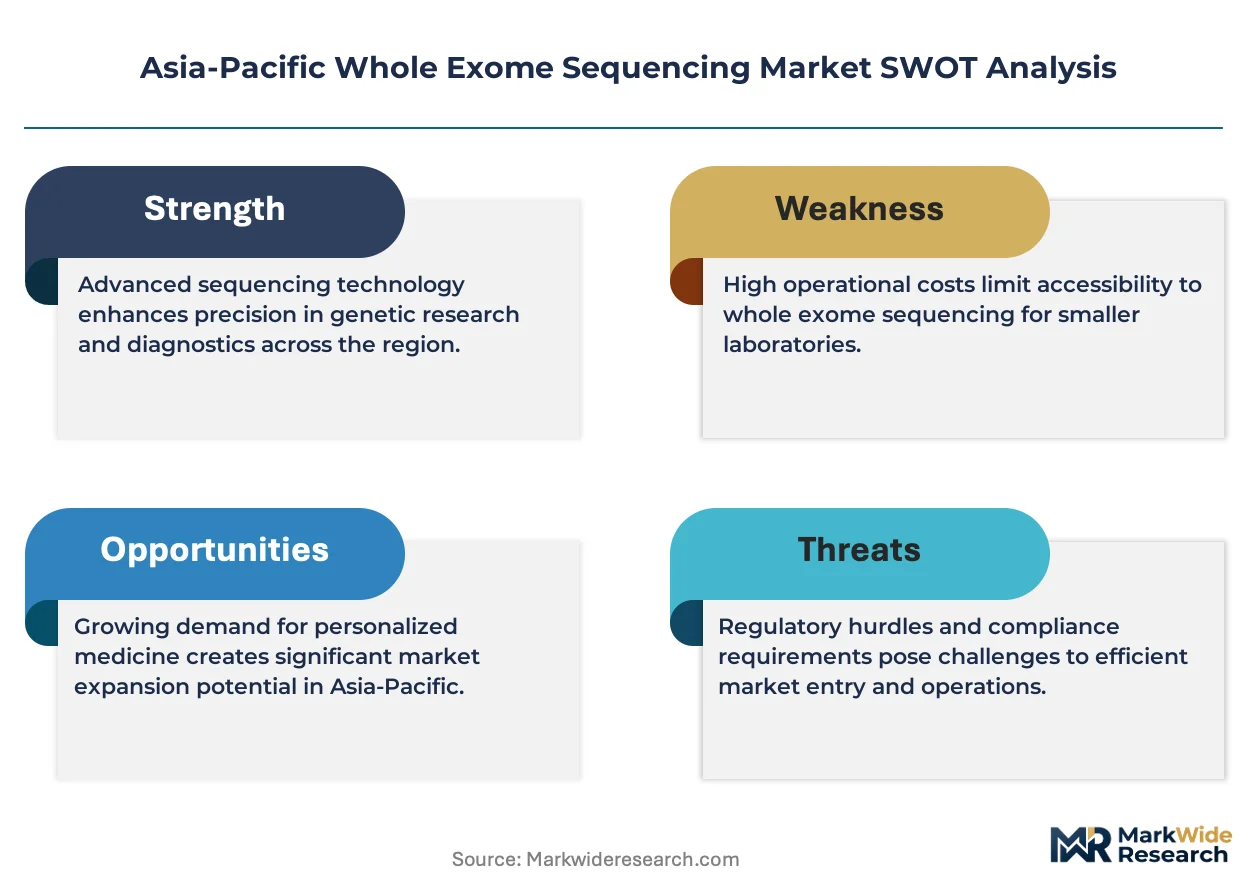
Japan's PMDA oversees in vitro diagnostic registration for clinical exome panels while Australia's TGA governs laboratory-developed test quality standards; both frameworks elevate compliance costs for market entry but simultaneously validate reimbursement pathways for accredited providers. China's NMPA and South Korea's MFDS maintain divergent classification schemes for sequencing-based devices, fragmenting product registration strategies across the region. Stakeholders must monitor convergence between research-use-only and clinical-grade regulatory categories as health systems demand diagnostic certainty from exome-derived reports.
Market Dynamics
Hybridization-based enrichment workflows are compressing turnaround times for clinical exome panels, forcing diagnostic laboratories across Asia-Pacific to consolidate sequencing platforms around single-vendor ecosystems that lock in consumable spend.
Growth Catalysts
- Japan's rare disease reimbursement expansion:The Ministry of Health, Labour and Welfare extended coverage for exome-based diagnostic testing in pediatric neurodevelopmental disorders, accelerating hospital laboratory accreditation.
- Pharmacogenomics integration:Healthcare systems in South Korea and Australia are embedding preemptive genotyping into oncology and psychiatry prescribing protocols, creating recurring test volume.
- BGI Genomics:Captive reagent manufacturing at Shenzhen facilities is compressing kit costs for domestic Chinese hospital networks, expanding addressable patient populations.
Market Restraints
- Consumable cost concentration:Proprietary flow cells and library prep chemistries from dominant platform vendors account for sixty to seventy percent of per-test expenditure, eroding laboratory margins.
- Interpretation bottleneck:Variant of uncertain significance rates exceeding thirty percent in ethnically diverse Asian populations slow diagnostic yield and extend reporting timelines.
- Regulatory fragmentation:Divergent classification schemes between China's NMPA and South Korea's MFDS force manufacturers to maintain parallel registration dossiers, elevating compliance overhead.
Strategic Opportunities
- India's CDSCO pathway streamlining:Accelerated quality certification timelines for nucleic acid testing kits are opening procurement access to tier-two hospital networks previously restricted to research-use-only products.
- Long-read integration:Hybrid workflows combining short-read exome capture with Pacific Biosciences or Oxford Nanopore long-read confirmation are resolving structural variant detection gaps in neurogenetic indications.
- Telemedicine-linked testing:Direct-to-consumer genetic counseling platforms in Australia are creating new sample collection and logistics channels outside traditional hospital pathology networks.
Industry Challenges
- Bioinformatics specialization gap:Clinical laboratories struggle to recruit variant curators with dual training in molecular genetics and ACMG guideline interpretation, extending validation timelines for new gene panels.
- Sample logistics cold chain:Temperature-controlled transport infrastructure remains underdeveloped in Indonesia, the Philippines, and Vietnam, degrading nucleic acid integrity for referral specimens.
- LIMS integration complexity:Legacy laboratory information management systems in Japanese university hospitals require custom API development to accept structured genomic data from cloud-based analysis pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Whole Exome Sequencing Market |
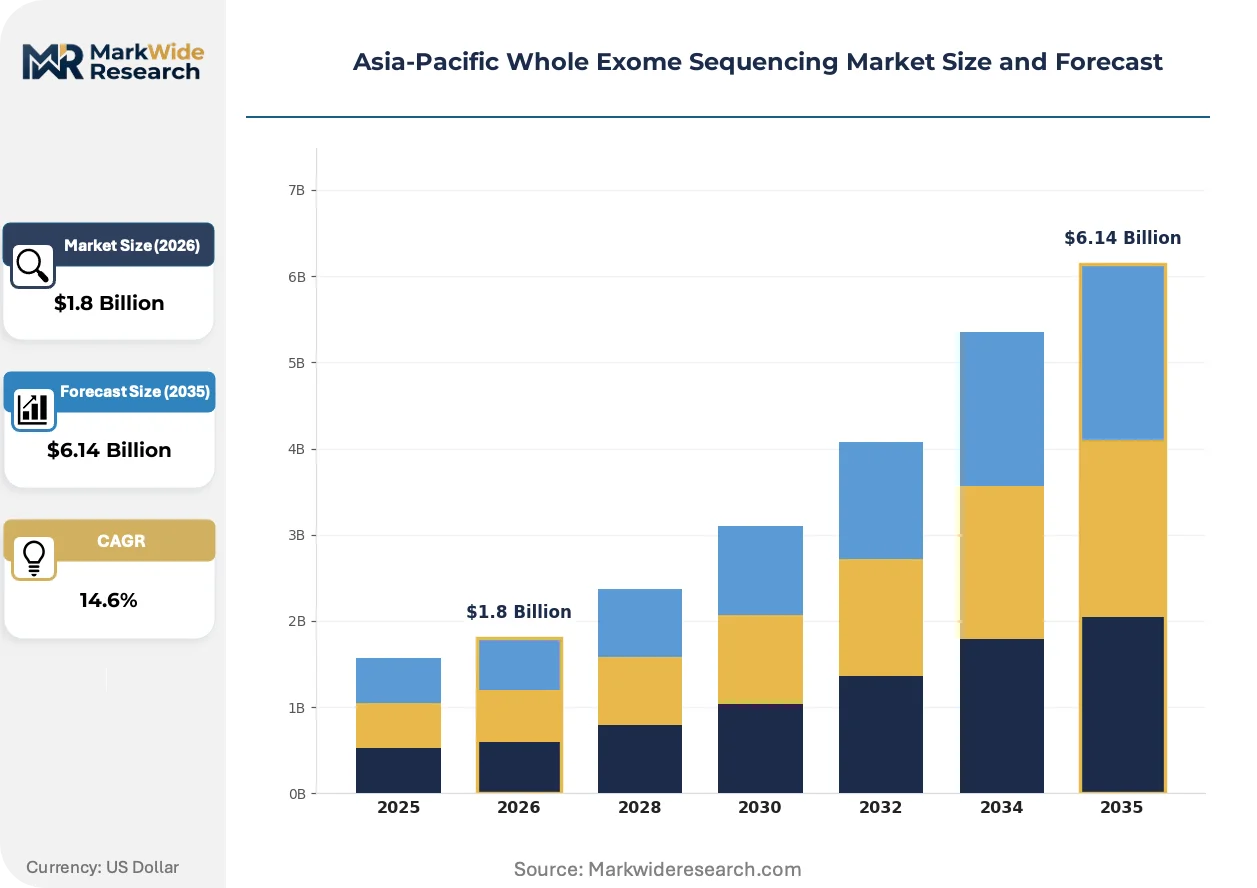
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kits, Instruments, Software, Reagents End User: Research Institutions, Hospitals, Diagnostic Laboratories, Academic Institutions Application: Oncology, Rare Diseases, Genetic Disorders, Pharmacogenomics Technology: Sanger Sequencing, Next-Generation Sequencing, Whole Genome Sequencing, PCR |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., QIAGEN, BGI Genomics, Eurofins Scientific, Beckman Coulter, Inc., BIONEER CORPORATION, MGI Tech Co., Ltd., Psomagen, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Whole Exome Sequencing Market Strategic Shifts
Artificial intelligence-powered variant prioritization engines are compressing interpretation timelines from weeks to days, reshaping staffing models in high-throughput diagnostic laboratories across the region.
CRISPR-based targeted enrichment is rendering obsolete hybridization capture methods for rapid turnaround oncology panels. Beijing and Shanghai cancer centers are adopting enzymatic target selection for same-day library preparation, collapsing the structural advantage of overnight hybridization workflows and enabling intraoperative sequencing decisions.
Australia's TGA revised laboratory-developed test quality standards to mandate participation in external quality assurance programs for exome-based reports. The framework elevates compliance costs for smaller pathology providers while validating premium reimbursement tiers for accredited tertiary centers, concentrating clinical testing volume in Melbourne and Sydney hospital networks.
Hospital procurement committees are consolidating vendor relationships around integrated platform-service contracts that bundle sequencing hardware, bioinformatics pipelines, and clinical reporting support. Australian and South Korean health systems are displacing à-la-carte reagent purchasing with multi-year total cost-of-ownership agreements that shift operational risk to manufacturers.
Asia-Pacific Whole Exome Sequencing Market Segmentation
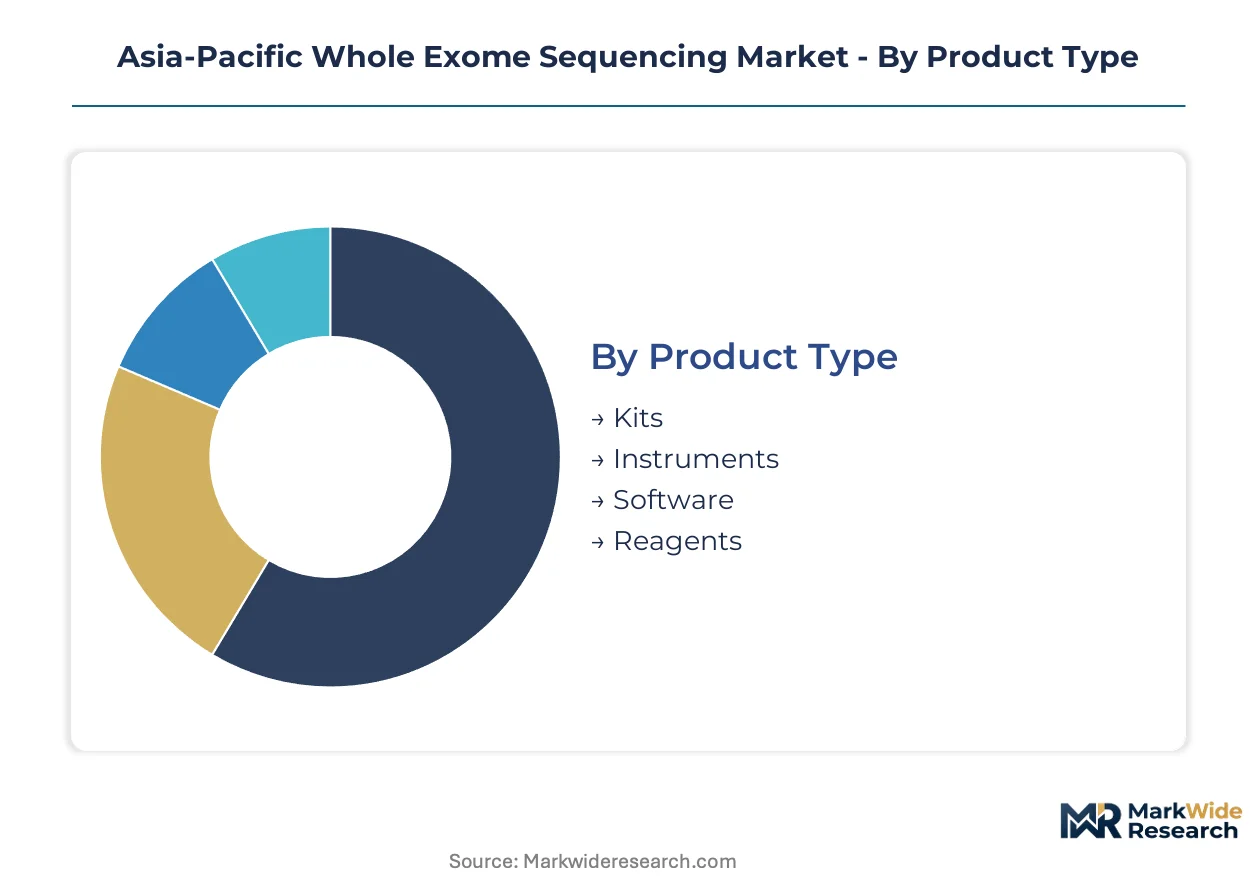
Segmentation in whole exome sequencing reveals distinct margin structures and service intensity profiles. Recurring consumable demand, instrument depreciation cycles, and software licensing terms create divergent investment timelines across customer categories.
Product Type:
After-sales service intensity varies sharply across product categories, with consumables requiring continuous technical support while hardware demands intermittent calibration contracts.
- Kits:Library preparation and target enrichment kits constitute the highest-margin recurring revenue stream, with proprietary chemistries locking laboratories into single-vendor ecosystems. Demand concentrates in Chinese tier-one hospital networks where provincial health commissions mandate standardized genetic disease protocols.
- Reagents:Flow cells, sequencing buffers, and quality control reagents generate pull-through revenue tied to instrument utilization rates. BGI Genomics compresses costs through captive manufacturing at Shenzhen facilities, expanding addressable patient populations across domestic Chinese networks.
- Instruments:Sequencing platforms require substantial capital outlay with 5-7 year depreciation schedules.
- Software:Variant calling and clinical interpretation platforms carry annual licensing fees with cloud deployment options.
Kits hold the largest share; momentum sits with reagents.
End User:
Customer concentration patterns split between capital-rich hospital networks and grant-dependent research organizations with divergent procurement timelines.
- Diagnostic Laboratories:Commercial reference laboratories process high-volume exome panels for oncology and rare disease indications, requiring LIMS integration and automated reporting workflows. Japan's rare disease reimbursement expansion accelerates laboratory accreditation investments.
- Hospitals:Tertiary medical centers embed exome sequencing into multidisciplinary tumor boards and pediatric genetics clinics. Australia's TGA-mandated external quality assurance programs validate premium reimbursement tiers for accredited Melbourne and Sydney hospital networks.
- Research Institutions:Academic medical centers and consortiums drive technology adoption for discovery applications.
- Academic Institutions:University laboratories prioritize publication-grade data generation over clinical turnaround times.
Diagnostic laboratories hold the largest share; momentum sits with hospitals.
Application:
Clinical utility validation timelines and reimbursement coding maturity create tiered adoption curves across disease areas.
- Oncology:Tumor-normal paired exome sequencing guides targeted therapy selection and clinical trial enrollment. Beijing and Shanghai cancer centers adopt CRISPR-based enzymatic enrichment for same-day library preparation, collapsing traditional overnight hybridization workflows.
- Pharmacogenomics:Preemptive genotyping for drug response prediction is climbing the fastest as South Korean and Australian health systems embed testing into oncology and psychiatry prescribing protocols, creating recurring test volume.
- Rare Diseases:Undiagnosed genetic disorder programs leverage trio exome analysis for pediatric neurodevelopmental cases.
- Genetic Disorders:Hereditary condition screening applications span prenatal, carrier, and predictive testing contexts.
Oncology holds the largest share; momentum sits with pharmacogenomics.
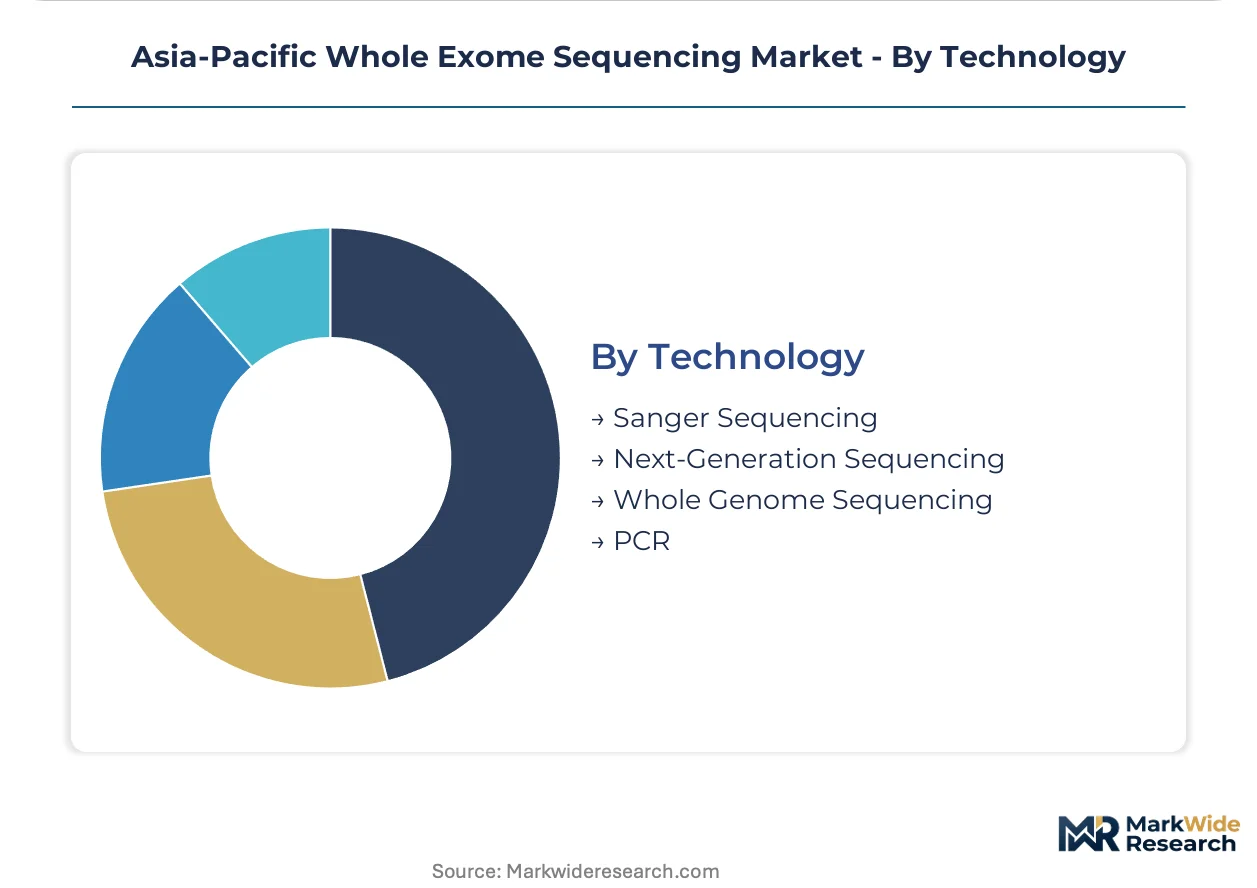
Technology:
Platform selection determines downstream bioinformatics requirements and variant detection capabilities for structural and copy-number alterations.
- Next-Generation Sequencing:Short-read massively parallel platforms dominate clinical throughput with 100x mean coverage depth for pathogenic variant identification. Illumina leverages its NovaSeq installed base to lock in consumable pull-through across Japanese research consortia.
- Sanger Sequencing:First-generation capillary electrophoresis retains niche utility for variant confirmation and targeted panel validation.
- Whole Genome Sequencing:Untargeted approaches capture non-coding regions but at higher per-sample cost.
- PCR:Amplicon-based enrichment offers rapid turnaround for hotspot mutation detection with limited gene content.
Next-generation sequencing holds the largest share; momentum sits with hybrid long-read integration workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across the Asia-Pacific whole exome sequencing market. Chinese hospital procurement committees negotiate aggressively on reagent costs, while Australian and Japanese buyers prioritize regulatory compliance and turnaround reliability over per-test expenditure.
China
Provincial health commissions in Jiangsu and Guangdong are embedding exome sequencing into standardized genetic disease protocols for tier-one hospitals. The NMPA maintains divergent classification schemes for sequencing-based devices compared with neighboring regulators, forcing manufacturers to maintain parallel registration dossiers. BGI Genomics anchors supply through captive reagent manufacturing at Shenzhen facilities, compressing kit costs for domestic networks.
Japan
The Ministry of Health, Labour and Welfare extended reimbursement coverage for exome-based diagnostic testing in pediatric neurodevelopmental disorders, accelerating hospital laboratory accreditation investments. The PMDA oversees in vitro diagnostic registration for clinical exome panels, elevating compliance costs that simultaneously validate premium reimbursement pathways. Illumina leverages its NovaSeq installed base to lock in consumable pull-through across Tokyo and Osaka research consortia.
South Korea
Healthcare systems are embedding preemptive pharmacogenomics genotyping into oncology and psychiatry prescribing protocols, creating recurring test volume for diagnostic laboratories. The MFDS maintains classification schemes for sequencing-based devices that diverge from China's NMPA framework, fragmenting product registration strategies. Seoul Capital Area hospital networks are consolidating vendor relationships around integrated platform-service contracts.
Australia
The TGA revised laboratory-developed test quality standards to mandate participation in external quality assurance programs for exome-based reports. This framework validates premium reimbursement tiers for accredited tertiary centers in Melbourne and Sydney, concentrating clinical testing volume. Telemedicine-linked testing platforms are creating new sample collection channels outside traditional hospital pathology networks.
India
The CDSCO tightened nucleic acid testing kit registration requirements, accelerating quality certification investments by domestic distributors seeking access to tier-two hospital networks. Maharashtra and Karnataka state health departments are piloting rare disease screening programs leveraging trio exome analysis. Cold chain infrastructure gaps in referral specimen transport remain a constraint for nucleic acid integrity.
Asia-Pacific Whole Exome Sequencing Market Competitive Environment
Capability concentration sits with integrated platform-service providers; scale advantage sits with consumable-anchored instrument manufacturers. The market structures around three tiers: dominant platform vendors with installed base lock-in, regional reagent manufacturers with captive supply chains, and service-oriented diagnostic laboratories with clinical interpretation expertise. Strategic moves center on multi-year total cost-of-ownership agreements that shift operational risk to manufacturers, and hybrid workflow integration combining short-read capture with long-read confirmation.
Within the platform vendor tier, Illumina, Inc. and MGI Tech Co., Ltd. occupy positions defined by instrument ecosystem control. Among Asia-Pacific-based reagent specialists, BGI Genomics exemplifies backward integration into captive manufacturing. These three anchors represent divergent competitive vectors: consumable pull-through, aggressive instrument pricing, and vertical supply chain control.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| BGI Genomics |
| Eurofins Scientific |
| Beckman Coulter, Inc. |
| BIONEER CORPORATION |
| MGI Tech Co., Ltd. |
| Psomagen |
| Others |
Value Chain & Pricing Dynamics
Shenzhen's captive reagent manufacturing cluster compresses kit costs for domestic Chinese hospital networks while amplifying pricing power for integrated platform vendors serving premium-tier markets in Japan and Australia. This geographic concentration of upstream supply capacity creates divergent margin structures across the Asia-Pacific region.
Pricing Analysis
Consumable pull-through contracts drive lifetime value for instrument manufacturers, with proprietary flow cells and library prep chemistries accounting for the dominant share of per-test expenditure. Three-tier pricing structure across premium, standard, and economy levels separates accredited tertiary centers from tier-two hospitals and research-use-only laboratories. Cost compression in economy tiers intensifies as BGI Genomics expands domestic manufacturing capacity. Tier-two hospital networks in India exhibit the highest price sensitivity, while Australian and Japanese buyers prioritize regulatory compliance and turnaround reliability.
Supply Chain Analysis
BGI Genomics and MGI Tech Co., Ltd. anchor contract manufacturing concentration for sequencing reagents and instruments across the Asia-Pacific region. Supply capacity concentrates in China, Japan, and South Korea, with raw material dependencies spanning semiconductor-grade substrates, synthetic oligonucleotides, and fluorescence-tagged nucleotides. Single-source vulnerability around Illumina's flow cell chemistries creates structural risk for laboratories locked into proprietary ecosystems. Distribution runs through integrated platform-service contracts that bundle hardware, bioinformatics pipelines, and clinical reporting support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific whole exome sequencing market rewards organizations that control scarce bioinformatics interpretation capabilities, where qualified variant curators with dual training in molecular genetics and ACMG guideline interpretation remain in short supply relative to expanding test volumes.
For Market Incumbents: Entrench installed base lock-in through multi-year total cost-of-ownership agreements that shift operational risk to manufacturers and consolidate consumable spend. Defend against MGI Tech Co., Ltd.'s aggressive instrument pricing by embedding AI-powered variant prioritization engines into cloud-based analysis pipelines, reducing interpretation timelines from weeks to days. For New Entrants and Emerging Players: India's tier-two hospital networks, newly accessible through streamlined CDSCO quality certification pathways, represent the most penetrable entry point for regional reagent manufacturers. Direct-to-consumer genetic counseling platforms in Australia create alternative sample collection channels outside traditional hospital pathology networks. Pursue telemedicine-linked testing partnerships to bypass entrenched procurement committees. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors diagnostic laboratories with clinical interpretation expertise and established external quality assurance participation under Australia's TGA-mandated frameworks. Long-term viability rests on hybrid workflow integration combining short-read exome capture with Pacific Biosciences or Oxford Nanopore long-read confirmation. Monitor convergence between research-use-only and clinical-grade regulatory categories as the inflection indicator for reimbursement pathway expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Long-Read Integration | Combining short-read capture with Pacific Biosciences confirmation resolves structural variant detection gaps in neurogenetic indications. |
| Multi-Year Platform-Service Contracts | Australian and South Korean health systems displace à-la-carte reagent purchasing with total cost-of-ownership agreements shifting risk to manufacturers. |
| CDSCO Quality Certification Investment | Accelerated timelines for nucleic acid testing kit registration open procurement access to India's tier-two hospital networks. |
| AI-Powered Variant Prioritization | Artificial intelligence engines compress interpretation timelines from weeks to days, reshaping staffing models in high-throughput diagnostic laboratories. |
| CRISPR-Based Enzymatic Enrichment | Beijing and Shanghai cancer centers adopt same-day library preparation, collapsing traditional overnight hybridization workflows for oncology panels. |
Study Parameters
A standing panel of clinical laboratory directors, hospital procurement managers, regulatory affairs specialists, and bioinformatics pipeline engineers provided ongoing calibration across the primary research phase. This practitioner input combined with secondary validation from NMPA registration databases, PMDA in vitro diagnostic filings, TGA laboratory-developed test quality standards, and MFDS device classification schemes. Bottom-up instrument shipment tracking and top-down healthcare expenditure modeling enabled triangulation across independent analytical streams.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity analysis applied to reimbursement expansion timelines and regulatory convergence assumptions. Segmentation dimensions modeled include product type, end user category, application area, technology platform, and geographic regulatory cluster. CAGRs derived from instrument depreciation cycles, consumable utilization rates, and test volume elasticity to pricing shifts. Forecast inputs incorporated pharmacogenomics integration velocity and rare disease program expansion trajectories.
Practitioners should monitor reimbursement coding maturity for pharmacogenomics applications and external quality assurance program participation thresholds for early signals of volume concentration. Forecasts reflect assumptions around regulatory pathway convergence and cold chain infrastructure development in Southeast Asia. Quarterly review of CDSCO registration timelines, provincial health commission protocol embeddings, and telemedicine platform partnership announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Cytogenetic Systems Market
Genomics
Kearns-Sayre Syndrome Market
Genomics
APO E Gene Test Kit Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Hereditary Testing Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Global Microarray Analysis Market
Genomics
Pharmacogenomics Technology Market
Genomics
UAE Genetic Testing Market
Genomics
DNA Methylation Market
Genomics
DNA Mass Ladder Market
Genomics
Glycan Sequencing Market
Genomics
North America DNA Sequencing Products Market
Genomics
SNP Genotyping Market
Genomics
Europe Epigenetics Market