
 Animal Genetics Market | 2026-2036
Animal Genetics Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Genetics Market Analysis
REACH compliance is realigning the cost-of-entry calculus for genetic reagents and diagnostic kits sold into European livestock markets. Genus PLC leverages its bovine germplasm network to sustain premium pricing across dairy breeding programs. Hendrix Genetics anchors poultry genetics innovation through in-house breeding lines and layer performance traits. Alta Genetics dominates North American dairy sire distribution through controlled semen processing and cooperative partnerships.
Animal genetics encompasses the study, manipulation, and commercial application of heritable traits in livestock and companion species through selective breeding, artificial insemination, embryo transfer, and molecular techniques such as marker-assisted selection and genomic prediction algorithms. The field serves primary industrial purposes including accelerated genetic gain, disease resilience, feed efficiency optimization, and standardized trait propagation across commercial populations. Genetic testing and breeding stocks command the deepest margin pools due to recurring revenue from genomic evaluations and proprietary germplasm licensing. Biotechnology solutions, particularly CRISPR-based editing platforms, represent the fastest-expanding segment as regulatory clarity emerges in key jurisdictions. DNA sequencing and bioinformatics underpin most modern breeding decisions, shifting value capture from physical animal sales toward data-driven genetic advisory services.
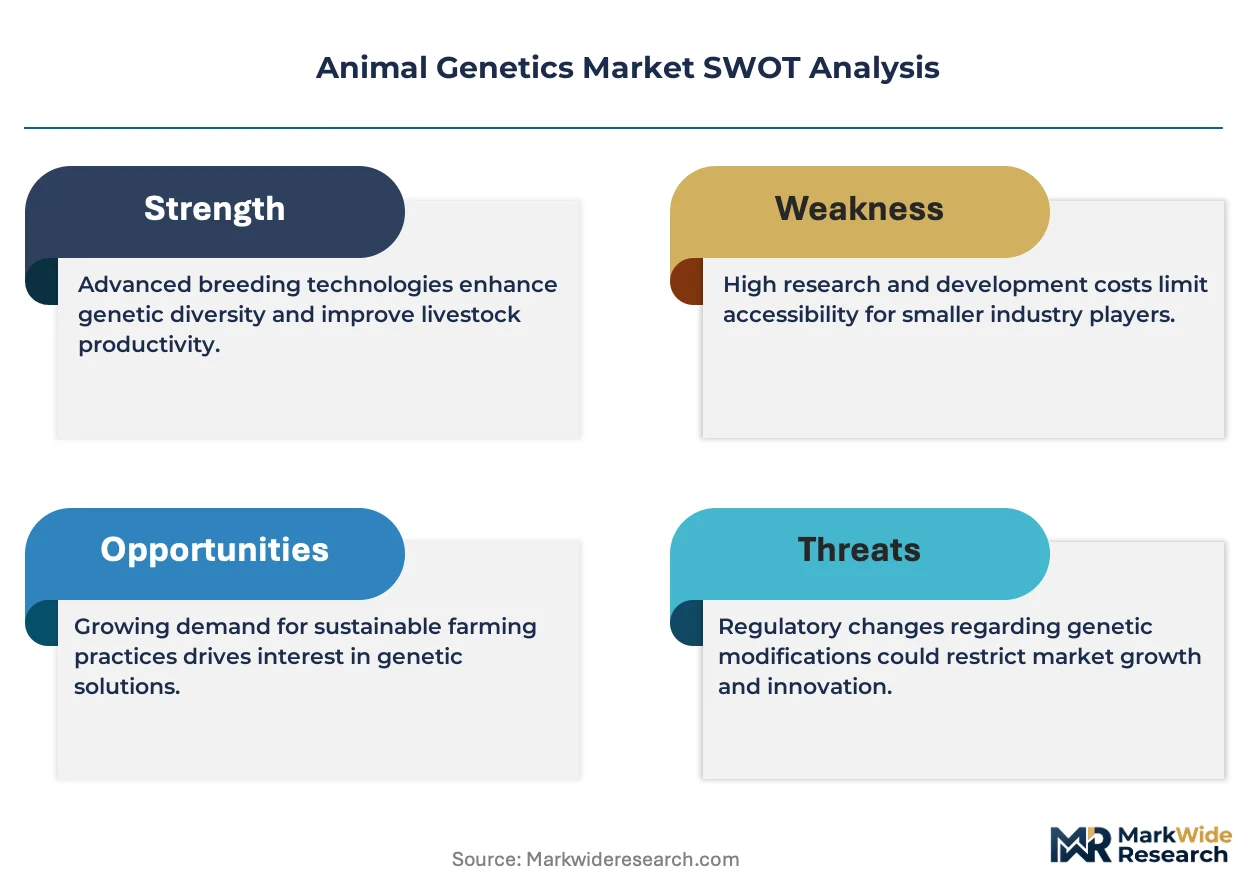
The FDA and USDA jointly oversee gene-edited animals and veterinary biologics in the United States, creating a bifurcated compliance pathway that delays market entry for novel traits. EMA and EFSA coordinate on genetically modified feed and animal health products within Europe, where the precautionary principle extends evaluation timelines beyond other regions. Stakeholders must monitor how national gene-editing classifications evolve, as regulatory divergence between major markets will determine where genetic innovators prioritize product development and field trials.
Market Dynamics
Genomic selection tools are compressing generational intervals in commercial breeding programs, forcing incumbents to restructure data infrastructure and subscription-based advisory models around predictive breeding values rather than physical germplasm sales.
Growth Catalysts
- EU F-Gas Regulation:Refrigerant phase-down mandates for semen storage cryogenic systems accelerate replacement demand for energy-efficient liquid nitrogen infrastructure across European AI centers.
- Dairy feed efficiency traits:Genomic predictions for residual feed intake cut input costs for large-scale integrated producers in the United States and Netherlands, driving recurring revenue from SNP chip evaluations.
- CRISPR regulatory clarity:Brazil's CTNBio streamlined classification of gene-edited livestock without foreign DNA inserts, reducing field trial approval timelines for heat-tolerance traits in commercial herds.
Market Restraints
- Semen processing concentration:Three cooperative networks control North American dairy sire distribution, creating bottleneck risk for independent genetic suppliers seeking AI technician access.
- Liquid nitrogen cost volatility:Cryogenic logistics account for 15-25% of germplasm operating costs, with energy price spikes compressing margins for regional semen storage facilities.
- Gene-editing regulatory fragmentation:Divergent classification between FDA oversight in the United States and EFSA precautionary review in Europe forces duplicate safety dossiers for identical traits.
Strategic Opportunities
- Layer breeding in Southeast Asia:Underpenetrated markets in Indonesia and Vietnam lack domestic nucleus herds, creating white space for turnkey breeding program licensing.
- Genomic advisory services:Cloud-based bioinformatics platforms enable subscription revenue from small-to-mid beef operations previously priced out of custom index calculations.
- Australian TGA gene-editing pathway:Streamlined notification process for site-directed nucleases without introduced DNA reduces regulatory lag for disease-resistance traits in sheep flocks.
Industry Challenges
- Bioinformatics talent scarcity:Quantitative genetics PhDs command premium compensation, constraining scale-up of in-house genomic prediction teams for mid-tier breeding companies.
- Legacy herd book integration:Paper-based pedigree registries in developing markets resist API connectivity, forcing manual data entry for genomic imputation pipelines.
- SNP chip standardization delays:Incompatible density panels between Illumina and Affymetrix platforms fragment reference population builds, degrading prediction accuracy across datasets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Genetics Market |
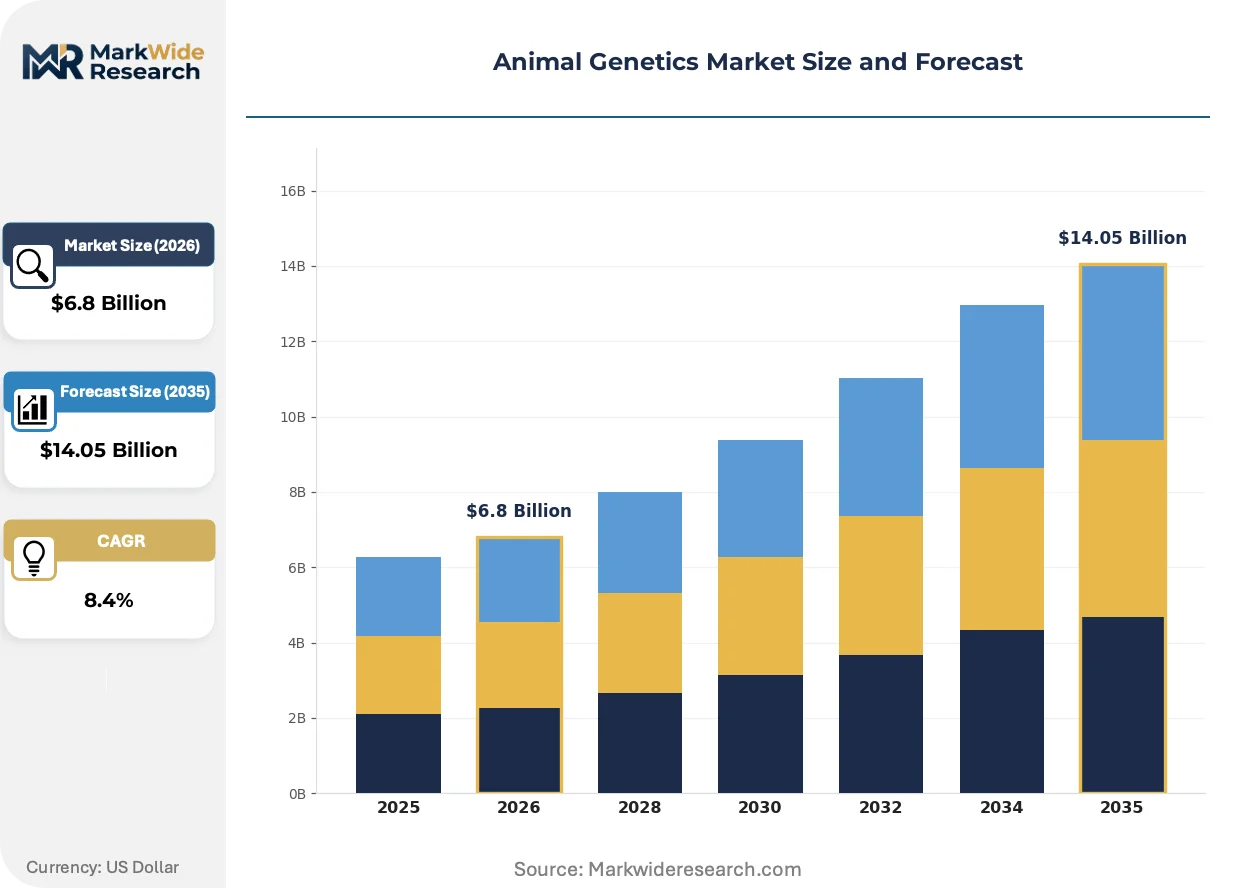
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Genetic Testing, Breeding Stocks, Genetic Services, Biotechnology Solutions End User: Farmers, Veterinary Clinics, Research Institutions, Livestock Producers Technology: DNA Sequencing, Genotyping, CRISPR, Bioinformatics Application: Disease Resistance, Trait Improvement, Breeding Programs, Genetic Research |
| Companies Covered | Zoetis, Groupe Grimaud, Genus PLC, Neogen Corporation, Topigs Norsvin, Hendrix Genetics, CRV Holding, Alta Genetics, EW Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Genetics Market Emerging Trajectories
Data-driven breeding decisions are displacing phenotype-centric selection, compressing the value chain toward algorithmic trait prediction and away from physical animal inspection. Three developments anchor this transformation.
Single-step genomic evaluation is electrifying dairy sire ranking accuracy by blending pedigree, phenotype, and dense marker data into unified breeding values. Large-scale cooperatives in the Netherlands and United States deploy these models to halve generation intervals. The technology is compressing market share for phenotype-only AI studs unable to fund in-house bioinformatics infrastructure.
REACH compliance deadlines for genetic reagents and diagnostic kits are forcing reformulation of buffer chemistries and packaging substrates sold into European livestock markets. ECHA substance-of-very-high-concern listings now cover several common PCR stabilizers, compelling suppliers to qualify replacement compounds. Diagnostic kit manufacturers serving bovine viral diarrhea screening face compressed registration timelines to maintain EU market access.
Integrated producers are consolidating genetic advisory procurement under enterprise software contracts rather than per-test transactions. Beef feedlot operators in the United States now demand bundled genomic testing, nutritional modeling, and health monitoring through single vendor relationships. This bundling is most visible in the Texas Panhandle and Nebraska feedlot corridors where thousand-head operations dominate procurement committees.
Animal Genetics Market Segmentation
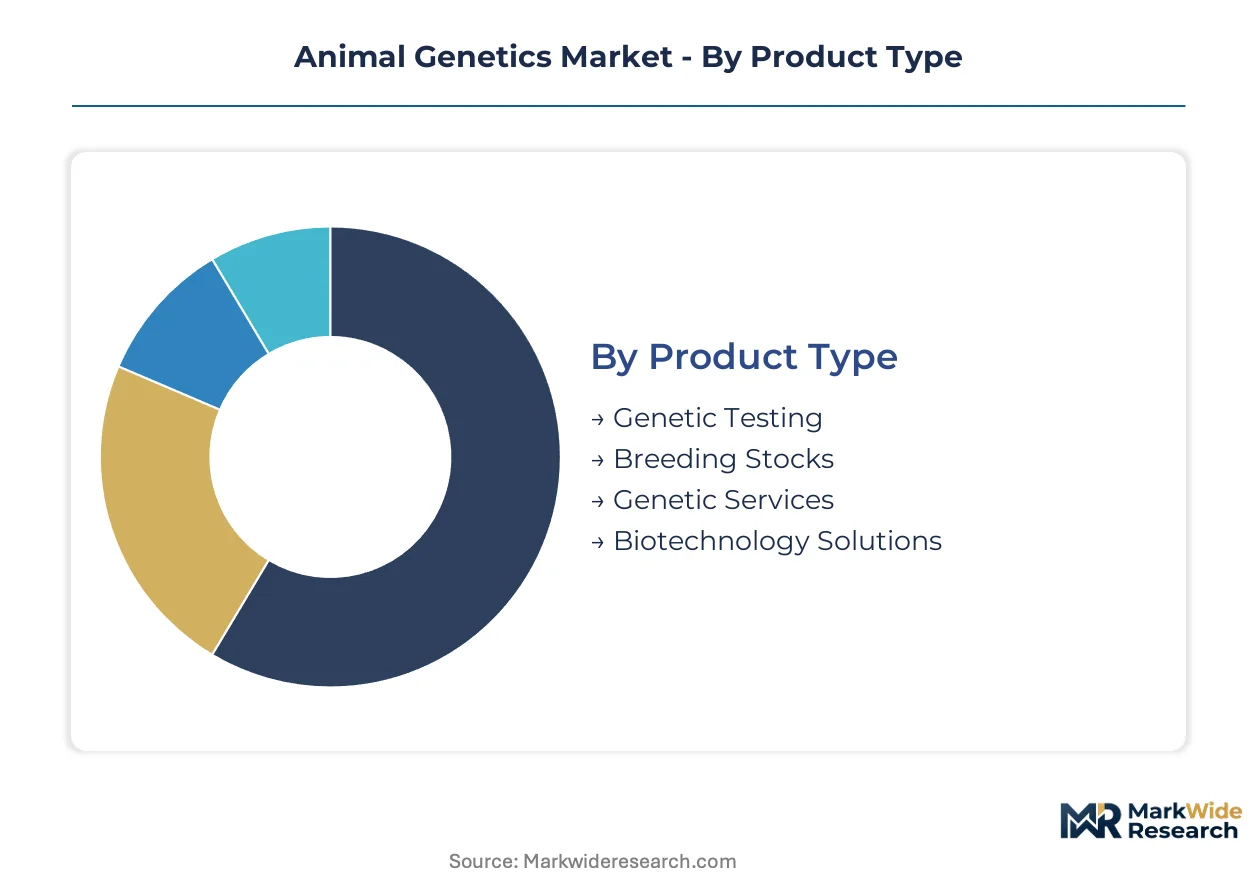
Animal genetics markets fragment across product tiers, customer sophistication, and technology maturity. Segmentation reveals where value pools concentrate and which innovation vectors command investment priority.
Product Type:
Volume flows through commoditized physical products while premium pools form around data and biotech intellectual property.
- Genetic Testing:SNP chip panels and PCR-based diagnostics generate recurring revenue from genomic evaluations. Dairy cooperatives in the Netherlands and beef feedlots in Texas drive standardized testing protocols for feed efficiency and marbling predictions.
- Biotechnology Solutions:Gene-editing platforms and transgenic trait development command the steepest expansion trajectory as regulatory pathways clarify in Brazil and Australia. CRISPR-based heat tolerance and disease resistance traits attract venture funding for field trial scaling.
- Breeding Stocks:Elite germplasm from nucleus herds underpins commercial multiplication pyramids. Semen and embryo sales concentrate in North American Holstein and Angus bloodlines.
- Genetic Services:Cloud-based bioinformatics and custom index calculations serve mid-tier producers previously priced out of in-house quantitative genetics teams.
Mature deployment sits with Breeding Stocks. Newer deployment is concentrated in Biotechnology Solutions.
End User:
Customer type determines procurement sophistication and contract structure across advisory versus transactional relationships.
- Livestock Producers:Large-scale integrated operations in the United States and China bundle genomic testing with nutritional modeling and health monitoring through enterprise software contracts rather than per-test transactions.
- Research Institutions:Universities and government labs anchor reference population builds and trait discovery pipelines. Public funding for bovine and porcine genome databases sustains open-source marker panels.
- Farmers:Small-to-mid beef operations access genomic advisory through cooperative purchasing groups and subscription-based prediction services.
- Veterinary Clinics:Companion animal genetic screening for heritable diseases drives margin in canine and feline DNA testing kits.
Procurement sophistication peaks with Livestock Producers. Accessibility expansion targets Farmers.
Technology:
Technology layers stack from data generation through interpretation, with value migration toward predictive algorithms.
- Bioinformatics:Cloud-based genomic prediction platforms and single-step evaluation models compress generation intervals for commercial breeding programs. The Netherlands and United States cooperatives deploy these tools to halve sire ranking cycles.
- CRISPR:Site-directed nuclease platforms enable trait editing without foreign DNA inserts. Brazil's CTNBio streamlined regulatory classification, reducing approval timelines for commercial herd applications.
- DNA Sequencing:Illumina and Affymetrix platforms underpin reference genome assembly and imputation pipelines. SNP density standardization remains unresolved between vendor ecosystems.
- Genotyping:Medium-density SNP chips balance cost and prediction accuracy for routine parentage verification and genomic selection in dairy and beef populations.
Platform consolidation centers on Bioinformatics. Regulatory momentum favors CRISPR.
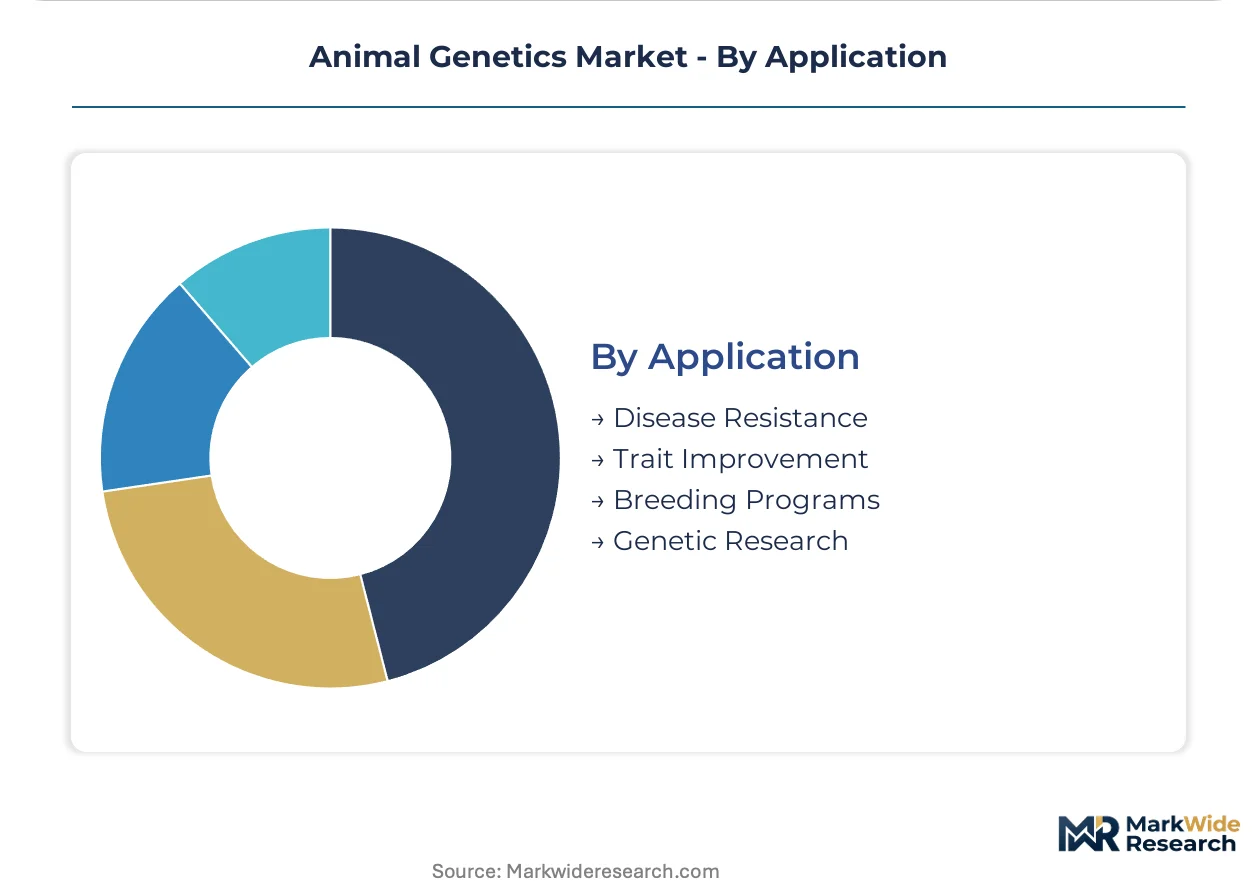
Application:
Use case priority reflects cost pressure in feed inputs and disease management versus trait premium capture.
- Trait Improvement:Feed efficiency and carcass quality selection dominate commercial breeding objectives. Residual feed intake predictions cut input costs for United States and Netherlands integrated producers.
- Disease Resistance:Genetic selection for mastitis tolerance and respiratory disease resilience reduces antibiotic dependence. Australian TGA's streamlined gene-editing notification pathway accelerates sheep flock applications.
- Breeding Programs:Nucleus herd multiplication and AI center networks propagate elite genetics through tiered multiplication pyramids.
- Genetic Research:Quantitative trait locus discovery and functional annotation underpin next-generation marker panels for commercial deployment.
Commercial scale concentrates in Trait Improvement. Regulatory tailwinds support Disease Resistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' Wageningen campus anchors Europe's densest concentration of livestock genetics research, with Dutch tax incentives for agricultural biotechnology R&D drawing nucleus herd operators and AI centers into Gelderland province.
United States
Wisconsin and California dairy cooperatives drive SNP chip volume for feed efficiency indexing. The FDA and USDA maintain bifurcated oversight of gene-edited livestock, extending approval timelines for novel traits. Texas Panhandle feedlot corridors now bundle genomic testing with nutritional modeling through single-vendor enterprise contracts.
China
Large-scale integrated pork producers in Sichuan and Guangdong provinces import elite breeding stock to rebuild herds after disease outbreaks. The country's national agricultural regulator classifies gene-edited animals under biosafety review pathways that remain less defined than Brazil's framework. Yangtze River Delta bioclusters host expanding reference population builds for commercial genomic selection.
Brazil
CTNBio's streamlined classification of gene-edited livestock without foreign DNA inserts accelerates field trials for heat-tolerance traits in commercial Nelore herds. São Paulo state concentrates artificial insemination infrastructure serving the country's beef multiplication pyramids. Federal agricultural credit programs subsidize genomic testing adoption among mid-scale producers in Mato Grosso.
Australia
TGA's notification-based pathway for site-directed nucleases reduces regulatory lag for disease-resistance traits in Merino flocks. New South Wales and Victoria host the densest networks of sheep breeding cooperatives deploying genomic advisory services. Melbourne-based bioinformatics platforms serve subscription demand from beef operations previously priced out of custom index calculations.
Netherlands
Dutch dairy cooperatives deploy single-step genomic evaluation models to halve sire ranking cycles, compressing market share for phenotype-only AI studs. EMA and EFSA coordination on genetically modified feed extends evaluation timelines under precautionary principles. Friesland and Overijssel provinces concentrate liquid nitrogen infrastructure serving European semen distribution networks.
Animal Genetics Market Vendor Landscape
North American producers anchor the dairy sire distribution tier; European specialists hold germplasm licensing and layer breeding positions. The market structure concentrates around cooperative networks controlling AI technician access, with three distribution systems dominating North American Holstein genetics. Strategic archetypes include integrated biotechnology platforms, nucleus herd operators with captive multiplication pyramids, and cloud-based genomic advisory services. Competitive moves center on M&A for bioinformatics capabilities and backward integration into reference population data assets.
Within the integrated platform tier, Zoetis and Genus PLC occupy positions spanning veterinary pharmaceuticals through germplasm distribution. Hendrix Genetics exemplifies the nucleus herd archetype through in-house layer breeding lines. Groupe Grimaud represents European specialization in multi-species genetic diversification. These anchors illustrate how value capture migrates from physical breeding stock sales toward recurring genomic evaluation subscriptions and proprietary trait licensing.
| Leading Market Players |
|---|
| Zoetis |
| Groupe Grimaud |
| Genus PLC |
| Neogen Corporation |
| Topigs Norsvin |
| Hendrix Genetics |
| CRV Holding |
| Alta Genetics |
| EW Group |
| Others |
Supply Flow & Price Mechanics
Liquid nitrogen spot price indices cascade through germplasm storage economics, compressing margins for regional semen facilities while concentrating pricing power among integrated cooperatives with captive cryogenic infrastructure.
Pricing Analysis
Expedited delivery premiums dominate transactional pricing for elite dairy sire semen, with standard inventory clearing at discounted rates. Three-tier pricing structure across premium, standard, and economy levels separates genomic-verified elite genetics from commercial-grade and unproven young sire categories. Price differentiation hinges on genomic reliability scores and cooperative membership status. Pricing pressure stems from energy cost volatility in cryogenic logistics. Small-to-mid beef operations exhibit highest price sensitivity, while integrated feedlot networks prioritize trait predictability over unit cost.
Supply Chain Analysis
REACH certification and USDA veterinary biologics qualification gates constrain reagent and diagnostic kit sourcing into European and North American markets. Production concentrates in the United States, the Netherlands, and Brazil. The supply chain draws from SNP chip foundries, liquid nitrogen infrastructure, and elite nucleus herd germplasm. Single-source vulnerability sits with Illumina's dominance in medium-density genotyping platforms. Distribution runs through artificial insemination cooperative networks and direct-to-producer genomic advisory platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are intensifying as bioinformatics talent scarcity and infrastructure capital requirements force mid-tier breeding companies toward acquisition or exit.
For Market Incumbents: Hedge against CRISPR regulatory divergence by maintaining parallel dossier preparation for FDA and EFSA pathways. Secure backward integration into reference population data assets through exclusive partnerships with university research herds. Channel control over AI technician networks remains the critical defensive lever against independent genetic suppliers. For New Entrants and Emerging Players: Cloud-based subscription platforms offer the lowest-friction entry vector for mid-tier beef operations previously priced out of genomic advisory services. Target underpenetrated layer breeding markets in Indonesia and Vietnam where domestic nucleus herds remain absent. Pursue turnkey breeding program licensing rather than germplasm sales to bypass cooperative distribution bottlenecks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier bioinformatics platforms in Australia and Brazil where regulatory clarity is accelerating field trial scaling. Long-term viability centers on recurring revenue models displacing transactional germplasm sales. Watch CTNBio and TGA gene-editing classification decisions as inflection signals for biotechnology solution valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Step Genomic Evaluation Deployment | Halves sire ranking cycles for Dutch and US cooperatives, compressing phenotype-only competitor market share. |
| CRISPR Field Trial Expansion | Brazil's CTNBio streamlining accelerates heat-tolerance trait commercialization in Nelore herds. |
| Cryogenic Infrastructure Modernization | EU F-Gas Regulation mandates energy-efficient liquid nitrogen systems across European AI centers. |
| Cloud-Based Advisory Platform Launch | Subscription revenue capture from small-to-mid beef operations previously excluded from custom index calculations. |
| Reference Population Data Partnership | Exclusive university herd agreements lock in imputation accuracy advantages for genomic prediction pipelines. |
Methodological Framework
Multi-period observation of SNP chip adoption rates, semen processing volumes, and gene-editing regulatory classification timelines anchored the trend analysis, supplemented by interviews with breeding program directors, AI center operations managers, genomic service platform executives, and veterinary diagnostic kit procurement leads. Secondary validation drew from USDA APHIS regulatory filings, EMA/EFSA coordination documents, CTNBio classification decisions, TGA notification pathways, and customs trade data for bovine germplasm imports. Bottom-up producer adoption modeling and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, end user sophistication, technology platform, and application use case structured the analytical framework. CAGRs were derived from fitted adoption curves and replacement cycle dynamics across the projection horizon. Forecast inputs incorporated dairy feed efficiency trait penetration rates, layer breeding program licensing velocity, and CRISPR regulatory pathway clarity indices.
Inputs from cooperative network disclosure filings and government agricultural biotechnology registers were available through the study window; gaps in private nucleus herd performance data introduce uncertainty bands around breeding stock valuation projections. Forecasts reflect documented assumptions regarding regulatory timeline stability and energy cost normalization. A model refresh is warranted upon material change in FDA-EFSA gene-editing classification convergence or liquid nitrogen supply contract restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Latin America Next Generation Sequencing Market
Genomics
UAE Genetic Testing Market
Genomics
Next Generation Genomics Market
Genomics
Global Next-Generation Sequencing (NGS) Services Market
Genomics
AI in Genomics Market
Genomics
Global Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Tumor-Sequencing Blood Testing Market
Genomics
Middle East and Africa Genetic Testing Market
Genomics
Reproductive Genetics Market
Genomics
Targeted DNA RNA Sequencing Market
Genomics
Whole Genome Amplification Market
Genomics
Next Generation Sequencing (NGS) Informatics Market
Genomics
Immunogenetics Market
Genomics
Agrigenomics Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Japan Next Generation Sequencing Market