
 APO E Gene Test Kit Market | 2026-2036
APO E Gene Test Kit Market Size, Share, and Industry Trends Forecast 2026-2036
APO E Gene Test Kit Market Insights
Saliva-based collection chemistry is rebalancing cost structures across the APO E gene test kit landscape, displacing blood-draw protocols in direct-to-consumer channels. 23andMe leverages its proprietary genotyping platform to sustain price competitiveness in the at-home segment. LabCorp anchors clinical credibility through its integrated laboratory network, while Thermo Fisher Scientific differentiates via upstream reagent and instrument control.
An APO E gene test kit detects allelic variants of the apolipoprotein E gene, typically through buccal swab or saliva specimens analyzed via PCR amplification or next-generation sequencing, to assess cardiovascular and neurodegenerative disease susceptibility. Laboratory Testing commands the dominant revenue share due to physician-mediated ordering and established CPT coding, though Direct-to-Consumer kits represent the fastest-expanding channel as telehealth platforms reduce traditional gatekeeping. Next-Generation Sequencing technology captures premium positioning through multi-gene panel integration, while Polymerase Chain Reaction retains volume leadership in point-of-care settings.
FDA premarket review pathways and CMS reimbursement determinations govern commercial viability for APO E test kits in the United States, with state-level laboratory licensing requirements creating additional compliance layers. The European Medical Device Regulation and IVDR classification standards shape market access timelines for manufacturers seeking CE marking. Stakeholders must monitor evolving FDA guidance on pharmacogenomic claims as the agency reconciles predictive utility with appropriate use criteria.
Market Dynamics
Saliva-based sample collection chemistry is compressing cost structures and eroding the traditional blood-draw infrastructure that once dominated APO E testing workflows.
Growth Catalysts
- Pharmacogenomic integration into clinical protocols:US-based health systems embed APO E data into statin selection algorithms, expanding physician-mediated test volumes through established CPT reimbursement pathways.
- Telehealth platform expansion:Virtual care delivery models reduce traditional gatekeeping friction, accelerating direct-to-consumer channel penetration without physical clinic visits.
- Polymerase Chain Reaction miniaturization:Point-of-care PCR devices enable same-result clinical workflows, displacing centralized laboratory routing for time-sensitive cardiovascular risk assessments.
Market Restraints
- Reagent supply concentration:Thermo Fisher Scientific and Illumina control critical PCR enzyme and sequencing consumable supply, creating input cost volatility for kit assemblers.
- FDA premarket review timelines:Laboratory-developed test enforcement discretion and direct-to-consumer kit classification create multi-year commercialization friction for novel APO E assay formats.
- Interpretation complexity:APO E ε2/ε3/ε4 variant penetrance varies across ancestry backgrounds, limiting predictive utility in non-European populations and constraining addressable market scope.
Strategic Opportunities
- Multi-gene panel convergence:Next-generation sequencing platforms integrate APO E with LDLR, PCSK9, and APOB variants, capturing premium positioning through comprehensive cardiovascular risk stratification.
- Employer wellness channel penetration:Self-insured corporations in the United States add pharmacogenomic screening to preventive benefit designs, bypassing traditional reimbursement gatekeepers.
- IVDR transition tailwinds:European Medical Device Regulation implementation creates competitive clearance advantages for manufacturers with notified body relationships and quality management maturity.
Industry Challenges
- Genetic counselor workforce scarcity:Interpretation of APO E results for neurodegenerative risk requires specialized counseling capacity that health systems struggle to staff at scale.
- Laboratory information system integration:APO E variant data lacks standardized HL7 FHIR implementation, forcing custom interface development for electronic health record connectivity.
- CE-IVD technical documentation burden:European performance evaluation requirements for common variant detection demand extensive analytical validation studies that compress development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APO E Gene Test Kit Market |
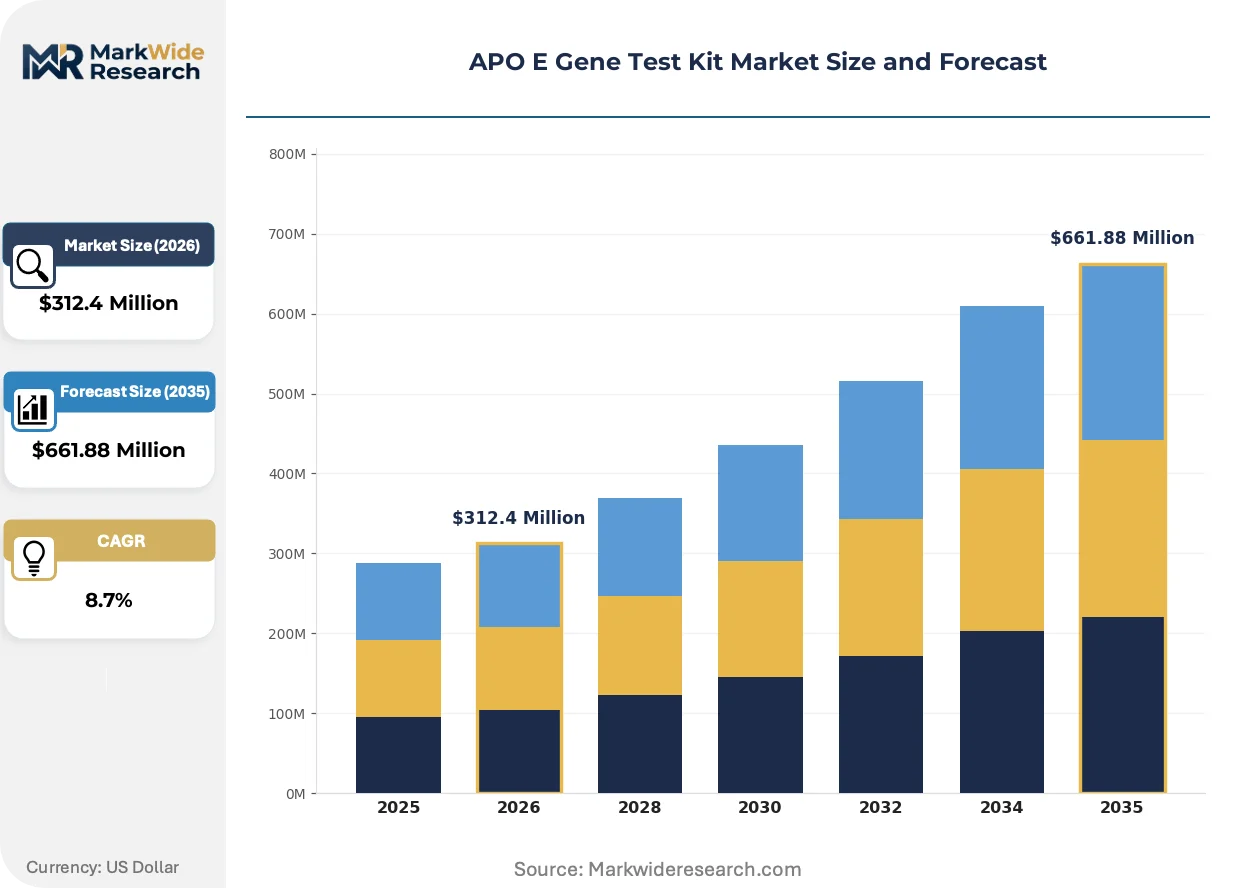
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct-to-Consumer, Laboratory Testing, At-Home Kits, Genetic Screening Technology: Polymerase Chain Reaction, Next-Generation Sequencing, Microarray Analysis, Bioinformatics Tools End User: Hospitals, Clinics, Research Institutions, Personal Users Application: Genetic Risk Assessment, Nutritional Guidance, Neurological Research, Personalized Medicine |
| Companies Covered | 23andMe, LabCorp, Quest Diagnostics, Myriad Genetics, Invitae Corporation, Thermo Fisher Scientific, Illumina, Inc., Color Genomics, Empower DX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APO E Gene Test Kit Market Trends and Innovations
Sample-to-answer automation and regulatory clarity around pharmacogenomic claims are compressing traditional testing workflows while expanding permissible commercial messaging.
Next-generation sequencing is consolidating multi-variant cardiovascular panels into single-workflow solutions, replacing discrete single-gene assays. Academic medical centers and integrated delivery networks adopt these platforms to reduce per-test reagent costs and consolidate vendor relationships. The technology is consolidating competitive positioning around upstream instrument and reagent control, favoring manufacturers with captive sequencing chemistry supply.
The European Medical Device Regulation and In Vitro Diagnostic Regulation classification standards are reshaping market access requirements for APO E test kits seeking CE marking. Manufacturers must demonstrate clinical evidence of analytical validity and, for higher-risk classifications, clinical performance against intended purpose. Small and mid-sized kit developers face compressed timelines to secure notified body engagement before transitional deadlines expire.
Employer-sponsored wellness programs are displacing traditional clinical ordering as the primary demand channel for preventive genetic screening. Self-insured corporations in the United States negotiate direct contracts with laboratory networks, bypassing physician gatekeeping and traditional reimbursement pathways. This shift concentrates purchasing power among benefits administrators rather than individual clinicians or patients.
APO E Gene Test Kit Market Segmentation
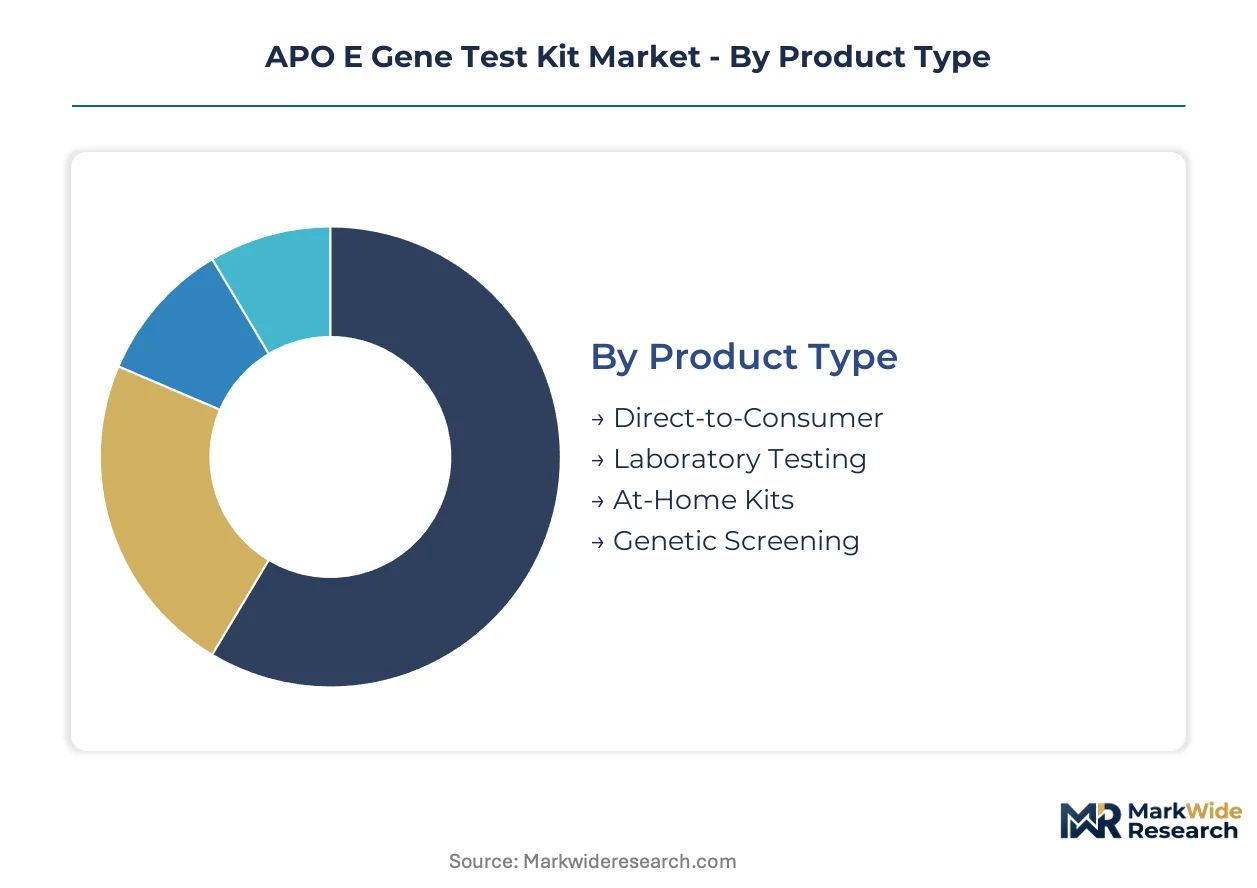
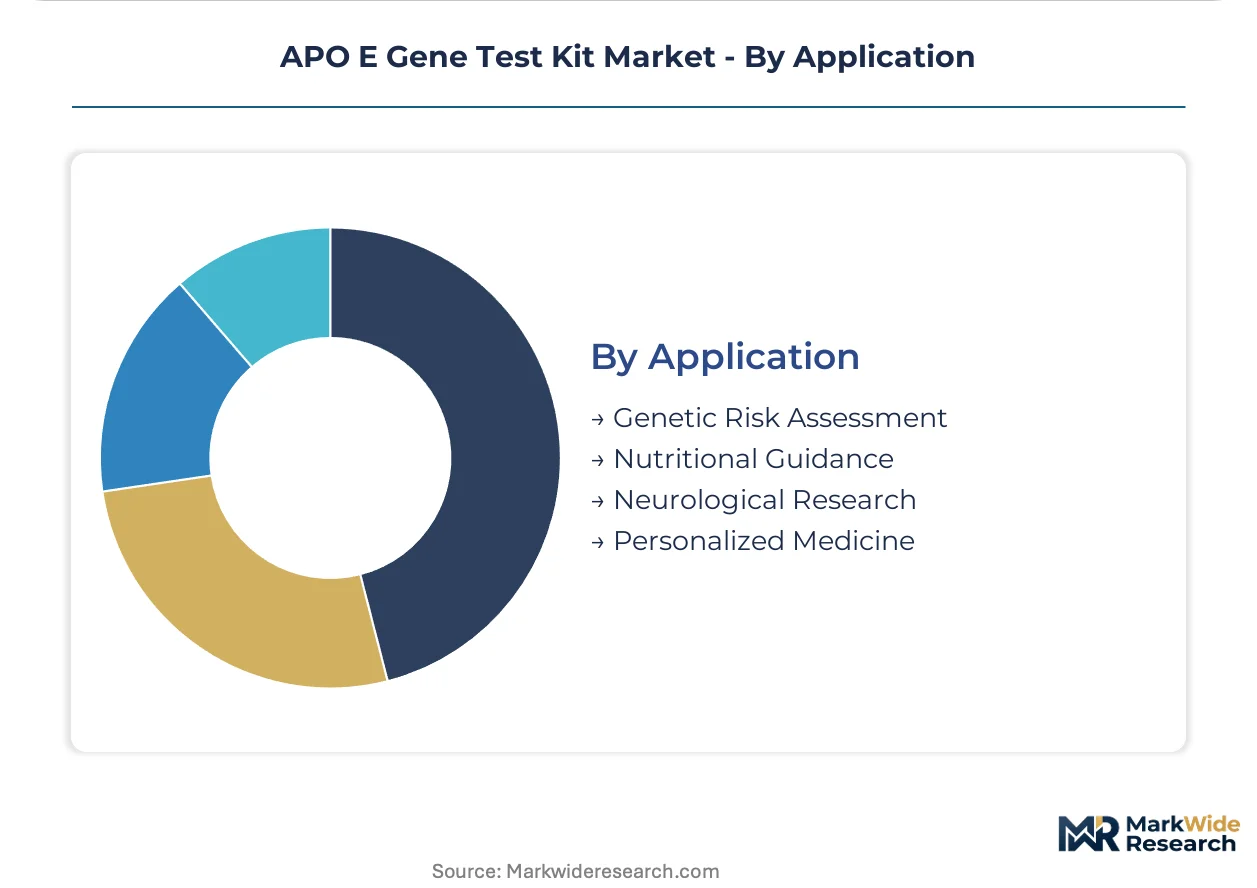
APO E gene test kit segmentation reveals divergent commercial models between regulated clinical channels and consumer-direct pathways. Technology choices and end-user access points determine pricing power, reimbursement eligibility, and regulatory burden across each segment cluster.
Product Type:
Product configuration dictates whether kits flow through physician-mediated ordering or bypass traditional healthcare gatekeepers entirely.
- Laboratory Testing:Physician-ordered assays processed through CLIA-certified facilities with established CPT coding for cardiovascular risk stratification. Hospital systems and specialty cardiology practices in the United States concentrate procurement volumes through integrated delivery network contracts.
- Direct-to-Consumer:Saliva-collection kits sold through e-commerce and telehealth platforms without mandatory clinical intermediation. Virtual care expansion and employer wellness programs accelerate channel penetration.
- At-Home Kits:Hybrid models requiring telehealth physician review before result release, navigating FDA enforcement discretion on pharmacogenomic claims.
- Genetic Screening:Population-scale offerings bundled with multi-gene cardiovascular panels for preventive health initiatives.
Laboratory Testing leads on scale; Direct-to-Consumer leads on momentum.
Technology:
Platform selection determines analytical sensitivity, throughput economics, and integration complexity with existing laboratory infrastructure.
- Polymerase Chain Reaction:Established amplification chemistry delivering ε2/ε3/ε4 variant detection at point-of-care throughput. Miniaturized thermal cycler devices enable same-day result workflows in cardiology clinics.
- Next-Generation Sequencing:Multi-gene panel integration capturing APO E alongside LDLR, PCSK9, and APOB variants. Academic medical centers consolidate vendor relationships around captive sequencing instrument supply.
- Microarray Analysis:Fixed-content genotyping platforms optimized for high-volume consumer screening with pre-designed variant content.
- Bioinformatics Tools:Variant interpretation software and clinical decision support modules required for pharmacogenomic reporting compliance.
Polymerase Chain Reaction dominates current installed base; Next-Generation Sequencing commands steepest expansion trajectory.
End User:
End-user category shapes purchasing authority, reimbursement pathways, and interpretation support requirements.
- Hospitals:Integrated delivery networks and academic medical centers with centralized laboratory infrastructure and genetic counselor staffing. Cardiology and lipidology departments drive test volume for statin selection protocols.
- Clinics:Outpatient cardiology and primary care settings adopting point-of-care PCR devices to reduce send-out delays.
- Research Institutions:Academic laboratories investigating APO E variant penetrance across diverse ancestry backgrounds for neurodegenerative disease cohort studies.
- Personal Users:Individual consumers accessing results through direct-to-consumer platforms or employer-sponsored wellness benefits.
Hospitals anchor procurement volume; Personal Users represent the fastest-climbing demand category.
Application:
Application focus determines clinical evidence requirements, regulatory classification, and permissible commercial claims.
- Genetic Risk Assessment:Cardiovascular disease susceptibility scoring for coronary artery disease and hyperlipidemia management. Physician-mediated ordering with established clinical utility evidence supports reimbursement.
- Personalized Medicine:Statin selection and dosing optimization based on APO E genotype-guided pharmacokinetic response.
- Neurological Research:Alzheimer's disease risk stratification applications facing FDA scrutiny on predictive utility claims for asymptomatic populations.
- Nutritional Guidance:Dietary recommendation algorithms linking APO E variants to saturated fat metabolism, operating in regulatory gray zones between wellness and medical device classification.
Genetic Risk Assessment commands revenue concentration; Personalized Medicine gains share fastest as pharmacogenomic protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors pharmacogenomic innovation through its dense concentration of direct-to-consumer genetic testing platforms and venture-backed bioinformatics ventures. Established reimbursement frameworks in the United States and European Union accelerate clinical adoption, while emerging markets in Asia-Pacific build laboratory infrastructure through public health initiatives.
United States
Integrated delivery networks in Massachusetts and North Carolina embed APO E testing into cardiology protocols for statin selection algorithms. FDA oversight of laboratory-developed tests and direct-to-consumer kits shapes commercialization timelines through premarket review pathways. The Research Triangle Park cluster in North Carolina concentrates clinical laboratory capacity serving employer wellness contracts.
Germany
University hospitals in Bavaria and Baden-Württemberg drive adoption of multi-gene cardiovascular panels integrating APO E variants into lipidology practice. The European Medical Device Regulation and IVDR classification standards govern CE marking timelines for kit manufacturers. The Munich biotech corridor hosts notified body relationships that accelerate quality management certification.
United Kingdom
The National Health Service's Genomic Medicine Service incorporates pharmacogenomic screening into regional genetics networks across England. Medicines and Healthcare products Regulatory Agency guidance on in vitro diagnostics shapes market access for APO E assay developers. The Cambridge-London corridor concentrates next-generation sequencing platform deployment in academic medical centers.
Japan
Pharmaceuticals and Medical Devices Agency oversight of genetic testing devices creates structured approval pathways for APO E kit manufacturers. The Kanto region around Tokyo hosts centralized clinical laboratory networks processing cardiovascular risk panels. Ministry of Economy, Trade and Industry initiatives promote precision medicine infrastructure in Osaka's medical device cluster.
China
National Medical Products Administration regulation of in vitro diagnostic reagents governs domestic manufacturing and import licensing for APO E test kits. The Yangtze River Delta around Shanghai concentrates contract research organizations conducting analytical validation studies. Beijing's healthcare reform pilots integrate pharmacogenomic data into tiered hospital prescribing systems.
APO E Gene Test Kit Market Competitive Landscape
Global majors compete with regional champions across technology platforms and distribution channels in the APO E gene test kit market. The vendor base stratifies into three tiers: multinational life science conglomerates controlling upstream reagent supply, national laboratory networks leveraging clinical credibility, and direct-to-consumer platforms optimizing digital acquisition. Strategic archetypes include instrument-captive sequencers, physician-mediated laboratory services, and telehealth-integrated wellness platforms. Competitive moves concentrate on multi-gene panel convergence and employer channel penetration.
Among platform-integrated conglomerates, Thermo Fisher Scientific and Illumina occupy positions defined by captive supply of PCR enzymes and sequencing consumables. 23andMe exemplifies the direct-to-consumer archetype through its proprietary genotyping infrastructure and digital-first distribution model. LabCorp represents the clinical laboratory network positioning, anchoring physician-mediated ordering through integrated testing facilities and established payer relationships.
| Leading Market Players |
|---|
| 23andMe |
| LabCorp |
| Quest Diagnostics |
| Myriad Genetics |
| Invitae Corporation |
| Thermo Fisher Scientific |
| Illumina, Inc. |
| Color Genomics |
| Empower DX |
| Others |
Pricing and Supply Chain Analysis
Employer wellness program procurement consolidation in the United States is compressing kit margins and forcing manufacturers to reconfigure reagent sourcing toward higher-volume contract structures. This demand-side concentration is reshaping how suppliers balance clinical-grade certification costs against direct-to-consumer price points.
Pricing Analysis
PCR enzyme and sequencing consumable costs pass through directly to kit assemblers, creating margin volatility when Thermo Fisher Scientific and Illumina adjust reagent pricing. Three-tier pricing structure across premium multi-gene panels, standard single-variant assays, and economy saliva-screening tiers reflects certification grade and clinical utility evidence depth. Pricing pressure stems from employer channel volume aggregation, which privileges scale suppliers. Hospital systems show lowest price sensitivity due to established CPT reimbursement; direct-to-consumer buyers face highest elasticity.
Supply Chain Analysis
Cold-chain logistics and specimen transport costs concentrate manufacturing proximity to major clinical laboratory clusters in the United States, Germany, and China. Critical inputs draw from Taq polymerase supply anchored in the United States, oligonucleotide synthesis concentrated in Germany and South Korea, and plastic consumables sourced from Chinese molders. Single-source vulnerability around FDA-cleared thermal cycler instruments creates procurement risk for point-of-care deployers. Distribution runs through CLIA-certified laboratory networks for clinical channels and direct fulfillment centers for consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The APO E gene test kit market has entered a late-cycle quality phase where clinical evidence depth and regulatory clearance status now determine procurement decisions ahead of raw price competition. Employer wellness programs are shifting specifications toward FDA-cleared multi-gene panels with embedded clinical decision support.
For Market Incumbents: To counter direct-to-consumer platform erosion of physician-mediated volumes, incumbents should deepen captive control over sequencing reagent supply through backward integration into oligonucleotide chemistry. Parallel investment in FDA 510(k) pathway acceleration for pharmacogenomic claims will defend hospital channel positioning against wellness-program price compression. For New Entrants and Emerging Players: Capture the at-home kit segment requiring telehealth physician review, where regulatory ambiguity has slowed incumbent entry and created white-space for agile developers. The employer wellness channel in self-insured US corporations offers the most penetrable procurement path, with benefits administrators seeking direct laboratory contracts bypassing traditional payer structures. For Investors and Strategic Acquirers: Asymmetric upside sits with platform-agnostic bioinformatics developers possessing clinical decision support modules compatible with multiple sequencing backends. Long-term viability hinges on IVDR transition readiness across the European access window. The signal to watch is FDA guidance publication on pharmacogenomic predictive claims for asymptomatic populations.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Technical Documentation Acceleration | Notified body engagement before IVDR transitional deadlines secures European market access for kit manufacturers. |
| Multi-Gene Cardiovascular Panel Integration | NGS platforms combining APO E with LDLR and PCSK9 variants capture premium hospital procurement contracts. |
| Employer Wellness Channel Direct Contracting | Self-insured corporations bypass physician gatekeeping and traditional reimbursement pathways for preventive screening. |
| Point-of-Care PCR Device Miniaturization | Same-day result workflows in cardiology clinics displace centralized laboratory routing for statin selection. |
| Pharmacogenomic Clinical Decision Support Development | FDA-compliant reporting modules enable permissible commercial claims for statin dosing optimization. |
Research Methodology
Multiple input streams — structured interviews with laboratory directors and genetic counselors, procurement data from hospital GPO contracts, and regulatory filing analysis — were reconciled against secondary validation from FDA 510(k) databases, CMS reimbursement schedules, and European notified body guidance documents. Primary fieldwork engaged CLIA laboratory managers, telehealth platform executives, and benefits administrators at self-insured employers. Bottom-up kit volume estimates triangulated with top-down market sizing derived from reagent supplier revenue disclosures.
Data-stream reconciliation across product type, technology platform, and end-user channel dimensions anchored the analytical framework over the projection horizon. Segmentation modeling captured laboratory testing versus direct-to-consumer pathway splits, PCR versus NGS technology transitions, and hospital versus employer wellness demand shifts. CAGRs were derived from regression analysis against pharmacogenomic protocol adoption curves and telehealth platform expansion rates.
Regulatory guidance revision, IVDR implementation delays, and genetic counselor workforce availability are the dominant revision risks that could compress or extend forecast trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Gene Sequencing Market
Genomics
Mitochondrial DNA Market
Genomics
Genetic Analysis Services Market
Genomics
Europe Genetic Testing Market
Genomics
Oligonucleotide Pool Market
Genomics
DNA Diagnostics Market
Genomics
North America Epigenetics Market
Genomics
Asia-Pacific Whole Exome Sequencing Market
Genomics
UAE Genetic Testing Market
Genomics
Restriction Endonucleases Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Genetic Material Market
Genomics
AI in Genomics Market
Genomics
Next Generation Genomics Market
Genomics
Global Mirna Sequencing and Assay Market