
 Genomics and Transcriptomics Market | 2026-2036
Genomics and Transcriptomics Market Size, Share, and Industry Trends Forecast 2026-2036
Genomics and Transcriptomics Market Analysis
Clinical-grade sequencing specifications is unwinding new revenue pools across the genomics and transcriptomics landscape. Illumina leverages its installed base of high-throughput platforms to sustain recurring consumable revenue. Bio-Rad Laboratories anchors its position through digital PCR specialization in oncology workflows. 10x Genomics differentiates via single-cell spatial transcriptomics systems that command premium placement in academic consortia.
Genomics and transcriptomics encompass the comprehensive study of DNA sequence variation, gene expression dynamics, and RNA population analysis through techniques measuring transcript abundance, splicing patterns, and epigenetic modulation with sensitivity thresholds reaching single-molecule detection. These disciplines enable target identification, patient stratification, and mechanistic understanding of disease progression across therapeutic development pipelines. Sequencing systems generate the dominant share of hardware revenue due to platform lock-in and reagent pull-through economics. Next-generation sequencing leads technology adoption while RNA sequencing captures the fastest expansion in immuno-oncology and neurodegeneration research. Pharmaceutical companies represent the highest-margin end-user segment given their scale and regulatory urgency around companion diagnostic co-development.
FDA oversees laboratory-developed test frameworks and premarket authorization pathways that directly shape commercialization timelines for transcriptomics-based diagnostics. EMA's In Vitro Diagnostic Regulation and ISO 15189 accreditation standards govern market access across European clinical laboratories. China's NMPA accelerates innovation through streamlined review channels for breakthrough genomic devices. Stakeholders must monitor evolving reimbursement determinations from Medicare and national health technology assessment bodies as these decisions will determine which transcriptomics applications transition from research expenditure to standard-of-care reimbursement.
Market Dynamics
Companion diagnostic co-development mandates from FDA and EMA are compressing timelines between biomarker discovery and commercial assay launch, forcing sequencing platform vendors to embed regulatory compliance into hardware architecture from initial design phases rather than retrofitting post-market.
Growth Catalysts
- Companion diagnostic frameworks:FDA's premarket authorization pathway and EMA's In Vitro Diagnostic Regulation create predictable commercialization routes for transcriptomics-based assays, accelerating pharmaceutical investment in biomarker programs.
- Single-cell resolution demand:Immuno-oncology and neurodegeneration research programs now require single-molecule sensitivity thresholds that only advanced RNA sequencing platforms deliver, pulling hardware upgrades across academic consortia.
- China precision medicine infrastructure:NMPA's streamlined review channels for breakthrough genomic devices concentrate manufacturing partnerships and clinical validation studies in Shanghai and Beijing bioclusters.
Market Restraints
- Reagent supply concentration:Sequencing consumables depend on specialized polymerase chemistries and modified nucleotide supply chains concentrated in select North American and European contract manufacturers.
- Platform lock-in economics:Instrument purchasing decisions commit laboratories to proprietary reagent ecosystems for multi-year depreciation cycles, raising switching costs and limiting vendor diversification.
- ISO 15189 accreditation complexity:European clinical laboratories face extended validation timelines for transcriptomics assays under harmonized quality management standards, delaying reimbursement eligibility.
Strategic Opportunities
- Liquid biopsy integration:Circulating tumor RNA analysis creates white space for transcriptomics platforms optimized for low-input samples, with oncology service lines in Germany and the United States piloting clinical workflows.
- Spatial transcriptomics convergence:Combination of in situ hybridization with single-cell sequencing enables tissue architecture mapping at sub-cellular resolution, opening premium pricing in immuno-oncology target discovery.
- India diagnostic expansion:CDSCO's emerging genomic device pathway and central government health scheme procurement create entry points for transcriptomics platforms in tier-two city hospital networks.
Industry Challenges
- Bioinformatics talent scarcity:Clinical laboratories lack computational biologists capable of interpreting complex RNA splicing patterns and fusion transcript calls for diagnostic reporting.
- Multi-omics data integration:Combining genomics, transcriptomics, and proteomics outputs requires interoperable pipelines that most institutional IT infrastructures cannot support without substantial capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genomics and Transcriptomics Market |
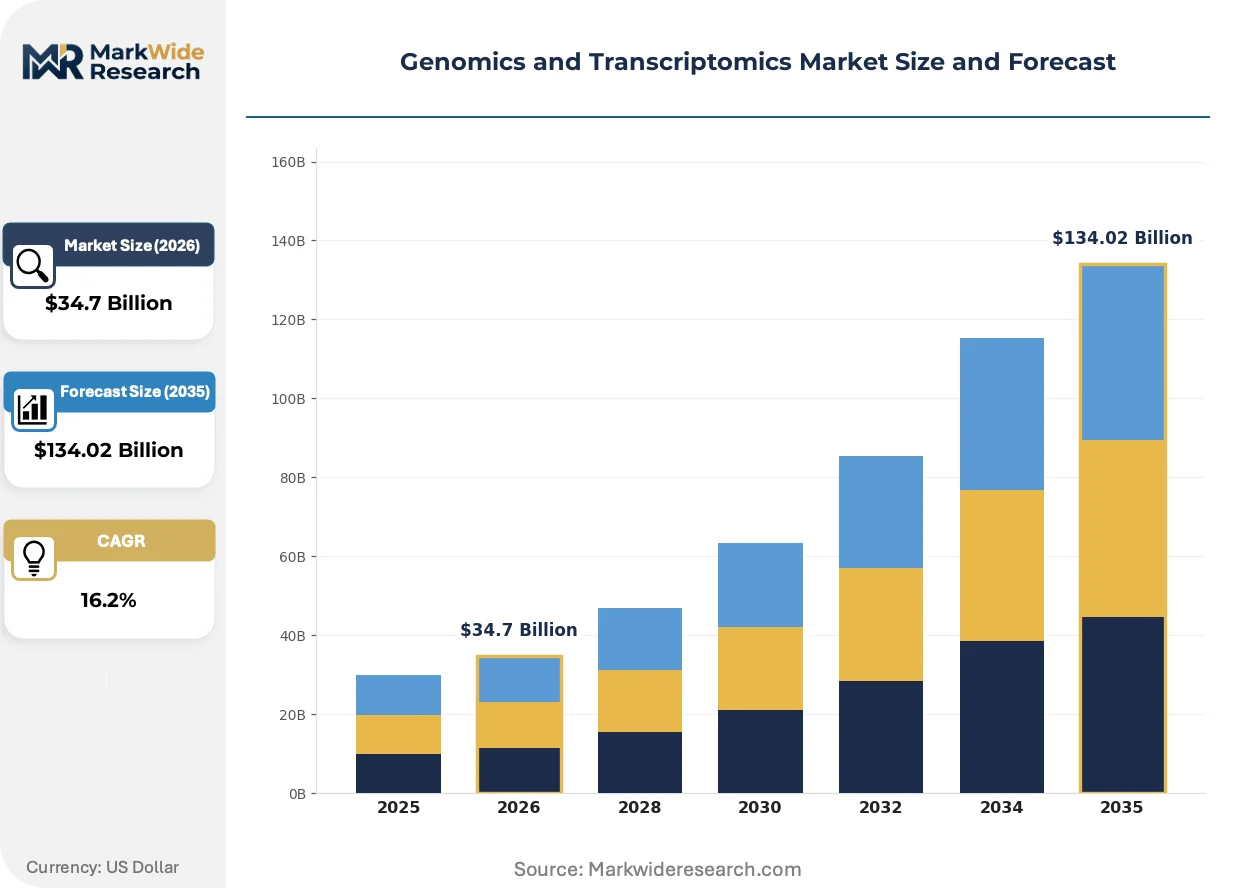
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $134.02 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sequencing Systems, Microarrays, PCR Kits, Reagents Technology: Next-Generation Sequencing, RNA Sequencing, Digital PCR, Sanger Sequencing End User: Research Institutions, Pharmaceutical Companies, Clinical Laboratories, Academic Institutes Application: Drug Discovery, Personalized Medicine, Clinical Diagnostics, Agricultural Genomics |
| Companies Covered | 10x Genomics, Illumina, NanoString Technologies, Bio-Techne, Bruker, Akoya Biosciences, Bio-Rad Laboratories, Standard BioTools, Revvity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genomics and Transcriptomics Market Emerging Trajectories
Transcriptomics instrumentation is compressing from room-scale systems to benchtop and eventually point-of-care formats, with regulatory science struggling to keep pace with hardware evolution and data output explosion.
Long-read sequencing technology is miniaturizing from centralized core facilities to distributed laboratory settings. Pharmaceutical toxicology groups now deploy portable RNA analysis for rapid compound screening. This format shift is compressing the traditional centralization economics that sustained Illumina's installed base dominance.
REACH regulation amendments governing chemical substances in laboratory reagents are forcing sequencing consumable manufacturers to reformulate polymerase buffers and fluorescent dyes. European diagnostic manufacturers face supply continuity risks during transition periods. German and French clinical laboratories are stockpiling legacy reagent lots to bridge validation gaps.
Pharmaceutical procurement teams now unbundle instrument purchasing from mandatory service contracts and reagent commitments. Large-scale buyers negotiate spot pricing for sequencing consumables through group purchasing organizations. This behavior is most visible among United States-based biopharma companies with centralized sourcing functions managing multi-site platform deployments.
Genomics and Transcriptomics Market Segmentation
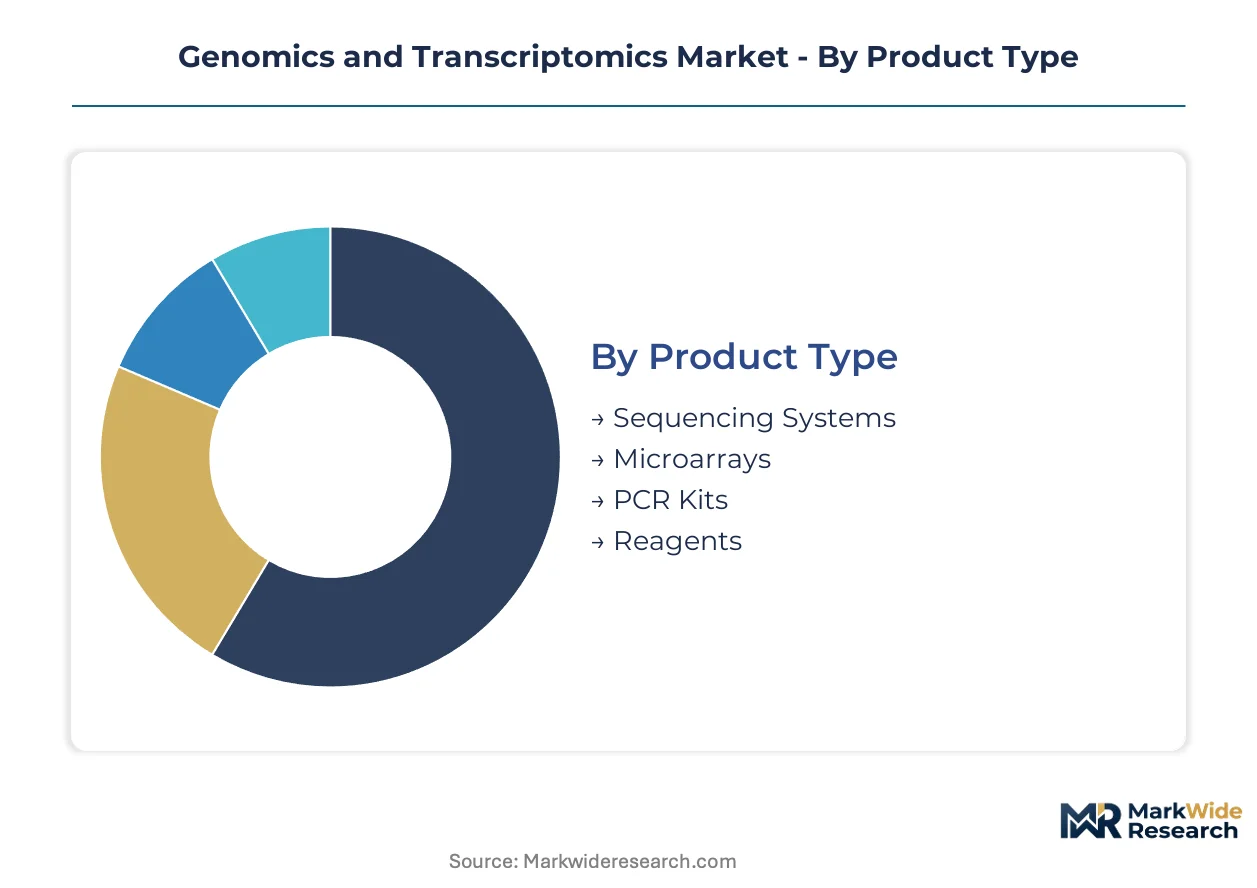
Segmentation in genomics and transcriptomics reveals divergent margin structures and purchasing behaviors across hardware, consumables, and services. Platform economics create distinct channel strategies for capital equipment versus recurring reagent revenue streams.
Product Type:
Capital equipment flows through direct sales teams with embedded field service engineers, while consumables penetrate via distribution partners and e-procurement platforms.
- Sequencing Systems:High-throughput platforms with integrated cluster generation and imaging subsystems command seven-figure price points. Pharmaceutical companies in the United States and Germany drive replacement cycles as companion diagnostic programs mandate CLIA-certified and ISO 15189-compliant infrastructure.
- Reagents:Polymerase master mixes, adapter oligonucleotides, and fluorescent nucleotides generate recurring revenue through proprietary cartridge formats. Supply concentration in North American contract manufacturers creates vulnerability during REACH regulatory transitions.
- Microarrays:Solid-state nucleic acid detection platforms for genotyping and CNV analysis serve agricultural genomics and ancestry testing segments with standardized content.
- PCR Kits:Lyophilized reagent formulations for digital PCR workflows target oncology liquid biopsy applications with minimal cold-chain requirements.
By volume, Reagents leads. By growth pace, Sequencing Systems is ahead.
Technology:
Cost tiers separate centralized core facility platforms from distributed benchtop systems, with premium pricing attached to single-molecule resolution capabilities.
- Next-Generation Sequencing:Short-read cluster amplification and sequencing-by-synthesis chemistry dominates installed base economics. Academic consortia in China concentrate procurement through national precision medicine infrastructure grants.
- RNA Sequencing:Full-length transcript capture and splice variant detection enables immuno-oncology biomarker programs. Pharmaceutical toxicology groups deploy portable formats for rapid compound screening.
- Digital PCR:Absolute quantification without standard curves supports rare allele detection in circulating tumor DNA workflows.
- Sanger Sequencing:Capillary electrophoresis for targeted validation retains niche positioning in clinical genetics confirmatory testing.
By installed base, Next-Generation Sequencing dominates. By expansion trajectory, RNA Sequencing is climbing the fastest.
End User:
Customer type determines pricing elasticity, with pharmaceutical procurement teams unbundling instrument purchases from service contracts while academic buyers accept bundled offerings.
- Pharmaceutical Companies:Centralized sourcing functions negotiate spot pricing for multi-site platform deployments. FDA and EMA companion diagnostic mandates compress timelines between biomarker discovery and commercial assay validation.
- Research Institutions:Core facility subsidization models spread capital costs across investigator groups. Single-cell spatial transcriptomics systems command premium placement through shared equipment grants.
- Clinical Laboratories:ISO 15189 accreditation requirements extend validation timelines for transcriptomics assays in European markets.
- Academic Institutes:Training-focused installations prioritize benchtop formats with simplified bioinformatics pipelines over maximum throughput specifications.
By revenue contribution, Pharmaceutical Companies leads. By volume placement, Research Institutions is gaining share fastest.
Application:
Maturity curves diverge sharply, with clinical diagnostics requiring regulatory clearance while agricultural genomics operates under research-use-only frameworks.
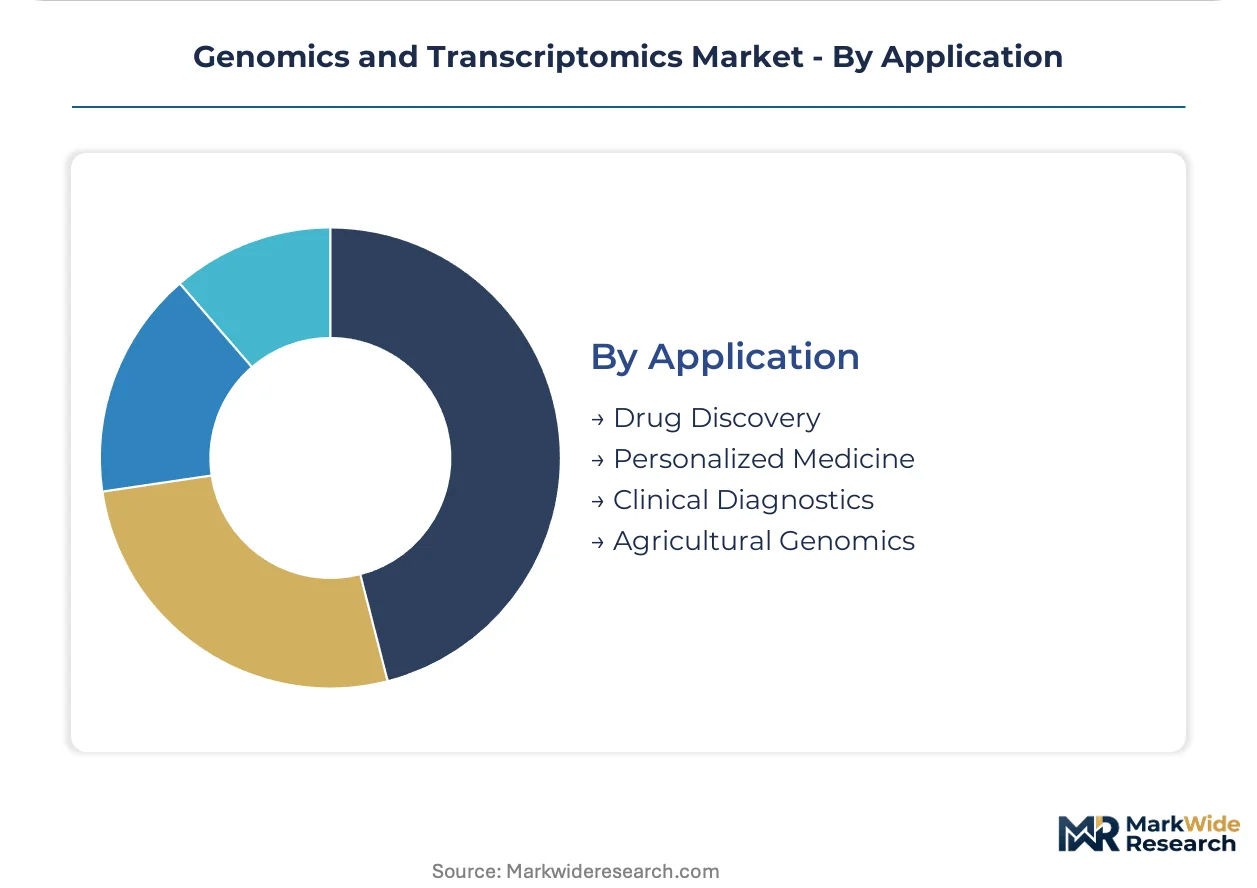
- Drug Discovery:Target identification and mechanistic understanding of disease progression across therapeutic pipelines. Toxicology groups deploy rapid RNA analysis for compound screening with miniaturized long-read platforms.
- Personalized Medicine:Patient stratification based on gene expression signatures and RNA splicing patterns. Medicare reimbursement determinations will dictate transition from research expenditure to standard-of-care coverage.
- Clinical Diagnostics:Laboratory-developed test frameworks and premarket authorization pathways shape commercialization timelines under FDA oversight.
- Agricultural Genomics:Marker-assisted breeding and trait selection operate without diagnostic regulatory burden in most jurisdictions.
By current revenue, Drug Discovery leads. By regulatory urgency, Personalized Medicine is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in genomics and transcriptomics equipment tilt toward net imports in emerging markets while the United States, Germany, and China maintain manufacturing surpluses in sequencing platforms and specialized reagents. Capital equipment shipments concentrate through regional distribution hubs that service clinical laboratory networks.
United States
Pharmaceutical toxicology groups in Massachusetts and California drive demand for portable RNA analysis systems. FDA premarket authorization pathways and CLIA certification requirements shape commercialization timelines for companion diagnostic programs. The Greater Boston biocluster anchors validation studies for breakthrough genomic devices.
Germany
EMA In Vitro Diagnostic Regulation and ISO 15189 accreditation standards govern market access for clinical laboratories in Baden-Württemberg and Bavaria. REACH regulation amendments force reagent manufacturers to reformulate polymerase buffers. Heidelberg and Munich hospital networks pilot liquid biopsy workflows for circulating tumor RNA analysis.
China
NMPA streamlined review channels accelerate innovation timelines for domestic sequencing platform vendors. National precision medicine infrastructure grants concentrate procurement through Shanghai and Beijing bioclusters. Yangtze River Delta manufacturing partnerships supply modified nucleotides to regional reagent producers.
United Kingdom
NHS England reimbursement determinations dictate transition of transcriptomics applications from research expenditure to standard-of-care coverage. MHRA post-Brexit regulatory frameworks align with EMA guidance on companion diagnostics. London and Cambridge academic consortia deploy single-cell spatial transcriptomics systems through shared equipment grants.
India
CDSCO emerging genomic device pathway and central government health scheme procurement create entry points for transcriptomics platforms. Bioinformatics talent scarcity limits clinical laboratory expansion in tier-two cities. Karnataka and Maharashtra hospital networks pilot oncology service lines with circulating tumor DNA workflows.
Genomics and Transcriptomics Market Vendor Landscape
Listed leaders compete with private specialists across platform economics and regulatory compliance capabilities. The vendor base stratifies between diversified life science conglomerates and focused genomics pure-plays. Three archetypes dominate: installed-base incumbents leveraging reagent pull-through, single-cell resolution specialists commanding premium academic placement, and digital PCR anchors in oncology workflows. Competitive moves center on unbundling instrument purchases from mandatory service contracts and embedding regulatory compliance into hardware architecture from initial design phases.
Within the installed-base tier, Illumina exemplifies recurring consumable revenue models through proprietary cartridge formats. 10x Genomics occupies a position representing single-cell spatial transcriptomics specialization in academic consortia. Bio-Rad Laboratories anchors the digital PCR archetype in clinical oncology workflows. These three entities collectively represent the strategic positioning vectors that shape competitive dynamics across sequencing systems, reagent supply, and diagnostic assay development.
| Leading Market Players |
|---|
| 10x Genomics |
| Illumina |
| NanoString Technologies |
| Bio-Techne |
| Bruker |
| Akoya Biosciences |
| Bio-Rad Laboratories |
| Standard BioTools |
| Revvity |
| Others |
Supply Flow & Price Mechanics
Modified nucleotide substitution for legacy fluorescent dyes under REACH amendments simultaneously shifts reagent manufacturing toward North American contract manufacturers and compresses margin structures for European diagnostic producers. Pharmaceutical procurement teams exploit this geographic reconfiguration to negotiate spot pricing for sequencing consumables through group purchasing organizations.
Pricing Analysis
Pharmaceutical OEM buyers anchor three-tier pricing stratification across premium CLIA-certified platforms, standard research-grade systems, and economy benchtop formats. Price differentiation hinges on FDA premarket authorization tier and after-sales service bundling. Cost compression in economy tiers intensifies as academic consortia unbundle instrument purchases from mandatory reagent commitments. Research institutions exhibit highest price sensitivity due to shared-equipment grant dependencies, while pharmaceutical toxicology groups absorb premium pricing for portable RNA analysis capabilities.
Supply Chain Analysis
United States and Germany anchor specialized polymerase chemistry production, while China concentrates modified nucleotide manufacturing through Yangtze River Delta partnerships. Sequencing consumables draw from fluorescent dye formulations, lyophilized enzyme master mixes, and proprietary adapter oligonucleotides. Single-source vulnerability concentrates in European contract manufacturers during REACH regulatory transition periods. Distribution runs through regional hub-and-spoke networks servicing CLIA-certified and ISO 15189-accredited clinical laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform specialization is fragmenting competitive architecture as single-cell spatial transcriptomics and liquid biopsy workflows create distinct capability niches beyond installed-base dominance.
For Market Incumbents: Secure reagent pull-through economics by embedding regulatory compliance into hardware architecture from initial design phases rather than post-market retrofitting. Deepen backward integration into modified nucleotide supply chains to offset REACH transition risks. Prioritize CLIA-certified and ISO 15189-accredited infrastructure partnerships to defend against emerging platform vendors targeting pharmaceutical companion diagnostic programs. For New Entrants and Emerging Players: Anchor in India CDSCO emerging genomic device pathway and central government health scheme procurement to bypass saturated United States and European installed-base markets. Target tier-two city hospital networks in Karnataka and Maharashtra where bioinformatics talent scarcity has limited incumbent expansion. Deploy simplified bioinformatics pipelines as primary go-to-market wedge against complex core-facility platforms. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed digital PCR specialists possessing ISO 13485 manufacturing infrastructure but limited companion diagnostic validation capabilities. Five-to-ten year viability hinges on FDA premarket authorization pathway execution rather than research-use-only revenue streams. Monitor Medicare reimbursement determinations for circulating tumor RNA analysis as inflection signal for transcriptomics applications transitioning from research expenditure to standard-of-care coverage.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Embedding | FDA premarket authorization pathway integration from initial hardware design phases compresses commercialization timelines for companion diagnostic programs. |
| Reagent Supply Backward Integration | Captive production of polymerase chemistries and modified nucleotides insulates margin structures from REACH regulatory transition disruptions. |
| Liquid Biopsy Platform Optimization | Low-input sample capabilities for circulating tumor RNA analysis open oncology service line placements in Heidelberg and Munich hospital networks. |
| Spatial Transcriptomics Convergence | In situ hybridization integration with single-cell sequencing commands premium pricing in immuno-oncology target discovery consortia. |
| India Market Entry Pathway | CDSCO emerging genomic device registration and central government health scheme procurement create tier-two city hospital network access points. |
Methodological Framework
Cross-validation between primary interviews with sequencing platform engineers, pharmaceutical toxicology directors, clinical laboratory quality managers, and GPO contracts specialists anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, NMPA breakthrough device designations, and CMS Medicare reimbursement determinations. Bottom-up instrument shipment analysis and top-down precision medicine infrastructure spending triangulation resolve segmentation discrepancies.
Sensitivity analysis across technology adoption curves, regulatory approval timelines, and reimbursement policy scenarios shapes the analytical framework over the projection horizon. Segmentation dimensions model product type, technology platform, end-user archetype, and application maturity across the analysis window. CAGRs derive from installed base replacement cycles, reagent consumption intensity per instrument, and geographic precision medicine infrastructure deployment rates.
Decision-makers should treat outputs as directional under stable FDA and EMA companion diagnostic policy assumptions; material deviation in Medicare reimbursement determinations or REACH enforcement timelines would warrant model refresh. Recalibration cycles align with material shifts in national precision medicine infrastructure grant allocations and pharmaceutical toxicology group procurement centralization patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Analysis Services Market
Genomics
Europe Digital PCR Market
Genomics
Molecular Breeding Market
Genomics
Asia Pacific Pharmacogenetics Testing in Psychiatry/Depression Market
Genomics
Global Lab Automation in Genomics Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Mitochondrial DNA Market
Genomics
Latin America Gene Expression Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Mendelian Disorders Testing Market
Genomics
Rare Disease Genetic Testing Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Asia-Pacific Genetic Testing Market
Genomics
NGS Automation Market
Genomics
Global NGS Sample Preparation Market