
 North America Microarray Market | 2026-2036
North America Microarray Market Size, Share, and Industry Trends Forecast 2026-2036
North America Microarray Market Analytics
Market Context
The split between premium high-density arrays and commodity low-density formats is hardening as end users diverge on sensitivity requirements and throughput economics. Thermo Fisher Scientific leverages its integrated instrument-reagent platform to sustain pricing power in the clinical diagnostics channel. Agilent Technologies anchors the premium research segment through specialized SurePrint manufacturing capabilities.
Technical Definition and Segments
North America microarrays are solid substrates—typically glass slides, silicon wafers, or nitrocellulose membranes—spotted or synthesized with thousands of nucleic acid probes, proteins, or tissue sections for parallel molecular detection, with feature densities ranging from hundreds to millions of targets per square centimeter. DNA microarrays retain the largest installed base across academic and pharmaceutical research, though protein microarrays are gaining structural momentum in biomarker discovery pipelines where post-translational modification profiling proves essential. Next-generation sequencing competes directly with hybridization-based microarrays for genomics applications, yet PCR-based microarray formats maintain durable positions in rapid diagnostic workflows where turnaround time governs purchasing decisions.
Regulatory Environment
FDA 510(k) and premarket approval pathways shape commercialization timelines for diagnostic microarrays, while CLIA regulations govern clinical laboratory validation standards across the United States. Health Canada and the FDA coordinate on harmonized quality system requirements, though provincial laboratory licensing in Ontario and Quebec introduces additional compliance layers. Stakeholders must monitor how emerging FDA guidance on artificial-intelligence-enabled diagnostic algorithms reclassifies software-integrated microarray readout systems.
Market Dynamics
The North America microarray market is experiencing a fundamental restructuring as next-generation sequencing platforms compress the addressable space for hybridization-based genomic analysis, forcing array manufacturers to defend installed bases through workflow integration and diagnostic certification strategies.
Growth Catalysts
- FDA 510(k) pathway acceleration:Streamlined premarket notification processes for in vitro diagnostics are shortening commercialization timelines for companion diagnostic microarrays, particularly in oncology biomarker validation.
- Boston-Cambridge biotech corridor concentration:Dense clustering of pharmaceutical R&D facilities in Massachusetts is generating concentrated demand for high-density expression profiling arrays and specialized manufacturing partnerships.
- Protein post-translational modification profiling:Rising structural importance of phosphorylation and glycosylation analysis in immuno-oncology pipelines is expanding the functional addressable market beyond nucleic acid detection.
Market Restraints
- Silicon wafer supply concentration:Dependence on specialized semiconductor-grade substrate suppliers in East Asia creates input cost volatility and geographic supply risk for high-density array manufacturing.
- Next-generation sequencing substitution:Declining per-base sequencing costs are systematically displacing whole-genome microarray applications in research settings, compressing the premium segment addressable market.
- Health Canada provincial licensing fragmentation:Divergent laboratory certification requirements between Ontario and Quebec introduce compliance complexity that extends market entry timelines for diagnostic array platforms.
Strategic Opportunities
- Point-of-care infectious disease testing:CLIA-waived PCR-microarray hybrid formats present underpenetrated expansion potential in urgent care and retail clinic channels across the United States.
- Artificial intelligence-enabled readout systems:Emerging FDA guidance on algorithm-based diagnostic interpretation is creating regulatory tailwinds for software-integrated microarray platforms with automated variant classification.
- San Francisco Bay Area cell therapy manufacturing:CAR-T and gene therapy process development workflows in Northern California are generating specialized demand for quality-control microarray applications in vector characterization.
Industry Challenges
- Bioinformatics specialist scarcity:Shortage of trained computational biologists capable of integrating multi-omic microarray data with clinical phenotypes is constraining pharmaceutical adoption of complex profiling platforms.
- CLIA laboratory certification timelines:Extended validation periods for high-complexity molecular testing under Clinical Laboratory Improvement Amendments are delaying revenue recognition for newly launched diagnostic arrays.
- Multi-platform data harmonization:Inconsistent file formats and analysis pipelines between Agilent, Thermo Fisher, and Illumina array systems are forcing redundant bioinformatics infrastructure investments at academic medical centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Microarray Market |
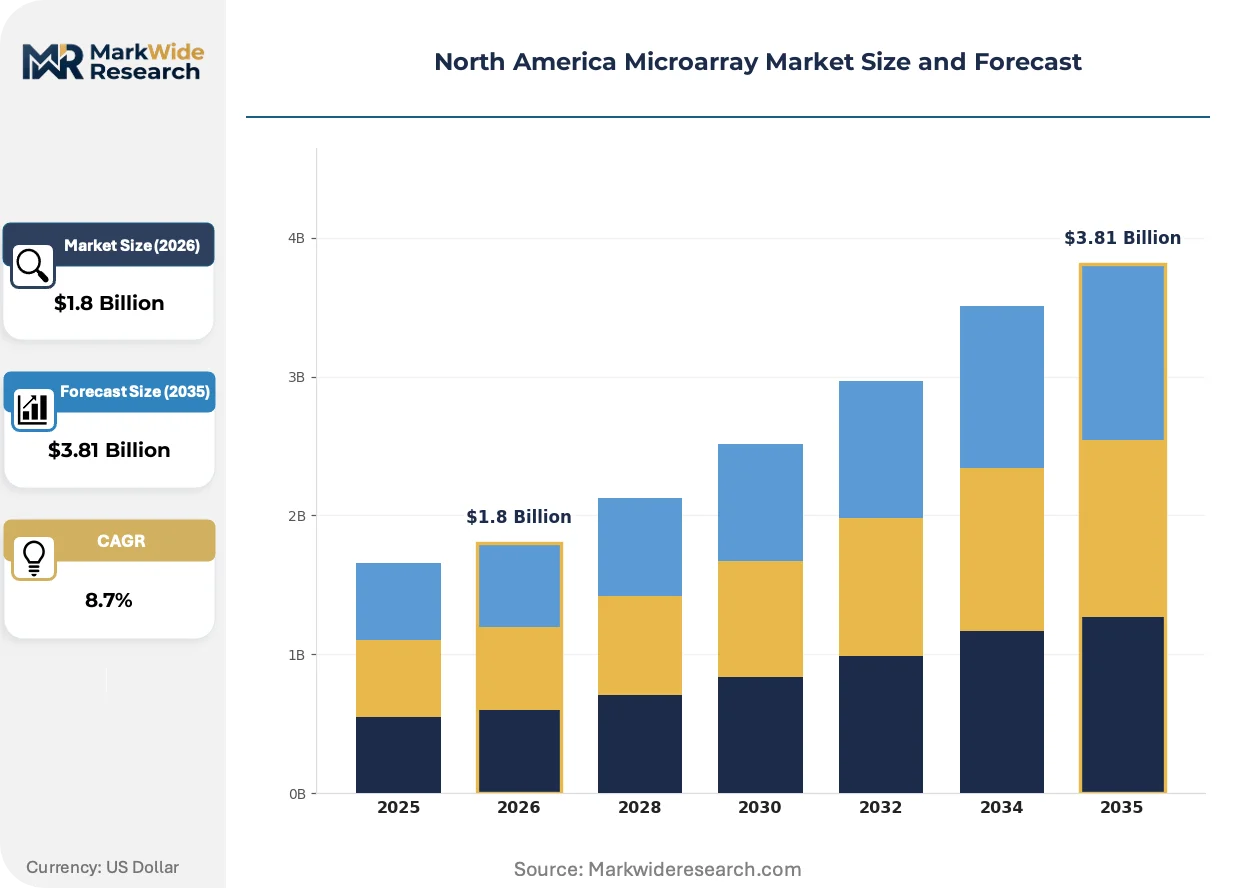
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Microarrays, Protein Microarrays, Tissue Microarrays, SNP Microarrays Application: Genomics, Diagnostics, Drug Discovery, Personalized Medicine Technology: Hybridization, PCR-based, Next-Generation Sequencing, Labeling Techniques End User: Academic Research, Pharmaceutical Companies, Clinical Laboratories, Biotechnology Firms |
| Companies Covered | Bio-Rad Laboratories Inc., Merck KGaA, Thermo Fisher Scientific Inc., Molecular Devices LLC, Arrayit Corporation, Agilent Technologies Inc., PerkinElmer Inc., RayBiotech Inc., Illumina Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Microarray Market Evolving Landscape
Digital microfluidics and miniaturized cartridge formats are actively redrawing the competitive boundary between centralized reference laboratories and distributed testing environments, compressing the traditional trade-off between throughput and accessibility.
Digital microfluidics-based sample preparation is decentralizing nucleic acid processing workflows previously confined to high-throughput core facilities. Regional hospital networks in Texas and Florida are adopting benchtop integrated systems that combine microfluidic cartridge handling with automated hybridization protocols. This architecture is decentralizing molecular diagnostic capability into mid-volume clinical settings while preserving analytical sensitivity standards.
Health Canada and FDA coordination on harmonized quality system requirements is accelerating cross-border diagnostic array commercialization, though provincial laboratory licensing in Ontario maintains distinct compliance layers. The mutual recognition framework reduces redundant manufacturing audits but requires dual-track regulatory documentation. Pharmaceutical companion diagnostic developers are responding by structuring parallel submission strategies that leverage FDA premarket approval timelines to precondition Health Canada reviews.
Academic medical centers are consolidating procurement authority for microarray platforms under centralized core facility management, displacing departmental purchasing autonomy that historically fragmented vendor relationships. The University of California system and Mayo Clinic have implemented enterprise-level reagent rental agreements that bundle instrument placement with per-sample consumable pricing. This concentration is most visible in the Northeast corridor, where institutional purchasing cooperatives are extracting volume-based pricing concessions from array manufacturers.
North America Microarray Market Segmentation
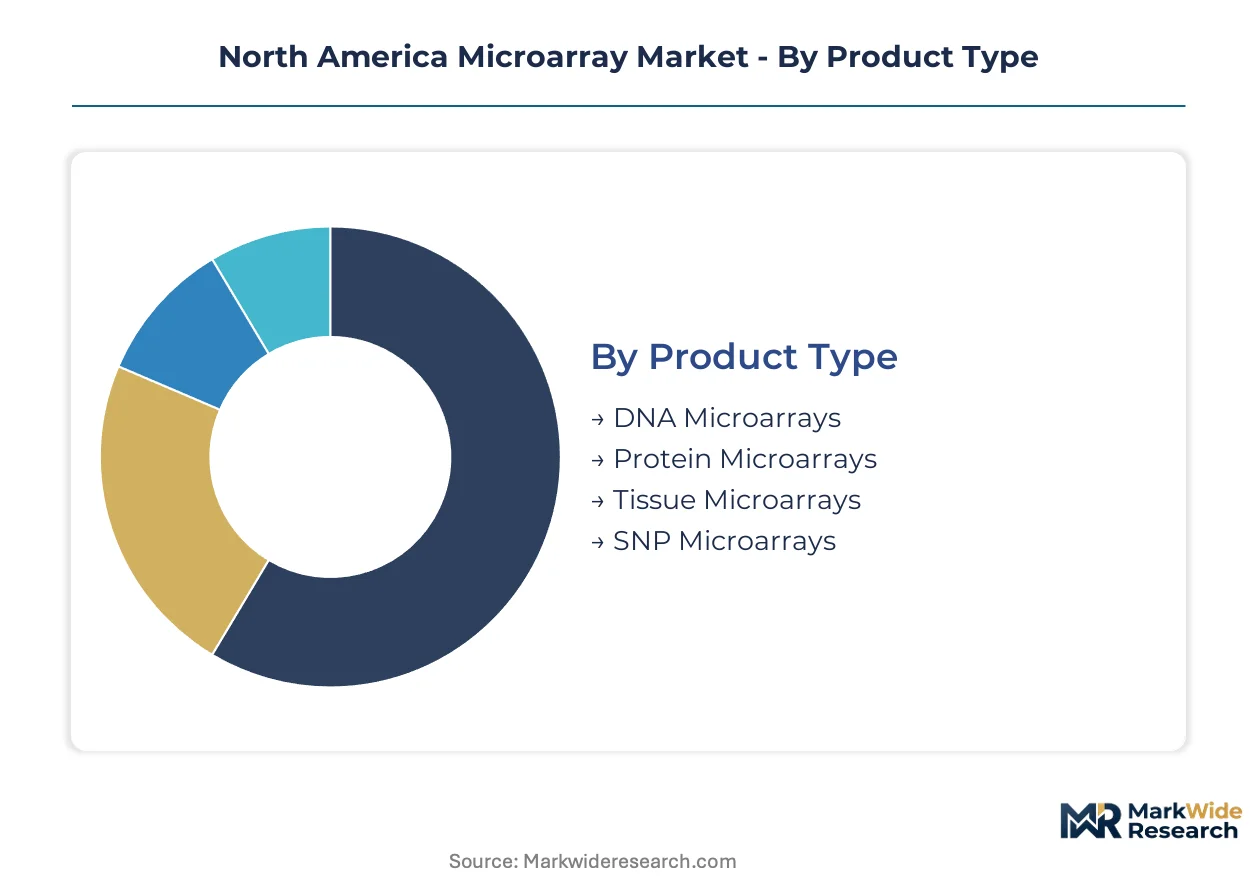
Microarray purchasing decisions fragment across technical specifications, regulatory pathways, and end-use economics. Each segmentation axis reveals distinct margin structures and vendor control points that shape competitive positioning in North American markets.
Product Type:
Customization intensity spans from off-the-shelf expression panels to fully bespoke disease-specific arrays, with manufacturing complexity and validation burden determining price architecture.
- DNA Microarrays:Oligonucleotide or cDNA probes immobilized on glass or silicon substrates for gene expression profiling and comparative genomic hybridization. Demand concentrates in the Boston-Cambridge biotech corridor for oncology biomarker validation, constrained by next-generation sequencing displacement in research settings.
- Protein Microarrays:Capture antibodies or recombinant proteins spotted for multiplexed antibody detection and post-translational modification mapping. San Francisco Bay Area immuno-oncology pipelines drive structural momentum as phosphorylation profiling becomes essential for checkpoint inhibitor development.
- Tissue Microarrays:Paraffin-embedded tissue cores arrayed for high-throughput immunohistochemistry and in situ hybridization. Academic medical centers in the Northeast corridor deploy these for retrospective biomarker studies.
- SNP Microarrays:Genotyping panels targeting single nucleotide polymorphisms for pharmacogenomics and ancestry analysis. Clinical laboratories favor these for FDA-cleared companion diagnostic workflows.
Leading the category by volume: DNA Microarrays. Expanding most quickly: Protein Microarrays.
Application:
Revenue concentration shifts from exploratory research budgets toward reimbursable diagnostic testing, altering procurement authority and pricing power.
- Genomics:Whole-genome association studies, expression profiling, and structural variation detection. Academic core facilities in Texas and Florida maintain installed bases despite sequencing competition.
- Diagnostics:FDA-cleared in vitro tests for infectious disease, cancer, and pharmacogenomic screening. CLIA-waived PCR-microarray hybrids present expansion potential in urgent care channels.
- Drug Discovery:High-throughput compound screening and toxicogenomics in pharmaceutical R&D. Massachusetts-based developers leverage specialized manufacturing partnerships for companion diagnostic co-development.
- Personalized Medicine:Patient stratification for targeted therapy selection and adverse event prediction. Ontario and Quebec provincial laboratory licensing introduces compliance complexity that extends market entry timelines.
Dominant by revenue: Diagnostics. Gaining share fastest: Personalized Medicine.
Technology:
Platform selection hinges on turnaround time requirements, multiplexing depth, and compatibility with existing laboratory automation infrastructure.
- Hybridization:Fluorescent probe-target binding on solid substrates, the foundational microarray chemistry. Retains position in copy number variation analysis where sequencing costs remain prohibitive.
- PCR-based:Amplification-coupled detection for enhanced sensitivity in low-abundance target detection. Digital microfluidics integration is decentralizing workflows into mid-volume clinical settings.
- Next-Generation Sequencing:Massively parallel sequencing platforms competing directly for genomic analysis budgets. Systematically displacing whole-genome microarray applications in research settings.
- Labeling Techniques:Direct and indirect fluorescent, chemiluminescent, or colorimetric detection methods. Emerging FDA guidance on AI-enabled readout systems favors automated variant classification platforms.
Widest installed base: Hybridization. Steepest expansion trajectory: PCR-based.
End User:
Procurement centralization under enterprise agreements is displacing fragmented departmental purchasing, compressing vendor margins while locking in volume commitments.
- Academic Research:University core facilities and principal investigator laboratories. The University of California system and Mayo Clinic have implemented enterprise-level reagent rental agreements bundling instrument placement with per-sample consumable pricing.
- Pharmaceutical Companies:Biomarker validation, companion diagnostic development, and toxicogenomics screening. Dense clustering in Massachusetts generates concentrated demand for high-density expression profiling arrays.
- Clinical Laboratories:Hospital-based and independent reference labs performing reimbursable molecular testing. Extended CLIA validation periods for high-complexity molecular testing delay revenue recognition for newly launched diagnostic arrays.
- Biotechnology Firms:CAR-T and gene therapy developers requiring quality-control applications in vector characterization. Northern California cell therapy manufacturing workflows create specialized demand.
Largest volume purchaser: Academic Research. Fastest-growing demand: Biotechnology Firms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge biotech corridor concentrates North American microarray demand through dense pharmaceutical R&D clustering and companion diagnostic development pipelines. FDA clearance pathways and Health Canada harmonization efforts compress cross-border commercialization timelines. Provincial laboratory licensing in Ontario and Quebec introduces compliance complexity that extends market entry for diagnostic platforms.
United States
Pharmaceutical companies in Massachusetts and California scale microarray deployment for biomarker validation and CAR-T quality control. FDA 510(k) pathway acceleration shortens commercialization timelines for oncology companion diagnostics. The San Francisco Bay Area generates specialized demand for vector characterization in gene therapy manufacturing workflows.
Canada
Health Canada coordinates with FDA on harmonized quality system requirements for diagnostic array commercialization. Provincial laboratory licensing in Ontario and Quebec maintains distinct compliance layers that extend validation timelines. Toronto and Montreal academic medical centers deploy tissue microarrays for retrospective biomarker studies in immuno-oncology.
Mexico
COFEPRIS regulatory alignment with FDA standards accelerates diagnostic microarray registration for cross-border supply chains. Manufacturing partnerships in Baja California and Chihuahua support consumable production for US clinical laboratories. Mexico City hospital networks adopt PCR-microarray hybrid formats for infectious disease testing expansion.
North America Microarray Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification grade and manufacturing complexity dimensions. Thermo Fisher Scientific leverages integrated instrument-reagent platforms to sustain pricing power in clinical diagnostics. Agilent Technologies anchors the premium research segment through specialized manufacturing capabilities. Three archetypes dominate: diversified life science conglomerates with full workflow integration, specialized array manufacturers with bespoke content libraries, and sequencing-platform competitors defending genomic analysis share. Consolidation pressure intensifies as next-generation sequencing substitution compresses addressable space for hybridization-based formats.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Agilent Technologies Inc. exemplify the integrated-platform archetype through instrument-reagent bundling strategies. Merck KGaA and Bio-Rad Laboratories Inc. occupy positions within the reagent and analytical instrumentation tier. Illumina Inc. represents the sequencing-platform competitor archetype that directly contests hybridization-based microarray applications. Specialized manufacturers including RayBiotech Inc. and Arrayit Corporation sit within the bespoke content and protein array segment. Molecular Devices LLC and PerkinElmer Inc. anchor the laboratory instrumentation and detection systems tier.
| Leading Market Players |
|---|
| Bio-Rad Laboratories Inc. |
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Molecular Devices LLC |
| Arrayit Corporation |
| Agilent Technologies Inc. |
| PerkinElmer Inc. |
| RayBiotech Inc. |
| Illumina Inc. |
| Others |
Value Network & Pricing Analysis
Semiconductor-grade silicon wafer spot prices and specialized glass substrate indices cascade through North American microarray manufacturing into three distinct pricing tiers tied to probe density and clinical certification status. Input cost volatility from East Asian substrate suppliers compresses margins on commodity low-density formats while reinforcing pricing power for FDA-cleared diagnostic-grade arrays.
Pricing Analysis
Per-sample consumable pricing anchored to diagnostic throughput and clinical outcome sensitivity dominates the North American market, with Thermo Fisher Scientific and Agilent Technologies extracting premiums through instrument-reagent bundling. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-validated companion diagnostic arrays from research-grade expression panels and unvalidated screening formats. Pricing pressure stems from next-generation sequencing substitution in genomic applications, forcing hybridization-based vendors to absorb reagent cost increases. Academic core facilities exhibit highest price sensitivity due to consolidated procurement authority, while pharmaceutical companion diagnostic developers prioritize regulatory certification over unit economics.
Supply Chain Analysis
Direct-to-clinical-laboratory channels handle high-throughput diagnostic demand, while specialized research distributors serve fragmented academic procurement. Manufacturing concentration in Taiwan, South Korea, and Germany supplies semiconductor-grade silicon wafers, borosilicate glass substrates, and precision spotting instrumentation. Raw material dependencies include photolithographic resists, nucleic acid synthesis reagents, and fluorescence detection chemistries. Single-source vulnerability for specialized nitrocellulose membranes creates supply continuity risk during geopolitical trade disruptions. Distribution runs through integrated life science distributors, direct field service organizations, and reagent rental agreements with enterprise health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American microarray competition is accelerating into a vertical-integration race, with manufacturers pursuing captive control over substrate fabrication and bioinformatics software stacks to defend margin structures against sequencing-platform encroachment.
For Market Incumbents: Anticipate next-generation sequencing substitution by locking in CLIA-waived PCR-microarray hybrid workflows for point-of-care infectious disease testing, while deepening backward integration into specialized glass and silicon substrate production to offset East Asian supply risk. FDA 510(k) pathway acceleration for AI-enabled readout systems represents the critical certification lever for pricing power retention. For New Entrants and Emerging Players: The mid-tier price-point gap between premium Agilent research platforms and economy Thermo Fisher clinical systems creates entry space for digital microfluidics-based benchtop systems targeting regional hospital networks in Texas and Florida. CLIA-waived urgent care channels present the most penetrable white space, with per-sample consumable pricing and automated sample preparation as the viable go-to-market angle. For Investors and Strategic Acquirers: Distressed-cycle entries favor protein microarray specialists with phosphorylation profiling capabilities in the San Francisco Bay Area immuno-oncology corridor, where checkpoint inhibitor pipeline demand outstrips specialized manufacturing supply. Long-term viability hinges on companion diagnostic co-development partnerships with Massachusetts-based pharmaceutical developers. The signal to monitor is Health Canada-FDA harmonization progress on AI-enabled diagnostic algorithm classification, which would revalue software-integrated platform assets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Acceleration | Streamlined premarket notification compresses oncology companion diagnostic commercialization timelines for Massachusetts developers. |
| Digital Microfluidics Integration | Benchtop cartridge systems decentralize molecular testing into mid-volume Texas and Florida clinical settings. |
| AI-Enabled Readout Development | Automated variant classification software aligns with emerging FDA guidance on algorithm-based diagnostic interpretation. |
| Backward Substrate Integration | In-house silicon wafer and glass slide production reduces East Asian supply concentration vulnerability. |
| Enterprise Reagent Rental Agreements | University of California and Mayo Clinic-style bundling locks in volume commitments against sequencing displacement. |
Research Methodology
FDA 510(k) premarket notification databases, Health Canada medical device licensing records, and CLIA laboratory certification registries formed the secondary backbone for regulatory pathway and commercialization timeline assessment. Primary interviews with companion diagnostic development executives, clinical laboratory directors, biomedical procurement managers at academic medical centers, and regulatory affairs specialists at array manufacturers were cross-validated against secondary sources. Bottom-up triangulation against top-down macroeconomic indicators ensured segmentation integrity across product type, application, technology, and end-user dimensions.
Bottom-up modeling of installed base, replacement cycles, and per-sample consumable attach rates was reconciled with top-down pharmaceutical R&D spending allocation and clinical laboratory capital equipment budgets across the analysis window. Segmentation dimensions included probe density tier, regulatory certification status, hybridization versus PCR-based chemistry, and geographic concentration in the Boston-Cambridge and San Francisco Bay Area corridors. CAGRs were derived from regression analysis of historical instrument placement and consumable revenue trajectories, with next-generation sequencing substitution rates and FDA approval velocity as key forecast inputs.
Inputs from FDA premarket databases and Health Canada licensing systems were available through the study window; gaps in proprietary pharmaceutical companion diagnostic pipeline disclosures introduce uncertainty bands around segment growth assumptions. Forecasts reflect documented base-case assumptions regarding regulatory harmonization progress and sequencing cost decline curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next Generation Genomics Market
Genomics
Non Invasive Prenatal Testing (NIPT) Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
Genetic Analysis Services Market
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Point-Of-Care Genetic Testing Market
Genomics
Mrna Sequencing Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Global Clinical Oncology Next Generation Sequencing Market
Genomics
North America Genetic Testing Market
Genomics
Genomic Biomarkers Market
Genomics
Dna Polymerase Market
Genomics
Global Nutrigenomics Market
Genomics
Multiomics Market