
 DNA Sequencing Market | 2026-2036
DNA Sequencing Market Size, Share, and Industry Trends Forecast 2026-2036
DNA Sequencing Market Intelligence
Clinical-grade accuracy standards is rotating demand away from research-only platforms toward diagnostic-validated systems. Illumina, Inc. dominates high-throughput instrument placements across major genome centers. Thermo Fisher Scientific Inc. leverages its integrated consumables-instrument workflow to sustain recurring revenue density. PacBio specializes in long-read applications where structural variant resolution anchors premium pricing power.
DNA sequencing denotes the determination of nucleotide order within a DNA molecule, typically resolving base-pair composition through enzymatic synthesis, single-molecule fluorescence, or nanopore conductance detection at throughput rates exceeding millions of reads per run. Its primary commercial purpose centers on identifying genetic variation, pathogen signatures, and gene-expression profiles to inform therapeutic selection, breeding programs, and forensic identification. Next-Generation Sequencing commands the dominant share of instrument-installed bases and consumables pull-through, while Sanger Sequencing retains stable demand for targeted validation and small-scale genotyping. Consumables generate the deepest margin pools due to per-run reagent depletion and proprietary cartridge lock-in. Clinical Diagnostics represents the fastest-expanding application as reimbursement codes broaden for somatic tumor profiling and hereditary disease screening.
The FDA regulates sequencing-based diagnostic devices through premarket notification and De Novo pathways, while the EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment requirements on European clinical laboratories. ISO 15189 accreditation and CLIA certification shape operational readiness for diagnostic-grade sequencing services. Stakeholders must monitor evolving payer coverage determinations for multi-gene panel tests and whole-genome sequencing in neonatal and oncology settings.
Market Dynamics
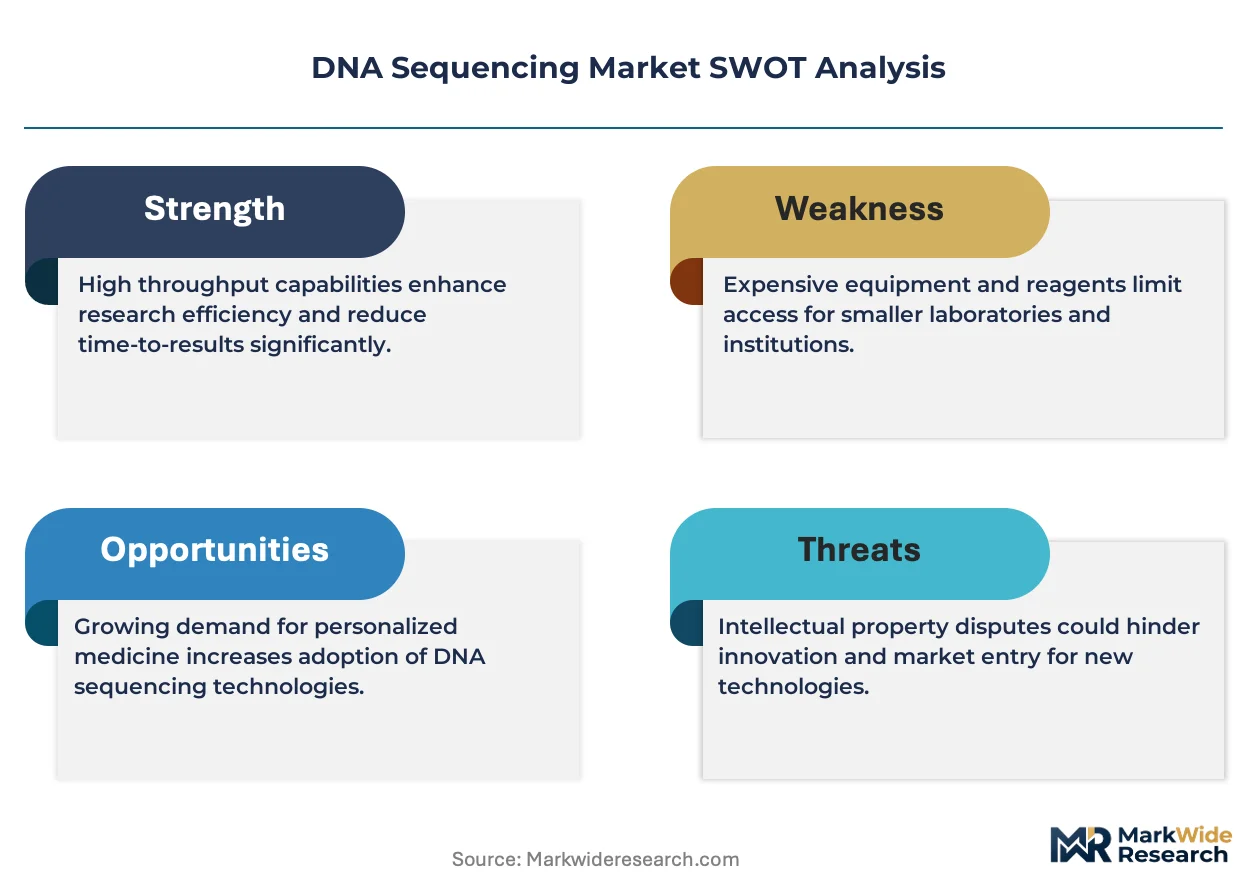
The transition from research-grade to clinical-validated sequencing platforms is compressing vendor margins while expanding addressable patient populations through diagnostic reimbursement codes.
Growth Catalysts
- CLIA laboratory certification expansion:The FDA's De Novo pathway for tumor profiling tests accelerates laboratory accreditation across United States cancer centers, pulling high-throughput instrument demand.
- Structural variant resolution demand:Long-read sequencing adoption in rare disease diagnostics creates premium consumables pull-through for cases refractory to short-read methods.
- Hereditary screening protocol integration:National health systems in Germany and France embed prenatal sequencing into standard obstetric workflows, normalizing clinical-grade accuracy expectations.
Market Restraints
- Consumables cost concentration:Proprietary reagent cartridges lock laboratories into single-vendor workflows, amplifying per-run cost exposure when list prices adjust.
- Bioinformatics talent scarcity:Variant interpretation pipelines require specialized computational biologists, constraining laboratory scaling velocity outside major academic clusters.
- Reimbursement lag:Payer coverage determinations for whole-genome sequencing trail technology capability by multiple policy cycles, deferring revenue recognition for service providers.
Strategic Opportunities
- Point-of-care sequencing miniaturization:Handheld nanopore devices enable infectious disease surveillance at district hospitals in India, bypassing centralized laboratory infrastructure constraints.
- Pharmacogenomic panel mandates:Japan's PMDA guidance on warfarin and clopidogrel dosing creates regulatory tailwinds for preemptive genotyping in cardiovascular protocols.
- AI-augmented variant classification:Machine learning integration with tertiary analysis software compresses reporting turnaround times, differentiating service laboratory offerings.
Industry Challenges
- ISO 15189 accreditation timelines:Quality management system implementation for diagnostic-grade sequencing extends facility commissioning by twelve to eighteen months.
- Legacy LIS integration complexity:Electronic health record interoperability gaps force manual data transfer between sequencing platforms and hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DNA Sequencing Market |
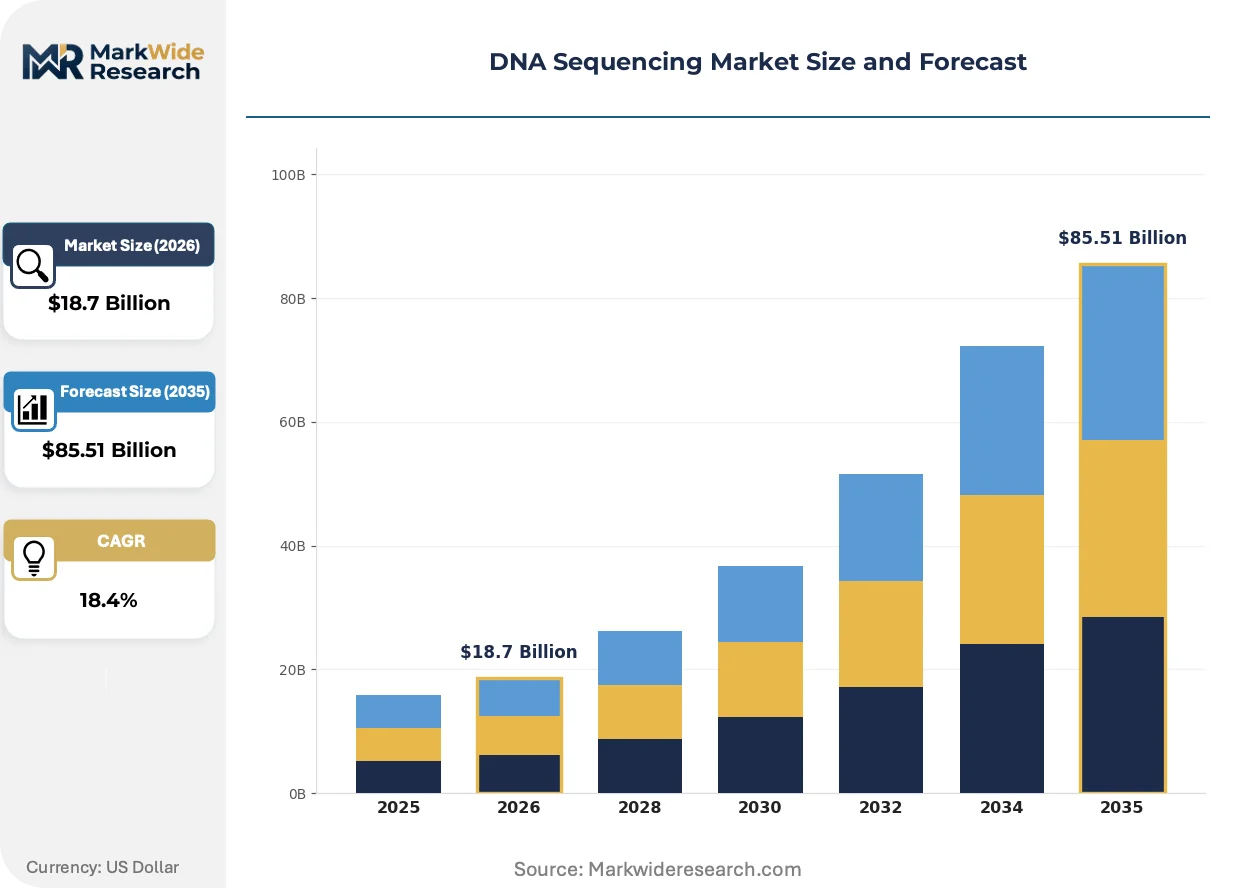
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $85.51 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Next-Generation Sequencing, Sanger Sequencing, Pyrosequencing, Sequencing by Synthesis, Solid-State Sequencing Product Type: Instruments, Consumables, Software, Services, Reagents Application: Genomic Research, Forensic Analysis, Agricultural Biotechnology, Clinical Diagnostics, Evolutionary Biology End User: Research Institutes, Diagnostic Laboratories, Pharmaceutical Companies, Agricultural Firms, Academic Centers |
| Companies Covered | Illumina, Inc., Thermo Fisher Scientific Inc., PacBio, Oxford Nanopore Technologies plc., QIAGEN, Agilent Technologies Inc., F. Hoffmann-La Roche Ltd., PerkinElmer Genomics, BGI Genomics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DNA Sequencing Market Strategic Shifts & Innovations
Sequencing technology maturation is fragmenting the vendor landscape into specialized modality camps, each optimized for distinct read-length, throughput, and capital-intensity profiles.
Long-read platforms are displacing short-read dominance in de novo assembly and structural variation detection. Reference laboratories in the United States and Germany now deploy Pacific BioSciences and Oxford Nanopore systems alongside Illumina infrastructure for complex cases. This modality diversification compresses per-sample economics while expanding clinically actionable variant yield.
The EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment requirements on European clinical laboratories offering sequencing-based tests. Commercial service providers must maintain technical documentation and post-market surveillance systems previously required only of device manufacturers. German and French academic medical centers are consolidating sequencing operations into centralized CLIA-equivalent facilities to distribute compliance overhead.
Hospital procurement committees now mandate total-cost-of-ownership modeling over instrument acquisition price alone. Reagent consumption rates, service contract terms, and bioinformatics licensing fees factor into vendor selection at United States academic medical centers. This analytical rigor favors integrated workflow providers with transparent consumables pricing and penalizes point-solution vendors with hidden downstream costs.
DNA Sequencing Market Segmentation
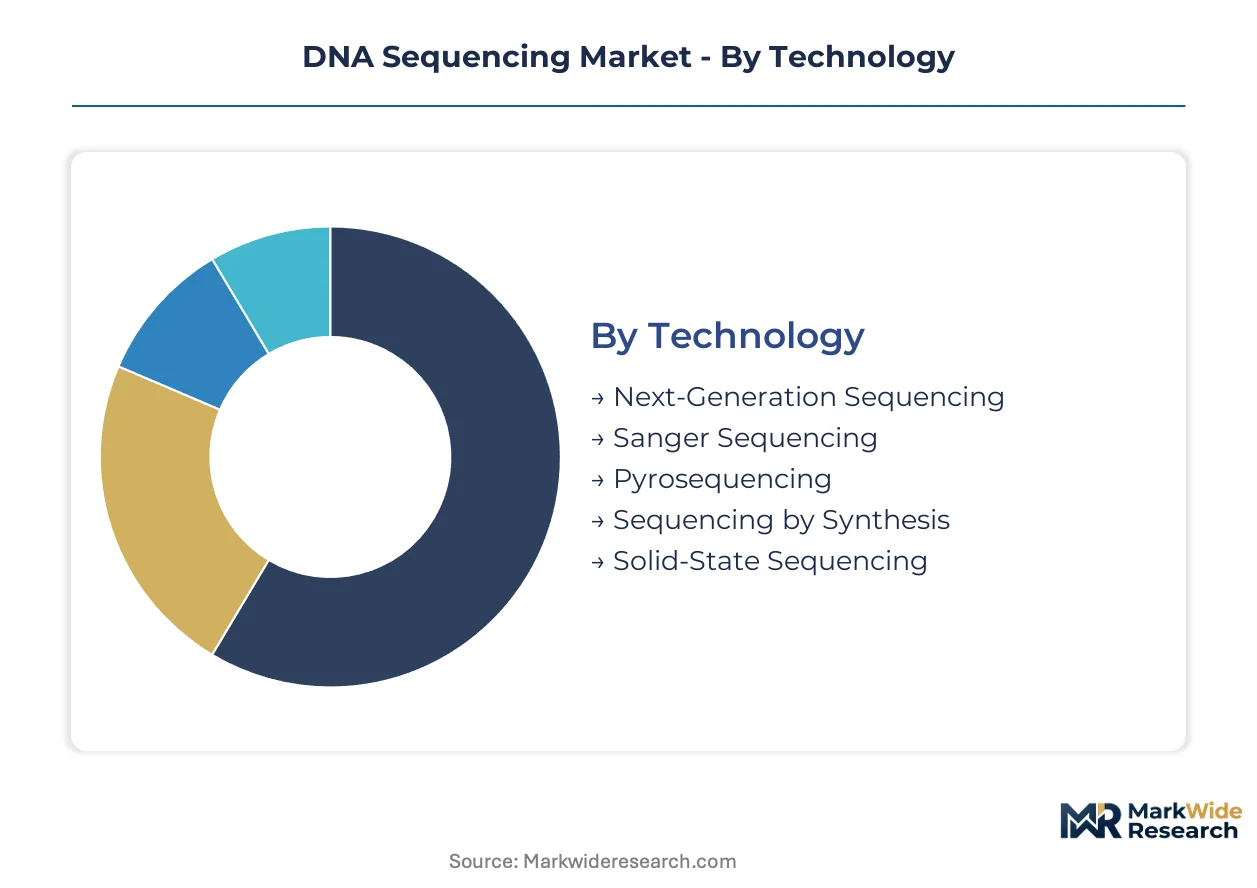
Technology modality and product mix determine margin capture in DNA sequencing, with consumables lock-in and clinical validation tiers creating divergent profitability profiles across vendor portfolios. End-user concentration in academic medical centers versus distributed diagnostic laboratories shapes instrumentation scale and service contract structures.
Technology:
Margin pools concentrate in proprietary enzymatic chemistries and detection subsystems that lock laboratories into vendor-specific reagent workflows.
- Next-Generation Sequencing:Massively parallel clonal amplification and reversible terminator chemistry enable throughput rates exceeding billions of reads per instrument run. United States academic medical centers anchor installed base expansion as CLIA-certified laboratories scale tumor profiling operations.
- Sanger Sequencing:Chain termination electrophoresis retains stable demand for targeted variant validation and forensic STR analysis where read accuracy exceeds 99.9%. German reference laboratories sustain instrument placements for small-scale genotyping and confirmatory testing.
- Pyrosequencing:Luciferase-based luminescence detection supports bacterial and viral identification in infectious disease surveillance.
- Sequencing by Synthesis:Fluorophore-labeled nucleotide incorporation dominates short-read structural variation detection.
- Solid-State Sequencing:Semiconductor pH detection enables rapid turnaround for targeted gene panels in point-of-care settings.
The dominant share belongs to Next-Generation Sequencing, while Sanger Sequencing retains defensible positioning in validation workflows.
Product Type:
Recurring revenue density varies sharply between capital equipment with multi-year depreciation and consumables with per-run depletion economics.
- Consumables:Proprietary flow cells, library preparation kits, and reagent cartridges generate pull-through revenue tied to instrument utilization rates. United States cancer centers drive highest per-instrument consumables velocity through high-sample-throughput tumor profiling protocols.
- Instruments:Capital placements carry extended sales cycles and service contract attachments that anchor long-term vendor relationships. French academic medical centers concentrate high-throughput system acquisitions into centralized genome center configurations.
- Reagents:Enzyme master mixes and buffer formulations support laboratory-developed test workflows.
- Software:Variant interpretation pipelines and laboratory information system modules enable diagnostic reporting automation.
- Services:Whole-genome sequencing and bioinformatics analysis offerings address capacity constraints at smaller diagnostic laboratories.
Consumables capture the deepest recurring margins, with Services expanding most quickly as outsourcing demand accelerates.
Application:
Clinical validation requirements and reimbursement availability segment addressable value pools across research and diagnostic use cases.
- Clinical Diagnostics:Somatic tumor profiling and hereditary disease screening command premium pricing where FDA-cleared assays support reimbursement claims. United States hospital systems integrate multi-gene panels into standard oncology care pathways.
- Genomic Research:Population-scale sequencing and functional genomics studies drive instrument utilization at genome centers. German Helmholtz institutes anchor high-throughput infrastructure for disease mechanism investigation.
- Agricultural Biotechnology:Marker-assisted breeding and trait identification support crop improvement programs.
- Forensic Analysis:STR profiling and mitochondrial sequencing sustain stable demand from government crime laboratories.
- Evolutionary Biology:Comparative genomics and phylogenetic reconstruction leverage long-read platforms for complex genome assembly.
Clinical Diagnostics holds the revenue concentration, with Genomic Research scaling fastest in absolute instrument placements.
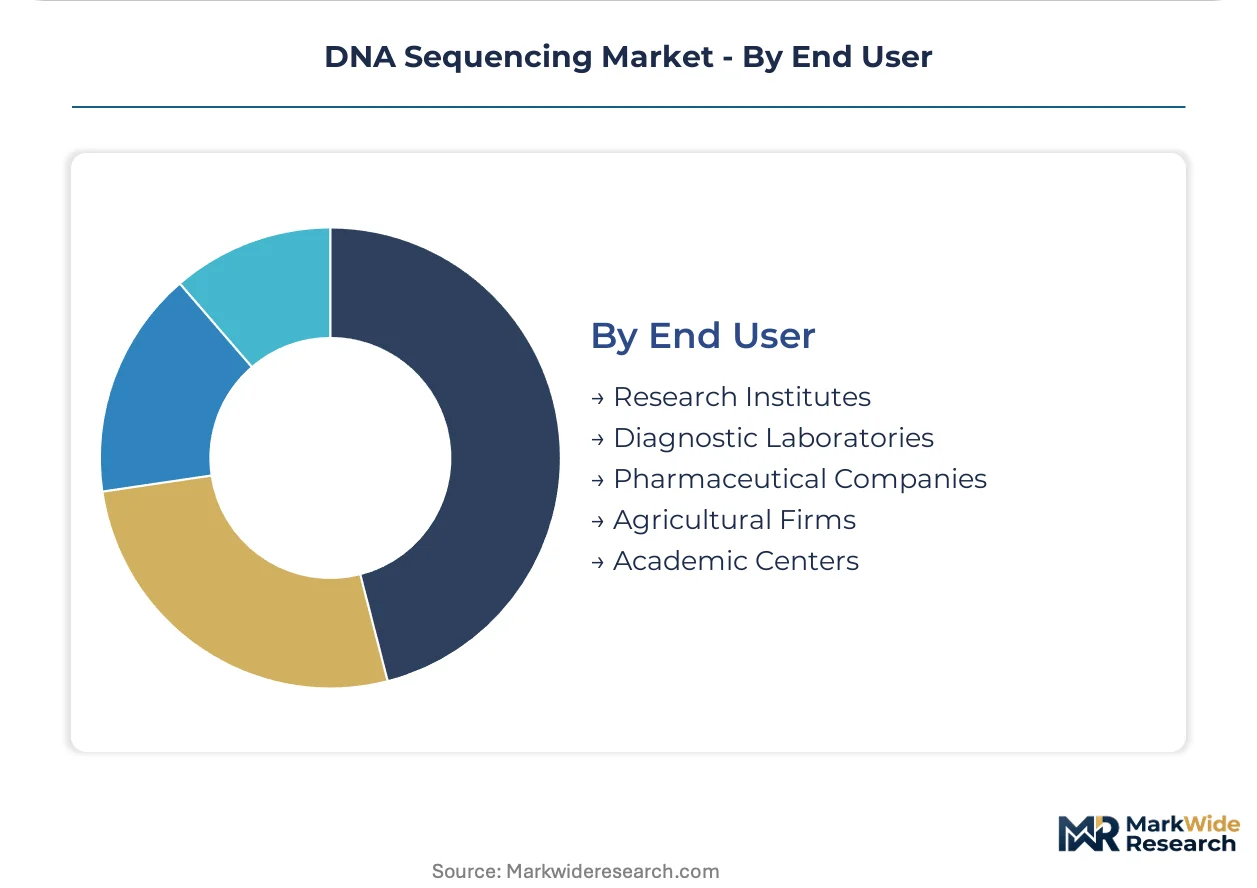
End User:
Procurement sophistication and total-cost-of-ownership modeling intensity vary across institutional categories.
- Diagnostic Laboratories:CLIA-certified facilities with ISO 15189 accreditation drive demand for clinical-validated platforms with diagnostic-grade accuracy specifications. United States reference laboratories concentrate high-throughput infrastructure for regional hospital network servicing.
- Research Institutes:Government-funded genome centers prioritize throughput scalability and open-source bioinformatics compatibility. French national research agencies coordinate instrument procurement through centralized funding mechanisms.
- Academic Centers:University-affiliated medical schools balance research flexibility with emerging clinical translation requirements.
- Pharmaceutical Companies:Companion diagnostic development and biomarker discovery programs anchor targeted sequencing investments.
- Agricultural Firms:Seed companies and livestock breeders deploy genotyping-by-sequencing for trait mapping and parentage verification.
Diagnostic Laboratories command the premium pricing tier, with Academic Centers expanding platform diversity most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate the lowest price elasticity, accepting premium instrument costs for diagnostic-grade accuracy, while Indian district hospitals and Brazilian public laboratories remain acutely sensitive to per-run consumables expenditure.
United States
Academic medical centers in Boston and the Research Triangle anchor high-throughput instrument placements as CLIA-certified laboratories scale tumor profiling operations. The FDA's De Novo pathway for oncology tests accelerates laboratory accreditation requirements across cancer centers. The San Francisco Bay Area concentrates venture-backed sequencing startups developing AI-augmented variant interpretation tools.
Germany
Helmholtz institutes and Max Planck facilities drive population-scale sequencing demand for disease mechanism investigation. The EMA's In Vitro Diagnostic Medical Devices Regulation imposes conformity assessment requirements on clinical laboratories offering sequencing-based diagnostics. Munich and Heidelberg host centralized genome center configurations that distribute compliance overhead across regional hospital networks.
China
National health system expansion in prenatal and oncology screening creates sustained instrument demand at provincial hospitals. The NMPA's guidance on next-generation sequencing-based diagnostic devices shapes premarket notification pathways for domestic manufacturers. Shenzhen and Shanghai concentrate BGI Genomics operations and domestic instrument assembly facilities serving Asia-Pacific markets.
Japan
Pharmacogenomic panel mandates for cardiovascular dosing protocols create regulatory tailwinds for preemptive genotyping investments. The PMDA's guidance on warfarin and clopidogrel genotyping standardizes reimbursement codes for companion diagnostic applications. The Kanto region around Tokyo anchors pharmaceutical company sequencing partnerships for biomarker discovery programs.
India
District hospital infectious disease surveillance drives demand for handheld nanopore devices bypassing centralized laboratory infrastructure. The CDSCO's evolving framework for in vitro diagnostics shapes import registration requirements for sequencing platforms. Bangalore and Hyderabad concentrate bioinformatics service providers addressing variant interpretation capacity constraints.
DNA Sequencing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium long-read specialists coexist with high-throughput short-read incumbents. The vendor base separates into three strategic camps: integrated workflow providers with consumables lock-in, specialized modality developers with structural variant resolution, and emerging point-of-care miniaturization players. Dominant competitive moves include strategic partnerships for bioinformatics integration and geographic expansion through distributor networks in Asia-Pacific markets.
Within the integrated workflow tier, Illumina, Inc. and Thermo Fisher Scientific Inc. exemplify archetypes sustaining recurring revenue density through proprietary reagent cartridges. PacBio occupies a position among long-read specialists where structural variant resolution anchors premium pricing power for complex diagnostic cases.
| Leading Market Players |
|---|
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| PacBio |
| Oxford Nanopore Technologies plc. |
| QIAGEN |
| Agilent Technologies Inc. |
| F. Hoffmann-La Roche Ltd. |
| PerkinElmer Genomics |
| BGI Genomics |
| Others |
Cost & Logistics Intelligence
Enzymatic reagent substitution for legacy dye-terminator chemistries simultaneously concentrates supply geography in United States and German manufacturing clusters while compressing per-run consumables economics for diagnostic laboratories.
Pricing Analysis
Consumables pull-through revenue drives lifetime instrument value, with proprietary flow cell and reagent cartridge lock-in sustaining recurring margin density. Three-tier pricing structure across premium diagnostic-validated, standard research-grade, and economy refurbished instrument levels separates CLIA-certified laboratories from academic genome centers. Pricing pressure stems from hospital procurement committees mandating total-cost-of-ownership transparency over headline instrument costs. Diagnostic laboratories in India and Brazil exhibit acute price sensitivity to per-run reagent expenditure, while Swiss and German buyers accept premium positioning for ISO 15189-compliant accuracy specifications.
Supply Chain Analysis
The United States and Germany anchor high-throughput instrument final assembly, while China and Singapore concentrate semiconductor detection chip fabrication and precision fluidics component manufacturing. Proprietary polymerases, fluorescently labeled nucleotides, and synthetic oligonucleotides constitute critical input dependencies. Single-source vulnerability in specialized enzyme master mix supply creates concentration risk for vendors locked into sole-supplier arrangements. Distribution runs through direct sales forces for major genome center placements and authorized distributor networks for mid-tier diagnostic laboratory penetration across Asia-Pacific markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical reimbursement code expansion for tumor profiling and hereditary screening creates a high-growth disruption trajectory, with the FDA's De Novo pathway acceleration serving as the definitive regulatory inflection reshaping competitive economics.
For Market Incumbents: Secure consumables lock-in through extended reagent supply agreements with CLIA-certified laboratory networks, insulating against nanopore miniaturization threats in infectious disease surveillance. Deepen backward integration into proprietary polymerase manufacturing to defend margin position against generic reagent encroachment in research-grade segments. For New Entrants and Emerging Players: AI-augmented variant interpretation services represent a service-layer gap where incumbents under-serve smaller diagnostic laboratories lacking specialized computational biology talent. Target district hospital networks in India and Brazil with handheld nanopore deployments bypassing centralized infrastructure requirements. Pursue pharmacogenomic panel partnerships with cardiovascular protocol committees as the most penetrable clinical entry point. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed bioinformatics platform specialists possessing ISO 27001 certification and hospital EHR integration capabilities. Long-term viability over the extended investment horizon hinges on reimbursement code breadth for whole-genome sequencing applications. Monitor payer coverage determination velocity for neonatal and oncology settings as the critical inflection signal distinguishing scalable service models from stranded capacity.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Accreditation Expansion | FDA De Novo pathway acceleration pulls high-throughput instrument demand across United States cancer centers. |
| AI-Augmented Variant Interpretation Development | Machine learning integration compresses reporting turnaround times for competing service laboratory differentiation. |
| Long-Read Platform Diversification | PacBio and Oxford Nanopore deployments alongside Illumina infrastructure expand clinically actionable variant yield. |
| Pharmacogenomic Panel Regulatory Alignment | PMDA guidance on warfarin and clopidogrel dosing standardizes reimbursement codes in Japanese cardiovascular protocols. |
| Point-of-Care Miniaturization Partnership | Handheld nanopore distribution agreements with Indian district hospitals bypass centralized laboratory infrastructure constraints. |
Research Approach
A spread of perspectives from clinical laboratory directors, bioinformatics pipeline architects, hospital procurement committee members, and regulatory affairs specialists converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation from FDA 510(k) and De Novo submission databases, EMA In Vitro Diagnostic Medical Devices Regulation technical documentation, and CLIA certification records. Bottom-up instrument placement and consumables velocity estimates triangulated against top-down market size reconstruction across technology modality and end-user segments.
Segmentation dimensions modeled include technology platform, product type mix, clinical versus research application tier, and end-user institutional category across the projection horizon. CAGRs derive from instrument installed base expansion rates, per-system consumables pull-through trajectories, and reimbursement code adoption curves. Forecast inputs incorporate CLIA laboratory certification timelines, ISO 15189 accreditation velocity, and payer coverage determination patterns for multi-gene panel tests.
Forecasts assume regulatory continuity in FDA De Novo and EMA MDR regimes; material policy shifts in sequencing-based diagnostic device classification would require re-modeling. Variant interpretation pipeline standardization and pharmacogenomic mandate expansion constitute specific risk factors with capacity to revise trajectory assumptions. Recalibration cycles align with material shifts in reimbursement code breadth and laboratory accreditation velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Global Whole Genome Sequencing (WGS) Market
Genomics
Short-Read Sequencing Market
Genomics
DNA Diagnostics Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Pre-Pregnancy Genetic Testing Market
Genomics
Mitochondrial DNA Market
Genomics
Alagille Syndrome Market
Genomics
DNA Sequencing Services Market
Genomics
Europe Whole Exome Sequencing Market
Genomics
Whole Exome Sequencing (WES) Market
Genomics
Apolipoprotein Test Market
Genomics
UAE Genetic Testing Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Global Blockchain in Genomic Data Management Market
Genomics
Global Microarray Analysis Market