
 Genetic Testing Service Market | 2026-2036
Genetic Testing Service Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Testing Service Market Analysis
Modular test panel bundling is consolidating around comprehensive hereditary risk profiles that combine cancer, cardiac, and pharmacogenomic markers into single workflows. Illumina, Inc. leverages sequencing platform scale to anchor clinical laboratory partnerships across North America. Thermo Fisher Scientific Inc. competes through integrated sample-to-answer systems that span extraction, amplification, and analysis. Quest Diagnostics Incorporated controls one of the largest commercial testing footprints, sustaining volume advantages in employer and payer contracts.
Genetic testing service denotes laboratory analysis of DNA, RNA, chromosomes, or proteins to detect heritable mutations, carrier status, or disease susceptibility, typically requiring extraction from blood, saliva, or tissue followed by PCR, sequencing, or microarray interrogation. Cancer risk assessment commands premium positioning due to reimbursement density and clinical actionability, while pharmacogenomics represents the fastest-growing application as health systems embed drug-gene interaction data into electronic prescribing. Consumer-facing ancestry and wellness segments occupy lower-margin, higher-churn positions that depend on marketing efficiency rather than clinical validation.
The FDA regulates in vitro diagnostic and laboratory-developed test quality, while the Centers for Medicare & Medicaid Services governs reimbursement through CLIA laboratory certification requirements. HIPAA privacy frameworks shape how genetic data flows between testing laboratories, physicians, and third-party platforms. Stakeholders must monitor whether Congress advances premarket review requirements for high-risk genetic tests, as this would reshape competitive barriers and capital requirements for new entrants.
Market Dynamics
Platform consolidation around next-generation sequencing infrastructure is compressing per-test economics while elevating CLIA laboratory certification requirements as the decisive competitive gate. This dual pressure favors scaled operators with captive sample volumes and integrated bioinformatics pipelines.
Growth Catalysts
- Hereditary cancer screening expansion:Oncology clinics in the United States are embedding BRCA and Lynch syndrome panels into standard-of-care protocols, creating recurring test demand tied to treatment pathways.
- Pharmacogenomic integration:Health systems are embedding drug-gene interaction data into electronic prescribing workflows, with the FDA guiding clinical utility validation for warfarin and clopidogrel metabolism markers.
- Direct-to-consumer channel maturation:Saliva-based collection kits are penetrating wellness segments through employer benefit programs and telemedicine platforms.
Market Restraints
- Reimbursement density concentration:Medicare and commercial payer coverage decisions in the United States determine addressable volume, with non-covered tests relegating services to cash-pay segments with higher patient abandonment.
- Sequencing reagent supply concentration:Critical consumables for Illumina platforms originate from concentrated chemical synthesis suppliers, exposing laboratories to input cost volatility and allocation constraints during supply shocks.
- Variant interpretation bottleneck:The American College of Medical Genetics and Genomics maintains evolving standards for variant classification, requiring perpetual curation investment that smaller laboratories cannot sustain.
Strategic Opportunities
- Rare disease diagnostic gaps:Undiagnosed patient populations in India present expansion potential for exome sequencing services, with the country's national pharmaceutical regulator streamlining import pathways for reference materials.
- Polygenic risk score commercialization:Cardiovascular and diabetes susceptibility algorithms are converging with lifestyle intervention programs, creating subscription-based revenue models beyond single-test transactions.
- Liquid biopsy adjacency:Cell-free DNA analysis for minimal residual disease monitoring is expanding oncology service menus, with the FDA's breakthrough device designation pathway accelerating clinical adoption timelines.
Industry Challenges
- Bioinformatics talent scarcity:Variant curation and pipeline development require dual expertise in computational biology and clinical genetics, with academic training programs failing to match commercial laboratory hiring velocity.
- HIPAA compliance architecture:Genetic data flows between testing platforms, physician portals, and third-party analytics vendors demand encrypted infrastructure investments that strain mid-scale operator capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Testing Service Market |
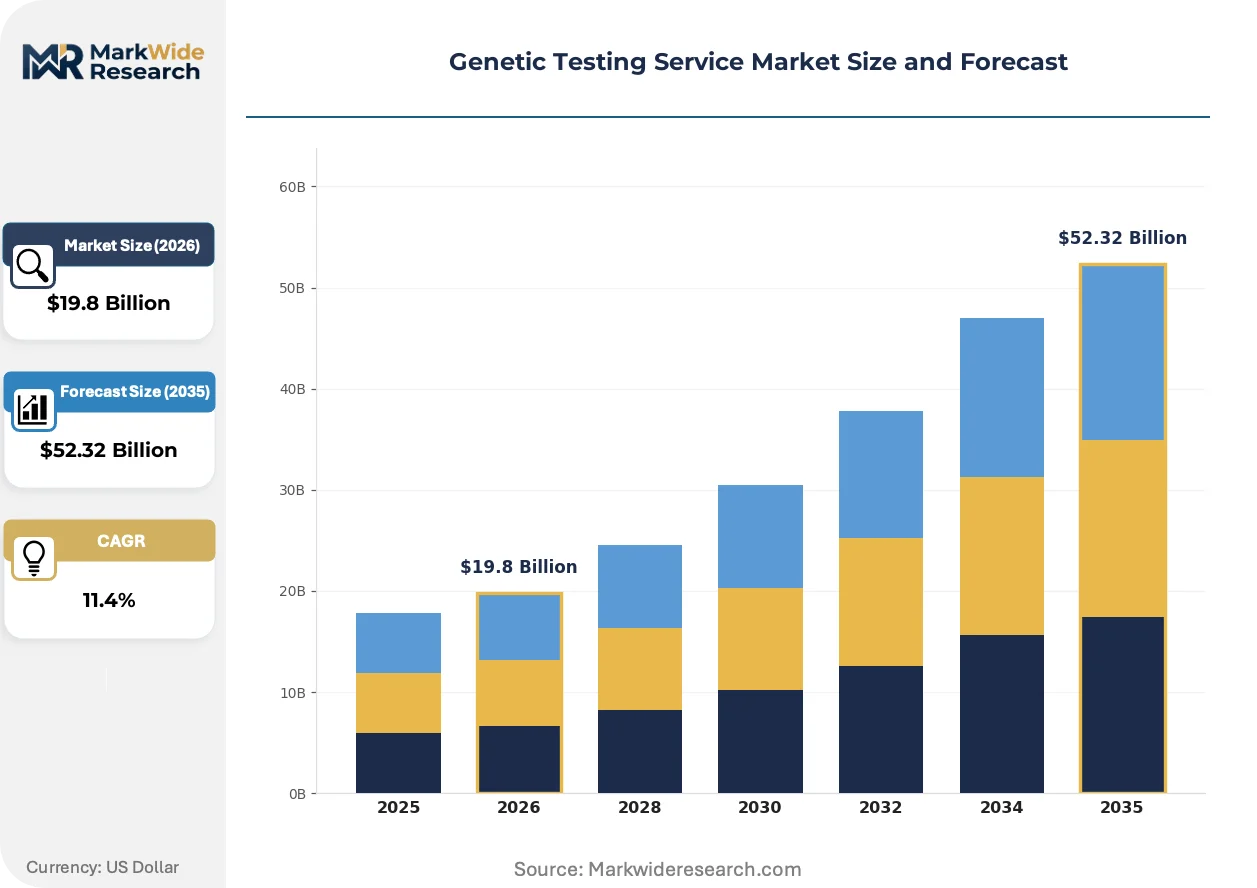
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $52.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Carrier Screening, Preimplantation Genetic Diagnosis, Ancestry Testing, Cancer Risk Assessment Application: Personalized Medicine, Prenatal Testing, Pharmacogenomics, Disease Prevention Sample Type: Blood, Saliva, Buccal Swab, Tissue Client Type: Consumers, Healthcare Providers, Research Institutions, Pharmaceutical Companies |
| Companies Covered | Hoffmann-La Roche Ltd., Illumina, Inc., Thermo Fisher Scientific Inc., QIAGEN, Danaher Corporation, Quest Diagnostics Incorporated, Myriad Genetics, Inc., Abbott Laboratories, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Testing Service Market Emerging Trajectories
Long-read sequencing platforms are disrupting variant detection accuracy standards while regulatory frameworks tighten premarket validation requirements for high-risk hereditary tests. These simultaneous pressures are reshaping competitive positioning around clinical evidence depth rather than marketing reach alone.
Third-generation sequencing technology is expanding into structural variant detection and methylation analysis, capabilities that short-read platforms cannot replicate. Academic medical centers in the United States are adopting Pacific Biosciences and Oxford Nanopore systems for undiagnosed disease programs. This capability expansion is compressing the diagnostic odyssey timeline for rare disease patients while fragmenting platform standardization across the clinical laboratory network.
The European Union's In Vitro Diagnostic Medical Devices Regulation is mandating notified body conformity assessments for hereditary cancer risk tests previously governed by self-certification. Commercial laboratories serving EU member states must now compile clinical performance studies and quality management documentation. High-risk genetic test categories face the steepest compliance burden, with German and French regulators interpreting clinical evidence requirements most stringently.
Employer-sponsored genetic benefits are displacing direct-to-consumer marketing as the primary patient acquisition channel. Large self-insured employers in the United States are contracting with laboratory networks to offer pharmacogenomic and carrier screening as preventive benefits. This channel migration concentrates volume with laboratories possessing health plan credentialing infrastructure and medical management integration capabilities.
Genetic Testing Service Market Segmentation
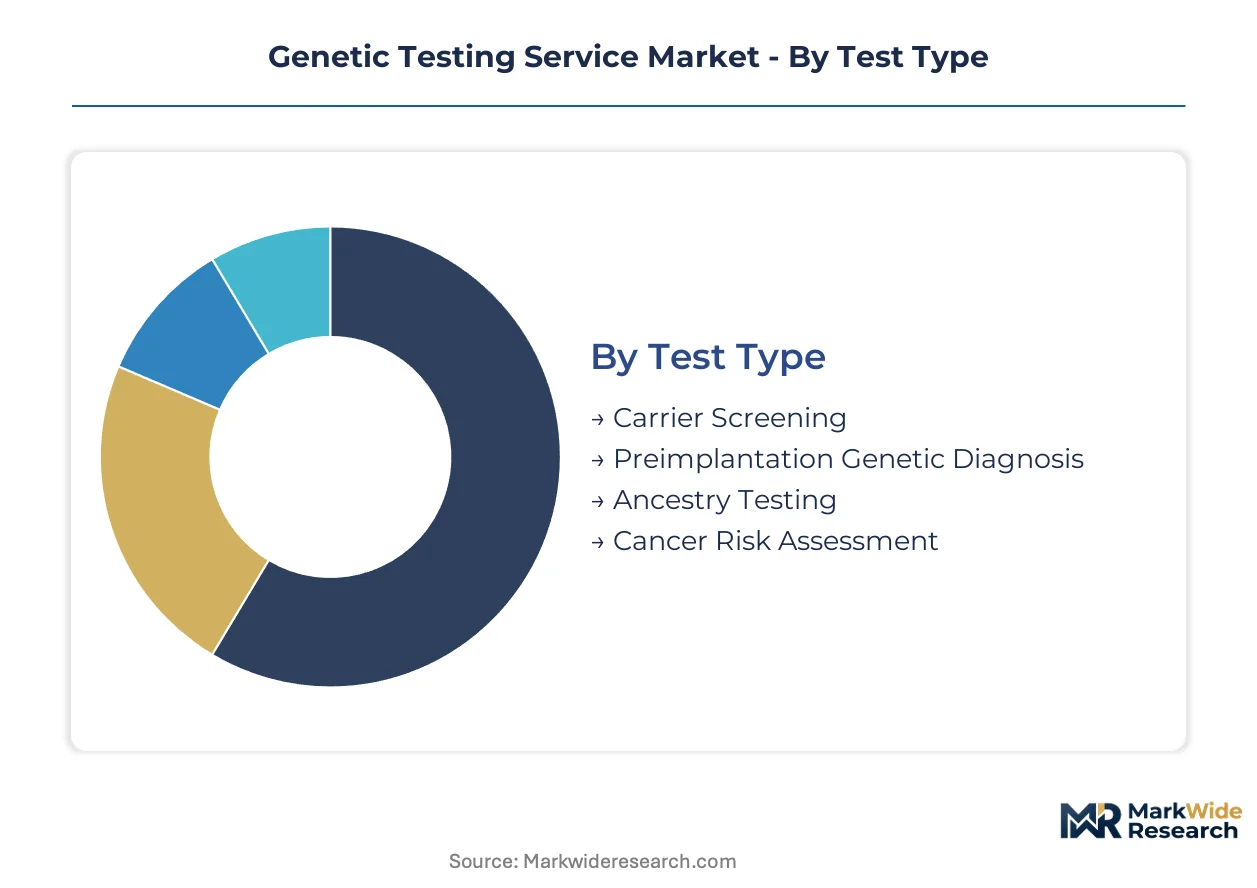
Genetic testing services fragment across multiple dimensions that determine reimbursement pathways, regulatory scrutiny, and operational infrastructure requirements. Test type and application define clinical utility standards, while sample type and client type shape logistics and commercial strategy.
Test Type:
Volume concentration sits with ancestry and wellness screening, while premium economics attach to clinical diagnostic categories with established reimbursement codes.
- Cancer Risk Assessment:BRCA and Lynch syndrome panels require CLIA-certified laboratory infrastructure and genetic counselor interpretation protocols. Oncology clinics in the United States concentrate demand through hereditary screening programs embedded in treatment pathways, with Medicare coverage decisions determining addressable volume.
- Carrier Screening:Expanded panels covering cystic fibrosis, spinal muscular atrophy, and hemoglobinopathies utilize next-generation sequencing of target gene regions. Reproductive endocrinology practices and preconception counseling programs drive demand, with employer-sponsored benefits expanding access beyond fertility clinic settings.
- Preimplantation Genetic Diagnosis:Embryo biopsy and chromosomal screening services attach to in vitro fertilization cycles. Fertility clinic partnerships determine market access, with regulatory variation across state laboratory licensing frameworks affecting operational footprint.
- Ancestry Testing:Single nucleotide polymorphism arrays and mitochondrial DNA analysis serve genealogical and ethnic origin questions. Direct-to-consumer marketing efficiency and database network effects determine competitive position, with lower margins and higher customer acquisition costs than clinical segments.
Mature deployment sits with ancestry testing. Newer deployment is concentrated in cancer risk assessment.
Application:
Clinical integration depth separates segments with embedded electronic health record workflows from those requiring standalone patient education and consent processes.
- Pharmacogenomics:Drug-gene interaction testing for warfarin, clopidogrel, and psychiatric medication metabolism requires clinical decision support integration. Health systems embedding pharmacogenomic data into electronic prescribing workflows represent the steepest expansion trajectory, with the FDA guiding validation requirements for specific drug-gene pairs.
- Personalized Medicine:Tumor profiling and therapy selection testing matches oncologic treatments to molecular biomarkers. Academic medical centers and community oncology networks concentrate demand, with tissue acquisition logistics and turnaround time requirements shaping laboratory competitive position.
- Prenatal Testing:Cell-free DNA screening for fetal aneuploidy and single-gene conditions operates through maternal blood draw. Maternal-fetal medicine specialists and obstetric practices drive volume, with non-invasive methodology displacing invasive diagnostic procedures for initial risk assessment.
- Disease Prevention:Polygenic risk scores for cardiovascular and diabetes susceptibility combine with lifestyle intervention programs. Wellness platforms and employer benefit administrators are testing subscription revenue models beyond single-test transactions.
Established clinical utility sits with prenatal testing. Emerging clinical evidence generation is concentrated in disease prevention applications.
Sample Type:
Collection logistics and stability requirements separate centralized laboratory processing from point-of-care or home-based collection models.
- Blood:Venous draw yields high DNA quantity and quality for complex sequencing applications. Hospital and clinic-based phlebotomy infrastructure supports oncology and rare disease testing with demanding analytical requirements.
- Saliva:Self-collection kits enable direct-to-consumer distribution and telemedicine-integrated workflows. Collection tube stabilization chemistry and shipping logistics determine laboratory operational radius.
- Buccal Swab:Non-invasive collection suits pediatric and elderly populations with compliance limitations. Lower DNA yield restricts application to targeted PCR and array-based testing.
- Tissue:Formalin-fixed paraffin-embedded samples and fresh biopsies support oncology molecular profiling. Pathology laboratory partnerships and sample preparation protocols determine testing access.
Standard clinical practice sits with blood collection. Convenience-driven expansion is concentrated in saliva-based workflows.
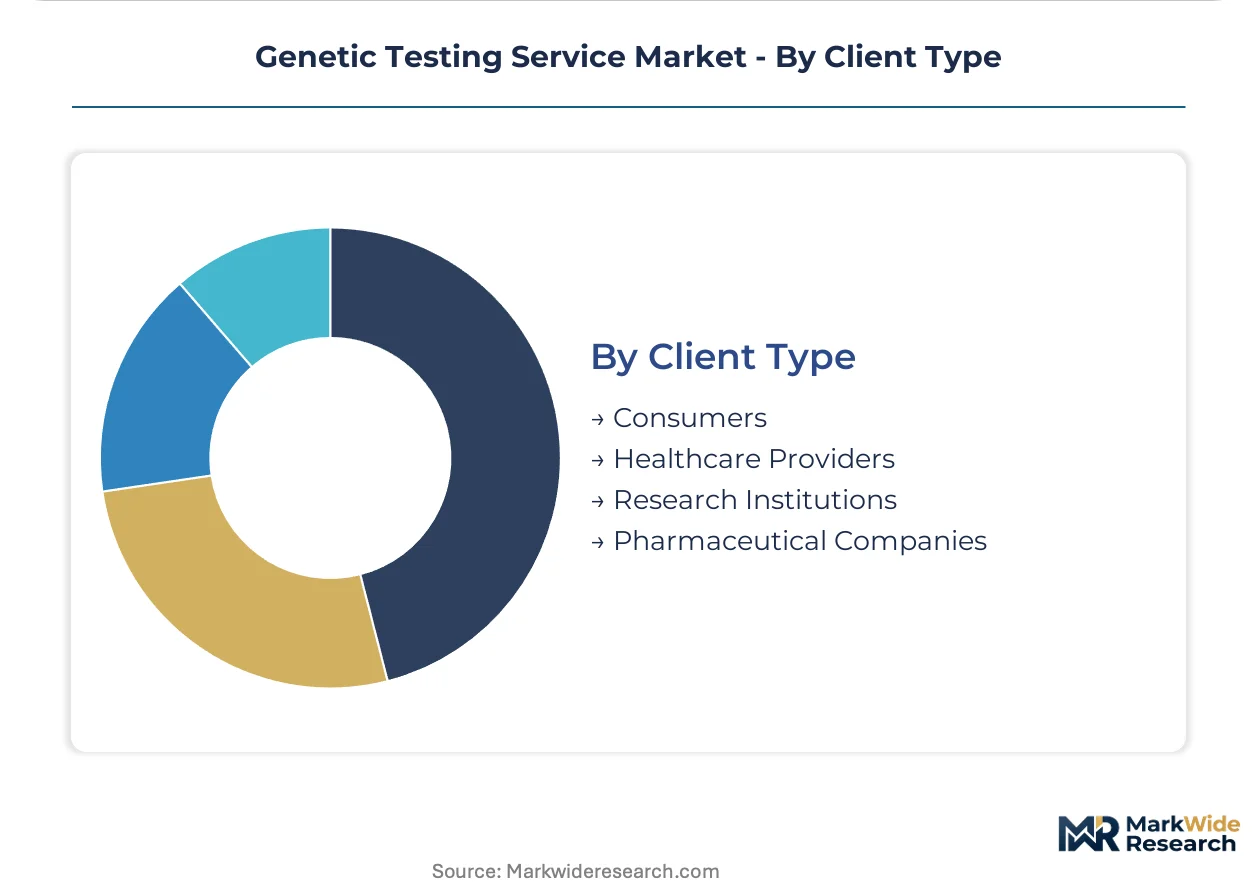
Client Type:
Purchasing sophistication and reimbursement negotiation leverage separate institutional buyers from individual decision-makers.
- Healthcare Providers:Hospital systems and physician practices contract for testing services through group purchasing organizations and integrated delivery network agreements. Volume commitments and electronic health record integration requirements favor scaled laboratory operators.
- Pharmaceutical Companies:Companion diagnostic development and clinical trial patient stratification drive demand for validated biomarker assays. Regulatory submission support and analytical validation documentation determine vendor selection criteria.
- Research Institutions:Academic laboratories utilize sequencing services for grant-funded investigations with distinct procurement and intellectual property frameworks.
- Consumers:Individual purchasers through direct-to-consumer channels or employer-sponsored benefit programs exhibit price sensitivity and limited clinical interpretation support expectations.
Contracting sophistication sits with healthcare providers. Volume growth is concentrated in pharmaceutical company partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in the United States and Germany, while consumption growth concentrates in India and China where diagnostic infrastructure expands faster than domestic laboratory buildout.
United States
Oncology clinics embed hereditary cancer screening into treatment protocols, generating recurring BRCA and Lynch syndrome test demand. The FDA tightens premarket review requirements for high-risk laboratory-developed tests, elevating compliance costs. Boston and San Francisco biotech corridors anchor sequencing platform development and clinical laboratory partnerships.
Germany
Academic medical centers adopt long-read sequencing for undiagnosed rare disease programs, compressing diagnostic timelines. The EU In Vitro Diagnostic Medical Devices Regulation mandates notified body conformity assessments for hereditary cancer risk tests. Berlin and Munich laboratory networks consolidate under health system contracting pressures.
China
Domestic pharmaceutical companies contract for companion diagnostic development and clinical trial patient stratification. The National Medical Products Administration streamlines import pathways for sequencing reference materials. Shanghai and Beijing clusters concentrate exome sequencing capacity serving undiagnosed patient populations.
India
Reproductive endocrinology practices drive expanded carrier screening panels for cystic fibrosis and spinal muscular atrophy. The Central Drugs Standard Control Organization accelerates reference material import approvals for rare disease diagnostics. Hyderabad and Bangalore laboratory networks scale to serve employer-sponsored genetic benefit programs.
United Kingdom
National Health Service genomic medicine service embeds pharmacogenomic data into electronic prescribing workflows. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR transition timelines for hereditary test categories. London and Cambridge academic hospital networks pilot polygenic risk score integration with lifestyle intervention programs.
Genetic Testing Service Market Vendor Landscape
The competitive structure tilts toward sequencing platform manufacturers with captive clinical laboratory partnerships. Three tiers emerge: integrated diagnostics conglomerates controlling sample-to-answer workflows, specialized genetic testing laboratories with health plan credentialing depth, and platform-agnostic service providers competing on turnaround time. Dominant competitive moves include strategic partnerships anchoring hospital system electronic health record integration and portfolio diversification into liquid biopsy adjacencies.
Among Switzerland-based pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd. exemplifies the integrated diagnostics archetype spanning platform instrumentation and clinical service delivery. California-based Illumina, Inc. and Massachusetts-based Thermo Fisher Scientific Inc. occupy positions as sequencing infrastructure anchors, with the former leveraging platform scale and the latter competing through integrated extraction-to-analysis systems. These three represent the capital-intensive tier where CLIA laboratory certification and bioinformatics pipeline investment create decisive competitive gates.
| Leading Market Players |
|---|
| Hoffmann-La Roche Ltd. |
| Illumina, Inc. |
| Thermo Fisher Scientific Inc. |
| QIAGEN |
| Danaher Corporation |
| Quest Diagnostics Incorporated |
| Myriad Genetics, Inc. |
| Abbott Laboratories |
| Bio-Rad Laboratories, Inc. |
| Others |
Supply Flow & Price Mechanics
Large self-insured employers and integrated delivery networks command contract-based pricing leverage through multi-year volume commitments, anchoring a tiered model where CLIA-certified laboratories extract premium rates for hereditary cancer panels while direct-to-consumer ancestry services compete on marketing efficiency alone.
Pricing Analysis
Cost-down pressure on clinical diagnostic tiers accelerates because Medicare coverage determinations and commercial payer prior authorization requirements compress reimbursable rates for BRCA and Lynch syndrome panels. Pricing stratifies across FDA-cleared companion diagnostics, laboratory-developed tests with health plan credentialing, and cash-pay wellness screening with minimal clinical validation. Brand premium and CLIA laboratory certification level separate incumbent operators from emerging entrants. Direct-to-consumer segments exhibit highest price sensitivity; oncology clinics with embedded genetic counselors demonstrate lowest.
Supply Chain Analysis
Cross-border shipping of temperature-controlled saliva collection kits and sequencing reagents adds logistics cost volatility that laboratories must absorb or pass through. Critical consumables for next-generation sequencing platforms originate from concentrated chemical synthesis suppliers in the United States, Germany, and China. Reagent supply draws from Illumina's proprietary flow cell chemistry and third-party oligonucleotide manufacturers. Single-source vulnerability in sequencing instrument ecosystems exposes laboratories to allocation constraints during supply shocks. Distribution runs through CLIA-certified laboratory networks, hospital system electronic health record integrations, and direct-to-consumer e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
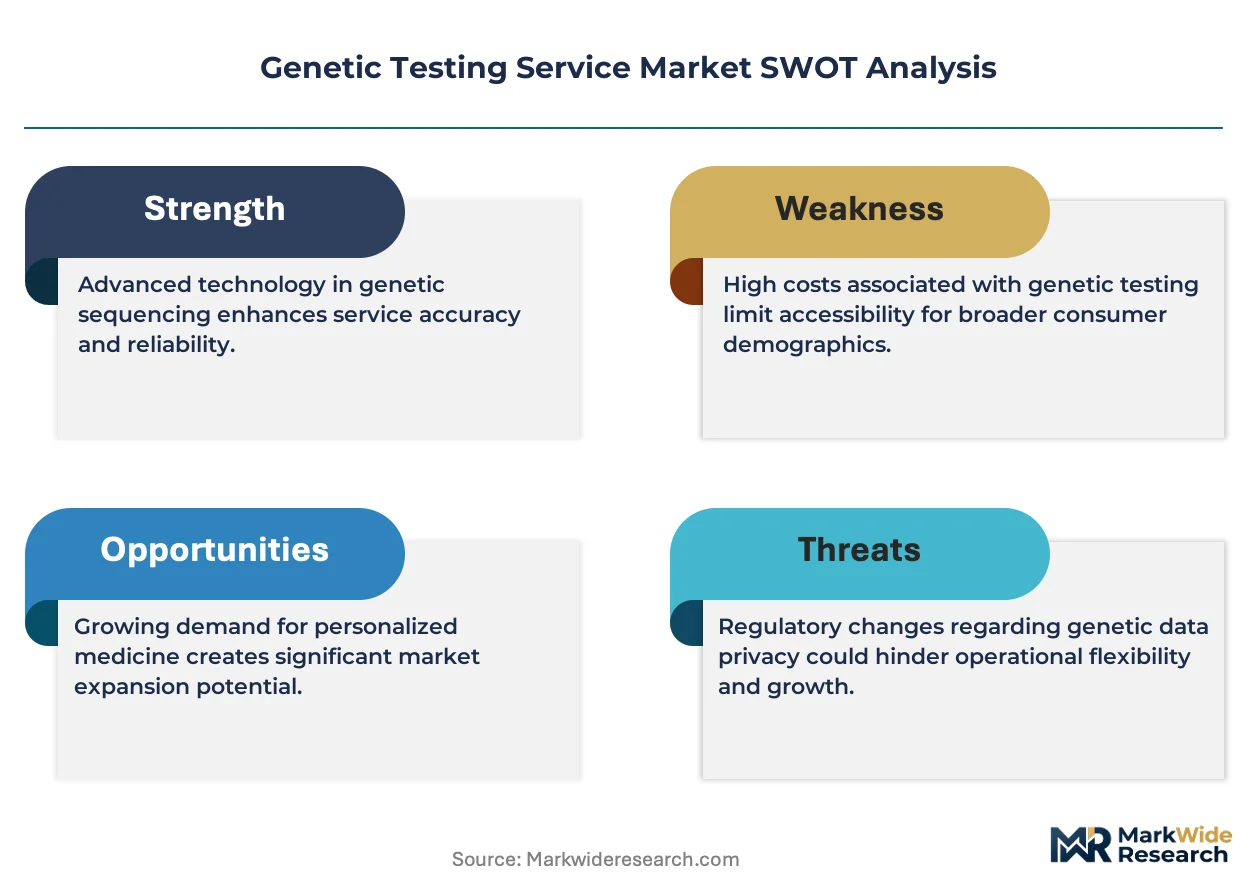
The FDA's tightening premarket review requirements for high-risk laboratory-developed tests erect a cost-of-compliance barrier that favors scaled incumbents with dedicated regulatory affairs infrastructure and punishes undercapitalized entrants.
For Market Incumbents: Anticipate reimbursement compression in hereditary cancer screening by deepening health plan credentialing infrastructure and securing exclusive electronic health record integration contracts with oncology clinic networks. Consolidate bioinformatics pipelines through strategic partnerships with academic medical centers to deflect variant interpretation cost inflation. Vertical integration into liquid biopsy sample processing offers margin defense against pure-play competitors. For New Entrants and Emerging Players: Telemedicine-integrated pharmacogenomic testing represents the most penetrable white-space channel, bypassing capital-intensive CLIA laboratory buildout through reference laboratory partnerships. Target employer-sponsored benefit administrators with subscription-based polygenic risk score offerings that bundle lifestyle intervention coaching. White-label partnerships with fertility clinics for expanded carrier screening panels offer faster revenue traction than direct-to-consumer marketing. For Investors and Strategic Acquirers: The window for entry favors CLIA-certified laboratories with established health plan contracts and proprietary variant databases that shorten diagnostic odyssey timelines. Mid-scale operators with oncology clinic network density and FDA breakthrough device designation experience represent priority acquisition profiles. Watch FDA premarket review requirement expansion for high-risk hereditary tests as the inflection signal for competitive consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Expansion | Extends testing capacity into new state jurisdictions under unified quality management systems. |
| Electronic Health Record Integration Partnership | Embeds pharmacogenomic decision support into Epic and Cerner workflows at academic medical centers. |
| Liquid Biopsy Adjacency Development | Captures minimal residual disease monitoring demand through cell-free DNA analysis capabilities. |
| Polygenic Risk Score Commercialization | Converts single-test transactions into recurring subscription revenue with lifestyle intervention platforms. |
| Long-Read Sequencing Platform Adoption | Differentiates structural variant detection accuracy for undiagnosed rare disease programs. |
Methodological Framework
Multi-period observation of Medicare coverage determination timelines, FDA premarket submission volumes, and health system pharmacogenomic implementation rates anchored the trend analysis, supplemented by interviews with laboratory directors, genetic counselors, health plan medical policy leads, and reproductive endocrinology practice administrators. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare claims data, Clinical Laboratory Improvement Amendments certification records, and American College of Medical Genetics and Genomics guideline updates. Bottom-up test volume modeling and top-down market sizing triangulated across direct-to-consumer shipment data and clinical laboratory revenue disclosures.
Segment-weighting approaches applied differential growth assumptions across cancer risk assessment, pharmacogenomics, and ancestry testing categories, with test type, application, sample type, and client type dimensions informing volume allocation. CAGRs were derived from regression analysis of historical reimbursement rate trajectories and platform cost curves across the projection horizon. Forecast inputs incorporated health system electronic prescribing adoption curves and employer benefit administrator contracting velocity.
Inputs from Medicare coverage determination databases and FDA submission tracking systems were available through the study window; gaps in direct-to-consumer channel unit economics introduce uncertainty bands around ancestry and wellness segment projections. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Next Generation Genomics Market
Genomics
China Genetic Testing Market
Genomics
Digital Genome Market
Genomics
Spatial OMICS Market
Genomics
Global Nucleic Acid Labeling Market
Genomics
Prenatal Genetic Testing Market
Genomics
Global Hereditary Cancer Testing Market
Genomics
Genomics Personalized Health Market
Genomics
North America Genetic Testing Market
Genomics
Global Mirna Sequencing and Assay Market
Genomics
Pharmacogenomics Technology Market
Genomics
Cancer-Focused Genetic Testing Services Market
Genomics
North America Epigenetics Market
Genomics
Spatial Genomics and Transcriptomics Market
Genomics
Global Single Nucleotide Polymorphism (SNP) Genotyping Market
Genomics
Kearns-Sayre Syndrome Market