
 Antisense Oligonucleotides Market | 2026-2036
Antisense Oligonucleotides Market Size, Share, and Industry Trends Forecast 2026-2036
Antisense Oligonucleotides Market Analysis
CE marking under the EU Medical Device Regulation is rotating toward a decisive gatekeeping function for European market access in oligonucleotide-based therapeutics. Ionis Pharmaceuticals leverages its integrated drug discovery engine to sustain one of the industry's deepest clinical pipelines. Biogen anchors its position through commercial infrastructure built around spinal muscular atrophy and broader neurology franchises. Sarepta Therapeutics differentiates via muscular dystrophy specialization and patient advocacy integration that controls prescriber relationships.
Antisense oligonucleotides are synthetic, single-stranded DNA or RNA polymers, typically 13–25 nucleotides in length, engineered to bind complementary mRNA targets through Watson-Crick base pairing and modulate protein expression via RNase H-mediated degradation or steric hindrance of translation; they are manufactured through solid-phase phosphoramidite synthesis with phosphorothioate backbone modifications to enhance nuclease stability and pharmacokinetic half-life. Phosphorothioate oligonucleotides occupy the dominant share of approved products due to established manufacturing scalability and regulatory familiarity. Locked nucleic acids represent the fastest-advancing chemistry class as developers seek improved binding affinity and reduced off-target effects in CNS indications. Intravenous delivery mode leads current revenue pools, though subcutaneous administration is gaining structural importance for chronic dosing regimens in genetic disorders.
FDA, EMA, and the Pharmaceuticals and Medical Devices Agency of Japan collectively shape development pathways through divergent evidentiary standards for accelerated and conditional approvals. The FDA's orphan drug exclusivity provisions and breakthrough therapy designation directly influence corporate prioritization of rare disease targets over broader indications. Stakeholders must monitor evolving payer evidence requirements for gene-silencing therapies, as health technology assessment bodies tighten cost-effectiveness thresholds for single-target mechanisms without curative claims.
Market Dynamics
FDA accelerated approval pathways and EMA conditional marketing authorization frameworks compress development timelines for novel modalities. Neurology clinics and specialized treatment centers represent the fastest-expanding buyer segment as patient access broadens.
Growth Catalysts
- FDA Orphan Drug Exclusivity:Rare disease incentives attract pipeline investment toward spinal muscular atrophy and Duchenne muscular dystrophy targets.
- Phosphorothioate Manufacturing Scale:Solid-phase phosphoramidite synthesis with backbone modifications enables production economies for chronic dosing regimens.
- Neurology Clinic Expansion:Specialized treatment centers in the United States broaden patient access and prescriber familiarity with antisense mechanisms.
Market Restraints
- Phosphoramidite Raw Material Concentration:Supply of modified nucleoside phosphoramidites concentrates among a limited supplier base in North America and Europe.
- EMA Health Technology Assessment Friction:Cost-effectiveness thresholds for single-target mechanisms without curative claims tighten reimbursement negotiations in Germany and France.
- Locked Nucleic Acid Manufacturing Complexity:Synthetic chemistry requirements for 2'-O,4'-C-methylene bridges limit batch yields and extend lead times.
Strategic Opportunities
- Japan PMDA Sakigake Designation:Priority review frameworks for innovative oligonucleotide therapeutics open accelerated market entry for CNS-targeted candidates.
- Subcutaneous Administration Shift:Chronic genetic disorder patients demand home-based delivery modes, displacing hospital-dependent intravenous infusion.
- Cardiometabolic Expansion:Apolipoprotein and angiopoietin-like protein targets represent untapped application areas beyond established neurology franchises.
Industry Challenges
- RNase H Pharmacology Talent Scarcity:Mechanistic understanding of tissue-specific cleavage kinetics requires specialized expertise concentrated at a handful of academic centers.
- CE Marking MDR Transition:EU Medical Device Regulation reclassification of companion diagnostic devices extends certification timelines for oligonucleotide-drug combinations.
- Cold Chain Distribution Complexity:Temperature-sensitive finished products require reconfigured logistics networks for direct-to-patient delivery models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antisense Oligonucleotides Market |
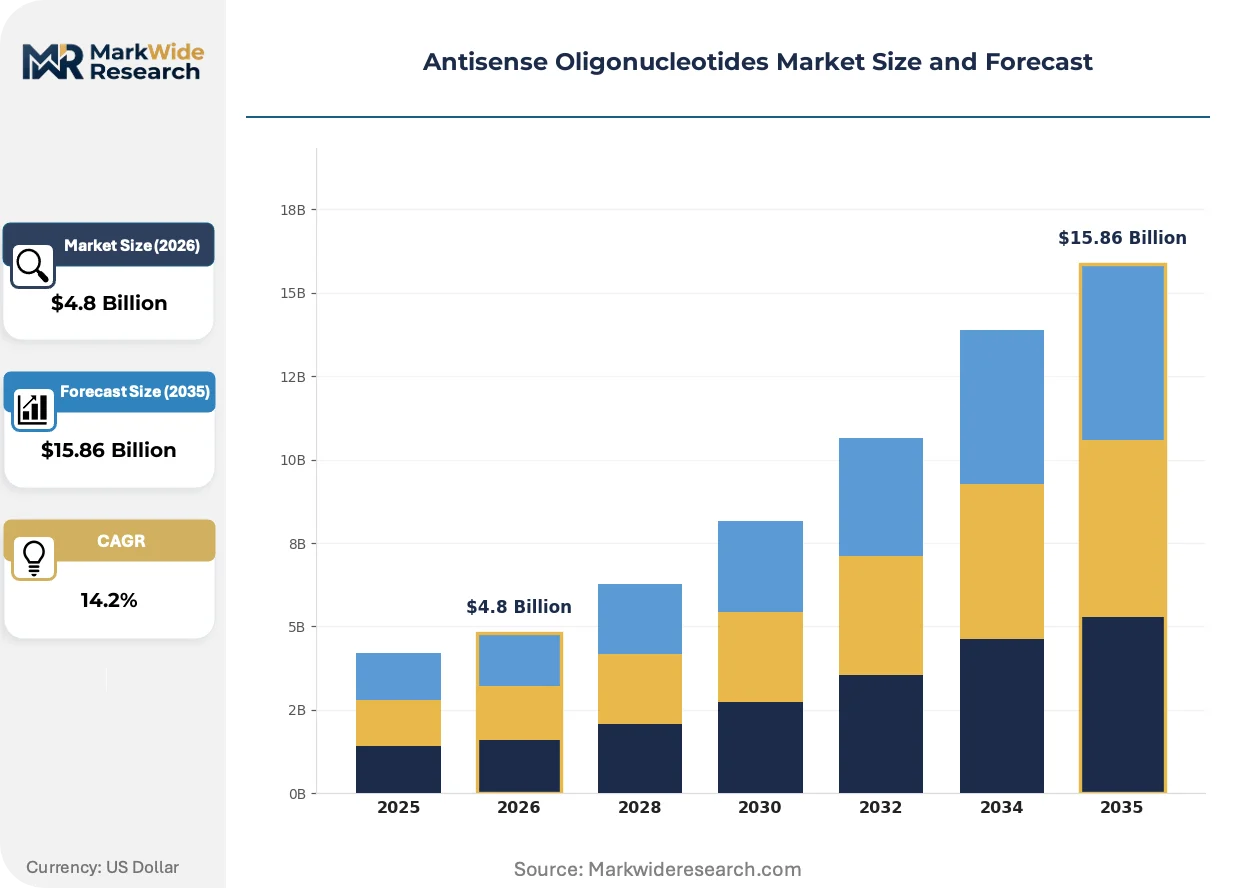
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2'-O-Methyl Oligonucleotides, Phosphorothioate Oligonucleotides, Locked Nucleic Acids, Peptide Nucleic Acids Therapy Area: Cancer, Cardiovascular Disorders, Genetic Disorders, Infectious Diseases Delivery Mode: Intravenous, Subcutaneous, Oral, Intramuscular End User: Pharmaceutical Companies, Research Institutions, Contract Manufacturing Organizations, Hospitals |
| Companies Covered | Ionis Pharmaceuticals, Biogen, Sarepta Therapeutics, Alnylam Pharmaceuticals, Wave Life Sciences, AstraZeneca, Novartis, Regulus Therapeutics, Antisense Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antisense Oligonucleotides Market Emerging Trajectories
Antisense chemistry platforms are diverging between established backbone modifications and next-generation constrained nucleic acids. This divergence reshapes competitive positioning across CNS and peripheral indications.
Phosphorothioate oligonucleotide chemistry is bifurcating the market between high-volume chronic disease applications and precision neurology targets. Biogen and Sarepta Therapeutics anchor the neurology segment with spinal muscular atrophy and muscular dystrophy franchises. The technology is enabling chronic dosing regimens while compressing development timelines for rare disease candidates through regulatory familiarity.
EMA conditional marketing authorization frameworks are tightening evidentiary standards for surrogate endpoints in genetic disorders. Manufacturers must now generate confirmatory clinical data post-authorization to maintain European market access. Neurology indications face the steepest compliance burden as health technology assessment bodies in Germany and France demand mortality or functional outcome data.
Specialized treatment centers are consolidating prescriber relationships and patient access pathways. Neurology clinics in the United States now control formulary placement for antisense therapies through integrated care models. This concentration shifts commercial strategy toward direct physician engagement and away from traditional hospital pharmacy distribution.
Antisense Oligonucleotides Market Segmentation
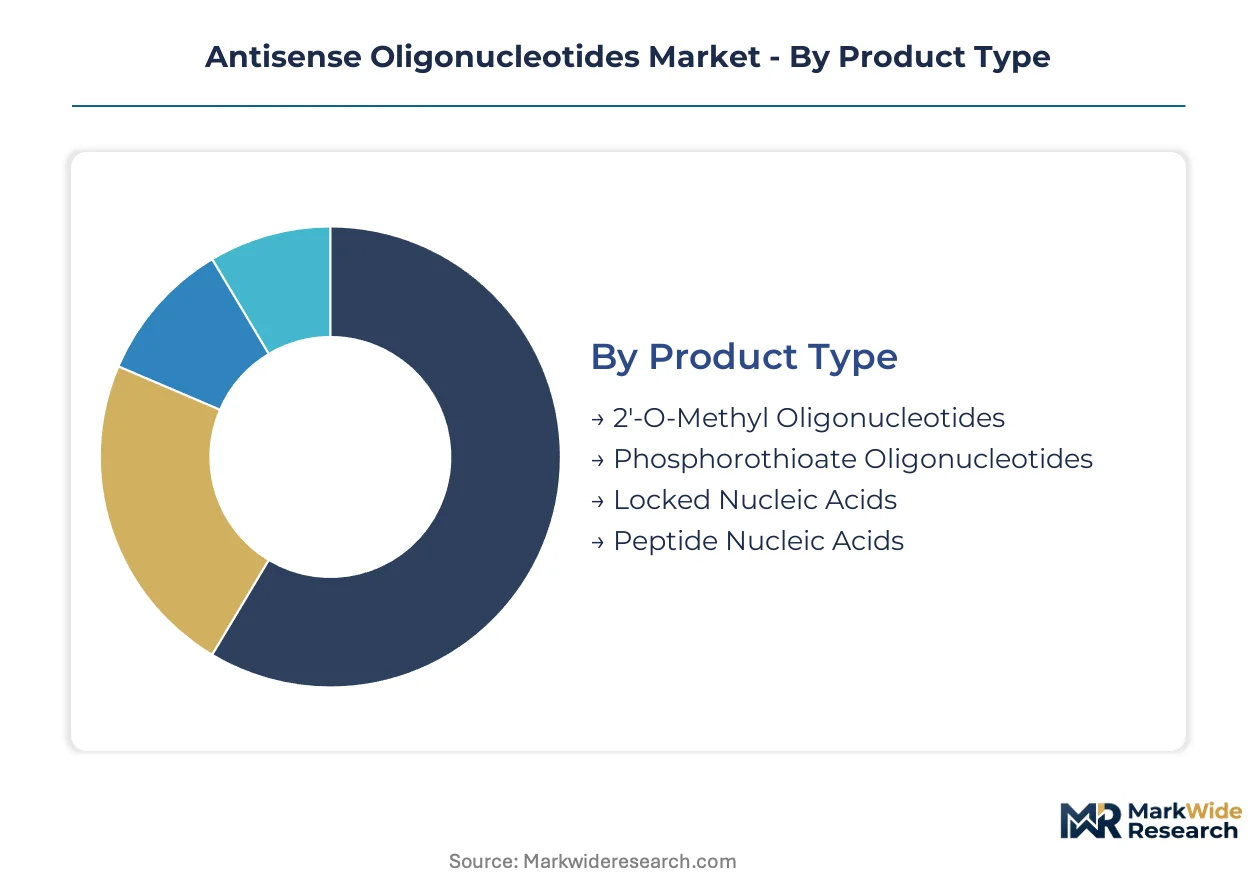
Antisense oligonucleotide developers face divergent substitution pressures across chemistry platforms, therapy areas, and delivery technologies. Segmentation reveals where established modalities defend against next-generation alternatives and where emerging formats displace incumbent standards.
Product Type:
Phosphorothioate backbone modifications face intensifying substitution pressure from constrained nucleic acid chemistries seeking improved target binding and reduced immunogenicity profiles.
- Phosphorothioate Oligonucleotides:Sulfur substitution at the non-bridging oxygen creates nuclease-resistant phosphorothioate linkages that extend plasma half-life. FDA familiarity with this chemistry accelerates regulatory reviews for chronic dosing regimens in spinal muscular atrophy. Manufacturing scalability through solid-phase phosphoramidite synthesis supports commercial production volumes.
- Locked Nucleic Acids:2'-O,4'-C-methylene bridges lock ribose conformations into RNA-mimicking structures, elevating melting temperatures and binding affinity. CNS-targeted developers in Japan and the United States adopt LNAs to improve blood-brain barrier penetration and reduce off-target hybridization. Synthetic complexity limits batch yields and extends lead times versus phosphorothioate alternatives.
- 2'-O-Methyl Oligonucleotides:Ribose modifications at the 2' position confer moderate nuclease stability with reduced immunostimulatory effects compared to phosphorothioates.
- Peptide Nucleic Acids:Synthetic backbones replacing sugar-phosphate structures with peptide linkages offer exceptional biostability and sequence specificity.
Phosphorothioate oligonucleotides retain volume leadership; locked nucleic acids hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates curative-intent genetic disorder applications from chronic disease management programs with extended dosing horizons.
- Genetic Disorders:Single-gene correction targets in Duchenne muscular dystrophy and Huntington's disease command premium pricing supported by orphan drug exclusivity. Prescriber concentration within specialized neurology clinics in the United States concentrates demand and streamlines reimbursement negotiations. Confirmatory trial requirements under EMA conditional marketing authorization frameworks impose post-launch data generation burdens.
- Cancer:Tumor suppressor gene silencing and oncogene targeting applications compete against established small molecule and biologic standards. Solid tumor penetration limitations and systemic toxicity profiles constrain adoption versus immune checkpoint inhibitors. Combination trial designs with chemotherapy or radiation therapy expand addressable patient populations.
- Cardiovascular Disorders:Apolipoprotein and lipoprotein(a) targeting programs address residual cardiovascular risk populations inadequately controlled by statin therapy.
- Infectious Diseases:Viral RNA targeting for hepatitis B and emerging pathogen applications leverages rapid program initiation against conserved genomic sequences.
Genetic disorders capture the highest pricing tiers; cardiovascular applications are climbing the fastest toward commercial scale.
Delivery Mode:
Patient preference and healthcare system cost pressures are displacing hospital-dependent administration toward home-compatible alternatives.
- Intravenous:Infusion center delivery dominates current revenue pools for acute and intermittent dosing protocols requiring clinical monitoring. Hospital pharmacy procurement controls formulary placement and drives contracting leverage toward integrated health systems. Cold chain requirements and infusion infrastructure limit geographic reach to metropolitan treatment centers.
- Subcutaneous:Self-administration devices enable chronic genetic disorder patients to maintain therapy outside clinical settings, reducing healthcare utilization costs. Prefilled syringe and autoinjector formats demand reformulated drug products with modified viscosity and stability profiles. Direct-to-patient distribution models require reconfigured logistics networks with temperature-controlled last-mile capabilities.
- Oral:Gastrointestinal stability and intestinal permeability barriers have historically constrained bioavailability for oligonucleotide therapeutics.
- Intramuscular:Localized depot formation supports sustained release kinetics for applications requiring prolonged pharmacodynamic effects.
Intravenous delivery retains current revenue concentration; subcutaneous administration is gaining structural importance for chronic regimens.
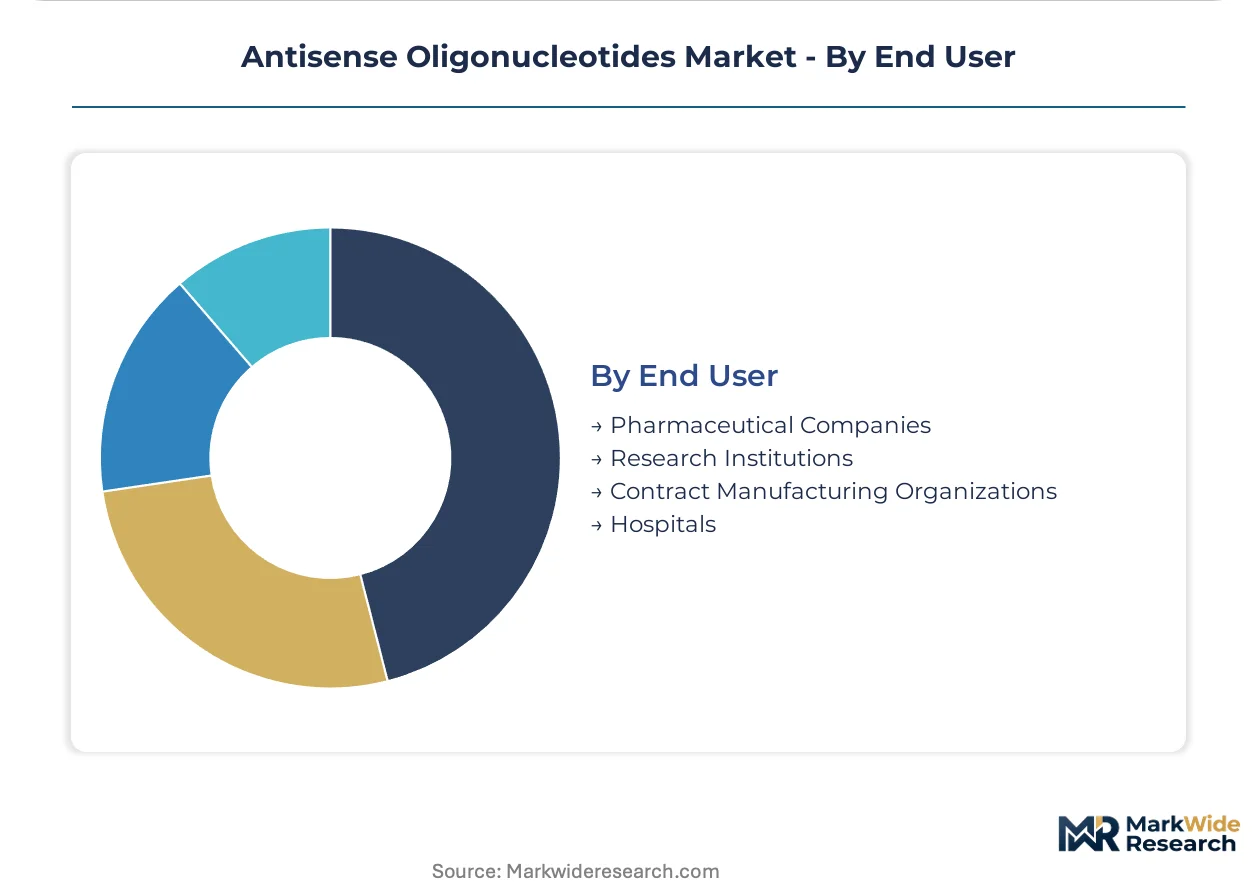
End User:
Supply concentration among phosphoramidite raw material suppliers in North America and Europe shapes procurement strategies across buyer categories.
- Pharmaceutical Companies:Integrated drug discovery engines at Ionis Pharmaceuticals and Biogen internalize manufacturing capabilities to secure supply chain control. In-house phosphoramidite synthesis and fill-finish operations reduce dependency on contract manufacturing networks. Pipeline prioritization decisions weigh regulatory pathway certainty against competitive positioning in crowded target spaces.
- Contract Manufacturing Organizations:Specialized oligonucleotide CDMOs concentrate capacity in regions with established chemical synthesis expertise and regulatory inspection histories. Batch release testing and analytical method validation requirements extend technology transfer timelines for novel chemistry platforms. Capacity constraints during clinical trial expansion phases create supply bottlenecks for mid-stage developers.
- Research Institutions:Academic laboratories and nonprofit research centers drive early-stage target validation and mechanism-of-action studies.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing power through specialty pharmacy carve-outs and payor-aligned formulary committees.
Pharmaceutical companies retain procurement volume leadership; contract manufacturing organizations are expanding most quickly to address pipeline capacity needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug exclusivity provisions concentrate pipeline investment in the United States, while EMA conditional marketing authorization frameworks and Japan's PMDA Sakigake designation create parallel accelerated pathways across three major regulatory jurisdictions.
United States
Specialized neurology clinics in Boston, New York, and San Francisco control prescriber relationships for spinal muscular atrophy and Duchenne muscular dystrophy therapies. FDA breakthrough therapy designation compresses development timelines for rare disease candidates. The Greater Boston biotech cluster anchors integrated drug discovery engines with in-house phosphoramidite synthesis capabilities.
Germany
EMA health technology assessment friction tightens cost-effectiveness thresholds for single-target mechanisms without curative claims. The Federal Joint Committee (G-BA) demands mortality or functional outcome data for neurology indications under conditional marketing authorization. The Rhine-Main biopharma corridor concentrates contract manufacturing capacity for European clinical trial supply.
Japan
PMDA Sakigake designation opens priority review frameworks for innovative oligonucleotide therapeutics targeting CNS indications. METI's regenerative medicine and cellular therapy commercialization programs extend to nucleic acid-based modalities. The Kanto region's pharmaceutical manufacturing base supports fill-finish operations for temperature-sensitive finished products.
Switzerland
Swissmedic's streamlined authorization procedures attract clinical trial sponsorship for locked nucleic acid platforms seeking European market entry. The country's central logistics position enables cold chain distribution networks spanning German, French, and Italian patient populations. Basel's biopharma cluster hosts analytical method validation capabilities for novel chemistry platforms.
United Kingdom
MHRA's Innovative Licensing and Access Pathway preserves accelerated review mechanisms post-Brexit for antisense candidates addressing unmet genetic disease needs. The NHS England specialized commissioning framework concentrates patient access for high-cost therapies in designated treatment centers. The Cambridge-London life sciences corridor sustains early-stage target validation research through academic-industry partnerships.
Antisense Oligonucleotides Market Vendor Landscape
Listed leaders compete with private specialists across chemistry platform diversification and manufacturing scale. The market structures around three tiers: integrated pharmaceutical conglomerates with neurology franchises, mid-cap biotechs with deep clinical pipelines, and emerging specialists pursuing next-generation constrained nucleic acids. Strategic moves center on backward integration into phosphoramidite raw material supply and capacity expansion among contract manufacturing networks to address clinical trial bottlenecks.
Within the integrated discovery engine tier, Ionis Pharmaceuticals exemplifies vertical control over solid-phase synthesis operations, while Biogen occupies a position anchored through commercial infrastructure in spinal muscular atrophy. Sarepta Therapeutics represents the muscular dystrophy specialization archetype with patient advocacy integration that controls prescriber relationships.
| Leading Market Players |
|---|
| Ionis Pharmaceuticals |
| Biogen |
| Sarepta Therapeutics |
| Alnylam Pharmaceuticals |
| Wave Life Sciences |
| AstraZeneca |
| Novartis |
| Regulus Therapeutics |
| Antisense Therapeutics |
| Others |
Supply Flow & Price Mechanics
FDA orphan drug exclusivity provisions and EMA conditional marketing authorization frameworks gate both supply qualification and price differentiation simultaneously, with certification tier determining which manufacturers can access premium pricing tiers for rare disease applications. Specialized neurology clinics in the United States concentrate procurement power while contract manufacturing organizations compete on phosphoramidite synthesis capabilities that anchor cost structures across the value chain.
Pricing Analysis
Certification level creates the primary spread between premium orphan drug tiers and standard chronic disease applications, with FDA breakthrough therapy designation commanding the steepest premiums. Three-tier pricing structure across premium genetic disorder, standard neurology maintenance, and economy cardiovascular prevention levels stratifies buyer access. Pricing pressure stems from EMA health technology assessment friction demanding mortality data for conditional marketing authorization renewals. Research institutions exhibit highest price sensitivity due to grant-funded procurement constraints, while integrated pharmaceutical conglomerates absorb premiums through captive manufacturing.
Supply Chain Analysis
Strategic stockpiling of modified nucleoside phosphoramidites dominates inventory strategy as batch yield variability in locked nucleic acid synthesis creates supply uncertainty. Manufacturing concentrates in the United States, Germany, and Switzerland where solid-phase synthesis expertise and regulatory inspection histories cluster. Raw material dependencies center on phosphoramidite monomers, sulfurizing reagents, and controlled-pore glass supports. Single-source vulnerability concentrates among North American phosphoramidite suppliers. Distribution runs through cold chain logistics networks with temperature-controlled last-mile capabilities for finished oligonucleotide therapeutics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated neurology clinics and specialized treatment centers in the United States, with hospital system consolidation fragmenting procurement leverage across regional markets.
For Market Incumbents: Secure backward integration into phosphoramidite raw material supply to defend against locked nucleic acid chemistry substitution and contract manufacturing organization capacity bottlenecks. Anchor manufacturing scale in the Greater Boston biotech cluster where regulatory familiarity with phosphorothioate synthesis accelerates batch release timelines. Reinforce prescriber relationships through patient advocacy integration that controls formulary placement in consolidated neurology clinic networks. For New Entrants and Emerging Players: Differentiate on constrained nucleic acid platforms targeting CNS indications with improved blood-brain barrier penetration as the most penetrable white space beyond established neurology franchises. Target cardiovascular applications in residual risk populations inadequately controlled by statin therapy where pricing thresholds remain less stringent than genetic disorders. Pursue Japan PMDA Sakigake designation as the primary go-to-market accelerant for novel oligonucleotide mechanisms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across locked nucleic acid manufacturing as synthetic complexity limits batch yields and extends lead times versus phosphorothioate alternatives. Mid-cap biotechs with deep clinical pipelines in muscular dystrophy and spinal muscular atrophy represent viable acquisition targets for pharmaceutical conglomerates seeking neurology franchise expansion. Watch EMA confirmatory trial completion rates as the signal to watch for European market access sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA conditional marketing authorization frameworks demand post-launch mortality data for neurology indications. |
| Manufacturing Scale-Up | Solid-phase phosphoramidite synthesis capacity expansion addresses clinical trial supply bottlenecks for mid-stage developers. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for rare disease candidates with surrogate endpoints. |
| Licensing Agreement | Phosphorothioate chemistry licensing from Ionis Pharmaceuticals anchors competitor pipeline positioning. |
| Pipeline Diversification | Cardiometabolic expansion into apolipoprotein targets reduces dependency on neurology franchise concentration. |
Methodological Framework
A spread of perspectives from drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers converged on the working assumptions underpinning this analysis. Primary interviews with payer access specialists and contract manufacturing organization operations heads combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient population sizing and top-down revenue triangulation anchored volume and value estimates.
Segmentation dimensions modeled include chemistry platform, therapy area, delivery mode, and end user across the projection horizon. CAGRs derived from epidemiological trend analysis, pricing trajectory assumptions, and regulatory pathway probability weighting. Forecast inputs incorporated phosphoramidite supply capacity expansion timelines and neurology clinic penetration rates by metropolitan statistical area.
Decision-makers should treat outputs as directional under assumptions of sustained orphan drug exclusivity provisions and stable phosphoramidite supplier concentration; material deviation would warrant model refresh. Revision becomes warranted when EMA health technology assessment thresholds for single-target mechanisms tighten beyond current mortality data requirements or when locked nucleic acid manufacturing yields inflect materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Genetic Leukemia Detection Testing Market
Genomics
Molecular Biomarkers for Cancer Detection Market
Genomics
Genetic Testing Market
Genomics
Genotyping Market
Genomics
APO E Gene Test Kit Market
Genomics
Gene Sequencing Market
Genomics
Whole Genome Amplification Market
Genomics
Global Molecular Cytogenetics Market
Genomics
DNA Sequencing Market
Genomics
Forensic Genomics Market
Genomics
Europe DNA Sequencing Products Market
Genomics
Transcriptomics Technologies Market
Genomics
Next-Generation Sequencing (NGS) Workflow Quality Control Test Kits and Instruments Market
Genomics
Short-Read Sequencing Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market