
 SNP Genotyping Market | 2026-2036
SNP Genotyping Market Size, Share, and Industry Trends Forecast 2026-2036
SNP Genotyping Market Outlook
Next-generation sequencing integration is rewriting the SNP genotyping technology stack, collapsing the cost per data point while expanding multiplexing capacity beyond legacy microarray limits. Illumina leverages its installed base of sequencing instruments to anchor clinical genotyping workflows in major diagnostic networks. Thermo Fisher Scientific competes through vertical control over reagent supply chains and thermal cycler hardware. Bio-Rad Laboratories specializes in droplet digital PCR architectures that address rare-variant detection in oncology panels.
SNP genotyping identifies single nucleotide polymorphisms at specific genomic loci using allele-specific hybridization, primer extension, or ligation-based chemistries, typically resolving variant calls at frequencies above 0.1% depending on platform sensitivity. The technology serves pharmacogenomic dosing guidance, agricultural trait selection, and forensic identity profiling. Sequencing-based approaches capture the fastest expansion as read-length improvements and bioinformatics pipelines mature, while PCR retains dominance in point-of-care settings where turnaround time governs purchasing decisions. Microarray formats occupy a narrowing but defensible niche in high-volume consumer genotyping and biobank applications where per-sample cost minimization outweighs discovery breadth.
FDA oversight of laboratory-developed tests and companion diagnostic co-approval requirements shapes product development timelines and clinical market access for genotyping assay manufacturers. EMA's In Vitro Diagnostic Regulation and ISO 13485 quality management standards impose additional conformity burdens on vendors seeking European clinical laboratory placement. Stakeholders must monitor evolving reimbursement coding for pharmacogenomic testing and premarket submission pathway harmonization between jurisdictions to anticipate capital allocation priorities and partnership structures.
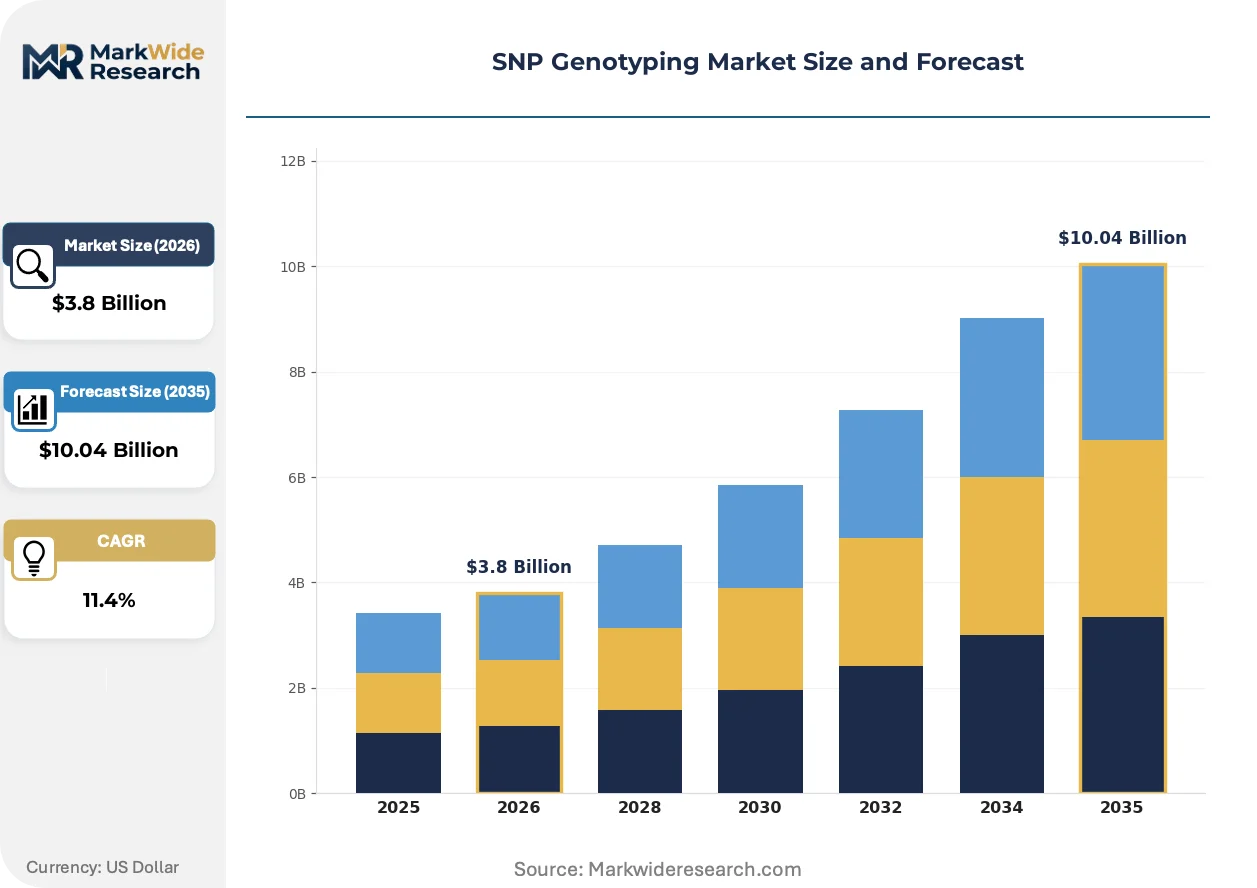
Market Dynamics
Next-generation sequencing platforms are compressing the cost-per-genotype threshold below microarray economics, forcing incumbent vendors to defend installed bases through workflow integration rather than hardware superiority alone.
Growth Catalysts
- Companion diagnostic co-approvals:FDA's tightened LDT oversight creates captive demand for validated genotyping platforms in oncology and cardiovascular therapeutic development pipelines.
- Pharmacogenomic reimbursement expansion:Germany's G-BA and US CMS coding updates for pre-emptive PGx testing in psychiatry and cardiology accelerate clinical laboratory adoption.
- CRISPR-integrated screening workflows:Agricultural biotechnology firms deploy high-plex SNP panels to accelerate trait stacking in row crops and livestock breeding programs.
Market Restraints
- Reagent supply concentration:Three vendors control over 80% of certified polymerase and fluorescent probe supply, exposing assay manufacturers to input cost volatility and allocation risk.
- Bioinformatics bottleneck:Variant interpretation pipelines require PhD-level computational biology talent that clinical laboratories cannot recruit at prevailing diagnostic technologist compensation bands.
- Sequencing substitution threat:Targeted NGS panels at sub-$50 per-sample price points erode the cost advantage that PCR-based SNP methods held in medium-plex applications.
Strategic Opportunities
- Point-of-care decentralization:India's CDSCO fast-track pathway for portable molecular diagnostics creates first-mover advantage for battery-operated isothermal amplification platforms in district hospital networks.
- Direct-to-consumer regulatory arbitrage:Brazil's ANVISA framework for wellness genotyping permits health-risk reporting that FDA-classified devices cannot offer, attracting kit manufacturers to São Paulo logistics hubs.
- AI-driven variant classification:Convergence of transformer architectures with population allele frequency databases reduces manual curation burden and accelerates report turnaround in high-volume reference laboratories.
Industry Challenges
- ISO 13485 certification timelines:European IVD-DR technical documentation requirements extend product launch cycles by 14-18 months for mid-cap assay developers lacking prior notified body relationships.
- LIMS integration complexity:Legacy laboratory information management systems in US health system networks require custom API development to accept structured genotyping output, inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | SNP Genotyping Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microarrays, Sequencing, PCR, SNP Panels Application: Medical Diagnostics, Agriculture, Forensic Biology, Pharmacogenomics End User: Research Institutions, Clinical Laboratories, Pharmaceutical Companies, Biotech Firms Product Type: Kits, Reagents, Software, Services |
| Companies Covered | Bio-Rad Laboratories, Affymetrix, Illumina, Sequenom, Agena Bioscience, Thermo Fisher Scientific, LGC Group, Promega, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
SNP Genotyping Market Strategic Shifts
Cloud-native bioinformatics architectures are collapsing the capital barrier to high-throughput variant analysis, enabling mid-scale laboratories to compete with reference-grade sequencing centers on turnaround time and report sophistication.
Digital PCR chemistries are digitizing rare allele detection workflows that previously required orthogonal confirmation sequencing, enabling circulating tumor DNA monitoring at 0.01% variant allele frequency thresholds. Oncology reference laboratories in the United States and Switzerland are adopting these platforms to support minimal residual disease testing contracts. The technology is digitizing the economics of liquid biopsy validation by eliminating the sequencing confirmation step that previously consumed 40% of assay cost.
EMA's In Vitro Diagnostic Regulation and FDA's pending LDT rulemaking are converging on str analytical validation standards for software-as-medical-device components in genotyping pipelines. Assay manufacturers must now submit locked algorithm versions with premarket submissions, freezing iterative bioinformatics improvements that previously shipped as post-launch updates. European clinical laboratories are responding by consolidating vendor relationships to reduce qualified platform count and audit burden.
Hospital procurement committees are unbundling after-sales service contracts from instrument purchase agreements, demanding à-la-carte training and remote support options that compress vendor service margins. Academic medical centers in Germany and the Netherlands lead this shift, using framework agreements to standardize service levels across multi-site instrument fleets. The pattern is most visible in NGS platform acquisitions where capital committees prioritize total cost-of-ownership transparency over bundled financing incentives.
SNP Genotyping Market Segmentation
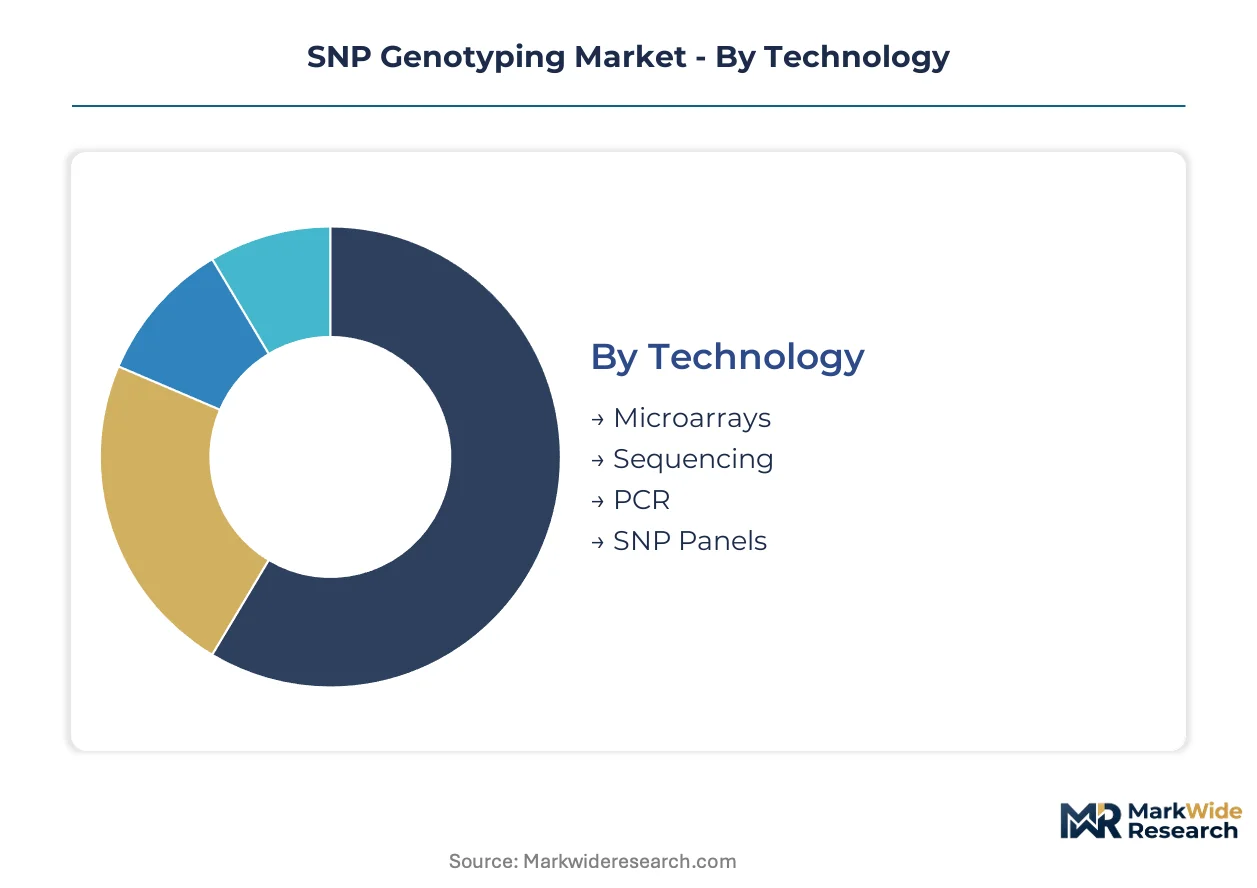
Technology heterogeneity in SNP genotyping creates distinct service and support requirements across customer segments. Platform selection drives recurring revenue intensity, consumable lock-in, and bioinformatics integration complexity for vendors.
Technology:
After-sales-service intensity varies sharply across technology platforms, with sequencing workflows demanding field application scientist deployment and PCR systems requiring thermal cycler calibration contracts.
- Microarrays:Silicon-based probe arrays enable parallel interrogation of thousands to millions of SNPs per hybridization event. Agricultural biotechnology firms in the United States and Germany concentrate demand for high-density trait screening panels where per-sample cost minimization governs purchasing decisions.
- Sequencing:Next-generation platforms capture variant calls through clonal amplification and fluorescent readout, collapsing cost-per-data-point below legacy methods. Clinical reference laboratories in Switzerland and the United States drive adoption for oncology companion diagnostic workflows where multiplexing breadth accelerates regulatory submission timelines.
- PCR:Thermal cycling amplification with allele-specific primers delivers rapid turnaround for low-plex applications. Point-of-care settings prioritize these systems where battery-operated portability enables district hospital deployment.
- SNP Panels:Pre-designed primer sets target disease-associated loci for targeted genotyping without full sequencing overhead. Pharmacogenomic testing programs in Germany leverage these for pre-emptive CYP2C19 and SLCO1B1 screening.
By volume, PCR leads. By growth pace, sequencing is ahead.
Application:
Application segments diverge by reimbursement pathway maturity, regulatory validation burden, and customer procurement sophistication.
- Medical Diagnostics:Germline and somatic variant detection for inherited disease risk assessment. United States health system networks concentrate demand where CMS coverage determinations for hereditary cancer panels stabilize revenue predictability.
- Agriculture:Marker-assisted selection and genomic estimated breeding value calculations for crop and livestock improvement. Brazilian agricultural biotechnology firms deploy high-plex panels for soybean trait stacking under ANVISA biosafety frameworks.
- Forensic Biology:Identity profiling and kinship analysis through CODIS-compatible short tandem repeat and SNP marker sets. FBI quality assurance standards govern United States crime laboratory procurement specifications.
- Pharmacogenomics:Drug-gene interaction testing to guide dosing and avoid adverse events. Germany's G-BA reimbursement expansion for psychiatric and cardiovascular PGx testing accelerates clinical laboratory adoption.
Pharmacogenomics claims the steepest expansion trajectory as pre-emptive testing protocols displace reactive genotyping.
End User:
End user categories separate by capital availability, technical staffing depth, and regulatory compliance maturity.
- Research Institutions:Academic genomics cores and government research facilities pursuing discovery-scale variant association studies. United States NIH-funded centers concentrate demand for population-scale biobank genotyping.
- Clinical Laboratories:CAP-accredited and ISO 15189-certified diagnostic facilities performing reimbursable testing. German hospital network laboratories lead European adoption of automated liquid handling for high-throughput pharmacogenomic workflows.
- Pharmaceutical Companies:Companion diagnostic co-development and clinical trial patient stratification. FDA premarket approval requirements drive investment in locked algorithm versions for prospective validation.
- Biotech Firms:Agile developers of CRISPR screening and synthetic biology applications. Switzerland's Basel cluster concentrates gene editing tool companies deploying SNP panels for guide RNA optimization.
Clinical laboratories generate the highest consumable pull-through per installed instrument.
Product Type:
Product type segmentation reveals margin architecture and customer switching cost distribution across the value chain.
- Kits:Pre-formulated reagent sets with validated protocols reducing assay development burden. Mid-scale clinical laboratories in the Netherlands prioritize CE-IVD marked kits to streamline EMA technical documentation.
- Reagents:Bulk polymerases, fluorescent probes, and master mixes for assay manufacturers. Supply concentration among three certified vendors exposes buyers to allocation risk during demand surges.
- Software:Variant calling algorithms, quality control pipelines, and laboratory information management interfaces. Cloud-native architectures enable mid-scale United States laboratories to compete with reference centers on turnaround time.
- Services:Contract genotyping, bioinformatics analysis, and regulatory consulting. Pharmaceutical sponsors in Switzerland outsource companion diagnostic validation to specialized reference laboratories.
Reagents capture the largest revenue share. Services are climbing the fastest as regulatory complexity drives outsourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clinical laboratories and agricultural biotechnology firms concentrate purchasing power in jurisdictions with mature reimbursement frameworks and biosafety infrastructure. FDA and EMA regulatory harmonization shapes vendor market access strategies across developed economies.
United States
CAP-accredited hospital networks and reference laboratories drive consumable pull-through for pharmacogenomic and oncology companion diagnostic workflows. FDA's pending LDT rulemaking tightens analytical validation requirements for laboratory-developed genotyping assays. The Boston-Cambridge corridor anchors companion diagnostic co-development partnerships between pharmaceutical sponsors and specialized testing facilities.
Germany
G-BA reimbursement expansion for pre-emptive CYP2C19 and SLCO1B1 screening accelerates clinical laboratory automation investments. EMA's In Vitro Diagnostic Regulation imposes ISO 13485 certification burdens on assay manufacturers seeking European market placement. The Rhine-Main cluster around Frankfurt concentrates high-throughput pharmacogenomic testing capacity for psychiatric and cardiovascular applications.
Switzerland
Swissmedic oversight of companion diagnostics and minimal residual disease testing sustains premium pricing for rare-variant detection platforms. Basel's gene editing tool companies deploy SNP panels for CRISPR guide RNA optimization in agricultural biotechnology applications. Zurich reference laboratories lead European adoption of digital PCR for circulating tumor DNA monitoring at 0.01% variant allele frequency thresholds.
Brazil
ANVISA's wellness genotyping framework permits health-risk reporting that FDA-classified devices cannot offer, attracting direct-to-consumer kit manufacturers. São Paulo logistics hubs serve Latin American distribution for agricultural biotechnology firms deploying high-plex panels for soybean trait stacking. The country's national pharmaceutical regulator maintains biosafety oversight of gene-edited crop field trials.
India
CDSCO's fast-track pathway for portable molecular diagnostics creates first-mover opportunity for battery-operated isothermal amplification platforms in district hospital networks. Hyderabad and Bangalore clusters concentrate contract research organizations supporting global pharmaceutical genotyping studies. State-level biotechnology parks in Telangana and Karnataka offer tax incentives for genomics infrastructure investment.
SNP Genotyping Market Competitive Environment
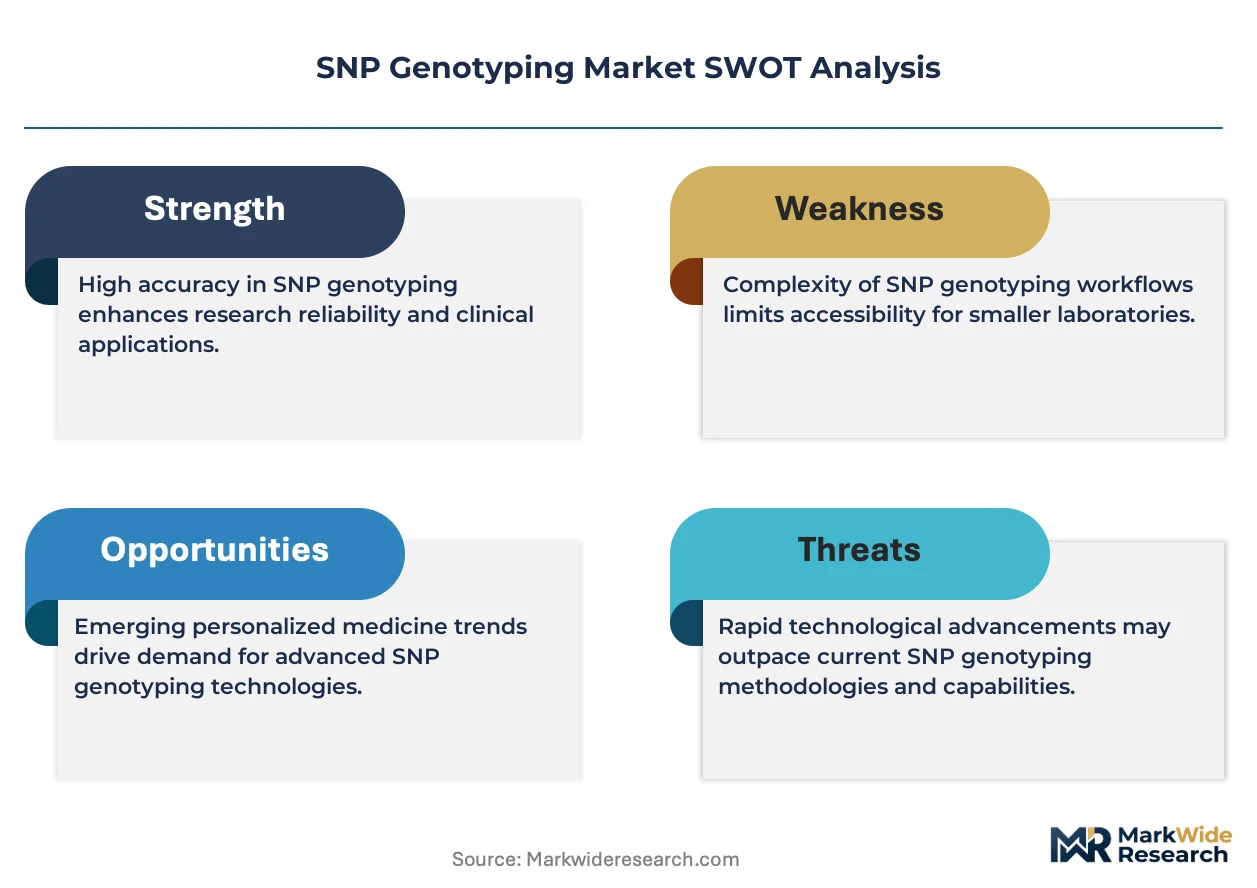
Channel-controlling players compete with product-specialist players for consumable lock-in and bioinformatics integration contracts. The market structure consolidates around sequencing platform vendors with installed base advantages and reagent manufacturers with certified polymerase supply control. Three archetypes dominate: integrated sequencing-software vendors, thermal cycler and reagent specialists, and droplet digital PCR innovators. Competitive moves center on workflow unbundling to capture service revenue and strategic partnerships to secure companion diagnostic co-approval pathways.
Within the integrated platform tier, Illumina leverages its sequencing instrument installed base to anchor clinical genotyping workflows, while Thermo Fisher Scientific exemplifies vertical control over reagent supply chains and thermal cycler hardware. Bio-Rad Laboratories occupies a specialist position in droplet digital PCR architectures for rare-variant detection applications. These three companies represent distinct competitive vectors: sequencing-based multiplexing expansion, consumable supply concentration, and digital PCR sensitivity thresholds.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Affymetrix |
| Illumina |
| Sequenom |
| Agena Bioscience |
| Thermo Fisher Scientific |
| LGC Group |
| Promega |
| Agilent Technologies |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on certified polymerase supply chains from three dominant vendors exposes assay manufacturers to simultaneous input cost volatility and allocation rationing, compressing margins across premium reagent tiers while forcing mid-scale buyers toward spot-market procurement strategies that fragment their supplier relationships.
Pricing Analysis
Cost-plus contracts with quarterly indexation to commodity chemical benchmarks govern bulk reagent supply agreements between certified polymerase manufacturers and large-scale assay developers. Three-tier pricing structure across premium, standard, and economy levels separates CE-IVD marked kits from research-use-only formulations and unvalidated bulk reagents. Cost compression in standard-tier PCR master mixes is intensifying because sequencing-based substitution erodes volume commitments. Academic medical centers exhibit the highest price sensitivity due to grant-funded procurement cycles, while pharmaceutical companion diagnostic programs absorb premium pricing for locked-algorithm regulatory submissions.
Supply Chain Analysis
Upstream feedstock concentration for fluorescent dyes and modified nucleotides centers on Germany, Switzerland, and the United States, where specialty chemical manufacturers maintain GMP-certified production lines for clinical-grade inputs. Certified polymerases, synthetic oligonucleotides, and optical detection reagents constitute the critical component trinity. Single-source vulnerability pervades dye chemistry supply, where one Swiss manufacturer controls the majority of far-red fluorophore production. Distribution runs through authorized distributor networks with regional stocking requirements that extend lead times for mid-scale clinical laboratories outside major metropolitan clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of PhD-level computational biologists capable of operating variant interpretation pipelines creates a capability bottleneck that constrains clinical laboratory expansion and inflates bioinformatics service premiums. This scarcity shapes competitive advantage around talent retention and automated algorithm deployment.
For Market Incumbents: Harden consumable lock-in through backward integration into certified polymerase production or captive oligonucleotide synthesis capacity, insulating against supply allocation shocks from the three dominant reagent vendors. Accelerate cloud-native bioinformatics platform deployment to reduce customer dependency on scarce computational biology talent, converting professional services revenue into recurring SaaS subscriptions that withstand pricing pressure from emerging sequencing-based competitors. For New Entrants and Emerging Players: India's district hospital networks present the most penetrable white-space target, where CDSCO's fast-track pathway for portable molecular diagnostics permits battery-operated isothermal amplification platforms to bypass established thermal cycler installed bases. Brazil's ANVISA wellness genotyping framework offers a regulatory arbitrage entry point for direct-to-consumer kit manufacturers seeking health-risk reporting capabilities unavailable under FDA classifications. A contract-manufacturing partnership with São Paulo logistics hubs enables pan-Latin American distribution without capital-intensive infrastructure buildout. For Investors and Strategic Acquirers: FDA's pending LDT rulemaking reshapes the acquisition landscape by elevating the strategic value of CAP-accredited laboratories with locked-algorithm validation dossiers already submitted for companion diagnostic co-approvals. Targets with ISO 13485 certification and established notified body relationships command premium positioning as European IVD-DR compliance timelines extend product launch cycles for mid-cap developers. The signal to watch is CMS reimbursement coding expansion for pre-emptive pharmacogenomic testing, which would trigger consolidation demand among health system networks seeking turnkey PGx program deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Approval Pathway | FDA premarket submission locks algorithm versions and secures oncology therapeutic development partnerships. |
| Cloud-Native Bioinformatics Platform Launch | Mid-scale United States laboratories compete with reference centers on turnaround time without PhD-level hires. |
| CE-IVD Marking Pathway Completion | EMA technical documentation streamlines German hospital network procurement under G-BA reimbursement expansion. |
| Backward Integration into Polymerase Supply | In-house production of certified enzymes insulates assay manufacturers from allocation risk during demand surges. |
| Hospital System Partnership for PGx Programs | Pre-emptive CYP2C19 and SLCO1B1 screening contracts anchor consumable pull-through in psychiatric and cardiovascular applications. |
Study Parameters
Operator-level perspectives from clinical laboratory directors, companion diagnostic program managers at pharmaceutical sponsors, CAP accreditation officers, and reagent procurement specialists anchored the qualitative base for this study. These primary insights combined with secondary validation from FDA 510(k) and PMA filings, EMA In Vitro Diagnostic Regulation technical documentation, CMS national coverage determinations, and German G-BA reimbursement decision memoranda. Bottom-up instrument and consumable unit economics triangulated against top-down market sizing from health system procurement databases and pharmaceutical clinical trial genotyping disclosures.
Scenario-bracketing around regulatory pathway timing and pharmacogenomic reimbursement expansion shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology platform, application vertical, end-user category, and product type, with additional granularity on regulatory certification tier and bioinformatics integration depth. CAGRs derived from weighted average of historical adoption curves and policy-inflected demand step-changes, incorporating companion diagnostic co-approval pipeline velocity and agricultural biotechnology trait-stacking program announcements as industry-specific forecast inputs.
Practitioners should monitor FDA LDT rulemaking finalization, EMA notified body capacity constraints, and CMS coding updates for pre-emptive PGx testing for early signals requiring forecast revision. Cross-checking against hospital capital expenditure surveys and pharmaceutical R&D pipeline disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Genomics
Mrna Sequencing Market
Genomics
Whole Genome Amplification Market
Genomics
Pharmacogenomic (Pgx) Testing Market
Genomics
Omics Lab Services Market
Genomics
Next Generation Molecular Assay Market
Genomics
Direct-To-Consumer (DTC) Genetic Testing Market
Genomics
Glycan Sequencing Market
Genomics
Global Microbiome Sequencing Services Market
Genomics
Genetic Testing Service Market
Genomics
NGS Automation Market
Genomics
DNA Sequencing Market
Genomics
Middle East and Africa Whole Exome Sequencing Market
Genomics
PCR and NGS Based Diagnostic Testing Market
Genomics
Global Microarray Analysis Market
Genomics
US Direct-To-Consumer Genetic Testing Market
Genomics
US Genetic Testing Market