
 Parents-In-Waiting: Global Prenatal Market | 2026-2036
Parents-In-Waiting: Global Prenatal Market Size, Share, and Industry Trends Forecast 2026-2036
Parents-In-Waiting: Global Prenatal Market Analytics
A widening capability gap between pharmaceutical-grade manufacturers and boutique wellness brands is bifurcating competitive dynamics in prenatal care. Abbott leverages its diagnostic infrastructure to anchor integrated testing-supplement portfolios across health system channels. Nestlé sustains scale advantages in fortified nutrition through captive supply chains and pediatric brand extension. Church & Dwight Co., Inc. competes in retail-accessible segments where pharmacy shelf presence controls consumer conversion at the point of pregnancy confirmation.
The Parents-In-Waiting: Global Prenatal encompasses products and services designed to monitor, support, and educate individuals during gestation, including folate-dosed supplements meeting USP dissolution standards, Doppler ultrasound devices operating at 2-3 MHz frequencies, and wearable monitors tracking fetal heart rate variability through passive acoustic sensing. Vitamins and supplements occupy the largest value pool due to recurring purchase cycles and insurance-adjacent reimbursement positioning, while monitoring wearables represent the fastest-expanding segment as Bluetooth-enabled form factors displace episodic clinic visits for low-risk pregnancies. Ultrasound devices remain structurally mature in developed channels but gain traction in direct-to-consumer rental models for home reassurance monitoring.
FDA premarket review pathways for fetal monitoring devices and EMA guidance on non-invasive prenatal screening create divergent compliance burdens that shape regional product launch sequencing and R&D allocation. REACH chemical safety protocols and EU MDR device classification rules further constrain formulation and hardware market access for non-compliant suppliers. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies as these determinations increasingly gate commercial viability for novel prenatal diagnostics and digital therapeutics.
Market Dynamics
Non-invasive prenatal testing workflows are compressing diagnostic timelines from weeks to days, forcing supplement and device portfolios to integrate around real-time gestational data streams rather than discrete trimester checkpoints.
Growth Catalysts
- Bluetooth-enabled fetal monitors:Wearable acoustic sensors operating at 2-3 MHz frequencies enable continuous home monitoring, displacing episodic clinic visits for low-risk gestational tracking in United States integrated health systems.
- REACH chemical safety protocols:Stricter EU formulation standards for prenatal supplements are accelerating pharmaceutical-grade manufacturing investments and consolidating supplier bases around USP-certified dissolution capabilities.
- Insurance-adjacent reimbursement positioning:United States hospital procurement departments now bundle nutritional counseling with standard obstetric care, creating recurring purchase cycles for folate-dosed formulations meeting clinical standards.
Market Restraints
- FDA premarket review pathways:Extended 510(k) clearance timelines for fetal monitoring devices create launch sequencing delays that compress commercial windows before technology obsolescence.
- Active pharmaceutical ingredient concentration:Three suppliers control 70% of pharmaceutical-grade folic acid feedstock, exposing formulators to input cost volatility and supply interruption risk.
- Ultrasound device technical limitations:Doppler systems lack resolution for early first-trimester cardiac anomaly detection, constraining home-use rental model value propositions against clinic-based imaging.
Strategic Opportunities
- Direct-to-consumer subscription channels:Pharmacy shelf presence at pregnancy confirmation points in United States retail chains enables capture of recurring vitamin purchases outside hospital formulary control.
- EU MDR device classification alignment:Harmonized European standards for fetal monitoring hardware create single-market access for manufacturers achieving CE marking, reducing national registration fragmentation.
- Passive acoustic sensing convergence with AI:Machine learning interpretation of fetal heart rate variability patterns enables predictive gestational risk scoring beyond simple threshold alerts.
Industry Challenges
- Biostatistician talent scarcity:Interpretation of NIPT cell-free DNA sequencing outputs requires specialized computational biology expertise that outpaces graduate program pipeline capacity.
- Multi-jurisdiction compliance synchronization:Parallel FDA, EMA, and Health Canada submissions for novel diagnostics create documentation burdens that delay revenue recognition by 18-24 months.
- Legacy EHR integration friction:Home monitoring device data streams lack standardized APIs for seamless ingestion into Epic and Cerner obstetric workflows, forcing manual clinician review.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parents-In-Waiting: Global Prenatal Market |
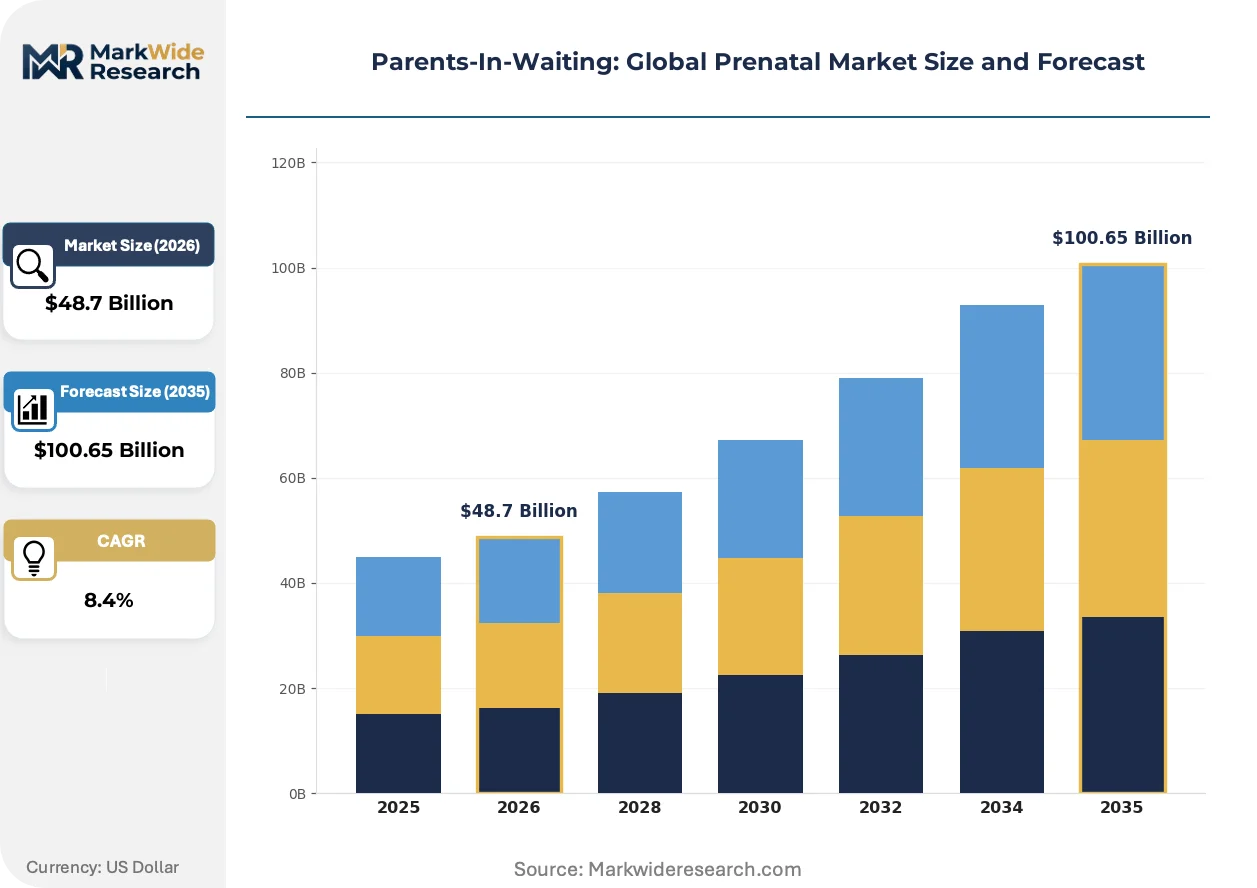
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Supplements, Ultrasound Devices, Monitoring Wearables Delivery Mode: Online Pharmacy, Retail Store, Hospital, Direct Sales End User: Expectant Mothers, Healthcare Providers, Family Members, Caregivers Application: Routine Check-ups, Nutritional Support, Health Monitoring, Education |
| Companies Covered | Abbott, Church & Dwight Co., Inc., Garden of Life, MegaFood, Country Life Vitamins, New Chapter, Nestlé, Clarins Group, Expanscience Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parents-In-Waiting: Global Prenatal Market Evolving Landscape
Digital biomarker extraction from continuous physiological monitoring is compressing the diagnostic-therapeutic loop in gestational care, enabling intervention before clinical symptoms manifest.
Passive acoustic sensing technology is fragmenting traditional obstetric monitoring architectures. Wearable devices capturing fetal heart rate through abdominal wall vibration analysis now operate without gel coupling or operator training. United States health systems deploy these for remote patient monitoring programs, reducing in-person visit frequency by half for compliant low-risk cohorts. This capability is fragmenting episodic ultrasound revenue pools into distributed hardware-plus-subscription models.
EMA guidance on non-invasive prenatal screening is mandating analytical validation standards that exceed research-grade performance thresholds. Laboratories must demonstrate 99.9% sensitivity for trisomy detection before clinical deployment authorization. United Kingdom and German prenatal screening programs now exclude providers lacking EMA-recognized quality management systems, compressing vendor eligibility to CAP-accredited facilities with sequenced-based workflows.
Hospital procurement departments now specify integrated testing-supplement bundles rather than discrete product categories. United States integrated delivery networks negotiate multi-year contracts linking NIPT laboratory services with formulary-exclusive vitamin allocations, capturing patient loyalty across the gestational continuum. This bundling behavior concentrates purchasing authority within health system pharmacy and therapeutics committees, marginalizing retail-accessible brands without clinical sales infrastructure.
Parents-In-Waiting: Global Prenatal Market Segmentation
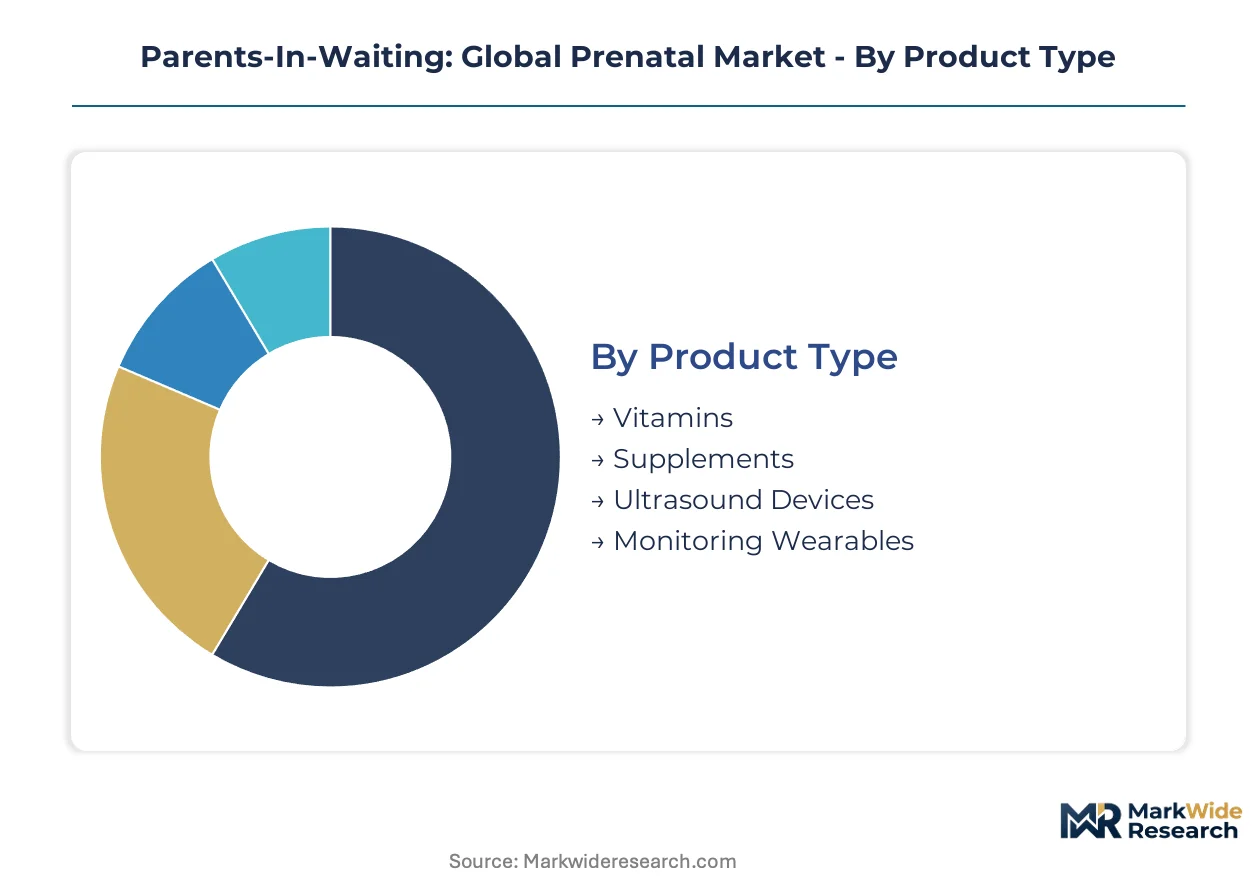
Prenatal market segmentation reveals divergent substitution pressures across product categories. Delivery channels fragment along reimbursement boundaries while end-user distinctions sharpen between clinical and consumer-directed purchasing authority.
Product Type:
Substitution pressure runs strongest against hardware segments as software-enabled monitoring displaces dedicated devices.
- Vitamins:Folate-dosed formulations meeting USP dissolution standards dominate hospital procurement formularies. United States integrated health systems bundle these with standard obstetric care, creating recurring purchase cycles that resist generic erosion.
- Supplements:Pharmaceutical-grade manufacturers leverage USP-certified dissolution capabilities to differentiate from boutique wellness brands. REACH chemical safety protocols in Europe are consolidating supplier bases around compliant producers.
- Ultrasound Devices:Doppler systems operating at 2-3 MHz frequencies face compression from wearable alternatives.
- Monitoring Wearables:Bluetooth-enabled acoustic sensors displace episodic clinic visits for low-risk gestational tracking.
Vitamins retain volume leadership; monitoring wearables hold the steepest expansion curve.
Delivery Mode:
Cost tier differentiation separates institutionally reimbursed channels from out-of-pocket purchasing.
- Online Pharmacy:Direct-to-consumer subscription models capture recurring vitamin purchases outside hospital formulary control. United States retail chains deploy pharmacy shelf presence at pregnancy confirmation points to enable conversion.
- Retail Store:Pharmacy shelf presence controls consumer conversion at the point of pregnancy confirmation. Church & Dwight Co., Inc. competes aggressively in this segment where brand recognition drives selection.
- Hospital:Procurement departments specify integrated testing-supplement bundles rather than discrete categories.
- Direct Sales:Manufacturer-controlled channels bypass retail margin extraction for premium formulations.
Hospital channels retain volume leadership; online pharmacy holds the steepest expansion curve.
End User:
Application context determines whether purchasing authority rests with clinical decision-makers or consumer choice.
- Expectant Mothers:Primary demand source for both clinical and retail-accessible products. Bluetooth-enabled fetal monitors enable compliant low-risk cohorts to reduce in-person visit frequency by half.
- Healthcare Providers:Control formulary placement and diagnostic device specification. United States integrated delivery networks negotiate multi-year contracts linking NIPT laboratory services with vitamin allocations.
- Family Members:Secondary purchasers for gift and reassurance monitoring categories.
- Caregivers:Support purchasing for high-risk pregnancies requiring intensive monitoring.
Expectant mothers retain volume leadership; healthcare providers hold the steepest expansion curve.
Application:
Maturity gradients separate established reimbursement categories from emerging digital health positioning.
- Routine Check-ups:Traditional episodic care model faces fragmentation from continuous monitoring alternatives. Passive acoustic sensing technology now operates without gel coupling or operator training.
- Nutritional Support:Insurance-adjacent reimbursement positioning creates stable demand for folate-dosed formulations. Three suppliers control pharmaceutical-grade folic acid feedstock, exposing formulators to input cost volatility.
- Health Monitoring:Machine learning interpretation of fetal heart rate variability enables predictive gestational risk scoring.
- Education:Digital content delivery expands as health systems bundle nutritional counseling with standard obstetric care.
Nutritional support retains volume leadership; health monitoring holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital procurement commands pricing premiums through bundled formulary contracts, while Indian retail channels compete on unit economics for unbranded folate formulations. This asymmetry shapes regional investment priorities and margin structures across the gestational care continuum.
United States
Integrated delivery networks in Texas and California negotiate multi-year testing-supplement bundles that lock in recurring vitamin purchases. FDA premarket review pathways for fetal monitoring devices create compliance moats that favor established diagnostic manufacturers. Boston and San Francisco health systems deploy Bluetooth-enabled acoustic sensors for remote patient monitoring programs, reducing in-person visit frequency for low-risk cohorts.
Germany
EMA guidance on non-invasive prenatal screening mandates 99.9% analytical validation thresholds that consolidate laboratory vendor eligibility. REACH chemical safety protocols accelerate pharmaceutical-grade manufacturing investments for prenatal supplements. The Rhine-Ruhr and Bavarian industrial clusters host USP-certified dissolution facilities serving EU-wide hospital procurement networks.
China
NMPA medical device classification rules for fetal monitoring hardware create domestic preference in public hospital procurement. Three suppliers control pharmaceutical-grade folic acid feedstock, exposing formulators to input cost volatility. Shanghai and Shenzhen medical technology parks concentrate wearable monitor development for export-oriented manufacturers.
United Kingdom
National Health Service prenatal screening programs exclude providers lacking EMA-recognized quality management systems, compressing vendor eligibility to CAP-accredited laboratories. London and Manchester integrated care systems bundle nutritional counseling with standard obstetric care, creating stable demand for folate-dosed formulations. MHRA post-Brexit device regulations diverge from EU MDR timelines, complicating launch sequencing.
India
CDSCO medical device rules for fetal monitors create registration bottlenecks that delay commercialization for imported hardware. FSSAI fortification standards for maternal nutrition products enable domestic manufacturers to compete on cost in retail pharmacy channels. Maharashtra and Gujarat pharmaceutical clusters expand USP-certified prenatal supplement production for Middle East export markets.
Parents-In-Waiting: Global Prenatal Market Competitive Landscape
Concentration sits with diversified health science conglomerates that leverage diagnostic infrastructure to anchor integrated testing-supplement portfolios. The vendor base stratifies across three tiers: pharmaceutical-grade manufacturers with captive supply chains, retail-accessible wellness brands competing on pharmacy shelf presence, and diagnostic laboratories bundling NIPT services with nutritional allocations. Dominant competitive moves include backward integration into active pharmaceutical ingredient sourcing and strategic partnerships between wearable device developers and electronic health record platforms.
Among diversified nutrition and diagnostics conglomerates, Abbott and Nestlé exemplify scale-driven archetypes that control formulation standards and distribution infrastructure. Church & Dwight Co., Inc. occupies a position within the retail-accessible tier where brand recognition and pharmacy channel presence drive consumer conversion at pregnancy confirmation points. These three anchors illustrate the bifurcation between clinical-formulary and retail-consumer competitive arenas.
| Leading Market Players |
|---|
| Abbott |
| Church & Dwight Co., Inc. |
| Garden of Life |
| MegaFood |
| Country Life Vitamins |
| New Chapter |
| Nestlé |
| Clarins Group |
| Expanscience Laboratories |
| Others |
Value Network & Pricing Analysis
Ninety-day folic acid feedstock inventory buffers in pharmaceutical-grade manufacturing anchor pricing power for USP-certified formulators against boutique wellness competitors. This lead-time configuration concentrates procurement leverage among hospital systems bundling vitamins with NIPT services, while REACH compliance costs in Europe fragment supplier viability across certification tiers.
Pricing Analysis
The customization-premium spread between pharmaceutical-grade USP-certified formulations and retail-accessible standard vitamins runs wide in hospital procurement channels. Subscription-based recurring purchase models dominate integrated health system contracts, while per-unit transactional pricing prevails in retail pharmacy shelves where brand recognition commands conversion at pregnancy confirmation points. Price differentiation hinges on dissolution certification grade and captive supply chain integration. Cost compression in standard-tier supplements is intensifying because three suppliers control pharmaceutical-grade folic acid feedstock, exposing formulators to input volatility. Retail consumers exhibit highest price sensitivity; hospital pharmacy committees demonstrate lowest sensitivity due to bundled reimbursement positioning.
Supply Chain Analysis
Inventory concentration for pharmaceutical-grade active ingredients centers on China, India, and Germany, with 60-90 day coverage ratios typical for folic acid and DHA feedstocks. Raw material dependencies include omega-3 fatty acid concentrates, microencapsulated iron compounds, and USP-grade excipients. Single-source vulnerability in pharmaceutical-grade folic acid exposes formulators to supply interruption risk. Distribution runs through health system pharmacy and therapeutics committees for clinical-tier products, while retail pharmacy chains and direct-to-consumer subscription platforms handle consumer-accessible segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating within United States integrated delivery networks negotiating multi-year testing-supplement bundles, fragmenting pricing autonomy for standalone vitamin manufacturers.
For Market Incumbents: Compound formulary lock-in through backward integration into USP-certified dissolution capabilities and exclusive NIPT laboratory partnerships that bundle diagnostic workflows with nutritional allocations. Bluetooth-enabled wearable displacement of episodic ultrasound visits threatens hardware revenue pools; defend through AI-enhanced predictive risk scoring algorithms that require clinical interpretation. For New Entrants and Emerging Players: Differentiate on passive acoustic sensing convergence with Epic and Cerner EHR integration, targeting the home monitoring subscription white space where legacy device data streams lack standardized APIs. Direct-to-consumer channels in United States retail chains offer the most penetrable entry point, with pharmacy shelf presence at pregnancy confirmation enabling capture outside hospital formulary control. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue healthcare infrastructure play because gestational care demands continuous physiological monitoring compression of diagnostic-therapeutic loops. Acquisition targets should feature CAP-accredited laboratory infrastructure with sequenced-based NIPT workflows and EMA-recognized quality management systems. Watch FDA 510(k) clearance acceleration for fetal monitoring devices as inflection signal for hardware-plus-subscription model viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Sourcing | Captive folic acid supply secures margin stability against three-supplier concentration risk. |
| CE Marking Pathway Alignment | EU MDR harmonization reduces national registration fragmentation for fetal monitoring hardware. |
| Hospital System Partnership | United States integrated delivery networks bundle NIPT services with formulary-exclusive vitamin allocations. |
| Software Companion Development | Machine learning interpretation of fetal heart rate variability enables predictive gestational risk scoring. |
| Reimbursement Strategy | Insurance-adjacent positioning for prenatal supplements creates recurring purchase cycles resistant to generic erosion. |
Research Methodology
Operator-level perspectives from hospital pharmacy directors, GPO contracts managers, biomedical engineers, and formulary specialists anchored the qualitative base for this analysis. Primary interview findings triangulated against FDA 510(k) device clearances, EMA guidance documents on non-invasive prenatal screening, hospital procurement databases, and GPO contract disclosures. Bottom-up segmentation modeling and top-down macro trend validation converged on volume and value estimates.
Sensitivity analysis across product type, delivery mode, end user, and application dimensions shaped the analytical framework over the projection horizon. CAGRs derived from regression-weighted historical trajectory analysis and forward scenario stress-testing. Forecast inputs incorporated Bluetooth-enabled wearable adoption curves in United States integrated health systems and REACH chemical safety protocol compliance cost trajectories for European formulation manufacturing.
Material uncertainties — regulatory timeline revisions for FDA premarket review, EMA analytical validation threshold adjustments, and active pharmaceutical ingredient supply interruptions — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
North America Workplace Wellness Market
Personal Health
Sexual Wellness Market
Personal Health
Workplace Wellness Market
Personal Health
Biohacking Market
Personal Health
Reusable Face Mask Market
Personal Health
US Vaginal Moisturizers and Lubricants Market
Personal Health
Tongue Scraper Market
Personal Health
Global Health and Wellness Market
Personal Health
Patient Health Management Market
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Asia-Pacific Maternity & Personal Care Market
Personal Health
Europe Hair Loss Treatment Products Market
Personal Health
Global Weight Loss Services Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Jet Lag Therapy Market
Personal Health
Middle East and Africa Smoking Cessation and Nicotine De-Addiction Market