
 Metered Dose Inhalers Market | 2026-2036
Metered Dose Inhalers Market Size, Share, and Industry Trends Forecast 2026-2036
Metered Dose Inhalers Market Outlook
CE marking under the EU Medical Device Regulation is unwinding the competitive landscape for metered dose inhalers, forcing manufacturers to rebuild quality management systems and clinical evidence portfolios. GlaxoSmithKline leverages its vertically integrated respiratory franchise to sustain manufacturing scale across multiple active pharmaceutical ingredient and device combinations. AstraZeneca anchors its position through biologic-MDI combination platforms, while Boehringer Ingelheim competes via soft mist inhaler technology leadership.
A metered dose inhaler is a pressurized device that delivers a measured quantity of therapeutic aerosol, typically using hydrofluoroalkane propellants at 25-100 microliter volumes per actuation, for direct lung deposition in respiratory disease management. Pressurized MDIs retain the largest installed base among product types, though soft mist inhalers are capturing margin pools in severe asthma and COPD segments where lung deposition efficiency determines clinical outcomes. Rescue inhalers dominate volume throughput in the delivery mode dimension, while combination inhalers command premium positioning through fixed-dose corticosteroid-long-acting beta agonist formulations.
The FDA, EMA, and EPA collectively govern metered dose inhaler market access through bioequivalence standards, clinical trial design requirements, and propellant environmental phase-out mandates under the Kigali Amendment. These frameworks elevate R&D barriers for generic entrants while accelerating the transition from chlorofluorocarbon and hydrofluoroalkane propellants to lower-global-warming-potential alternatives. Stakeholders must monitor propellant transition timelines and device interoperability standards to secure supply continuity and formulary placement across regulated markets.
Market Dynamics
The transition from hydrofluoroalkane to hydrofluoroolefin propellants under the Kigali Amendment is restructuring manufacturing investments and supplier qualification timelines across the metered dose inhaler supply base.
Growth Catalysts
- Asthma prevalence in the United States:Elevated diagnostic rates and established reimbursement pathways sustain per-capita inhaler utilization above other developed markets.
- EU Medical Device Regulation:CE marking requirements for connected inhalers are accelerating device-digitization roadmaps among European manufacturers.
- Home care migration:Post-acute respiratory therapy is shifting from clinical settings to patient-administered regimens, expanding the addressable patient base for portable delivery systems.
Market Restraints
- Propellant supply concentration:Three chemical manufacturers control global hydrofluoroolefin feedstock output, creating single-source vulnerability for MDI formulators.
- Bioequivalence demonstration costs:FDA requirements for pharmacokinetic and pharmacodynamic bridging studies impose capital barriers that deter generic entrants.
- Soft mist inhaler substitution:Boehringer Ingelheim's Respimat platform captures severe asthma and COPD patients seeking superior lung deposition efficiency.
Strategic Opportunities
- India's respiratory disease burden:Underdiagnosed COPD prevalence in urban corridors creates first-mover advantage for affordable MDI platforms with local manufacturing.
- Connected inhaler ecosystems:Bluetooth-enabled dose counters paired with adherence analytics platforms open recurring revenue streams beyond hardware.
- Japan's aging demographic:METI incentives for geriatric-friendly device designs reward simplified actuation mechanisms and larger dose displays.
Industry Challenges
- Formulation scientist scarcity:Specialized expertise in suspension stability and particle engineering for pressurized systems commands premium compensation and extended hiring cycles.
- Legacy device interoperability:Proprietary valve and actuator geometries from incumbent suppliers complicate propellant-transition programs for second-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metered Dose Inhalers Market |
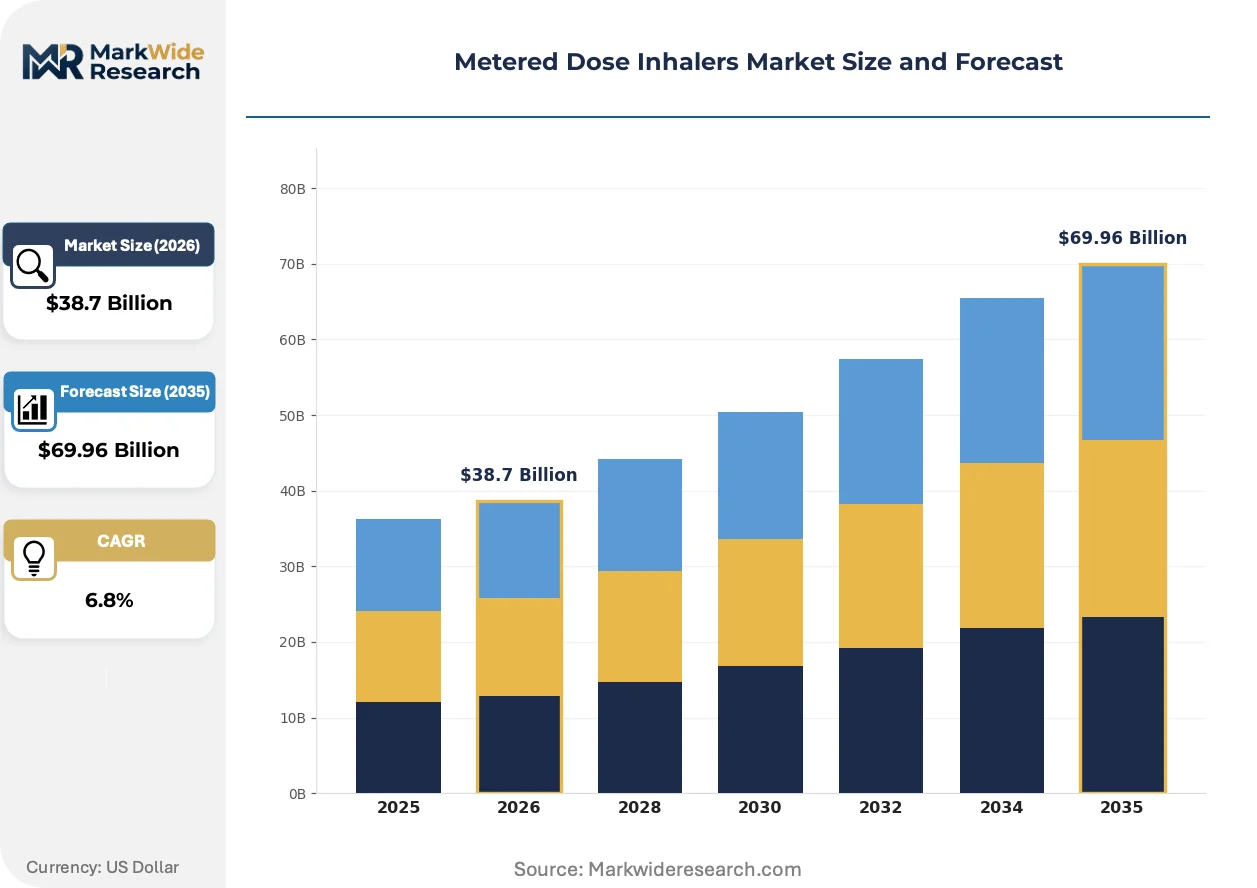
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressurized MDIs, Soft Mist Inhalers, Breath-Actuated Inhalers, Jet Nebulizers Delivery Mode: Rescue Inhalers, Maintenance Inhalers, Combination Inhalers, Children’s Inhalers End User: Hospitals, Clinics, Home Care, Pharmacies Therapy Area: Respiratory Diseases, Asthma, COPD, Allergies |
| Companies Covered | GlaxoSmithKline, AstraZeneca, Cipla, 3M, Beximco Pharmaceuticals, Teva Pharmaceuticals, Boehringer Ingelheim, H&T Presspart Manufacturing, MidasCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metered Dose Inhalers Market Strategic Shifts
Propellant chemistry, device connectivity, and patient-data monetization are converging to redefine competitive advantage in respiratory delivery systems.
Dry powder inhaler technology is supplanting conventional pressurized MDIs in maintenance therapy segments where corticosteroid sensitivity and dose consistency matter. Pulmonology practices in Germany and the United Kingdom are prioritizing DPI prescriptions for pediatric and geriatric cohorts. This transition is compressing R&D timelines for breath-actuated mechanisms while extending the commercial runway for hydrofluoroalkane-dependent rescue inhalers.
The EPA's hydrofluoroolefin approval pathway under the Significant New Alternatives Policy program is accelerating propellant-transition investments. Domestic manufacturers must reformulate existing products and resubmit stability data to maintain market authorization. Generic sponsors face the steepest compliance burden, as the FDA requires additional in-vitro and clinical bridging studies for propellant-switched reference products.
Pharmacy benefit managers are consolidating inhaler procurement around outcomes-linked contracts that tie formulary placement to adherence metrics. United States payers are piloting programs that reward manufacturers for sustained patient engagement rather than unit volume. This reconfiguration is most visible in Medicare Part D plans, where star-rating incentives align PBM and manufacturer interests around chronic disease management.
Metered Dose Inhalers Market Segmentation
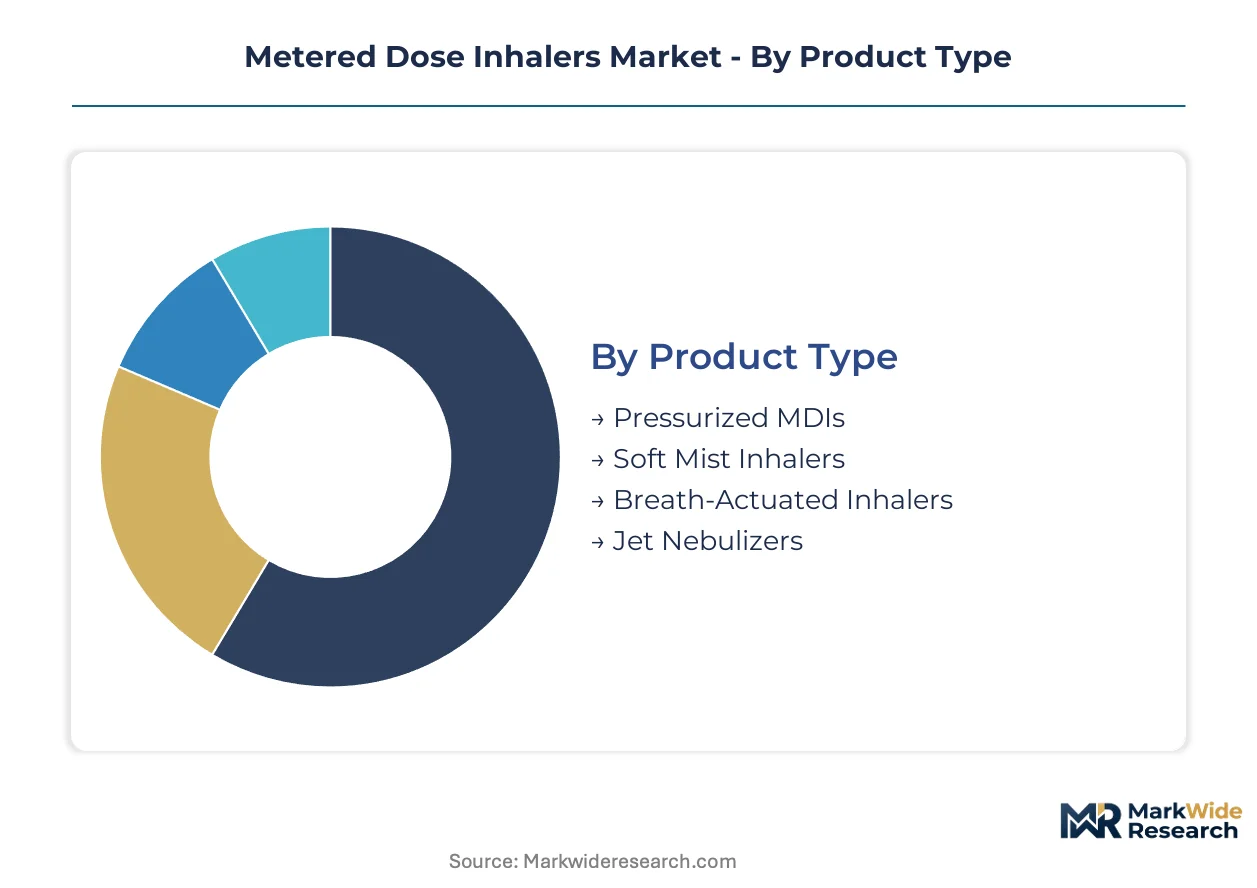
Segmentation in the metered dose inhalers market reveals divergent margin structures across device mechanics, clinical applications, and care settings. Manufacturers calibrate portfolio investments based on propellant transition costs, reimbursement tiering, and patient adherence economics.
Product Type:
Margin pools concentrate in propellant-based platforms where formulation expertise creates defendable positions against generic entry.
- Pressurized MDIs:Hydrofluoroalkane-propelled devices delivering 25-100 microliter aerosol volumes per actuation retain the largest installed base. Demand clusters in the United States rescue therapy segment, where rapid bronchodilation and compact form factors sustain per-capita utilization above European benchmarks despite environmental transition pressures.
- Soft Mist Inhalers:Mechanical energy systems generate slower-moving aerosol clouds with superior lung deposition efficiency. Germany's severe asthma and COPD cohorts drive adoption, as pulmonology practices prioritize deposition metrics over device cost in reimbursement decisions.
- Breath-Actuated Inhalers:Trigger mechanisms coordinate aerosol release with patient inspiration, reducing oropharyngeal deposition.
- Jet Nebulizers:Compressor-driven systems convert liquid formulations into respirable droplets for patients unable to coordinate inhalation.
The dominant share belongs to Pressurized MDIs, while Soft Mist Inhalers are gaining share fastest.
Delivery Mode:
Volume throughput and pricing power split sharply between acute rescue applications and chronic maintenance regimens.
- Rescue Inhalers:Short-acting beta agonist formulations address acute bronchospasm with immediate onset requirements. United States pharmacy benefit managers process rescue inhalers at volumes exceeding maintenance therapies threefold, though per-unit margins compress under generic albuterol competition.
- Combination Inhalers:Fixed-dose corticosteroid-long-acting beta agonist platforms command premium positioning through once-daily convenience and adherence-linked outcomes contracts. Medicare Part D star-rating incentives align manufacturer and payer interests around sustained patient engagement.
- Maintenance Inhalers:Long-acting bronchodilator monotherapies stabilize chronic respiratory conditions through scheduled dosing.
- Children's Inhalers:Spacer-compatible designs and dose counters accommodate pediatric coordination limitations and caregiver oversight needs.
Rescue Inhalers process the highest unit volumes, yet Combination Inhalers capture the steepest expansion trajectory as payers shift toward outcomes-based procurement.
End User:
Care setting determines device complexity requirements, reimbursement pathways, and patient training investment levels.
- Home Care:Self-administered respiratory therapy is expanding the addressable patient base for portable delivery systems. Post-acute migration from hospitals to home settings in the United States and United Kingdom accelerates demand for connected inhalers with adherence analytics.
- Hospitals:Acute care facilities require nebulizer-compatible and high-dose emergency formulations for severe exacerbations.
- Clinics:Pulmonology and allergy practices serve as prescription gatekeepers for maintenance therapy initiation.
- Pharmacies:Retail dispensing channels handle the majority of rescue inhaler fulfillment with limited clinical intervention.
Home Care is expanding most quickly, while Hospitals retain the highest per-patient device expenditure.
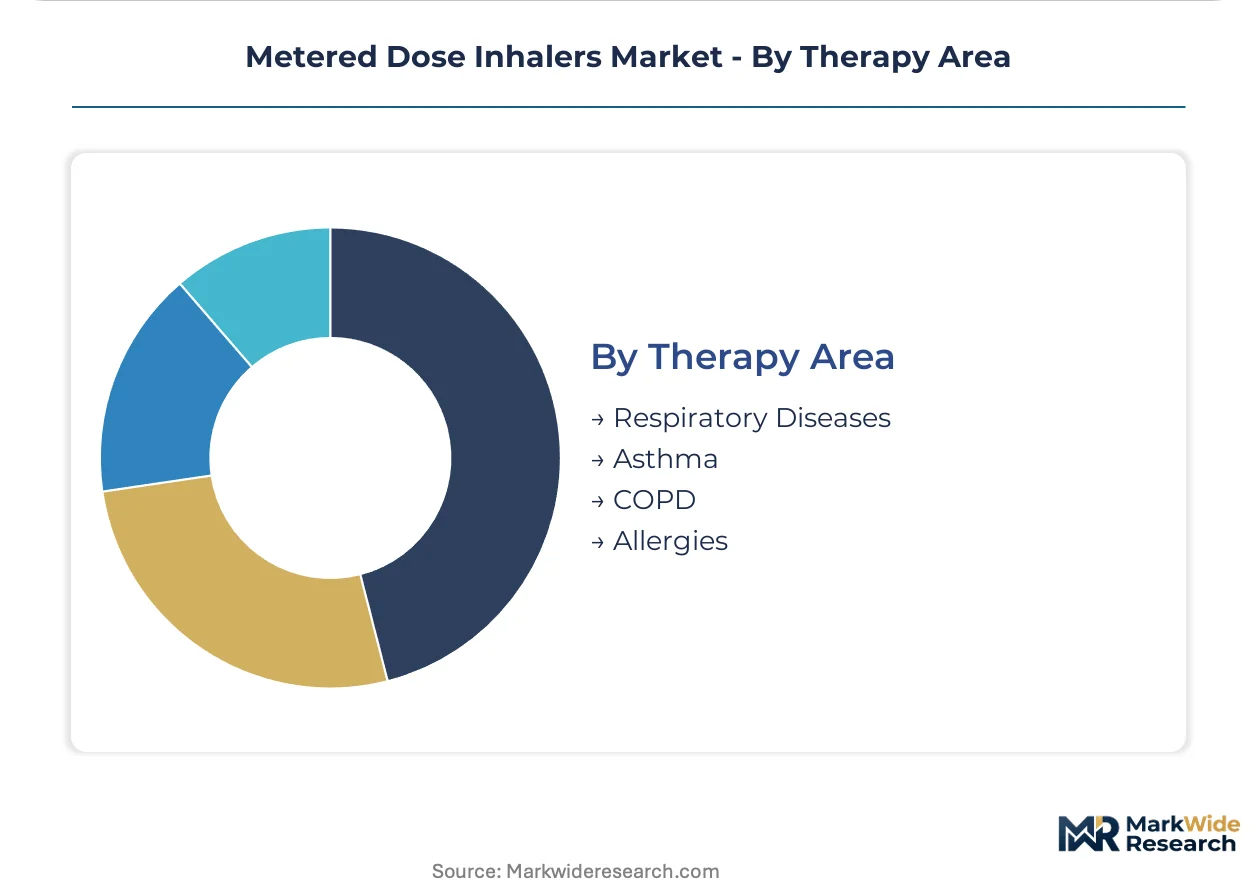
Therapy Area:
Disease prevalence, diagnostic penetration, and treatment guideline stringency reshape segment attractiveness across respiratory conditions.
- Asthma:Chronic inflammatory airway disease with established diagnostic criteria and stepwise treatment algorithms. United States pediatric and adolescent prevalence sustains rescue inhaler demand, while biologic-eligible severe asthma shifts maintenance therapy toward combination platforms.
- COPD:Progressive airflow limitation with underdiagnosed prevalence in India's urban corridors and Japan's aging demographic. Smoking cessation programs and exacerbation prevention drive maintenance inhaler adherence in reimbursed markets.
- Respiratory Diseases:Broad category encompassing interstitial lung disease, pulmonary fibrosis, and other non-asthma non-COPD conditions.
- Allergies:Seasonal and perennial allergic rhinitis with overlapping pharmaceutical procurement channels.
Asthma maintains the largest patient base, though COPD is climbing the fastest as diagnostic penetration improves in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical cold-chain infrastructure underwrites European distribution for hydrofluoroalkane and hydrofluoroolefin propellant feedstocks. This logistics backbone positions the Netherlands as a transit hub for MDI components bound for formulation sites across the continent.
United States
FDA's bioequivalence guidance for generic MDIs sustains elevated R&D barriers that protect incumbent formulators. The EPA's Significant New Alternatives Policy program mandates hydrofluoroolefin transition timelines that compress reformulation windows. Research Triangle Park in North Carolina hosts device engineering clusters where connected inhaler startups partner with contract manufacturers.
Germany
Pulmonology practices in Bavaria and Baden-Württemberg prioritize soft mist inhaler prescriptions for severe COPD cohorts seeking superior lung deposition. EMA's Medical Device Regulation CE marking requirements force manufacturers to rebuild quality management systems for connected devices. Frankfurt's chemical manufacturing corridor supplies hydrofluoroolefin propellants to European MDI formulators.
India
Underdiagnosed COPD prevalence in Maharashtra and Gujarat's urban corridors creates demand for affordable pressurized MDI platforms. CDSCO's streamlined approval pathways for locally manufactured respiratory devices accelerate market entry for domestic sponsors. Hyderabad's formulation science clusters specialize in suspension stability engineering for generic albuterol products.
Japan
METI incentives for geriatric-friendly device designs reward simplified actuation mechanisms and larger dose displays. PMDA's adherence to ICH guidelines ensures clinical trial data portability for multinational sponsors. Osaka's precision manufacturing belt produces valve and actuator components for Asia-Pacific MDI assembly.
United Kingdom
NHS England's outcomes-based procurement pilots tie inhaler formulary placement to real-world adherence metrics. MHRA's post-Brexit regulatory autonomy permits divergence from EMA timelines on propellant transition deadlines. Cambridge's medtech corridor hosts connected inhaler developers integrating Bluetooth dose counters with digital health platforms.
Metered Dose Inhalers Market Competitive Environment
Listed leaders compete with private specialists across formulation expertise and device engineering dimensions. The market structure concentrates around vertically integrated respiratory franchises that control active pharmaceutical ingredient supply, device manufacturing, and distribution networks. Three archetypes dominate: multinational pharmaceutical conglomerates with respiratory divisions, specialized inhalation device engineers, and generic pharmaceutical sponsors with regional manufacturing scale. Capacity expansion and technology licensing represent the dominant competitive moves as players position for hydrofluoroolefin transition timelines.
Among UK-based pharmaceutical conglomerates, GlaxoSmithKline occupies a position exemplifying vertically integrated respiratory franchise scale across multiple propellant and device combinations. AstraZeneca, also UK-based, represents the biologic-MDI combination platform archetype. India's Cipla anchors the generic specialist tier with regional manufacturing scale serving price-sensitive emerging markets.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| AstraZeneca |
| Cipla |
| 3M |
| Beximco Pharmaceuticals |
| Teva Pharmaceuticals |
| Boehringer Ingelheim |
| H&T Presspart Manufacturing |
| MidasCare |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at propellant manufacturing facilities in Germany, the United States, and China shapes both supply concentration and price floors for metered dose inhaler components. High minimum efficient scale for hydrofluoroolefin synthesis creates barriers that sustain incumbent chemical manufacturers' pricing power while compressing margins for second-tier device assemblers.
Pricing Analysis
Certification level (FDA-grade, CE-marked MDR, ISO 13485) creates the primary spread between premium and standard inhaler tiers. Pricing stratifies across connected devices with adherence analytics, conventional pressurized MDIs, and economy generic rescue inhalers. Cost compression in the generic albuterol segment is intensifying because pharmacy benefit managers consolidate procurement around outcomes-linked contracts. Pediatric and geriatric caregivers show highest price sensitivity, while severe asthma and COPD patients prioritize lung deposition efficiency over unit cost.
Supply Chain Analysis
Inventory lead times for valve and actuator components extend 16-24 weeks due to proprietary geometries from incumbent suppliers. Manufacturing concentrates in Germany, the United States, and India for device assembly, with propellant feedstock anchored in China's chemical corridor and the US Gulf Coast. Formulation stability rests on hydrofluoroolefin supply from three qualified chemical manufacturers, creating single-source vulnerability. Distribution runs through pharmaceutical cold-chain hubs including Rotterdam for European formulation sites and direct manufacturer-to-wholesaler arrangements in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metered dose inhalers market is entering a cyclical recovery phase as propellant transition investments peak and connected device adoption accelerates through Medicare Part D star-rating incentives.
For Market Incumbents: Compound manufacturing scale advantages by securing long-term hydrofluoroolefin offtake agreements with German and US chemical suppliers before capacity constraints tighten. Deepen backward integration into valve and actuator production to insulate against proprietary geometry licensing costs from legacy component suppliers. Prioritize FDA bioequivalence dossier investments for propellant-switched reference products to defend against generic entrants.
For New Entrants and Emerging Players: Anchor in India's underdiagnosed COPD corridors where CDSCO's streamlined approval pathways reward locally manufactured affordable platforms. Target connected inhaler ecosystems with Bluetooth-enabled dose counters paired with adherence analytics, as pharmacy benefit managers pilot outcomes-based procurement that rewards patient engagement metrics. Pursue hospital system partnerships in Japan leveraging METI incentives for geriatric-friendly device designs.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized inhalation device engineers with formulation science capabilities and propellant-transition readiness. Long-term viability over the next decade hinges on capturing recurring revenue from connected inhaler data platforms rather than hardware margins alone. Monitor FDA bioequivalence guidance revisions as the primary inflection indicator for generic entry timing and incumbent pricing power erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks connected device revenue streams across European reimbursement markets. |
| Backward Integration into Propellant Supply | Captive hydrofluoroolefin sourcing insulates against three-supplier concentration risk in chemical feedstocks. |
| Hospital System Partnership | Pulmonology practice alliances secure maintenance therapy formulary placement and real-world adherence data. |
| Software Companion Development | Bluetooth dose counters paired with adherence analytics enable outcomes-linked contracting with pharmacy benefit managers. |
| Reimbursement Strategy | Medicare Part D star-rating alignment transforms inhaler procurement from unit volume to patient engagement metrics. |
Study Parameters
Desk research of FDA bioequivalence guidance documents, EPA Significant New Alternatives Policy filings, and EMA Medical Device Regulation technical standards preceded structured interviews with respiratory device engineering leads, pulmonology practice administrators, pharmacy benefit manager formulary directors, and generic pharmaceutical regulatory affairs specialists. Secondary validation drew from CMS Medicare Part D utilization data, hospital procurement databases, and chemical industry capacity disclosures. Bottom-up patient population modeling and top-down manufacturer revenue triangulation cross-checked segment estimates.
Variance decomposition across product type, delivery mode, end user setting, and therapy area dimensions structured the analytical framework over the projection horizon. CAGRs derived from segmented patient population growth, per-capita utilization trends, and pricing trajectory assumptions. Forecast inputs incorporated propellant transition timelines under the Kigali Amendment, connected device adoption curves, and reimbursement policy shifts toward outcomes-based procurement.
Decision-makers should treat outputs as directional under assumptions of stable regulatory timelines for hydrofluoroolefin approval and continued pharmacy benefit manager consolidation; material deviation in propellant supply availability or FDA bioequivalence stringency would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Therapy
Chronic Obstructive Pulmonary Disease Treatment Market
Respiratory Therapy
Compression Therapy Market
Respiratory Therapy
Lung (Pulmonary) Airway Disease Treatment Market
Respiratory Therapy
Pleural Effusion Treatment Market
Respiratory Therapy
Global Pneumonia Therapeutics Market
Respiratory Therapy
Oscillating Positive Expiratory Pressure (OPEP) Devices Market
Respiratory Therapy
Global Acute Respiratory Distress Syndrome (ARDS) Treatment Market
Respiratory Therapy
Emphysema Treatment Market
Respiratory Therapy
Respiratory Antiviral Treatment Market
Respiratory Therapy
Pulmonary Fibrosis Treatment Market
Respiratory Therapy
Pediatric Respiratory Syncytial Virus Infection Market
Respiratory Therapy
Croup Treatment Market
Respiratory Therapy
Diaphragm Pacing Therapy System Market
Respiratory Therapy
Alpha-1 Antitrypsin Deficiency (AATD) Augmentation Therapy Market
Respiratory Therapy
Bronchial Thermoplasty Market
Respiratory Therapy
Interventional Pulmonology Market