
 Fluidics for Preclinical Market | 2026-2036
Fluidics for Preclinical Market Size, Share, and Industry Trends Forecast 2026-2036
Fluidics for Preclinical Market Foresight
Market Context
Biotech firms is realigning procurement priorities toward integrated lab platforms for high-throughput toxicology studies. Thermo Fisher Scientific dominates bench-top device distribution through its extensive service infrastructure. PerkinElmer differentiates with specialized flow controllers calibrated for cell analysis workflows. Harvard Bioscience anchors the research institute channel with modular pump systems designed for protocol flexibility.
Technical Definition and Segment Structure
Fluidics for preclinical research encompasses precision liquid handling systems—typically operating at microliter-to-nanoliter scales with pressure ranges from 0.1 to 10 bar—that enable controlled reagent delivery in drug candidate evaluation before human trials. Microfluidic chips capture the largest margin pool due to fabrication complexity and disposable revenue models, while flow controllers represent the fastest-growing product category as laboratories automate protocol standardization. Among end users, contract research organizations are expanding capacity fastest, though pharmaceutical companies sustain the highest absolute spending on validated portable systems for multi-site studies.
Regulatory Frame and Outlook
The FDA enforces GLP standards for preclinical fluidic data used in IND submissions, while the EMA's MDR alignment pressures European labs to upgrade traceability features on legacy equipment. ISO 13485 certification is becoming a de facto gate for supplier qualification at tier-one pharmaceutical buyers. Stakeholders must monitor how evolving EPA substance-handling rules affect sensor material specifications in North American installations.
Market Dynamics
Microfluidic chip fabrication is consolidating around polymer-based manufacturing as academic labs and CROs demand disposable platforms that eliminate cross-contamination risks in high-throughput screening workflows.
Growth Catalysts
- NIH Funding Concentration:United States research institutes channel federal grants into automated liquid handling infrastructure for precision medicine initiatives.
- EMA MDR Alignment:European laboratories face mandatory equipment traceability upgrades that accelerate replacement cycles for legacy pump systems.
- Organ-on-Chip Maturation:Biotech firms integrate microphysiological systems into toxicology pipelines to reduce animal model dependency.
Market Restraints
- PDMS Material Volatility:Silicone precursor costs fluctuate with semiconductor sector demand, squeezing margins for chip fabricators.
- ISO 13485 Certification Burden:Small European suppliers struggle with quality management system implementation timelines required by tier-one pharmaceutical buyers.
- Optical Detection Substitution:Label-free biosensor platforms threaten fluorescence-based microfluidic readout market share in certain biomarker applications.
Strategic Opportunities
- India CRO Expansion:Contract research organizations in Hyderabad and Bangalore seek validated fluidic platforms for Western pharmaceutical outsourcing contracts.
- AI-Integrated Flow Control:Machine learning algorithms enable real-time droplet manipulation for single-cell analysis workflows.
- EPA Green Chemistry Incentives:Reduced solvent consumption through microfluidic miniaturization qualifies North American labs for federal sustainability credits.
Industry Challenges
- Mechatronics Talent Scarcity:Precision pump engineering requires rare cross-training in fluid mechanics and embedded systems programming.
- GLP Validation Timelines:FDA documentation requirements for 21 CFR Part 11 compliance extend equipment commissioning by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluidics for Preclinical Market |
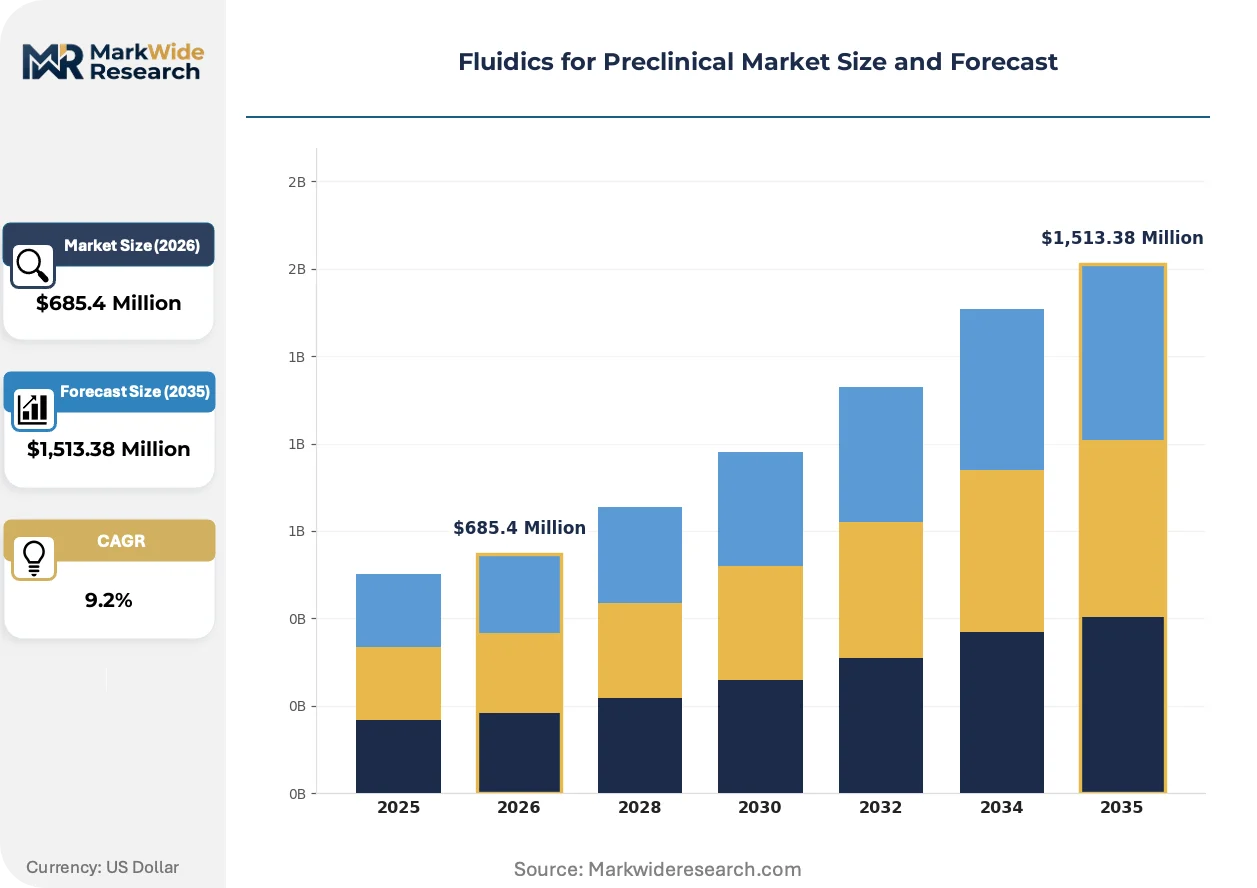
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Chips, Flow Controllers, Pumps, Valves, Sensors Application: Drug Screening, Toxicology Studies, Biomarker Detection, Cell Analysis End User: Pharmaceutical Companies, Biotech Firms, Research Institutes, Contract Research Organizations Deployment Model: Bench-top Devices, Portable Systems, Integrated Lab Platforms, Modular Units |
| Companies Covered | Fluigent SA, Halma Plc, Thermo Fisher Scientific Inc, PerkinElmer Inc, IDEX Corp, Harvard Bioscience Inc, Blacktrace Holdings Ltd, Agilent Technologies, AMETEK Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluidics for Preclinical Market Shifts & Advancements
Digital microfluidics is redefining protocol flexibility through electrowetting-on-dielectric platforms that eliminate fixed-channel architectures. This shift compresses assay development cycles and opens new service revenue models.
Electrowetting-on-dielectric chips manipulate discrete droplets through voltage-controlled surface tension modulation. Top-ten pharmaceutical manufacturers are absorbing this technology into central nervous system drug screening programs. The approach is absorbing market share from traditional continuous-flow designs by enabling mid-assay reagent reconfiguration without hardware replacement.
REACH substance restrictions on perfluorinated compounds are forcing material substitutions in hydrophobic chip coatings. German and French laboratories now specify fluoropolymer alternatives in procurement tenders. Microfluidic foundries in Switzerland and the Netherlands are responding with plasma-deposited coating processes that maintain droplet mobility without restricted chemistries.
Equipment leasing structures are displacing capital purchase models among mid-size biotechnology firms. Third-party service providers in Massachusetts and California now bundle maintenance, calibration, and consumable replenishment into per-sample pricing. This transformation is most advanced in gene therapy development verticals where assay volumes remain unpredictable through clinical candidate selection phases.
Fluidics for Preclinical Market Segmentation
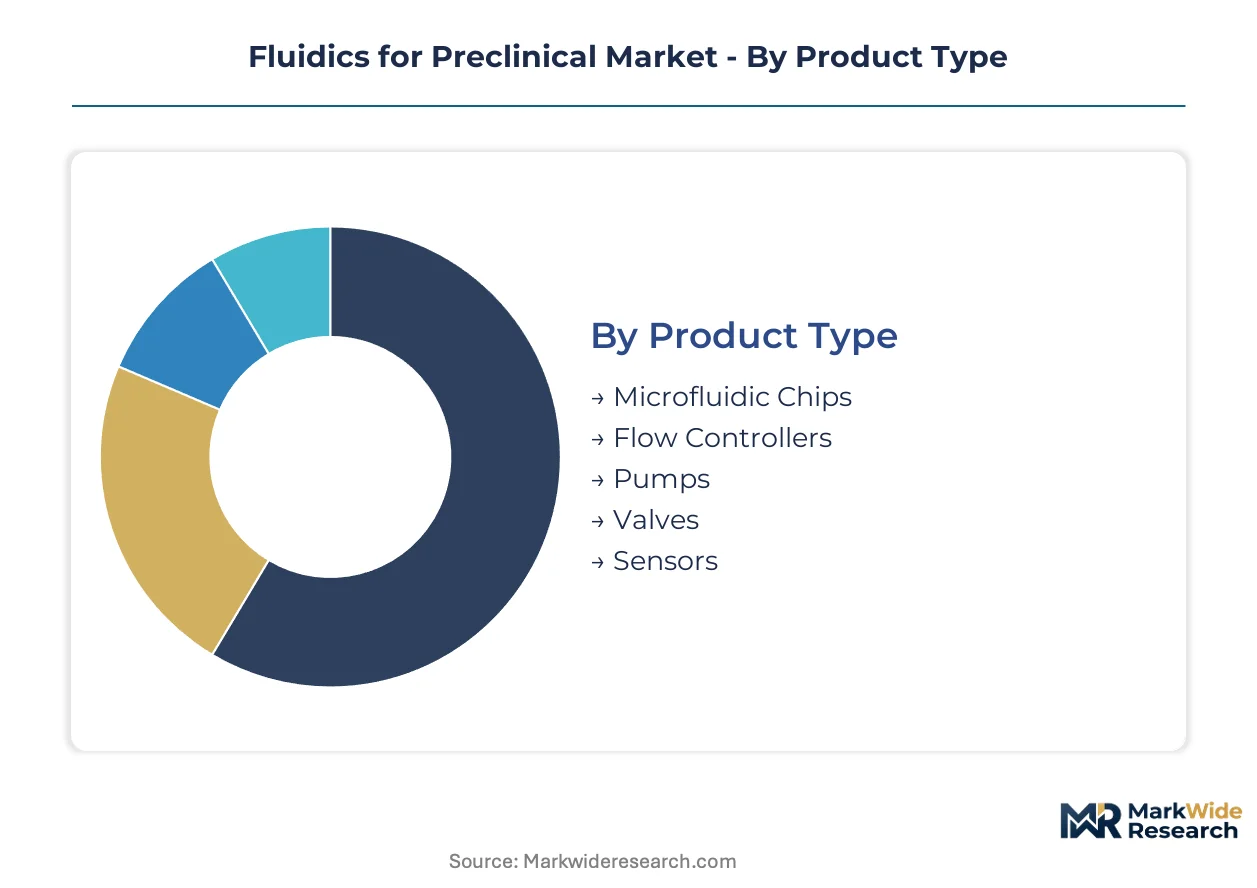
Fluidics for preclinical research fragments across product architectures, scientific workflows, and procurement models. Each dimension carries distinct margin profiles and regulatory burdens that reshape vendor positioning.
Product Type:
Volume concentration sits with disposable consumables, while premium capture gravitates toward precision control instrumentation.
- Microfluidic Chips:Polymer-based substrates with embedded channel networks (10-500 µm width) enable parallel reaction containment. Pharmaceutical toxicology programs in Massachusetts and New Jersey drive procurement for organ-on-chip compatibility.
- Flow Controllers:Piezoelectric or thermal mass flow modules regulate reagent delivery at 0.1-1000 µL/min precision. Biotech firms automating biomarker detection workflows represent the steepest expansion trajectory for multi-channel units with programmable pressure profiles.
- Pumps:Syringe and peristaltic architectures dominate legacy installations.
- Valves:Solenoid and pneumatic actuators manage fluid routing in high-throughput screening lines.
- Sensors:Optical and electrochemical detection elements integrate at chip outlets for real-time readout.
Mature deployment sits with Pumps. Newer deployment is concentrated in Flow Controllers.
Application:
Regulatory stringency varies sharply across therapeutic validation stages, with IND-enabling studies demanding the most rigorous instrumentation documentation.
- Drug Screening:High-throughput compound libraries against cellular targets require 384-well microfluidic parallelism. Contract research organizations in Hyderabad and Bangalore absorb capacity for Western pharmaceutical outsourcing contracts.
- Toxicology Studies:Organ-on-chip and microphysiological systems model organ-level responses to reduce animal model dependency. FDA GLP standards for preclinical fluidic data tighten validation requirements for multi-parameter monitoring.
- Biomarker Detection:Circulating nucleic acid and protein quantification workflows.
- Cell Analysis:Single-cell encapsulation and sorting applications.
Revenue concentration clusters in Drug Screening. Capability investment is accelerating fastest in Toxicology Studies.
End User:
Procurement authority splits between centralized pharmaceutical capital committees and distributed biotech technical buyers with grant-funded flexibility.
- Pharmaceutical Companies:Multi-site validation protocols demand portable systems with synchronized calibration certificates. Tier-one buyers now mandate ISO 13485 certification as a de facto supplier qualification gate.
- Biotech Firms:Venture-backed development programs prioritize modular architectures that scale from discovery into IND-enabling phases without hardware replacement.
- Research Institutes:NIH-funded precision medicine initiatives anchor early-stage adoption in the United States.
- Contract Research Organizations:Capacity expansion for Western outsourcing contracts drives platform standardization.
Absolute spending leadership rests with Pharmaceutical Companies. Procurement velocity is climbing fastest among Contract Research Organizations.
Deployment Model:
Capital constraints and assay volume uncertainty are compressing ownership models toward operational expenditure structures.
- Bench-top Devices:Self-contained units for individual investigator labs dominate academic procurement. Thermo Fisher Scientific's service infrastructure anchors distribution through direct field support.
- Portable Systems:Battery-powered or lightweight units enable multi-site study consistency. EMA MDR alignment pressures European laboratories to upgrade traceability features on legacy equipment, accelerating replacement demand.
- Integrated Lab Platforms:Robotic liquid handling with LIMS connectivity.
- Modular Units:Protocol-flexible pump and sensor configurations.
Installed base dominance belongs to Bench-top Devices. Contract structure innovation is concentrating in Portable Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of precision fluidic components clusters in Switzerland and the Netherlands, while consumption concentrates in United States research institutes and German pharmaceutical manufacturing corridors. This geographic split creates specialized trade flows in validated instrumentation and disposable chip architectures.
United States
NIH-funded precision medicine initiatives drive procurement of automated liquid handling infrastructure across Massachusetts and New Jersey pharmaceutical corridors. FDA GLP standards for preclinical fluidic data tighten validation requirements for IND-enabling studies. Greater Boston anchors early-stage adoption through Harvard-affiliated research institutes and venture-backed biotech development programs.
Germany
EMA MDR alignment pressures laboratories to upgrade traceability features on legacy pump systems, accelerating replacement cycles. REACH substance restrictions on perfluorinated compounds force material substitutions in hydrophobic chip coatings. Microfluidic foundries in Baden-Württemberg respond with plasma-deposited coating processes that maintain droplet mobility without restricted chemistries.
Switzerland
Swissmedic certification requirements elevate quality management system implementation as a supplier qualification gate for tier-one pharmaceutical buyers. Precision manufacturing heritage supports fabrication of polymer-based microfluidic substrates with embedded channel networks. Basel and Zurich industrial clusters specialize in modular pump systems designed for protocol flexibility in toxicology workflows.
India
Contract research organizations in Hyderabad and Bangalore absorb capacity expansion for Western pharmaceutical outsourcing contracts. CDSCO alignment with international GLP standards drives platform standardization requirements. The Telangana life sciences corridor attracts validated fluidic platform procurement for gene therapy development verticals.
Netherlands
Eindhoven Region microfluidic foundries consolidate polymer-based manufacturing as academic labs demand disposable platforms eliminating cross-contamination risks. EU Green Deal incentives qualify microfluidic miniaturization for reduced solvent consumption credits. Amsterdam and Rotterdam logistics infrastructure supports distribution of precision flow controllers calibrated for cell analysis workflows.
Fluidics for Preclinical Market Competitive Landscape
Top-tier vendors anchor pharmaceutical and biotech procurement channels, while mid-tier specialists capture academic and CRO segments through modular architectures. The vendor base stratifies across integrated laboratory platform providers, precision component fabricators, and consumable-focused chip manufacturers. Three archetypes dominate: full-service distributors with extensive field infrastructure, specialized flow control engineers, and disposable substrate foundries. Competitive moves concentrate on strategic partnerships for regulatory compliance bundling and technology licensing for electrowetting-on-dielectric platforms.
Among precision instrumentation providers, Thermo Fisher Scientific Inc and PerkinElmer Inc exemplify the integrated platform archetype, while Harvard Bioscience Inc occupies a position within the modular research equipment tier. These entities represent contrasting approaches to channel strategy—direct field service infrastructure versus specialized workflow calibration—without implying specific market share positions or recent strategic actions.
| Leading Market Players |
|---|
| Fluigent SA |
| Halma Plc |
| Thermo Fisher Scientific Inc |
| PerkinElmer Inc |
| IDEX Corp |
| Harvard Bioscience Inc |
| Blacktrace Holdings Ltd |
| Agilent Technologies |
| AMETEK Inc |
| Others |
Supply & Pricing Matrix
Tier-one pharmaceutical procurement committees concentrate purchasing authority for validated fluidic systems, enforcing contract-based long-term offtake structures that bundle hardware, consumables, and calibration services into per-sample operational expenditure models. This buyer concentration shifts pricing power toward vendors with ISO 13485 certification and multi-site service infrastructure.
Pricing Analysis
Margin tightening in precision flow controllers reflects PDMS precursor cost volatility tied to semiconductor sector demand cycles. Three-tier pricing structure across premium, standard, and economy levels stratifies by validation grade and after-sales bundling intensity. Cost-down pressure on disposable microfluidic chips accelerates because contract research organizations in India negotiate volume-scale discounts for Western outsourcing contracts. Biotech firms with grant-funded flexibility exhibit highest price sensitivity, while pharmaceutical quality assurance departments prioritize certification tier over unit cost.
Supply Chain Analysis
ISO 13485 certification gates supplier qualification for tier-one pharmaceutical buyers, concentrating component sourcing on Swiss and Dutch precision manufacturing clusters. Polymer substrate fabrication draws from German chemical feedstock suppliers and specialized photolithography equipment anchored in Japanese and Dutch capital goods sectors. Single-source vulnerability in piezoelectric actuator supply creates exposure to logistics chokepoints through Rotterdam and Hamburg port infrastructure. Distribution runs through direct field service networks for bench-top devices and third-party leasing platforms for portable systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital microfluidics platforms are displacing fixed-channel continuous-flow architectures across toxicology and biomarker detection workflows, compressing assay development cycles and opening subscription revenue models.
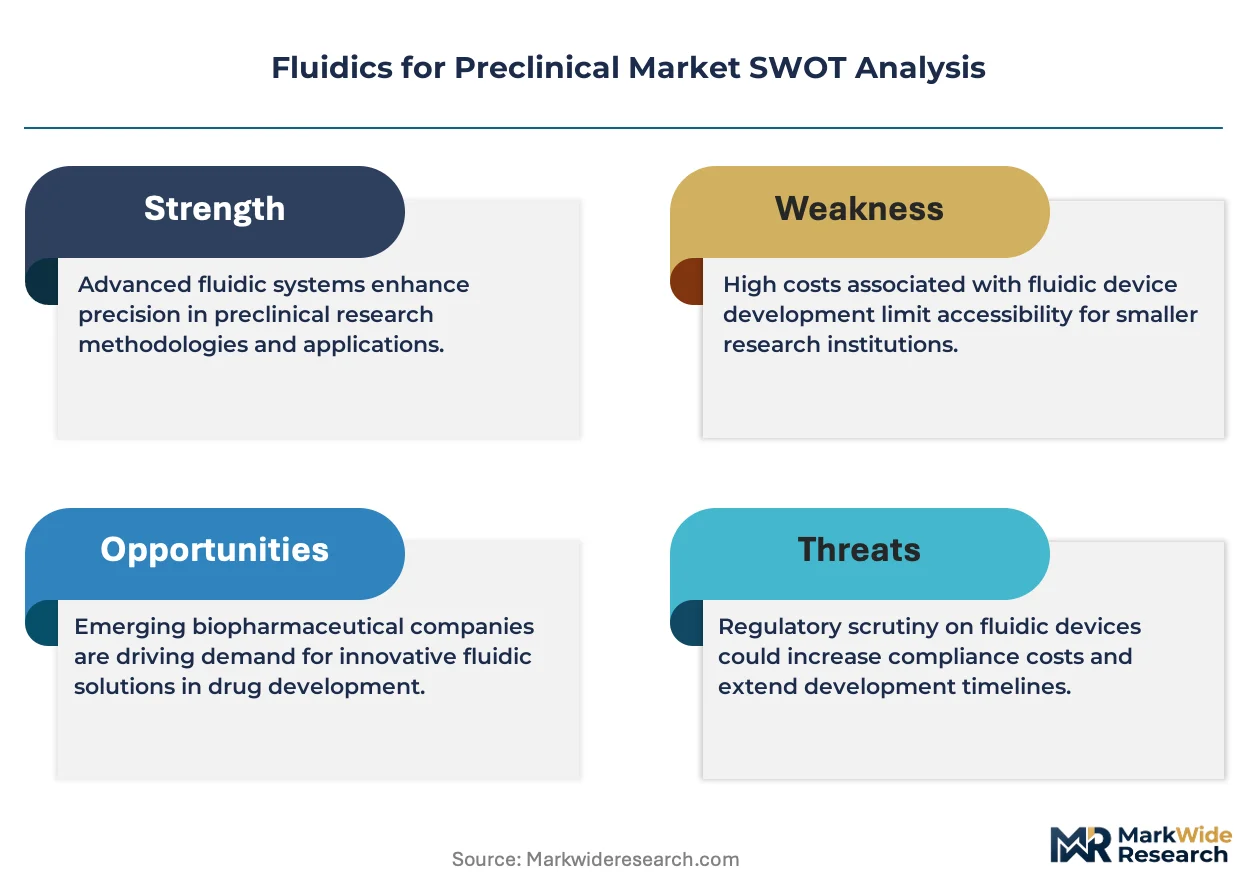
For Market Incumbents: Lock in multi-year service contracts with pharmaceutical quality assurance departments before electrowetting-on-dielectric platforms achieve GLP validation status. Deepen backward integration into polymer substrate fabrication to capture disposable chip margins and insulate against PDMS cost volatility. Prioritize certification investment in Swissmedic and FDA 21 CFR Part 11 compliance to maintain procurement gatekeeping position. For New Entrants and Emerging Players: Mid-size biotechnology firms with unpredictable assay volumes represent the most penetrable buyer archetype for equipment-as-a-service offerings. Enter through Massachusetts and California gene therapy development clusters where leasing structures displace capital purchases. Deploy AI-integrated flow control as a differentiated go-to-market angle for single-cell analysis workflows. For Investors and Strategic Acquirers: The window for entry favors modular pump system specialists with protocol-flexible architectures and established research institute channel relationships. Long-term viability hinges on regulatory compliance bundling capabilities across FDA, EMA, and Swissmedic jurisdictions. Watch for CDSCO alignment with international GLP standards as the inflection indicator for India CRO platform standardization demand.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Bundling | Integrated FDA, EMA, and Swissmedic validation packages accelerate pharmaceutical procurement cycles. |
| Electrowetting-on-Dielectric Licensing | Technology partnerships with top-ten pharmaceutical manufacturers expand central nervous system drug screening deployment. |
| India CRO Capacity Partnership | Validated platform deployment in Hyderabad and Bangalore captures Western pharmaceutical outsourcing contract flow. |
| Consumable-Plus-Service Integration | Per-sample pricing models align vendor revenue with biotech assay volume uncertainty through clinical candidate phases. |
| Plasma-Deposited Coating Development | Fluoropolymer alternatives to REACH-restricted perfluorinated compounds maintain German and French laboratory procurement eligibility. |
Research Methodology
Multi-period observation of NIH funding disbursement patterns, FDA 510(k) and IND submission volumes, and EMA MDR implementation timelines anchored the trend analysis, supplemented by interviews with microfluidic platform engineering directors, pharmaceutical regulatory affairs leads, contract research organization procurement managers, and precision manufacturing plant managers. Secondary validation drew from FDA GLP inspection records, Swissmedic certification databases, ECHA REACH substance restriction notices, and SEC filings of publicly traded laboratory instrumentation providers. Bottom-up segment sizing triangulated against top-down industry expenditure estimates.
The input-output matrix framed demand drivers against supply-side capacity constraints across product architecture, scientific workflow, and procurement model dimensions. Modeled segmentation spanned microfluidic chips, flow controllers, pumps, valves, and sensors by application in drug screening, toxicology studies, biomarker detection, and cell analysis, with end-user stratification across pharmaceutical companies, biotech firms, research institutes, and contract research organizations. CAGRs derived from regression analysis of historical procurement patterns against regulatory milestone schedules and funding authorization trajectories. Forecast inputs incorporated organ-on-chip technology maturation curves and EPA green chemistry incentive program uptake rates.
Revisions become necessary when FDA guidance on preclinical fluidic data requirements shifts, EMA MDR enforcement intensity changes, or PDMS precursor supply disruptions exceed historical volatility bands. A model refresh is warranted upon material change in NIH precision medicine initiative funding levels or CDSCO GLP alignment implementation pace.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Surgical Tourniquets Market
Medical Devices
Europe Organ-On-Chip Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Cervical Spine System Market
Medical Devices
3D Surgical Microscope Systems Market
Medical Devices
Global Nebuliser Market
Medical Devices
Gastroretentive Drug Delivery Systems Market
Medical Devices
Global Artificial Pancreas Device System Market
Medical Devices
Global Pneumatic Tourniquets Market
Medical Devices
South Korea Artificial Organs and Bionics Market
Medical Devices
Microdebrider Market
Medical Devices
South Africa Neurology Devices Market
Medical Devices
Wireless Surgical Cameras Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Pneumology Digital Stethoscope Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market