
 Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market | 2026-2036
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market Insights
Japanese sensor foundries is recalibrating output priorities toward photodetector arrays for photoacoustic and optical imaging platforms. GE Healthcare leverages captive semiconductor partnerships to secure supply of high-density detector substrates. Siemens Healthineers sustains R&D intensity across electromagnetic imaging coils and real-time reconstruction algorithms. Philips Healthcare anchors its competitive position through integrated software-hardware ecosystems for hybrid modality suites.
Non-invasive and minimally invasive medical imaging and visualization systems encompass diagnostic equipment that captures anatomical or functional data without penetrating the skin beyond needle insertion, utilizing magnetic fields, ionizing radiation, acoustic waves, or light in the near-infrared to gamma spectrum to generate tomographic, projection, or surface-rendered images for clinical decision-making. These systems operate at field strengths up to 7 Tesla for MRI, employ cadmium-zinc-telluride detectors for spectral CT, and rely on GPU-accelerated iterative reconstruction to achieve sub-millimeter spatial resolution within dose constraints. Ultrasound imaging and CT scans represent mature volume categories where procurement is consolidating into multi-year enterprise contracts, while photoacoustic imaging and electromagnetic imaging constitute faster-growing technology segments attracting venture-stage investment for preclinical-to-clinical translation. Public hospitals dominate installed base volume globally, though private clinics command premium pricing for same-day diagnostic workflows and specialized imaging services.
The FDA's 510(k) and de novo pathways govern US market access for novel imaging algorithms and hardware, while the EMA's Medical Device Regulation (MDR) imposes clinical evidence requirements that lengthen certification timelines for European commercialization. Japan's PMDA operates a phased review system that prioritizes software-as-a-medical-device submissions, creating regulatory arbitrage opportunities for AI-native imaging vendors. Stakeholders must monitor divergence between FDA's predetermined change control plans and EMA's stricter post-market surveillance mandates when architecting global product development roadmaps.
Market Dynamics
Hybrid imaging platforms are compressing capital deployment cycles as academic medical centers consolidate procurement around multi-modality suites that merge anatomical and functional data streams into unified diagnostic workflows.
Growth Catalysts
- AI-enhanced reconstruction algorithms:FDA breakthrough device designations are compressing clearance timelines for deep-learning diagnostic tools, accelerating clinical adoption across radiology departments.
- Germany's university hospital networks:Consolidated procurement initiatives for advanced visualization suites are creating concentrated demand pull for integrated software-hardware ecosystems.
- Photoacoustic imaging platforms:Japanese sensor foundries are recalibrating photodetector array output toward optical imaging substrates, enabling clinical translation of preclinical technologies.
Market Restraints
- Cadmium-zinc-telluride detector supply:Captive semiconductor partnerships at major OEMs are creating supply access barriers for second-tier equipment manufacturers.
- EMA MDR clinical evidence requirements:Extended certification timelines for European commercialization are diverting R&D resources toward regulatory compliance documentation.
- GPU-accelerated iterative reconstruction dependency:Concentration in high-performance computing chip supply is exposing equipment manufacturers to input cost volatility and allocation constraints.
Strategic Opportunities
- Same-day diagnostic workflows:Private clinics are commanding premium pricing for rapid-turnaround imaging services, creating margin expansion potential outside public hospital procurement channels.
- Software-as-a-medical-device arbitrage:Japan's PMDA phased review system prioritizes AI-native imaging submissions, enabling faster market entry for algorithm-focused vendors.
- Near-infrared to gamma spectrum convergence:Optical and electromagnetic imaging modalities are merging detection architectures, opening hybrid platform development white space.
Industry Challenges
- Real-time reconstruction algorithm talent:Scarcity of GPU programming specialists with medical imaging domain expertise is extending development timelines for iterative reconstruction software.
- Legacy PACS integration complexity:New visualization suites face friction connecting with hospital picture archiving systems, requiring costly middleware development for enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market |
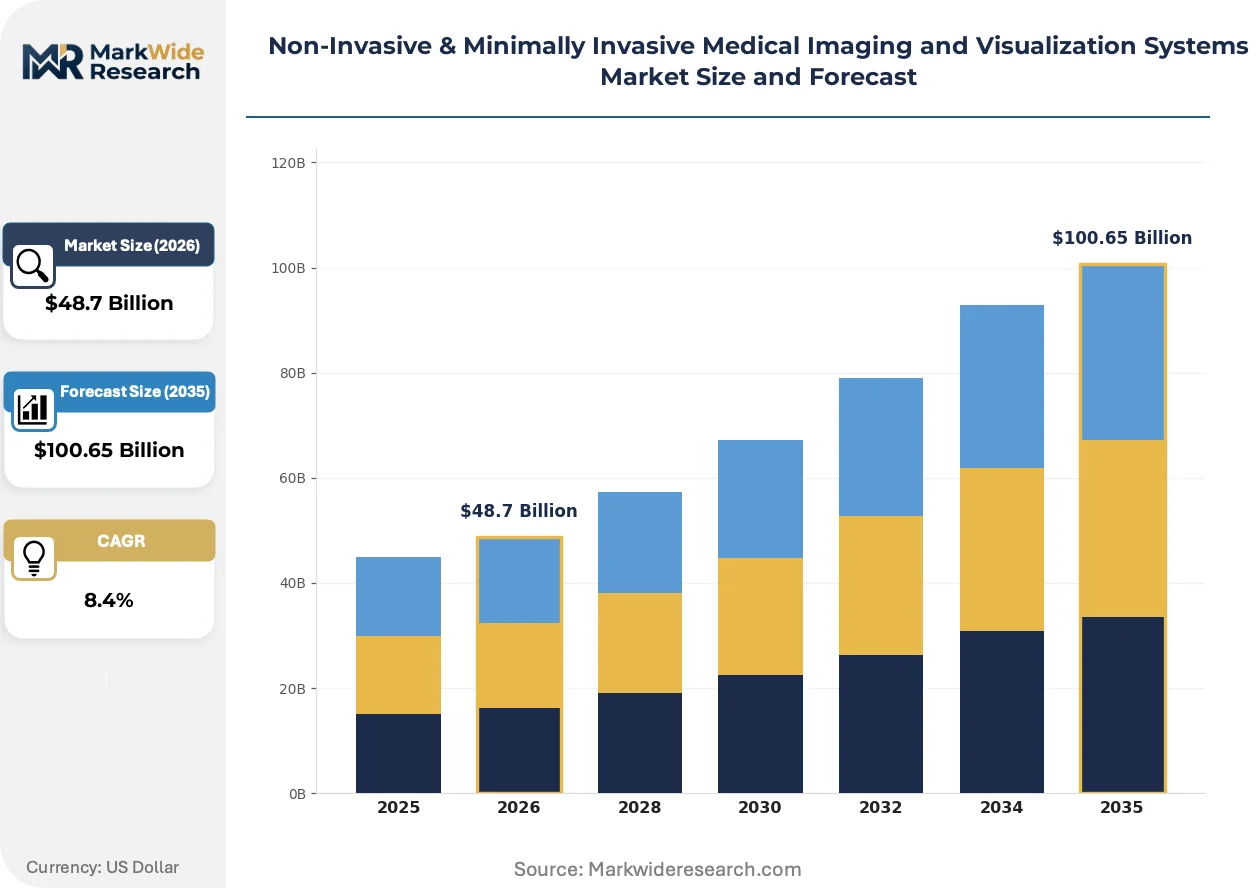
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Ultrasound Imaging, Magnetic Resonance Imaging, X-Ray Imaging, CT Scans Technology: Optical Imaging, Nuclear Imaging, Photoacoustic Imaging, Electromagnetic Imaging End User: Public Hospitals, Private Clinics, Diagnostic Laboratories, Research Institutions Service Type: Consultation Services, Maintenance Services, Imaging Services, Training Services |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Medtronic, Boston Scientific Corporation, Stryker Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market Trends and Innovations
Computational imaging architectures and regulatory pathway innovations are restructuring how diagnostic data is captured, processed, and reimbursed across hospital networks and specialized clinics.
Point-of-care ultrasound systems with AI-guided probe positioning are decentralizing image acquisition from centralized radiology departments to emergency wards and primary care settings. Community hospitals and ambulatory surgical centers are deploying these platforms for rapid triage. This shift is compressing specialist radiologist workflow bottlenecks while expanding addressable procedure volumes beyond traditional imaging suites.
EMA's Medical Device Regulation post-market surveillance mandates are diverging from FDA predetermined change control plans, forcing manufacturers to architect dual-track compliance systems. European notified bodies are demanding extended clinical follow-up data for algorithm updates. AI-native vendors are responding by establishing separate European regulatory subsidiaries with dedicated quality management systems.
Enterprise buyers are consolidating multi-year contracts across ultrasound and CT modalities, unbundling after-sales service from equipment purchase agreements. Public hospital networks in Germany and Japan are leading this shift toward performance-based maintenance contracts. Procurement committees now prioritize total cost-of-ownership metrics over upfront capital expenditure in vendor selection criteria.
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market Segmentation
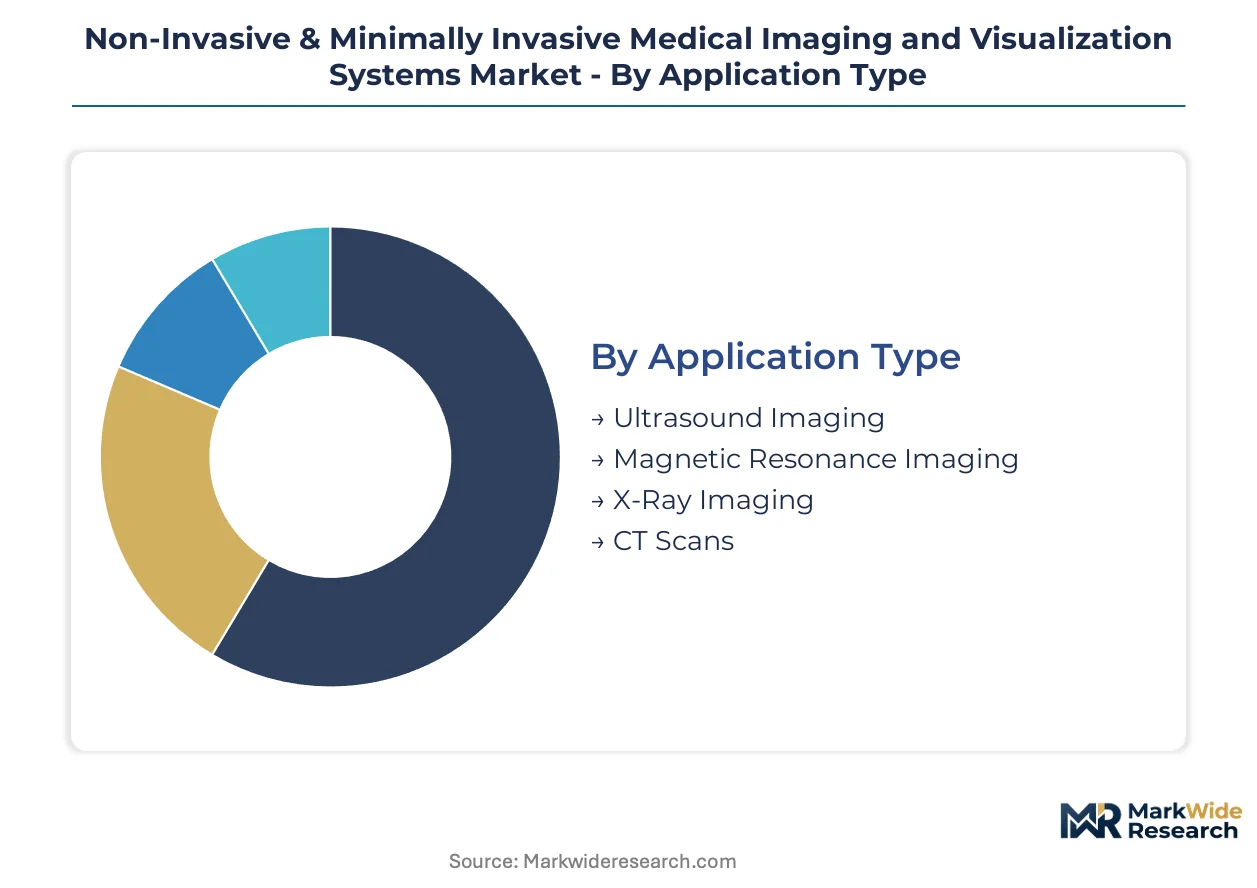
Equipment refresh cycles vary dramatically across imaging modalities, with MRI and CT platforms commanding decade-long replacement timelines while optical and photoacoustic technologies compress upgrade windows to three-to-five-year intervals. Understanding segment-specific procurement patterns enables vendors to align R&D roadmaps with predictable capital deployment cycles.
Application Type:
Replacement-cycle dynamics diverge sharply across modalities, with mature platforms facing extended upgrade delays and emerging technologies triggering accelerated fleet turnover.
- Magnetic Resonance Imaging:Systems operate at field strengths up to 7 Tesla using superconducting magnets and radiofrequency coils. University hospital networks in Germany are consolidating procurement around hybrid MRI-PET suites, though helium supply constraints are extending installation timelines for new high-field installations.
- CT Scans:Cadmium-zinc-telluride detector arrays enable spectral imaging with sub-millimeter spatial resolution. Public hospitals dominate installed base volume globally, with enterprise procurement committees prioritizing total cost-of-ownership metrics over upfront capital expenditure in multi-year contract negotiations.
- Ultrasound Imaging:Point-of-care systems with AI-guided probe positioning are decentralizing acquisition from radiology departments to emergency wards.
- X-Ray Imaging:Digital radiography panels are replacing computed radiography cassettes in cost-sensitive procurement channels.
CT Scans sits at the top of the volume ranking, with Ultrasound Imaging climbing the fastest.
Technology:
Supply concentration in detector substrates and reconstruction hardware is creating tiered access patterns across technology categories.
- Photoacoustic Imaging:Japanese sensor foundries are recalibrating photodetector array output toward optical imaging substrates, enabling clinical translation from preclinical research platforms. Academic medical centers are piloting hybrid photoacoustic-ultrasound systems for oncology applications.
- Electromagnetic Imaging:Real-time reconstruction algorithms require GPU-accelerated iterative processing to achieve diagnostic throughput. Siemens Healthineers sustains R&D intensity across electromagnetic imaging coils, though scarcity of GPU programming specialists is extending software development timelines.
- Optical Imaging:Near-infrared spectroscopy systems are merging detection architectures with gamma imaging modalities.
- Nuclear Imaging:PET and SPECT platforms face radiopharmaceutical supply chain dependencies that constrain procedure scheduling flexibility.
Photoacoustic Imaging commands the steepest expansion trajectory, while Nuclear Imaging maintains the largest installed revenue base.
End User:
Pricing power and procurement sophistication vary systematically across customer categories, with private channels capturing margin premiums and public networks extracting volume discounts.
- Private Clinics:Same-day diagnostic workflows command premium pricing outside public hospital procurement channels. These facilities prioritize rapid-turnaround imaging services and specialized procedure volumes that justify higher per-scan reimbursement rates.
- Public Hospitals:Enterprise buyers are consolidating multi-year contracts across ultrasound and CT modalities, unbundling after-sales service from equipment purchase agreements. Procurement committees now weight performance-based maintenance metrics heavily in vendor selection.
- Diagnostic Laboratories:Independent imaging centers are deploying teleradiology infrastructure to extend specialist coverage across geographic catchment areas.
- Research Institutions:Preclinical imaging suites require flexible platform configurations that accommodate protocol modifications during study execution.
Public Hospitals anchor the volume ranking, with Private Clinics gaining share fastest.
Service Type:
Revenue mix is shifting from capital equipment toward recurring service streams as enterprise contracts unbundle hardware from ongoing support obligations.
- Maintenance Services:Performance-based contracts are replacing time-and-materials service agreements across German and Japanese hospital networks. Uptime guarantees and predictive analytics for component replacement are becoming standard contractual terms.
- Imaging Services:Teleradiology platforms enable centralized interpretation across distributed acquisition sites. Diagnostic Laboratories are outsourcing specialist reads to contracted radiologist networks, compressing turnaround times for complex cases.
- Consultation Services:Clinical workflow optimization advisory supports new platform adoption and staff training protocols.
- Training Services:AI-guided probe positioning systems require competency certification programs for point-of-care operators.
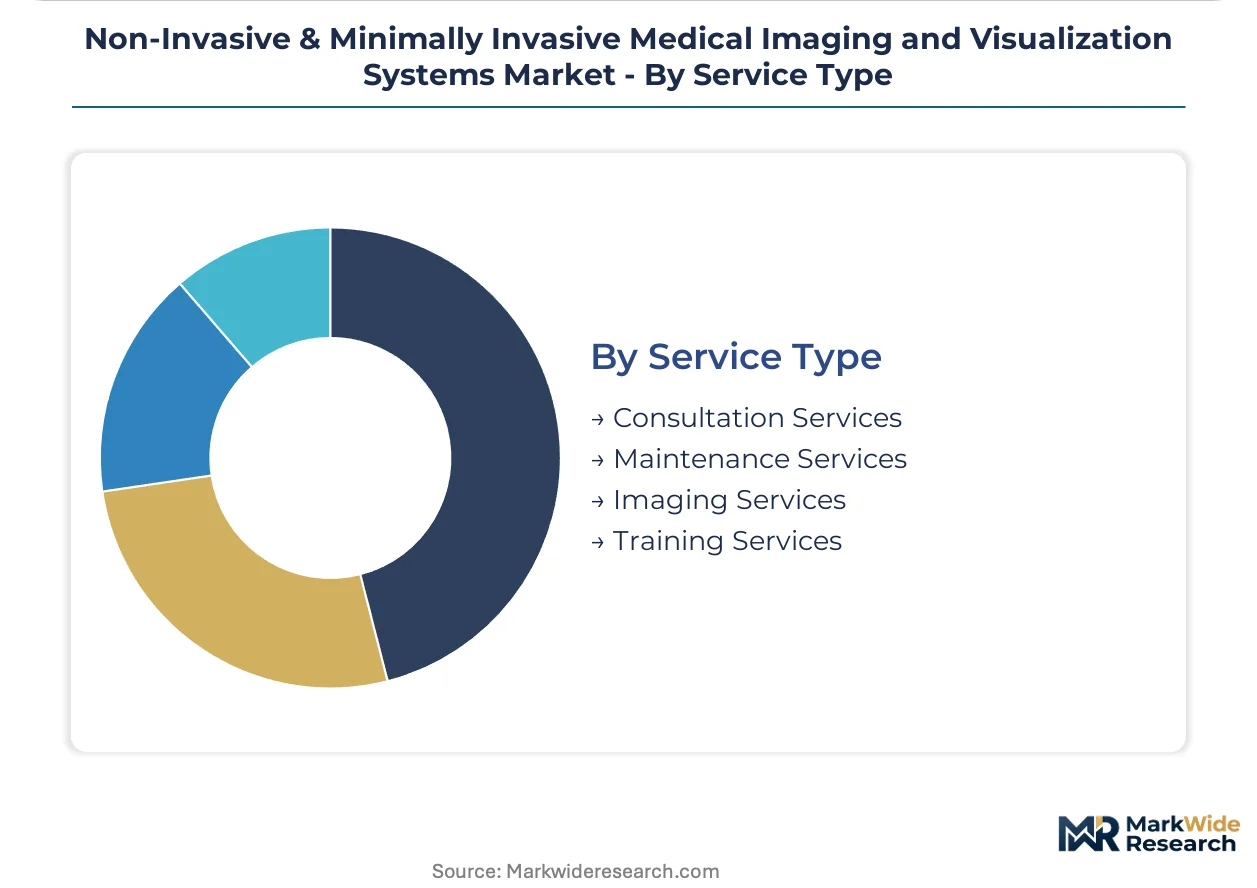
Maintenance Services occupies the top volume position, with Imaging Services expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between FDA breakthrough pathways and EMA MDR clinical evidence requirements is redirecting commercialization sequencing toward jurisdictions with faster clearance timelines. Japanese PMDA prioritization of software-as-a-medical-device submissions creates arbitrage opportunities for algorithm-native vendors. Production and R&D investment patterns track these compliance cost differentials.
Germany
University hospital networks in Baden-Württemberg and Bavaria are consolidating procurement for hybrid MRI-PET suites and advanced visualization ecosystems. EMA MDR post-market surveillance mandates extend certification timelines, diverting vendor resources toward dual-track compliance systems. Heidelberg and Munich academic clusters anchor demand concentration for 7 Tesla field-strength installations.
United States
FDA breakthrough device designations compress clearance timelines for AI-enhanced reconstruction algorithms, accelerating radiology department adoption. Predetermined change control plans enable iterative software updates without redundant submissions. Boston and San Francisco Bay Area hospital networks pilot point-of-care ultrasound with AI-guided probe positioning for emergency ward deployment.
Japan
METI industrial policy and PMDA phased review systems prioritize photodetector array outputs for photoacoustic imaging platforms. Tokyo and Osaka sensor foundries recalibrate production toward optical imaging substrates. Kanto region academic medical centers pilot hybrid photoacoustic-ultrasound systems for oncology applications.
China
NMPA regulatory harmonization efforts accelerate domestic approval timelines for GPU-accelerated iterative reconstruction software. Yangtze River Delta hospital procurement committees weight total cost-of-ownership metrics in multi-year enterprise contracts. Shanghai and Hangzhou medical device clusters concentrate teleradiology infrastructure development for distributed interpretation networks.
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-native diagnostic tools and point-of-care decentralization. The vendor base stratifies around three archetypes: integrated imaging conglomerates with captive semiconductor supply, specialized coil and detector substrate fabricators, and algorithm-focused SaaS vendors exploiting regulatory arbitrage. Consolidation pressures intensify as enterprise procurement committees unbundle after-sales service from hardware purchases. Dominant competitive moves include strategic partnerships for GPU supply security and geographic expansion through regulatory subsidiary establishment.
Among integrated imaging conglomerates, GE Healthcare, Siemens Healthineers, and Philips Healthcare exemplify the captive supply archetype. GE Healthcare leverages semiconductor partnerships for high-density detector substrate access. Siemens Healthineers sustains R&D intensity across electromagnetic imaging coils and reconstruction algorithms. Philips Healthcare anchors competitive positioning through integrated software-hardware ecosystems for hybrid modality suites. These three entities represent the consolidated tier where procurement scale and regulatory sophistication create defensive moats.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Medtronic |
| Boston Scientific Corporation |
| Stryker Corporation |
| Olympus Corporation |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between FDA breakthrough-designated AI platforms and standard 510(k) imaging hardware manifests in both procurement premiums and captive semiconductor sourcing strategies. German university hospital networks extract volume discounts on visualization suites while Japanese sensor foundries prioritize photodetector arrays for premium optical imaging substrates, creating tiered access patterns that ripple through detector supply allocation.
Pricing Analysis
Distributor margins on GPU-accelerated reconstruction hardware compress as OEMs consolidate direct-to-hospital enterprise contracts. Three-tier pricing structure across premium, standard, and economy levels tracks field strength and detector density specifications. Cost compression in mid-tier CT platforms intensifies as public procurement committees weight total cost-of-ownership metrics over upfront capital expenditure. Private clinics exhibit lowest price sensitivity due to same-day diagnostic workflow premiums, while research institutions negotiate hardest on preclinical imaging suite configurations.
Supply Chain Analysis
Freight costs for helium-cooled MRI magnet shipments from Japan and Germany constrain installation scheduling flexibility for high-field systems. Cadmium-zinc-telluride detector fabrication concentrates in Japanese and German foundries, with GPU chip supply anchored in Taiwan and South Korea. Single-source vulnerability in high-performance computing substrates exposes equipment manufacturers to allocation constraints. Distribution runs through regional service subsidiaries that maintain localized spare parts inventories for uptime guarantee contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
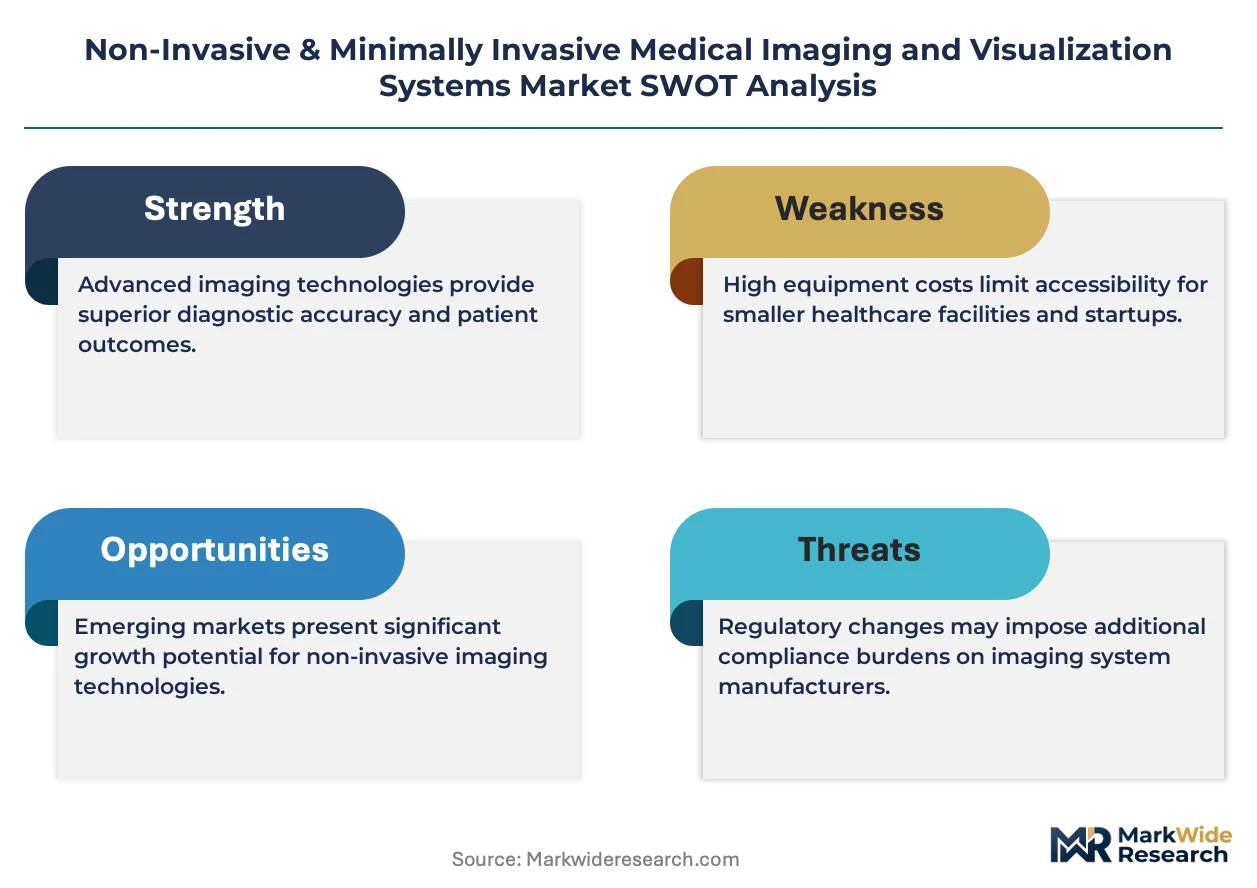
This market compounds regulatory complexity into durable competitive advantage, with FDA breakthrough device designations and EMA MDR post-market surveillance mandates creating divergent compliance cost structures that favor incumbent scale.
For Market Incumbents: Cement captive semiconductor partnerships for high-density detector substrate security while consolidating service infrastructure around predictive analytics capabilities. Algorithm-native vendors threaten margin compression in reconstruction software; defend through backward integration into electromagnetic imaging coil fabrication and GPU supply allocation agreements with foundry partners. For New Entrants and Emerging Players: Teleradiology infrastructure providers represent the most penetrable channel partner type for SaaS-native imaging algorithms. Target diagnostic laboratories in China's Yangtze River Delta with GPU-accelerated iterative reconstruction tools that bypass hardware-heavy capital deployment. Pursue Japan's PMDA phased review pathway for faster software-as-a-medical-device clearance. For Investors and Strategic Acquirers: Asymmetric upside sits with algorithm-focused vendors possessing regulatory arbitrage expertise across FDA and PMDA pathways. Long-term viability hinges on recurring revenue transition from capital equipment to performance-based maintenance contracts. Watch for inflection when hospital procurement committees unbundle after-sales service from hardware purchases in additional European markets.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year enterprise contracts with German university networks lock in visualization suite deployment. |
| Software Companion Development | AI-guided probe positioning modules expand point-of-care ultrasound into emergency ward workflows. |
| FDA Submission | Breakthrough device designation compresses clearance timelines for deep-learning reconstruction algorithms. |
| CE Marking Pathway | MDR clinical evidence requirements demand dedicated European regulatory subsidiaries for sustained access. |
| Reimbursement Strategy | Same-day diagnostic workflow coding enables premium pricing capture in private clinic channels. |
Research Methodology
Multiple input streams — primary interviews with hospital purchasing committees, biomedical engineers, and GPO contracts managers; secondary validation through FDA 510(k) filings, EMA MDR submission databases, and hospital procurement records; plus customs data on detector substrate trade flows — were reconciled through bottom-up equipment shipment analysis and top-down healthcare capital expenditure triangulation.
Historical installation base trajectories were cross-referenced against panel input from radiology department heads and medical device regulatory consultants. Segmentation modeling spanned imaging modality, technology maturity, end-user category, and service type across the projection horizon. CAGRs were derived from fitted growth curves incorporating replacement cycle dynamics and academic medical center capital deployment patterns.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to helium supply constraints, GPU allocation volatility, and divergence between FDA predetermined change control plans and EMA post-market surveillance mandates. Forecasts reflect documented assumptions about regulatory pathway stability and hospital network consolidation trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
United Kingdom Digital X-Ray Devices Market
Medical Imaging
Asia-Pacific Digital X-Ray Devices Market
Medical Imaging
Republic of Ireland (ROI) and Northern Ireland MRI and CT Scan Radiology Services Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
South Africa Diagnostic Imaging Equipment Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Portable Ultrasound Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
Global 3D Laparoscopy Imaging Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Ultrasound Image Processing Software Market