
 UK Digital Radiology Market | 2026-2036
UK Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
UK Digital Radiology Market Insights
Hospital procurement consolidation across NHS Foundation Trusts is expanding as regional imaging networks centralize capital expenditure on enterprise-scale digital radiology platforms. GE Healthcare leverages its installed base of CT and MRI modalities to cross-sell direct radiography detectors, while Siemens Healthineers anchors its position through artificial intelligence-embedded acquisition software. Carestream Health competes on service density, sustaining maintenance contracts that lock in detector refresh cycles across England's acute trusts.
Digital radiology encompasses the capture, processing, storage, and transmission of X-ray images using solid-state detectors rather than photographic film, with detector quantum efficiency exceeding 65% in modern cesium iodide-amorphous silicon panels enabling dose reduction. Its primary purpose is to replace analog film-screen systems with immediate image availability for diagnostic decision-making. Direct radiography dominates capital procurement budgets due to superior throughput and lower long-term consumable costs, while cloud-based deployment architectures are capturing incremental share as NHS trusts migrate Picture Archiving and Communication Systems to NHS England-approved hyperscale environments. Diagnostic imaging applications absorb the largest volume of detector placements, though cardiology and oncology represent concentrated margin pools where hybrid angiography-fluoroscopy systems command premium pricing.
MHRA enforces UKCA marking requirements for all medical imaging equipment placed on the Great Britain market, with conformity assessment routes diverging from EU MDR since Brexit. NHS England's Diagnostic Imaging Dataset mandates digital image quality standards and interoperability protocols that shape vendor product roadmaps. Stakeholders must monitor whether NHS Long Term Workforce Plan commitments to expand radiographer training translate into sustained capital allocation for detector replacement programs.
Market Dynamics
NHS England's regional imaging network consolidation is compressing procurement timelines and favoring vendors with enterprise-scale service architectures over point-product specialists.
Growth Catalysts
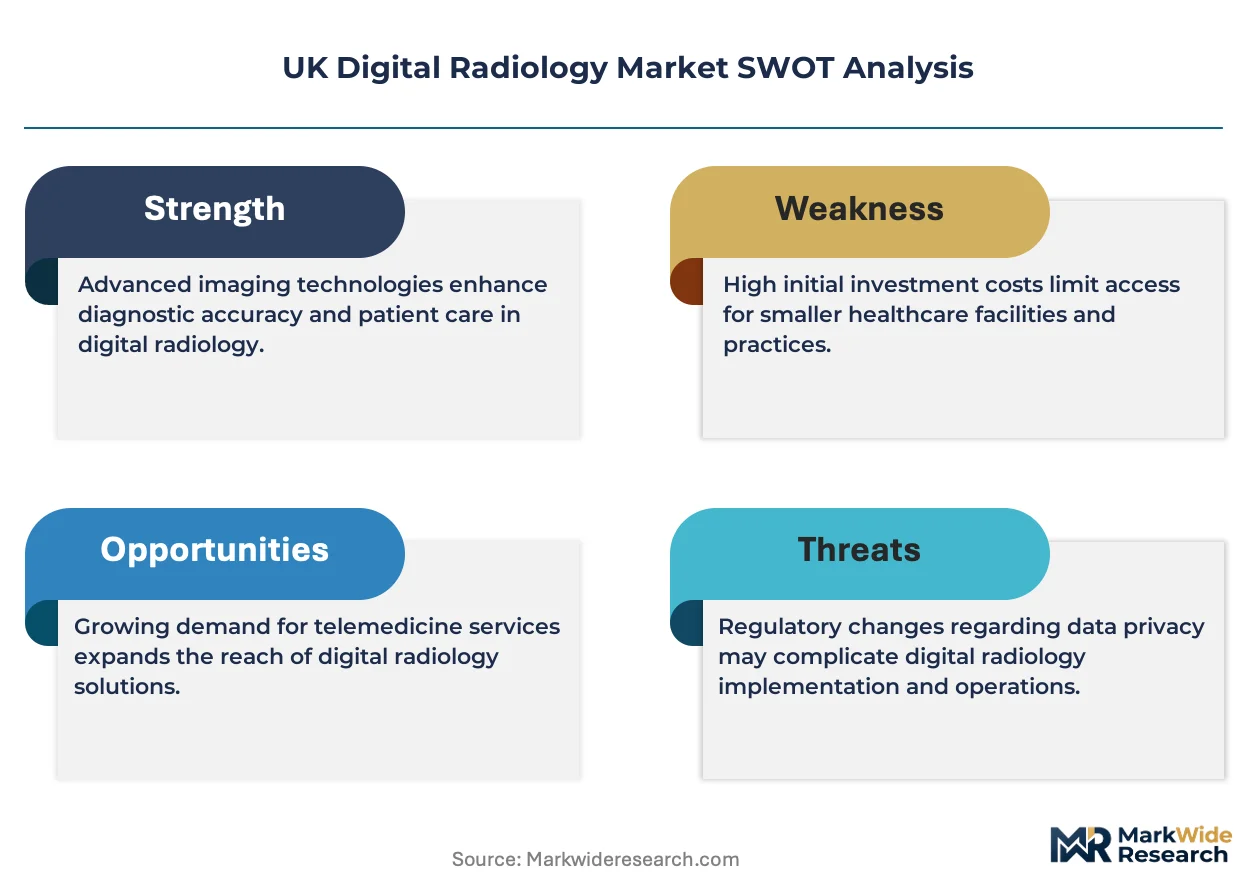
- UKCA Marking Transition:MHRA's post-Brexit conformity assessment routes are accelerating replacement cycles for EU MDR-certified legacy equipment as trusts face 2028 deadlines for Great Britain market compliance.
- Detector Technology Maturation:Cesium iodide-amorphous silicon panels achieving quantum efficiency above 65% are enabling diagnostic dose reduction protocols that align with NHS England's radiation safety mandates.
- London Cluster Concentration:Specialist cardiac and oncology centres in the capital and South East are absorbing premium hybrid angiography-fluoroscopy placements at double the rate of Northern regions.
Market Restraints
- Capital Intensity Barrier:Direct radiography suites require seven-figure GBP outlays that strain acute trust capital budgets amid NHS England's efficiency targets.
- Supply Concentration Risk:Solid-state detector substrates depend on specialized semiconductor foundries concentrated in East Asian manufacturing corridors.
- Workforce Pipeline Constraint:NHS Long Term Workforce Plan radiographer training expansion lags equipment deployment, creating operational bottlenecks at installed sites.
Strategic Opportunities
- Scotland Network Expansion:NHS Scotland's imaging modernization program offers concentrated procurement windows for vendors with established England service infrastructure.
- Cloud PACS Migration:NHS England-approved hyperscale environments are creating white space for subscription-based image archiving models that displace on-premise storage.
- AI-Embedded Acquisition Convergence:Machine learning algorithms for automated positioning and exposure optimization are opening premium pricing tiers at teaching hospital trusts.
Industry Challenges
- Interoperability Certification Complexity:NHS Digital's Diagnostic Imaging Dataset standards require vendor-specific integration testing that extends deployment timelines.
- Detector Refresh Cycle Coordination:Trusts struggle to synchronize multi-site detector replacements with consolidated procurement frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Digital Radiology Market |
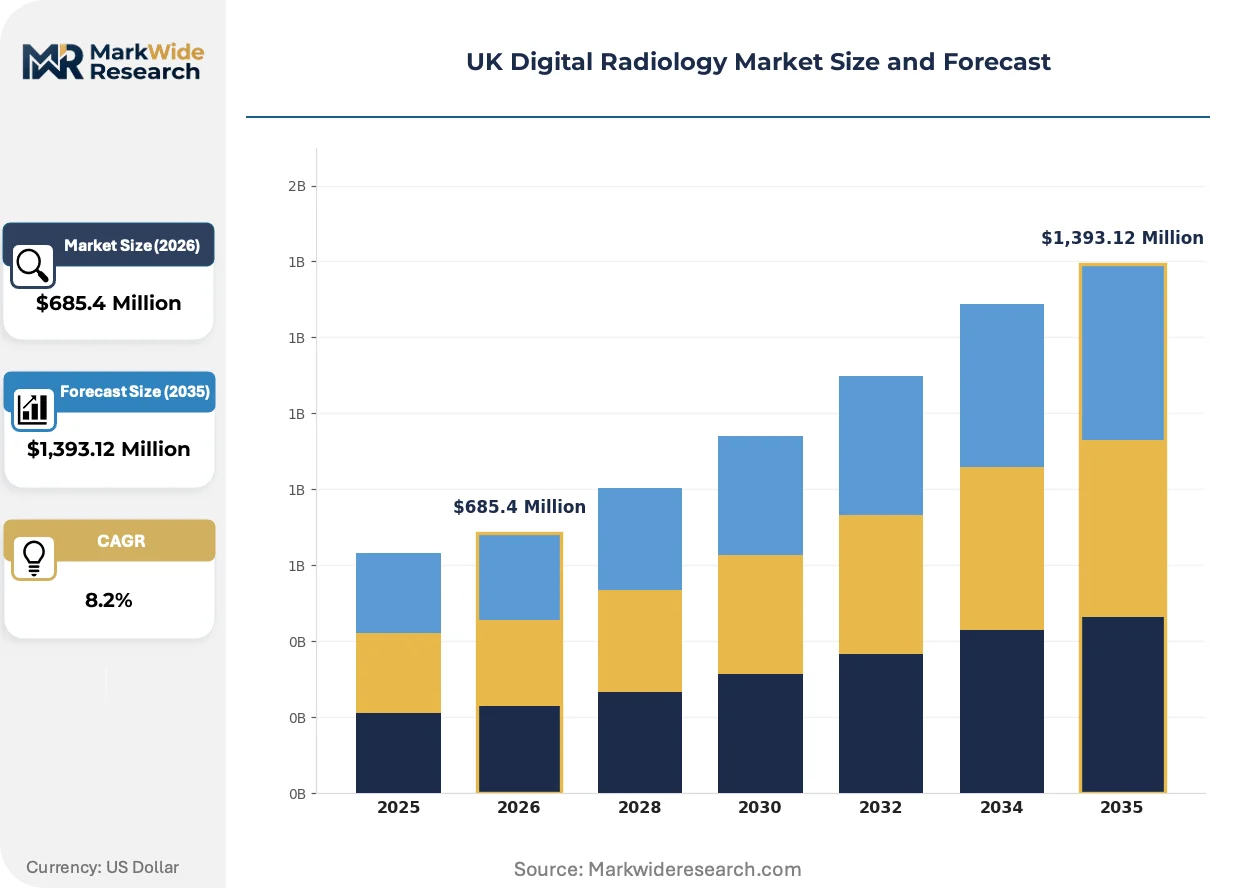
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Computed Radiography, Direct Radiography, Digital Radiography Systems, Imaging Software, PACS Equipment Application: Diagnostic Imaging, Orthopedics, Oncology, Cardiology, Emergency Medicine End User: Hospitals, Diagnostic Centers, Specialty Clinics, Research Institutes Deployment: On-Premises, Cloud-Based, Hybrid Systems, Mobile Units |
| Companies Covered | GE Healthcare, Carestream Health, FUJIFILM, Canon Medical Systems, Siemens Healthineers, Koninklijke Philips, Hologic, Agfa-Gevaert Group, Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Digital Radiology Market Trends and Innovations
Artificial intelligence integration is compressing the gap between image acquisition and diagnostic decision-making, while procurement centralization is reshaping vendor-customer relationships across NHS regional networks.
Deep learning algorithms for automated chest X-ray triage and fracture detection are consolidating radiologist workflow prioritization at NHS Foundation Trusts with high emergency department throughput. These tools reduce reporting backlogs during overnight shifts. The technology is consolidating first-line screening responsibilities away from specialist consultants toward radiographer-led reporting pathways.
MHRA's post-Brexit medical device regulation framework is diverging conformity assessment routes from EU MDR, forcing manufacturers to maintain parallel certification systems for Great Britain and Northern Ireland markets. This regulatory friction increases compliance overhead for vendors with limited UK regulatory affairs capacity. Smaller equipment suppliers are responding by withdrawing from the Great Britain market or pursuing UKCA marking through notified body partnerships.
Regional NHS imaging networks are centralizing capital allocation decisions that previously sat with individual trust procurement departments. This buyer concentration favors vendors offering multi-site service contracts and remote monitoring capabilities. The shift is most visible in England's North West and Midlands regions where integrated care systems have merged imaging procurement functions across former competing trusts.
UK Digital Radiology Market Segmentation
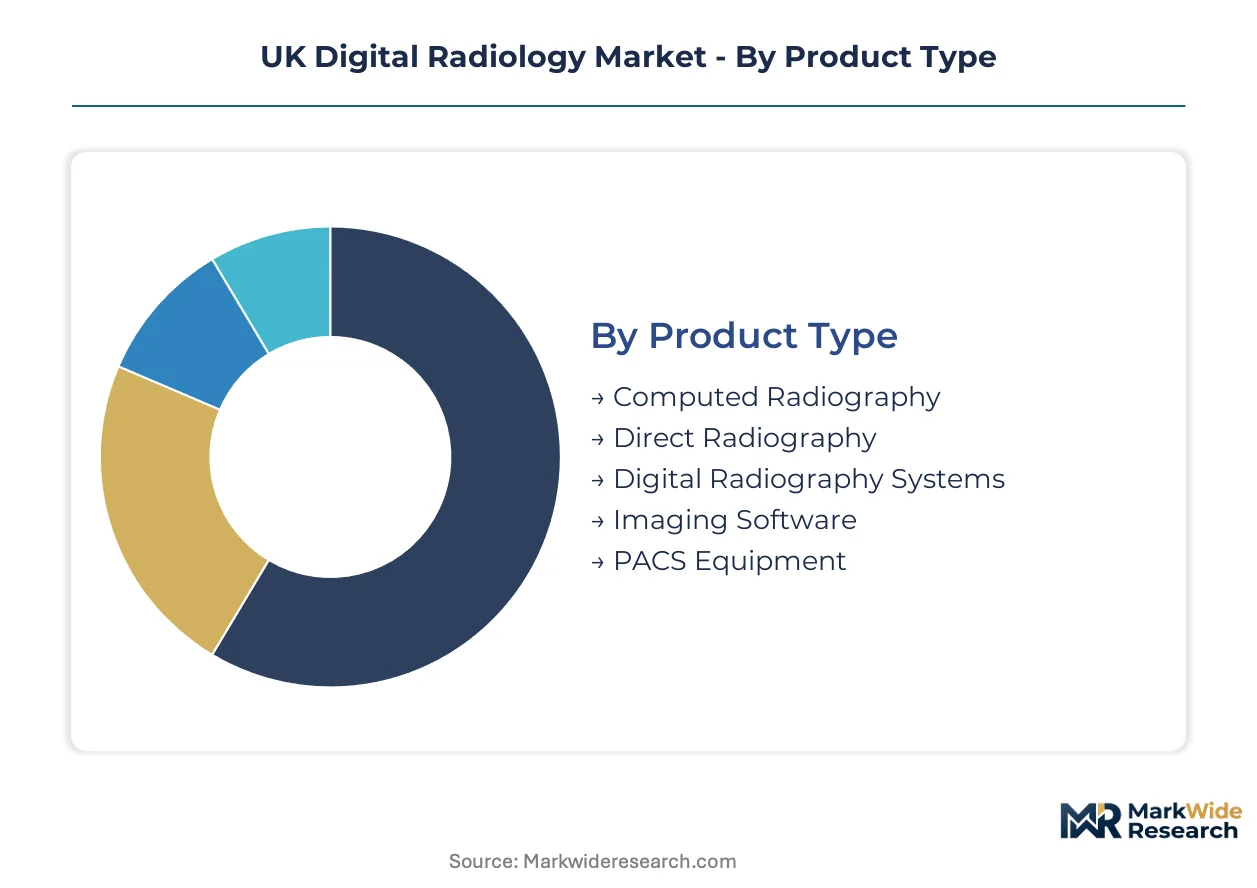
Digital radiology segmentation reveals how procurement priorities diverge across NHS trusts with varying capital intensities and clinical specializations. Technology maturity, application criticality, and deployment architecture each reshape vendor competitive positioning and pricing power across England and Scotland.
Product Type:
Detector substrate technology and image acquisition architecture define performance tiers and replacement cycle economics across NHS procurement frameworks.
- Computed Radiography:Photostimulable phosphor plates with laser scanning readout persist in smaller acute trusts with constrained capital budgets. Demand concentrates in Northern England trusts where seven-figure DR outlays face NHS efficiency target scrutiny, though MHRA's UKCA marking deadlines accelerate phase-out timelines.
- Direct Radiography:Cesium iodide-amorphous silicon flat-panel detectors with quantum efficiency exceeding 65% dominate London and South East specialist centres. Procurement concentrates in cardiac and oncology hubs where throughput requirements justify premium detector investments and dose reduction protocols align with NHS England radiation safety mandates.
- Digital Radiography Systems:Integrated tube-stand-detector configurations with automated positioning reduce radiographer workload at high-volume emergency departments.
- Imaging Software:AI-embedded acquisition platforms with automated exposure optimization command pricing premiums at teaching hospital trusts.
- PACS Equipment:On-premise archival infrastructure faces displacement pressure as NHS England-approved hyperscale cloud environments expand.
Mature deployment sits with Computed Radiography. Newer deployment is concentrated in Direct Radiography.
Application:
Clinical workflow urgency and reimbursement complexity fragment demand concentration across NHS specialist networks and district general hospitals.
- Diagnostic Imaging:General radiography departments process the highest detector placement volumes across England's acute trusts. Demand spreads across district general hospitals and foundation trusts with 24-hour emergency services, where detector reliability and rapid image availability compress clinical decision timelines.
- Oncology:Hybrid angiography-fluoroscopy systems with cone-beam CT capability absorb concentrated capital allocation at London's specialist cancer centres. Procurement clusters at Royal Marsden NHS Foundation Trust and Manchester's Christie Hospital where image-guided radiation therapy and interventional oncology procedures command premium equipment specifications.
- Orthopedics:Weight-bearing extremity imaging systems with specialized detector geometries serve fracture clinics and joint replacement pathways.
- Cardiology:Flat-panel detector angiography suites with rotational acquisition support structural heart interventions at regional cardiac centres.
- Emergency Medicine:Portable DR systems with battery-powered wireless detectors enable trauma bay imaging without patient transport.
Volume concentration rests with Diagnostic Imaging. Margin expansion is climbing the fastest in Oncology.
End User:
Capital access and procurement autonomy determine equipment specification tiers across NHS organizational structures.
- Hospitals:NHS Foundation Trusts and acute trusts with consolidated regional imaging networks command enterprise-scale procurement leverage. Multi-site service contracts and remote monitoring capabilities favor vendors with established England infrastructure, while detector refresh cycle coordination challenges trusts with fragmented legacy estates.
- Diagnostic Centers:Independent sector providers with NHS outsourcing contracts prioritize rapid turnaround and competitive per-scan economics. Demand concentrates in London and South East where patient choice policies expand capacity beyond hospital radiology departments.
- Specialty Clinics:Orthopedic and sports medicine practices with self-referral pathways favor compact DR systems with limited room requirements.
- Research Institutes:University hospital partners with NIHR funding access experimental detector technologies for clinical trial imaging endpoints.
Procurement scale sits with Hospitals. Flexibility requirements are expanding most quickly in Diagnostic Centers.
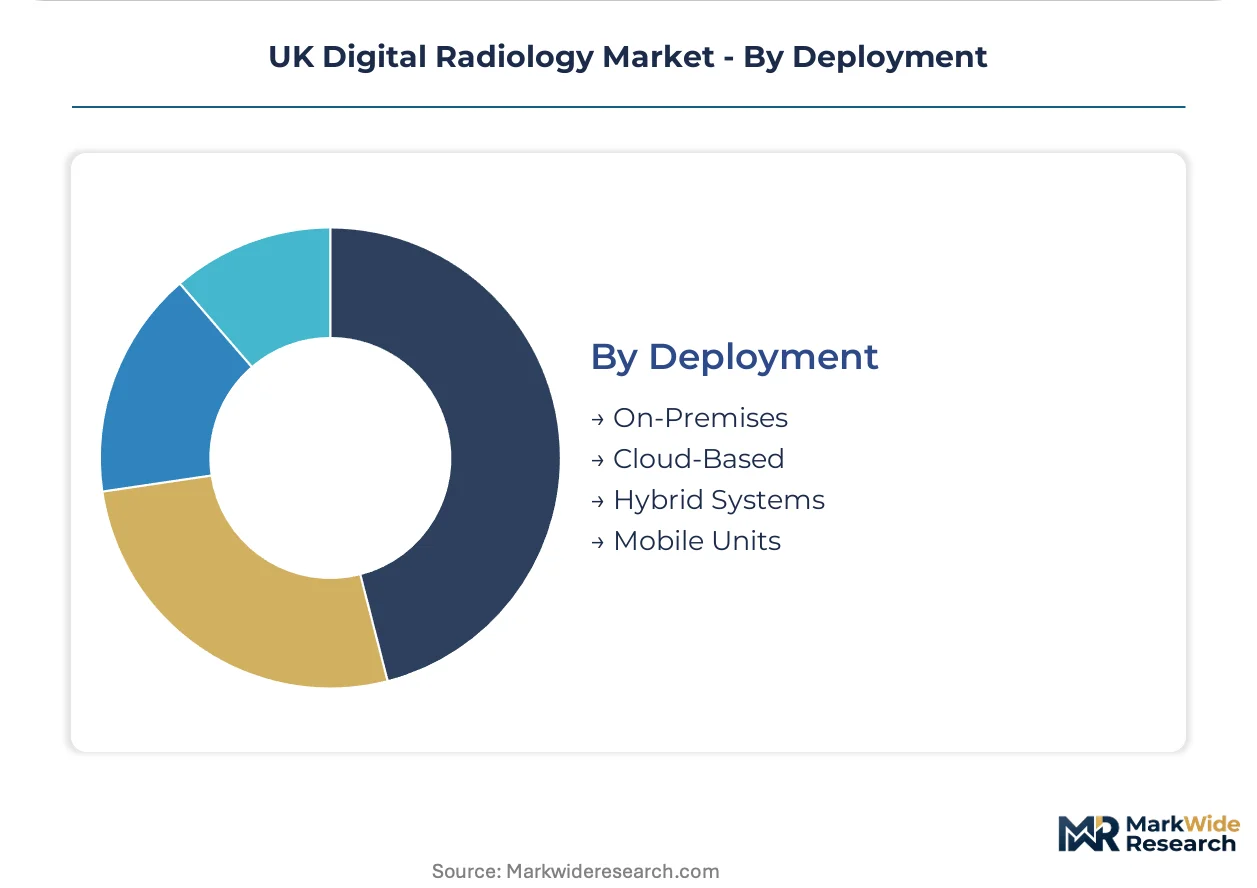
Deployment:
Infrastructure ownership models and data sovereignty requirements fragment architectural preferences across NHS digital transformation timelines.
- On-Premises:Dedicated server rooms with local PACS storage persist at trusts with legacy IT estates and cybersecurity risk aversion. Deployment concentrates in trusts with substantial capital depreciation schedules and specialized IT workforce retention, though operational cost burdens and disaster recovery limitations create migration pressure.
- Cloud-Based:NHS England-approved hyperscale environments with Diagnostic Imaging Dataset interoperability certification capture incremental share. Procurement accelerates at trusts with consolidated regional networks where subscription models convert capital expenditure to operational budgets aligned with NHS efficiency targets.
- Hybrid Systems:Edge caching with cloud archival balances latency-sensitive diagnostic workstations against long-term storage economics.
- Mobile Units:Truck-mounted DR suites with onboard generators extend screening services to rural Scotland and Northern England communities.
Established infrastructure sits with On-Premises. Architectural transition is gaining share fastest in Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London and the South East concentrate specialist cardiac and oncology demand, while NHS Scotland's imaging modernization program opens concentrated procurement windows beyond England's core markets.
London and South East England
Specialist cardiac and oncology centres at Royal Brompton Hospital and Royal Marsden NHS Foundation Trust absorb premium hybrid angiography-fluoroscopy placements. NHS England's regional imaging network consolidation compresses procurement timelines across foundation trusts. The capital's teaching hospital trusts command enterprise-scale service contracts with remote monitoring capabilities.
Midlands
Integrated care systems in the West Midlands have merged imaging procurement functions across former competing acute trusts. University Hospitals Birmingham NHS Foundation Trust anchors detector refresh cycle coordination for multi-site estates. The region's consolidated capital allocation favors vendors with established England service infrastructure over point-product specialists.
North West England
Manchester's Christie Hospital drives concentrated capital allocation for image-guided radiation therapy equipment. NHS England's Diagnostic Imaging Dataset mandates shape vendor product roadmaps across the region's district general hospitals. The Manchester University NHS Foundation Trust network exemplifies procurement centralization that converts capital expenditure to operational budgets.
Scotland
NHS Scotland's imaging modernization program offers procurement windows for vendors with cross-border service capabilities. Edinburgh and Glasgow specialist centres pursue detector technology maturation aligned with NHS England radiation safety mandates. The country's national health service structure enables centralized equipment specification tiers distinct from England's trust-fragmented landscape.
Wales
Cardiff and Swansea health boards navigate UKCA marking transition timelines for EU MDR-certified legacy equipment replacement. Wales's smaller acute trust structure sustains computed radiography persistence where capital budgets face efficiency target scrutiny. The country's imaging procurement functions through All-Wales contracts that aggregate demand across health board boundaries.
UK Digital Radiology Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-embedded acquisition software and cloud-based deployment architectures. The vendor base stratifies across three tiers: diversified medical technology conglomerates with installed base cross-selling leverage, specialized imaging equipment manufacturers competing on service density, and software-centric challengers capturing subscription-based image archiving share. Consolidation pressure favors enterprise-scale service architectures as NHS regional networks centralize procurement decisions. Dominant competitive moves include portfolio diversification into adjacent modalities and strategic partnerships for UKCA marking compliance support.
Among diversified medical technology conglomerates, GE Healthcare leverages its CT and MRI installed base to anchor detector placement decisions, while Siemens Healthineers exemplifies the AI-embedded acquisition tier through premium pricing at teaching hospital trusts. Carestream Health occupies a position within the service-density competitive vector, sustaining maintenance contracts that lock in detector refresh cycles across England's acute trusts. These three entities represent distinct strategic archetypes: installed-base cross-selling, algorithmic differentiation, and contractual lock-in through service infrastructure.
| Leading Market Players |
|---|
| GE Healthcare |
| Carestream Health |
| FUJIFILM |
| Canon Medical Systems |
| Siemens Healthineers |
| Koninklijke Philips |
| Hologic |
| Agfa-Gevaert Group |
| Shimadzu Corporation |
| Others |
Pricing and Supply Chain Analysis
Semiconductor substrate costs for cesium iodide-amorphous silicon panels flow through specialized East Asian foundries into three-tier pricing structures across NHS procurement frameworks, with detector quantum efficiency ratings separating premium cardiac installations from economy-tier district general hospital deployments.
Pricing Analysis
Volume concentration in diagnostic imaging departments absorbs standard-tier detector placements at compressed margins, while premium pricing persists at London cardiac and oncology centres where hybrid angiography-fluoroscopy specifications command service-integrated contracts. Price differentiation hinges on detector quantum efficiency certification and MHRA UKCA marking compliance tier. Pricing pressure stems from NHS England's efficiency targets forcing capital-to-operational budget conversions. District general hospitals in Northern England exhibit highest price sensitivity; teaching hospital trusts with NIHR funding show lowest sensitivity to premium AI-embedded acquisition software.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor corridors amplifies landed cost uncertainty for cesium iodide substrate shipments destined for Great Britain assembly facilities. Solid-state detector manufacturing concentrates in Japan, South Korea, and Taiwan. Production draws from specialized silicon wafer and phosphor material inputs. Single-source vulnerability persists at substrate foundry tier where capacity allocation favors consumer electronics. Distribution runs through vendor-managed inventory arrangements at NHS regional imaging network consolidation hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NHS regional imaging network consolidation is compressing vendor count as enterprise-scale service contracts displace point-product specialists unable to sustain multi-site maintenance infrastructure.
For Market Incumbents: Anticipate detector refresh cycle coordination challenges across merged trust estates by embedding remote monitoring capabilities into service contracts. Counter software-centric challengers through backward integration into AI-embedded acquisition modules. Prioritize UKCA marking compliance investment to capture EU MDR legacy equipment replacement windows before MHRA deadlines. For New Entrants and Emerging Players: MHRA's post-Brexit UKCA marking divergence from EU MDR opens a window for regulatory affairs partnerships with smaller EU manufacturers exiting Great Britain. Target Scotland's NHS imaging modernization program where cross-border service infrastructure gaps persist. Pursue cloud-based PACS subscription models at trusts converting capital expenditure to operational budgets. For Investors and Strategic Acquirers: NHS England Diagnostic Imaging Dataset interoperability certification delays are the leading indicator that software-centric challengers face extended deployment timelines against established service infrastructure. Five-to-ten year viability favors vendors with captive detector refresh cycle visibility through maintenance contract lock-in. Monitor radiographer training pipeline expansion rates as workforce constraints create operational bottlenecks at installed sites.| Strategic Initiative | Industry Significance |
|---|---|
| AI-Embedded Acquisition Development | Machine learning algorithms for automated positioning command premium pricing at teaching hospital trusts with NIHR funding. |
| Cloud PACS Migration Partnership | NHS England-approved hyperscale environments enable subscription revenue conversion from capital-intensive on-premise archival sales. |
| UKCA Marking Compliance Investment | Parallel certification systems for Great Britain and Northern Ireland markets secure access against EU MDR-only competitor withdrawal. |
| Scotland Service Infrastructure Expansion | Cross-border maintenance capabilities capture NHS Scotland imaging modernization procurement windows beyond England's consolidated networks. |
| Detector Refresh Cycle Coordination | Multi-site estate synchronization services lock in long-term maintenance contracts across merged regional imaging networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with NHS procurement managers, biomedical engineers, radiology department heads, and GPO contracts managers. MHRA device registration databases, NHS England Diagnostic Imaging Dataset compliance records, and hospital capital expenditure disclosures provided demand-side validation. Bottom-up detector placement estimates triangulated against top-down NHS trust budget allocation analyses.
Segment-level modeling addressed product type across computed and direct radiography architectures, application concentration across diagnostic imaging and oncology specializations, deployment architecture spanning on-premise and cloud-based PACS, and end-user procurement autonomy across foundation trusts and independent sector providers. CAGRs derived from fitted growth curves against historical NHS capital allocation patterns, incorporating detector technology replacement cycle assumptions and workforce pipeline constraints.
The model assumes a particular technology adoption path; alternative pathways for AI-embedded acquisition convergence would alter the outlook if radiographer reporting autonomy expands faster than projected. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Artificial Intelligence in Medical Imaging Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Global Ultrasound Imaging Devices Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
France Mammography Market
Medical Imaging
Teleultrasound System Market
Medical Imaging
Robotic X-Ray Scanner Market
Medical Imaging
Smart X-Ray Detectors Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
India Mammography Market
Medical Imaging
Computed Tomography (CT) Scanners Market
Medical Imaging
Global Refurbished Medical Imaging Equipment Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market