
 Global Refurbished Medical Imaging Equipment Market | 2026-2036
Global Refurbished Medical Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refurbished Medical Imaging Equipment Market Foresight
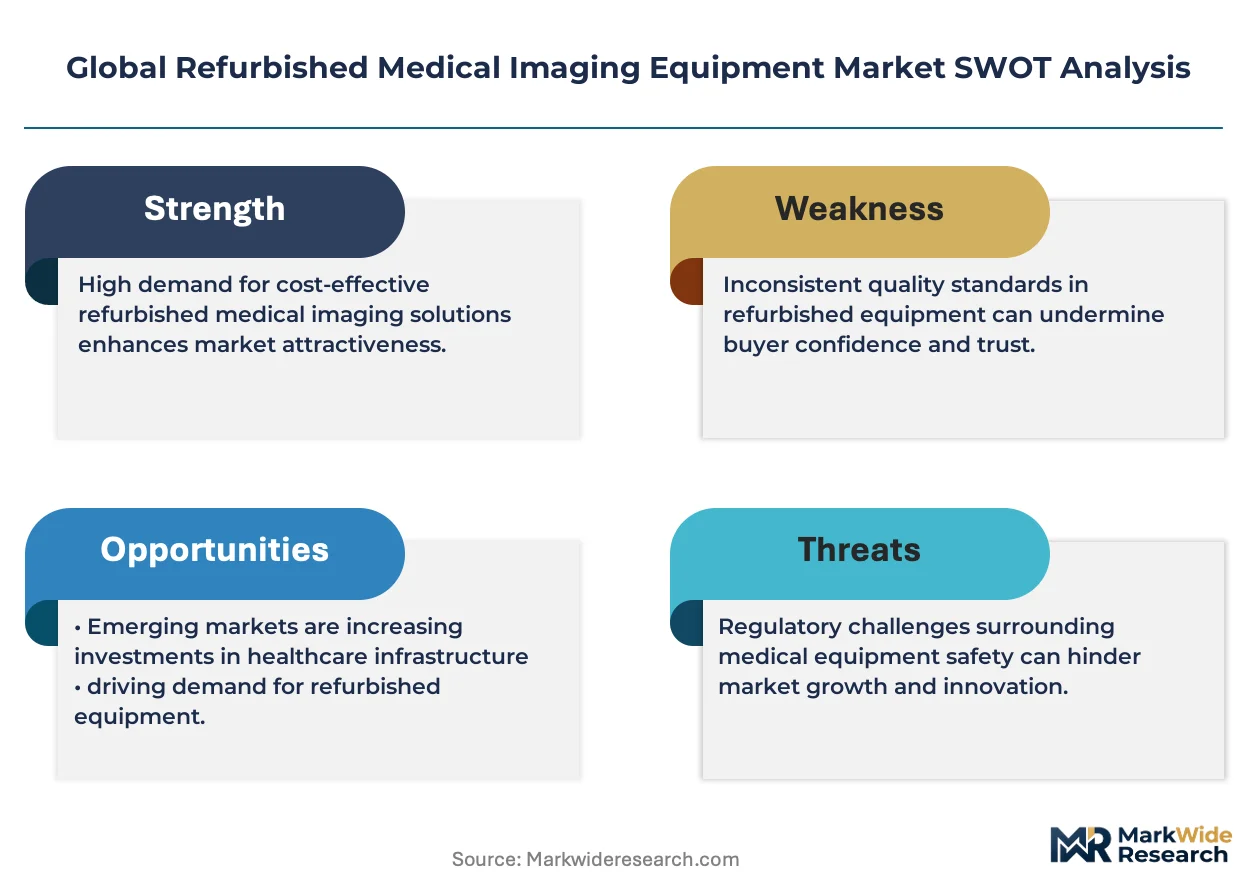
Equipment leasing and pay-per-scan financing is reshaping competitive dynamics in refurbished medical imaging, lowering barriers for mid-sized providers to access premium modalities. GE HealthCare leverages its OEM refurbishment pipelines to sustain certified pre-owned CT and MRI programs across North America and Europe. Siemens Healthineers anchors its market position through comprehensive warranty structures and remote service integration for refurbished installations. Block Imaging International competes on price-accessible sourcing networks, specializing in late-model systems from decommissioned hospital fleets.
Refurbished medical imaging equipment comprises previously installed diagnostic systems restored to manufacturer-specified performance through component replacement, software updates, and calibration against original technical parameters such as spatial resolution, contrast-to-noise ratio, and dose efficiency metrics; these systems serve healthcare providers seeking diagnostic parity at reduced capital outlay. Magnetic Resonance Imaging and Computed Tomography dominate product type revenue pools due to high replacement costs and extended useful lives under refurbishment protocols. Digital Radiography leads technology adoption as film-based imaging retreats to cost-constrained rural clinics, while 3D Imaging reconstruction capabilities are expanding fastest among oncology diagnostics applications requiring volumetric analysis.
The FDA enforces 510(k) premarket notification for refurbished devices, while the EU Medical Device Regulation mandates notified body oversight and unique device identification traceability, collectively elevating compliance costs for uncertified refurbishers and favoring OEM-backed programs. ISO 13485 quality management systems and IEC 60601 electrical safety standards further constrain market entry for non-specialized operators. Stakeholders must monitor evolving reimbursement policies for refurbished equipment across national health systems and assess whether OEM certification programs will consolidate secondary-market supply or preserve independent refurbisher viability.
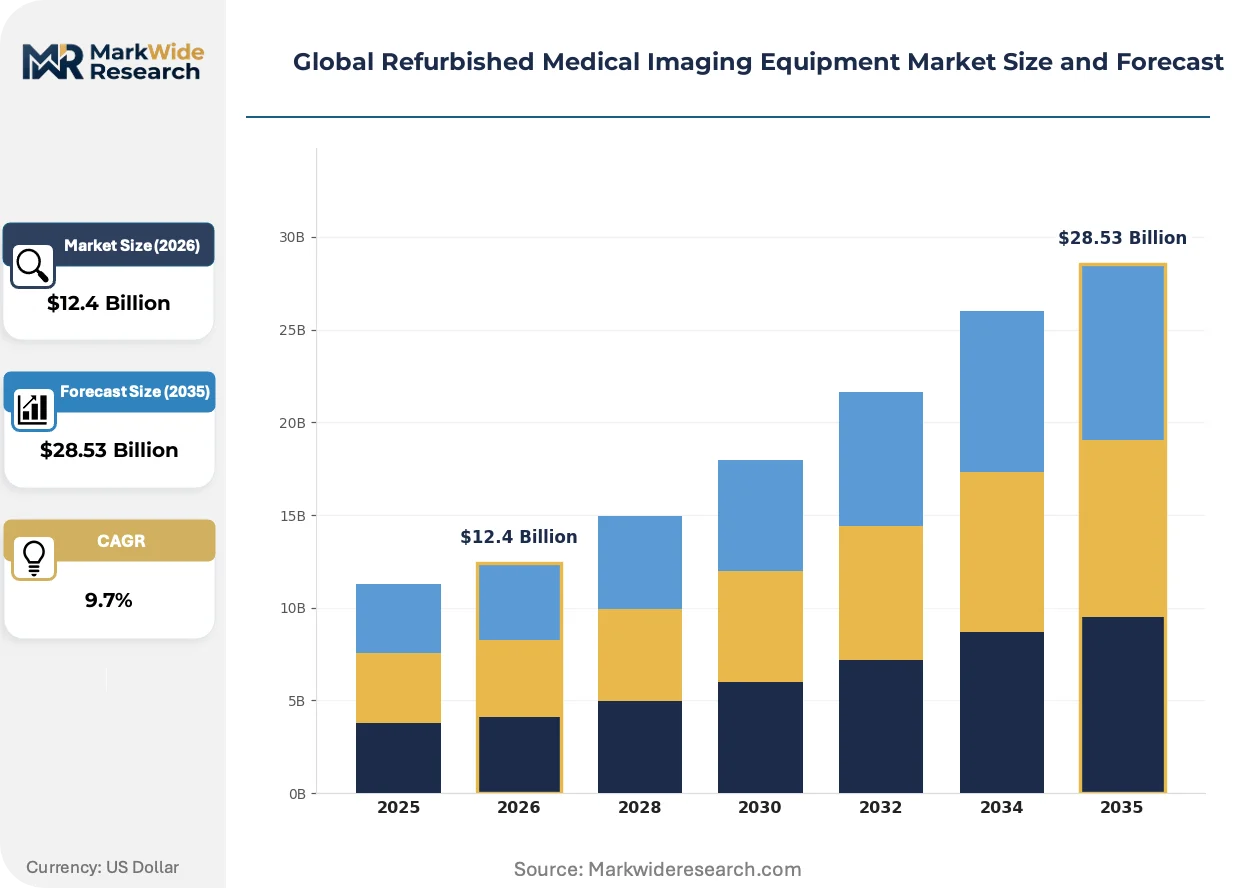
Market Dynamics
Equipment leasing and pay-per-scan financing are compressing capital barriers for mid-sized diagnostic providers, redirecting procurement flows toward certified pre-owned CT and MRI systems across North America, Europe, and emerging Asian markets.
Growth Catalysts
- FDA 510(k) Clearance Pathway:The streamlined premarket notification process for refurbished devices accelerates regulatory approval timelines, enabling faster commercialization of restored imaging systems in the United States.
- Diagnostic Laboratories:Capital-constrained facilities in India are accelerating procurement of refurbished CT and MRI equipment to expand imaging capacity without premium OEM pricing.
- Extended Useful Lives:Refurbishment protocols now restore spatial resolution and contrast-to-noise ratios to manufacturer specifications, preserving diagnostic parity at reduced capital outlay.
Market Restraints
- EU Medical Device Regulation Compliance:Notified body oversight and unique device identification traceability requirements elevate certification costs for independent refurbishers, favoring OEM-backed programs.
- Component Supply Concentration:Specialized detector arrays and gradient coil assemblies concentrate among limited suppliers in Germany and Japan, creating input bottlenecks for high-field MRI restoration.
- Substitution by Digital Radiography:Flat-panel detector systems are displacing refurbished film-based equipment in cost-constrained rural clinics, narrowing the addressable market for legacy modality refurbishment.
Strategic Opportunities
- Oncology Diagnostics:3D imaging reconstruction capabilities represent the fastest-expanding application segment, with volumetric analysis requirements driving demand for refurbished systems with advanced software packages.
- Remote Service Integration:Telemedicine-enabled maintenance protocols allow refurbishers to extend warranty coverage across dispersed installations, opening rural and semi-urban geographies previously served only by OEM field engineers.
- India Hospital Chains:Mumbai and Delhi-based health systems are standardizing on certified pre-owned equipment procurement frameworks, creating scalable demand templates for replication in Bangalore and Hyderabad.
Industry Challenges
- ISO 13485 Certification Timelines:Quality management system audits and IEC 60601 electrical safety testing create extended validation periods that strain working capital for independent operators.
- Legacy System Integration:PACS compatibility and DICOM conformance testing for refurbished modalities from decommissioned hospital fleets requires specialized software engineering capabilities that concentrate among experienced technicians.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refurbished Medical Imaging Equipment Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Resonance Imaging, Computed Tomography, Ultrasound Systems, X-ray Machines, Positron Emission Tomography Technology: Digital Radiography, Film-Based Imaging, Computer-Aided Detection, Image Processing Software, 3D Imaging Application: Oncology Diagnostics, Cardiovascular Assessment, Orthopedic Imaging, Neurology Screening, Pulmonary Examination End User: Hospitals, Diagnostic Laboratories, Specialty Clinics, Imaging Centers, Mobile Health Units |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Block Imaging International, Soma Technology, Avante Health Solutions, Hitachi Healthcare Systems, Radiology Oncology Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refurbished Medical Imaging Equipment Market Shifts & Advancements
Artificial intelligence is embedding into refurbished imaging workflows, compressing reconstruction times and enabling remote quality assurance that previously required on-site physicist verification.
Cloud-native reconstruction software is virtualizing post-processing workloads that previously demanded dedicated workstation hardware. Diagnostic networks in the United Kingdom are adopting subscription-based AI augmentation for refurbished CT systems, eliminating per-site software licensing. This architecture is virtualizing the capital boundary between premium and economy-tier refurbished equipment, allowing mid-range systems to match high-end diagnostic throughput through off-premise compute.
EU Medical Device Regulation mandates for unique device identification traceability are reshaping documentation requirements across the secondary market. Refurbishers must now maintain component-level provenance records through entire device lifecycles, elevating information systems investment. Independent operators in Poland and Spain are consolidating to share compliance infrastructure costs, while OEM programs absorb these requirements through existing quality management systems.
Hospital procurement departments are unbundling after-sales service contracts from equipment acquisition, negotiating direct maintenance agreements with third-party service organizations. This pattern concentrates among National Health Service trusts in England and integrated delivery networks in Texas and Florida. The disintermediation compresses OEM service margins while elevating demand for refurbishers with in-house biomedical engineering capabilities and spare parts inventories.
Global Refurbished Medical Imaging Equipment Market Segmentation
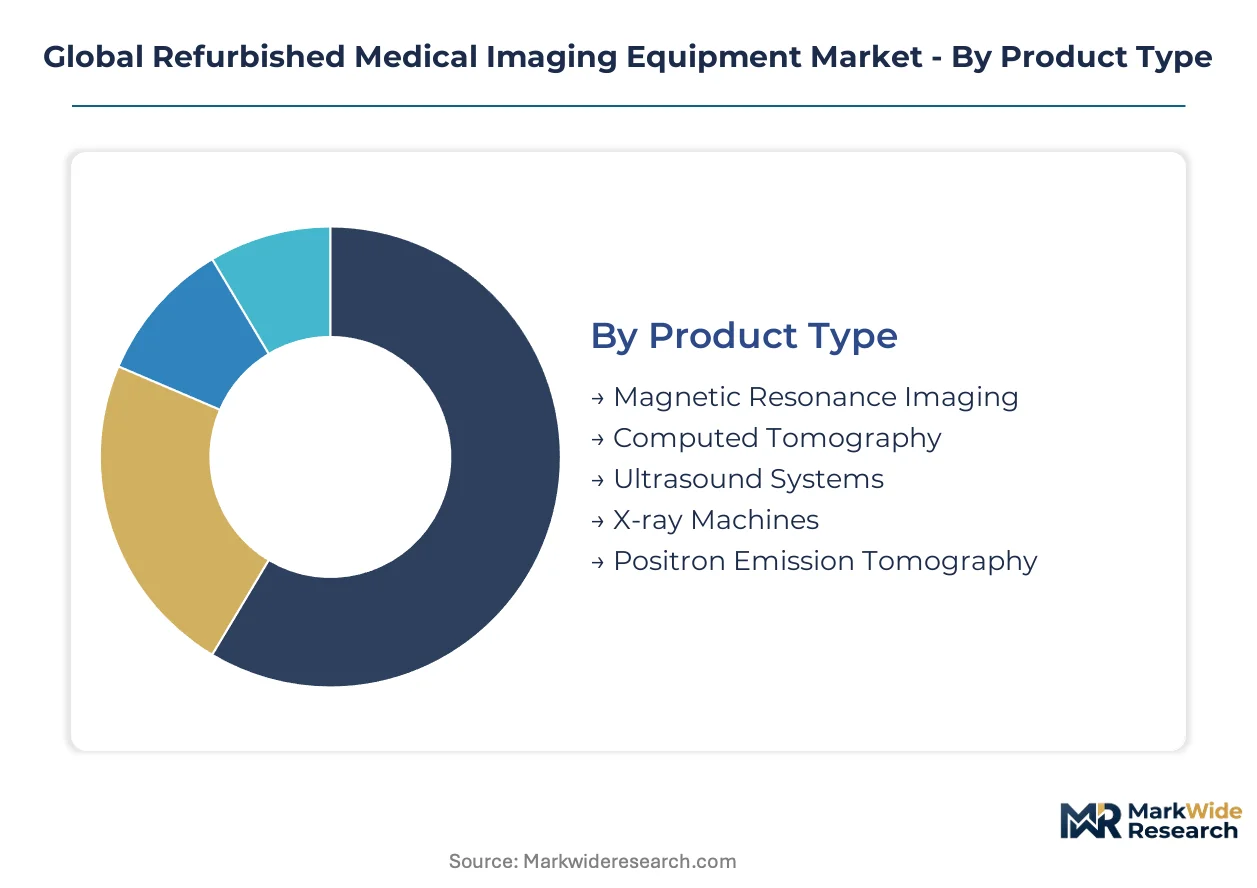
Segmentation in refurbished medical imaging equipment reveals how procurement patterns diverge across capital tiers, clinical applications, and facility capabilities. Understanding these dimensions allows suppliers to align certification programs with specific performance requirements and compliance obligations.
Product Type:
Cost tier stratification dominates procurement decisions, with capital outlay determining access to specific modalities across healthcare systems.
- Magnetic Resonance Imaging:High-field systems require gradient coil refurbishment and cryogen management to restore Tesla specifications. Hospital chains in India concentrate demand for 1.5T refurbished units as MRI access expands beyond tertiary centers.
- Computed Tomography:Detector array replacement and iterative reconstruction software updates restore dose efficiency metrics. Diagnostic laboratories in emerging markets accelerate CT procurement to manage rising oncology screening volumes without premium capital deployment.
- Ultrasound Systems:Transducer probe refurbishment and firmware updates restore acoustic output specifications for point-of-care deployment.
- X-ray Machines:Generator recalibration and grid replacement address film-to-digital conversion requirements in rural clinics.
- Positron Emission Tomography:Cyclotron sourcing constraints and radiopharmaceutical logistics limit refurbishment scalability to major academic medical centers.
Magnetic Resonance Imaging commands the established base. The steepest expansion runs through Computed Tomography.
Technology:
Application maturity separates legacy modalities from digitally native platforms, with software capabilities increasingly determining diagnostic parity.
- Digital Radiography:Flat-panel detector refurbishment and calibration against DICOM conformance standards enable PACS integration. Mobile health units in Texas and Florida adopt portable DR systems for rural deployment where fixed installation costs prove prohibitive.
- 3D Imaging:Volumetric reconstruction algorithms and GPU-accelerated post-processing expand oncology diagnostic capabilities. Imaging centers in the United Kingdom prioritize refurbished CT systems with cloud-native 3D reconstruction to eliminate per-site workstation hardware.
- Film-Based Imaging:Processor chemistry management and darkroom infrastructure sustain niche demand in cost-constrained rural clinics.
- Computer-Aided Detection:AI algorithm licensing and training dataset validation create software-dependent value differentiation.
- Image Processing Software:Subscription-based licensing models virtualize the capital boundary between mid-range and premium refurbished equipment tiers.
Digital Radiography maintains volume leadership. 3D Imaging gains share fastest through oncology application expansion.
Application:
Customer type specialization determines equipment specification requirements, with oncology and cardiovascular segments driving premium modality demand.
- Oncology Diagnostics:Volumetric analysis requirements and multi-phase contrast protocols demand high-resolution reconstruction capabilities. Hospital chains in Mumbai and Delhi standardize on refurbished PET-CT and advanced MRI for radiation therapy planning.
- Cardiovascular Assessment:ECG-gated acquisition and coronary calcium scoring require temporal resolution restoration through detector calibration. Specialty clinics in Germany concentrate demand for refurbished cardiac CT systems with dual-source capabilities.
- Orthopedic Imaging:Weight-bearing extremity protocols and metal artifact reduction serve ambulatory surgical center requirements.
- Neurology Screening:Diffusion-weighted imaging and perfusion sequences demand gradient coil performance verification.
- Pulmonary Examination:Low-dose protocols and emphysema quantification drive CT refurbishment specifications.
Oncology Diagnostics anchors revenue concentration. Cardiovascular Assessment shows the strongest volume trajectory.
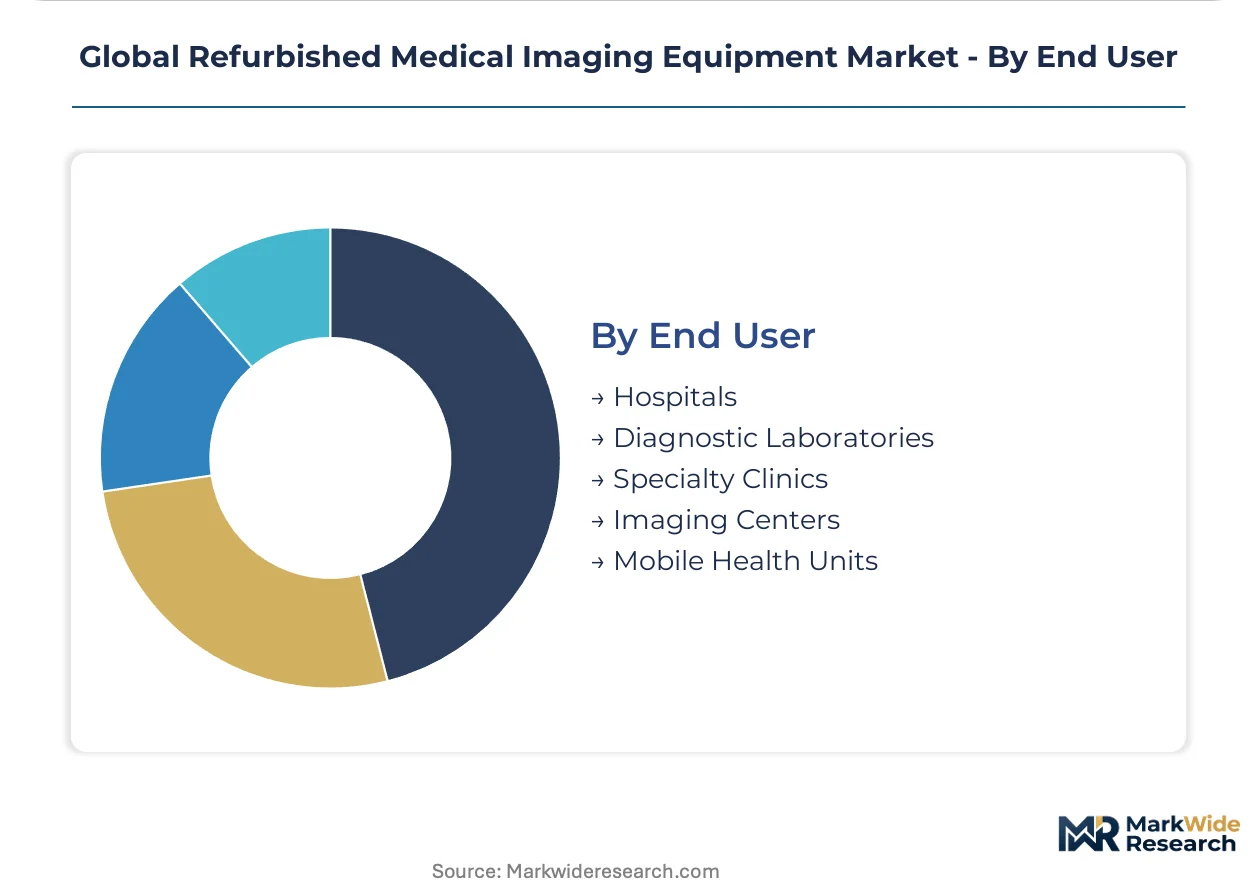
End User:
Geography and facility scale determine procurement authority, with hospital chains and diagnostic laboratories diverging on certification requirements.
- Hospitals:Multi-modality integration and enterprise PACS compatibility require OEM-backed certification with comprehensive warranty structures. Integrated delivery networks in Texas and Florida unbundle service contracts to negotiate direct maintenance agreements.
- Diagnostic Laboratories:High throughput demands and capital constraints favor independent refurbishers with rapid turnaround capabilities. Facilities in India accelerate procurement of certified pre-owned CT and MRI systems to expand imaging capacity.
- Specialty Clinics:Single-modality focus and limited biomedical engineering staff prioritize remote service integration.
- Imaging Centers:Pay-per-scan financing alignment and equipment leasing structures compress capital barriers for mid-tier refurbished systems.
- Mobile Health Units:Transport durability and generator power requirements constrain modality selection to robust refurbished platforms.
Hospitals retain the largest installed base. Diagnostic Laboratories are expanding most quickly through emerging market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways and EU Medical Device Regulation compliance costs are redirecting procurement flows toward certified refurbishment programs in mature markets, while capital constraints in emerging economies accelerate secondary-market equipment adoption.
United States
Integrated delivery networks in Texas and Florida unbundle service contracts to negotiate direct maintenance agreements with third-party biomedical engineering providers. FDA enforcement of 510(k) premarket notification elevates certification barriers for independent refurbishers. Hospital procurement departments in Houston and Dallas concentrate demand for OEM-backed CT and MRI restoration with comprehensive warranty structures.
Germany
Specialty cardiac clinics concentrate demand for refurbished dual-source CT systems with ECG-gated acquisition capabilities. EU Medical Device Regulation mandates for notified body oversight and unique device identification traceability reshape documentation requirements. Industrial clusters in Bavaria and North Rhine-Westphalia host refurbishment operations serving radiation therapy planning departments across Central Europe.
India
Hospital chains in Mumbai and Delhi standardize procurement frameworks for certified pre-owned equipment to expand imaging capacity without premium capital deployment. Central Drugs Standard Control Organization oversight governs medical device import and distribution licensing. Diagnostic laboratories in Bangalore and Hyderabad replicate scalable demand templates for refurbished 1.5T MRI and advanced CT systems.
United Kingdom
National Health Service trusts adopt subscription-based AI augmentation for refurbished CT systems, eliminating per-site software licensing costs. Medicines and Healthcare products Regulatory Agency enforcement aligns with EU MDR transitional provisions for secondary-market equipment. Imaging networks in London and Manchester prioritize cloud-native 3D reconstruction capabilities for oncology diagnostics.
Japan
Ministry of Economy, Trade and Industry industrial policy supports domestic refurbishment capabilities for high-field MRI gradient coil assemblies. Pharmaceuticals and Medical Devices Agency quality management requirements constrain market entry for non-specialized operators. Medical equipment distributors in Osaka and Nagoya concentrate sourcing networks for late-model systems from decommissioned hospital fleets.
Global Refurbished Medical Imaging Equipment Market Competitive Landscape
On the supply side, the industry is consolidating around OEM-backed certification programs and specialized independent refurbishers with in-house biomedical engineering capabilities. Three strategic archetypes dominate: original equipment manufacturers leveraging factory refurbishment pipelines, independent specialists competing on price-accessible sourcing networks, and diversified health technology conglomerates integrating remote service platforms. Competitive moves concentrate on M&A to absorb compliance infrastructure costs and strategic partnerships to secure component supply for high-field MRI restoration.
Within the OEM archetype, GE HealthCare and Siemens Healthineers occupy positions anchoring certified pre-owned programs across North America and Europe with comprehensive warranty structures and remote service integration. Among independent specialists, Block Imaging International exemplifies the price-accessible sourcing model, concentrating on late-model systems from decommissioned hospital fleets with rapid turnaround capabilities. Koninklijke Philips N.V. sits within the diversified health technology tier, representing integrated diagnostic imaging portfolios that span primary and secondary equipment markets.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Block Imaging International |
| Soma Technology |
| Avante Health Solutions |
| Hitachi Healthcare Systems |
| Radiology Oncology Systems |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Japanese gradient coil assemblies concentrates refurbishment cost risk and compresses margin structures across certification tiers. FDA 510(k) clearance timelines and EU Medical Device Regulation compliance investments amplify working capital requirements, forcing independent refurbishers toward OEM partnership models or geographic consolidation to absorb fixed documentation costs.
Pricing Analysis
Certification level (ISO 13485/FDA 510(k)/CE-MDR grade) creates the primary spread between premium OEM-backed programs and independent refurbishment offerings. Three-tier pricing structure across OEM-certified, third-party certified, and uncertified equipment tiers reflects warranty duration, remote service integration depth, and software update entitlements. Cost compression in the independent tier is intensifying because CDSCO import licensing delays in India and extended IEC 60601 validation periods strain liquidity for smaller operators. Diagnostic laboratories in emerging markets exhibit the highest price sensitivity, prioritizing rapid turnaround over comprehensive warranty structures, while integrated delivery networks in Texas and Florida demonstrate lowest sensitivity when bundling service contracts with equipment acquisition.
Supply Chain Analysis
Contract manufacturing for detector arrays and cryogen management systems concentrates among specialized electronics manufacturers in Germany, Japan, and the United States. Refurbishment operations draw from decommissioned hospital fleets in North America and Western Europe as primary equipment sources, with component harvesting feeding secondary parts markets. Single-source vulnerability in superconducting wire supply for high-field MRI gradient coils creates bottleneck risk for 3T system restoration. Distribution runs through medical equipment distributors with biomedical engineering capabilities, hospital procurement departments unbundling service contracts, and direct refurbishment-to-provider relationships in cost-constrained markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now govern competitive positioning as cloud-native reconstruction software and subscription-based AI augmentation virtualize the capital boundary between equipment tiers. Interoperability requirements for PACS integration and DICOM conformance are consolidating procurement authority around vendors with end-to-end digital infrastructure.
For Market Incumbents: Insulate certified pre-owned programs against independent price competition by deepening backward integration into component remanufacturing for gradient coils and detector arrays. Accelerate ISO 13485 certification pipelines in Poland and Spain through shared compliance infrastructure investments, neutralizing the emerging threat of consolidated independent operators achieving MDR economies of scale. For New Entrants and Emerging Players: Diagnostic laboratories in Bangalore and Hyderabad represent the most penetrable entry point, replicating Mumbai and Delhi procurement frameworks for refurbished 1.5T MRI systems. Remote service integration capabilities for dispersed rural installations in India offer a go-to-market angle that bypasses OEM field engineer density advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified health technology conglomerates with existing quality management systems. Long-term viability hinges on regulatory compliance infrastructure rather than sourcing network scale alone. Watch for CDSCO enforcement patterns on import licensing as the inflection indicator for independent refurbisher viability in emerging markets.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Compliance Infrastructure Sharing | Polish and Spanish refurbishers consolidate to split notified body audit costs under EU Medical Device Regulation. |
| Cloud-Native Reconstruction Licensing | UK NHS trusts eliminate per-site workstation hardware through subscription-based AI augmentation for refurbished CT. |
| Gradient Coil Remanufacturing Investment | OEM-backed programs secure captive supply of high-field MRI components against German and Japanese supplier concentration. |
| Direct Maintenance Agreement Expansion | Texas and Florida IDNs bypass OEM service margins by contracting third-party biomedical engineering providers. |
| CDSCO Import Licensing Acceleration | Mumbai and Delhi hospital chains standardize procurement frameworks to reduce regulatory delay in certified pre-owned equipment sourcing. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with hospital procurement managers, biomedical engineering directors, GPO contracts specialists, and independent refurbishment operators; and secondary validation against FDA 510(k) clearance databases, EU MDR notified body registries, CDSCO import licensing records, and hospital procurement databases. Bottom-up equipment flow modeling triangulated against top-down market sizing across product type, technology, application, and end-user segmentation dimensions.
Forecast inputs incorporated refurbishment protocol standardization trends, regulatory compliance cost trajectories, and capital constraint patterns across emerging market diagnostic networks. Segmentation modeling spanned product type (MRI, CT, ultrasound, X-ray, PET), technology tier (digital radiography, 3D imaging, film-based, CAD, software), application (oncology, cardiovascular, orthopedic, neurology, pulmonary), and end-user archetype (hospitals, diagnostic laboratories, specialty clinics, imaging centers, mobile health units). CAGRs derived from equipment replacement cycle analysis and procurement intention surveys across the projection horizon.
Practitioners should monitor FDA enforcement patterns on 510(k) premarket notification, EU MDR transitional provision deadlines, and CDSCO import licensing throughput for early signals of competitive structure shifts. Quarterly review of notified body audit backlogs, gradient coil supplier delivery lead times, and AI reconstruction software licensing adoption rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Fluorescein Angiography Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Point of Care (POC) CT Imaging Systems Market
Medical Imaging
Contrast Media Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Perfusion Imaging Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
France Digital Radiology Market
Medical Imaging
Global Contrast Enhanced Digital Mammography (CEDM) Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
India Magnetic Resonance Imaging Market
Medical Imaging
Australia Magnetic Resonance Imaging Market