
 Americas Interventional Radiology Market | 2026-2036
Americas Interventional Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Interventional Radiology Market Outlook
Hospital procurement consortiums across the Americas are reshaping how interventional radiology devices reach end users, with group purchasing organizations consolidating contract volumes and squeezing distributor margins. Boston Scientific leverages its direct sales infrastructure to bypass traditional distribution layers and secure multi-year catheter supply agreements with major health systems. Medtronic anchors its position through backward integration into guidewire manufacturing, while Siemens Healthineers competes by bundling imaging hardware with software service contracts that lock in recurring revenue streams.
Interventional radiology encompasses image-guided, minimally invasive diagnostic and therapeutic procedures performed using percutaneous access techniques under real-time visualization, typically requiring fluoroscopy systems capable of sub-millimeter spatial resolution and dose modulation below 3 mGy per minute for patient safety. The primary purpose spans vascular recanalization, tumor ablation, and fluid drainage across cardiology, oncology, and urology applications. Catheters and guidewires constitute the mature volume base where manufacturing scale determines unit economics, while stent platforms command premium positioning due to drug-eluting surface engineering and prolonged regulatory pathways. Imaging modality segmentation shows X-ray fluoroscopy retaining dominance in procedural volume, though CT-guided interventions are capturing margin pools in complex ablation cases where three-dimensional anatomical mapping justifies higher reimbursement.
FDA premarket notification pathways and CMS national coverage determinations govern product entry and reimbursement access across the United States, while Health Canada and ANVISA impose parallel but divergent clinical evidence requirements that fragment regulatory strategy for manufacturers. The IRA's Medicare price negotiation provisions for selected physician-administered drugs indirectly pressure interventional radiology departments to justify procedure volumes through outcome documentation. Stakeholders must monitor how FDA breakthrough device designations for AI-assisted navigation tools will reshape training requirements and capital allocation across outpatient clinic networks.
Market Dynamics
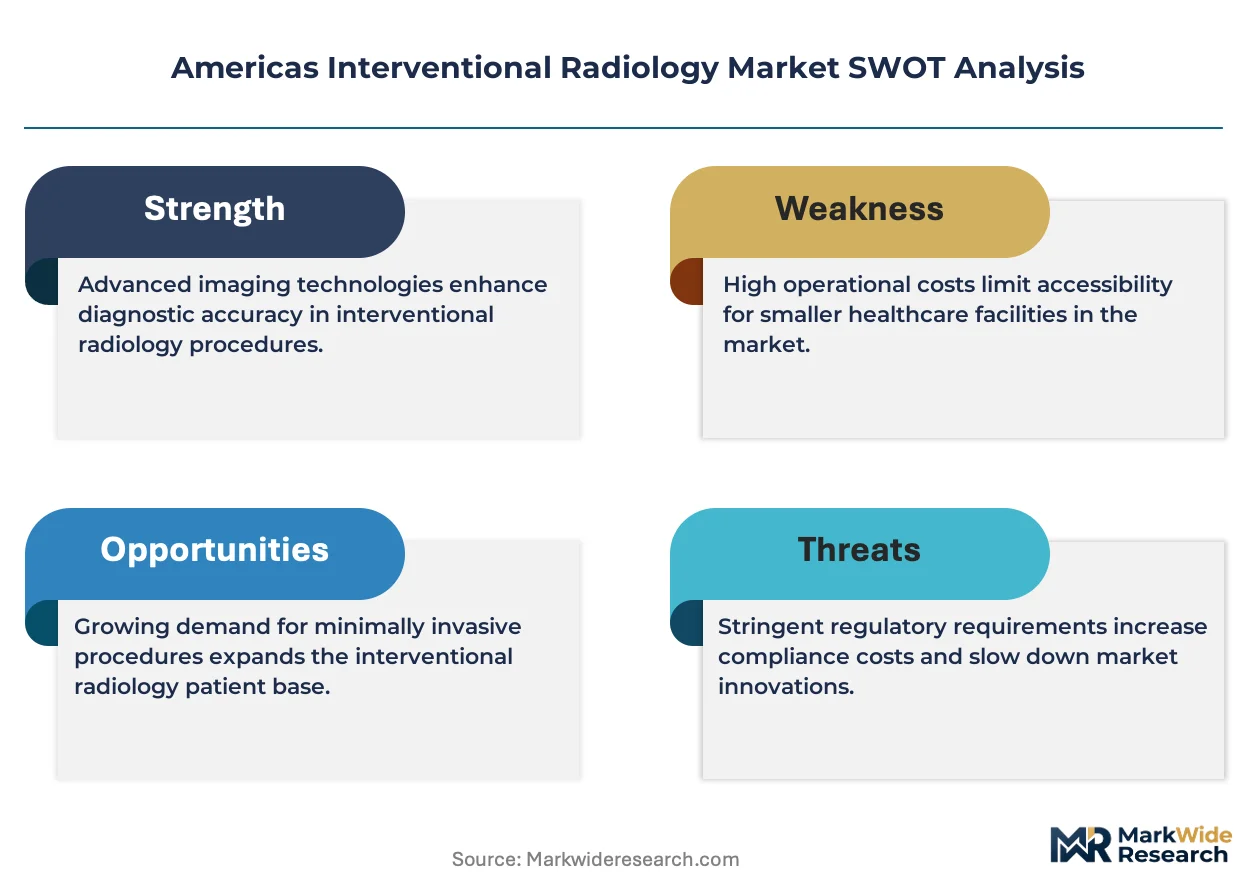
CMS reimbursement shifts toward outpatient settings are compressing hospital capital cycles and forcing catheterization labs to justify capacity expansion through documented patient throughput rather than procedural prestige alone.
Growth Catalysts
- IRA Medicare Provisions:The Inflation Reduction Act's price negotiation framework for physician-administered drugs incentivizes interventional radiology departments to document outcome metrics and expand qualifying procedure volumes.
- Texas and Florida IDN Expansion:Integrated delivery networks in these states are building dedicated interventional radiology service lines with standalone outpatient facilities to capture shifting reimbursement differentials.
- AI-Assisted Navigation:FDA breakthrough device designations for machine learning-guided catheter positioning tools are reducing fluoroscopy exposure times and expanding treatable patient populations.
Market Restraints
- Guidewire Supply Concentration:Backward integration by dominant manufacturers has consolidated captive production of nitinol core wires, limiting second-source options for mid-tier catheter assemblers.
- FDA 510(k) Pathway Friction:Substantial equivalence determinations for next-generation drug-eluting stents now require extended bench testing data, stretching premarket notification timelines.
- CT-Guided Substitution:Complex ablation cases are migrating toward computed tomography navigation systems that command higher reimbursement but require entirely separate capital infrastructure.
Strategic Opportunities
- Brazil ANVISA Harmonization:Convergence between Brazilian and FDA clinical evidence requirements creates pathway for US-validated devices to enter Latin American markets with reduced duplicate trials.
- Software Service Bundling:Imaging hardware vendors are locking recurring revenue through AI-powered procedural planning subscriptions attached to fluoroscopy system leases.
- Canada Health Technology Assessment:CADTH reimbursement reviews for same-day discharge procedures create tailwind for ambulatory surgical centers adopting minimally invasive tumor ablation protocols.
Industry Challenges
- Cross-Training Bottlenecks:Radiologists transitioning from diagnostic to interventional practice require proctored case volumes that exceed current fellowship pipeline capacity in Texas and Florida training programs.
- Legacy PACS Integration:New navigation software platforms face interoperability friction with installed picture archiving systems, delaying deployment timelines in hospital networks with fragmented IT estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Interventional Radiology Market |
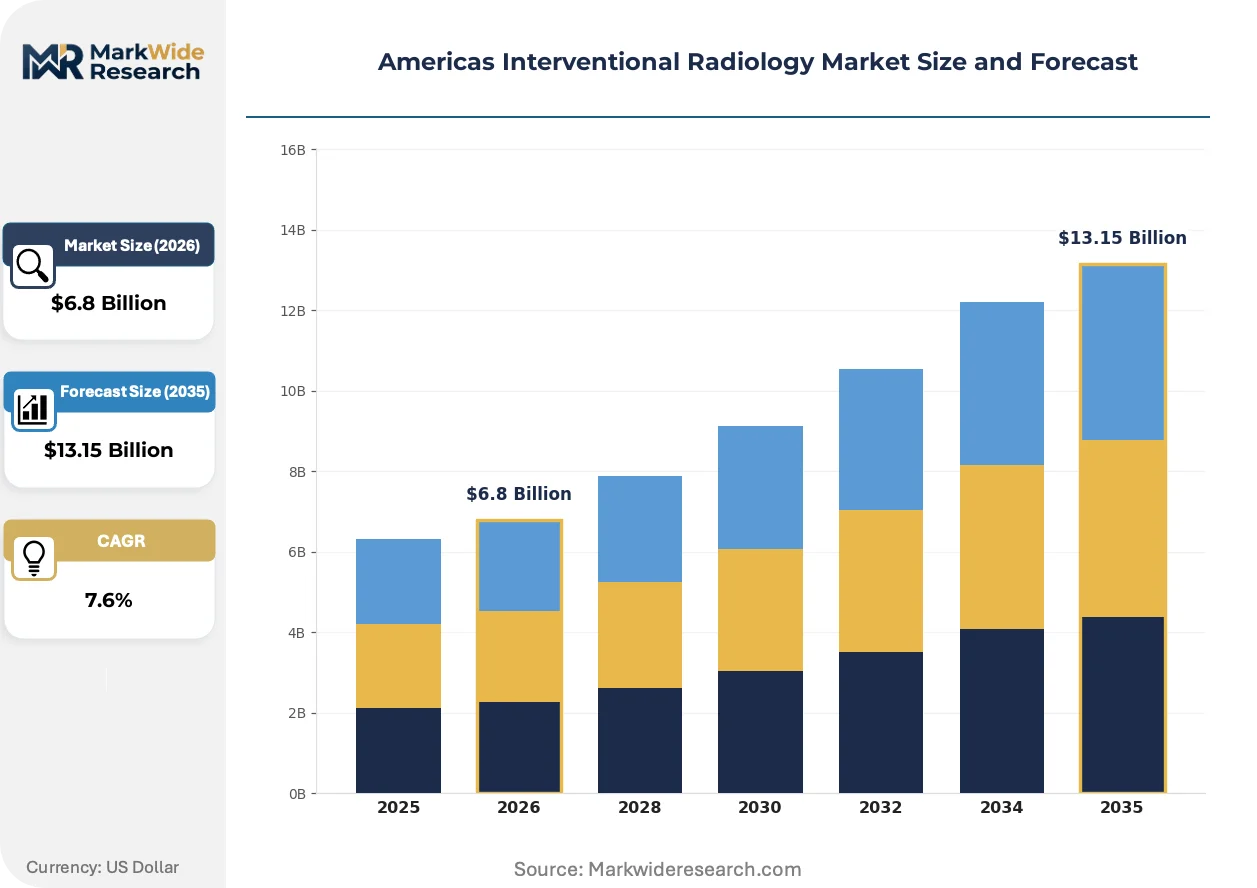
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Guidewires, Balloons, Stents Technology: X-ray Imaging, Ultrasound, MRI, CT End User: Hospitals, Outpatient Clinics, Diagnostic Centers, Specialty Clinics Application: Cardiology, Oncology, Urology, Vascular |
| Companies Covered | Boston Scientific Corporation, Medtronic, Abbott Laboratories, GE HealthCare, Siemens Healthineers, Philips Healthcare, Stryker Corporation, Cook Medical, Terumo Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Interventional Radiology Market Strategic Shifts
Fluoroscopy systems are incorporating real-time three-dimensional overlay capabilities that merge preoperative CT datasets with live X-ray positioning, compressing the learning curve for complex vascular access.
Robotic catheter manipulation platforms is hybridizing mechanical precision with haptic feedback systems originally developed for laparoscopic surgery. Academic medical centers in California and Massachusetts are piloting these systems for neurointerventional procedures where tremor elimination outweighs capital cost premiums. The technology is hybridizing the skill requirements for complex recanalization cases, enabling community hospitals to retain patients who previously transferred to tertiary centers.
CMS national coverage determinations for same-day discharge after peripheral arterial interventions have eliminated prior inpatient stay requirements that governed reimbursement for two decades. Device manufacturers now face pressure to demonstrate 23-hour complication rates below 2% to maintain coverage eligibility. Ambulatory surgery centers in Arizona and Colorado are responding by standardizing discharge protocols and remote monitoring handoffs.
Group purchasing organizations have consolidated contract volumes for catheters and guidewires into multi-year sole-source agreements that bypass traditional distributor markups. Hospital procurement consortiums in the Southeast and Midwest are replacing spot-buying with committed volume tiers that exchange price concessions for demand visibility. This concentration is most visible among Catholic health systems operating across Illinois, Wisconsin, and Missouri, where standardization mandates override individual physician preference items.
Americas Interventional Radiology Market Segmentation
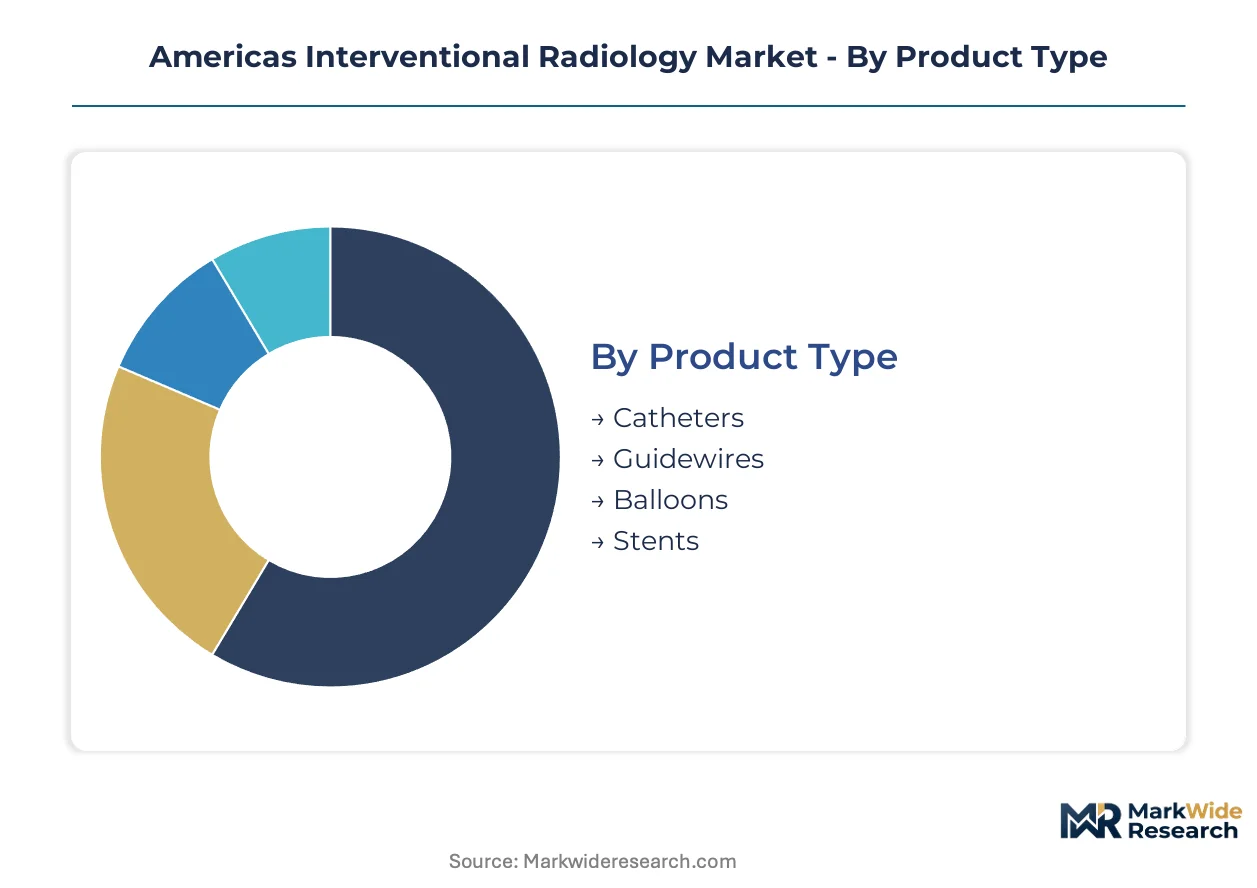
Interventional radiology devices serve distinct clinical workflows where product specifications, imaging modality, and care setting each impose unique procurement criteria. Segmentation reveals how margin pools concentrate in drug-eluting platforms and how reimbursement shifts are redistributing volume across facility types.
Product Type:
Cost tier stratification separates commodity consumables from engineered platforms requiring extended regulatory validation and specialized manufacturing.
- Catheters:Polymer-based delivery systems with variable durometer shafts and hydrophilic coatings dominate procedural volume. Texas and Florida hospital networks are consolidating catheter procurement through multi-year sole-source agreements that exchange price concessions for demand visibility.
- Stents:Drug-eluting metal scaffolds with bioresorbable polymer matrices command premium positioning due to surface engineering complexity and prolonged FDA premarket notification pathways. Integrated delivery networks prioritize stent platforms with documented 23-hour complication rates below 2% to maintain CMS coverage eligibility for same-day discharge protocols.
- Guidewires:Nitinol core wires with torque-responsive distal segments enable vascular navigation across tortuous anatomy.
- Balloons:Compliant and non-compliant inflation systems facilitate lesion preparation and vessel remodeling.
Catheters command the established base. The steepest expansion runs through stent platforms with drug-eluting surface engineering.
Technology:
Application requirements determine imaging modality selection, with procedural complexity and reimbursement differentials driving capital allocation across hardware categories.
- X-ray Imaging:Fluoroscopy systems with sub-millimeter spatial resolution and dose modulation below 3 mGy per minute retain procedural volume dominance. Real-time three-dimensional overlay capabilities merging preoperative CT datasets with live positioning are compressing learning curves for complex vascular access in community hospital settings.
- CT:Three-dimensional anatomical navigation systems capture margin pools in complex ablation cases where enhanced visualization justifies higher reimbursement. Arizona and Colorado ambulatory surgery centers are deploying CT-guided protocols for tumor ablation with standardized same-day discharge pathways.
- Ultrasound:Portable systems with Doppler capability enable bedside vascular access and drainage procedures.
- MRI:Magnetic resonance-guided interventions serve niche applications requiring soft tissue contrast without ionizing radiation.
X-ray imaging anchors current installed base. CT navigation is climbing the fastest as reimbursement differentials reward complex ablation cases.
End User:
Customer type segmentation tracks how CMS reimbursement shifts are redistributing procedural volume across facility categories with distinct capital cycles and staffing models.
- Hospitals:Academic medical centers and community hospitals with catheterization lab infrastructure perform high-acuity interventions requiring overnight observation capabilities. California and Massachusetts academic centers are piloting robotic catheter manipulation platforms for neurointerventional procedures.
- Outpatient Clinics:Standalone interventional radiology facilities in Texas and Florida are capturing shifting reimbursement differentials through dedicated service lines with 23-hour recovery protocols.
- Diagnostic Centers:Imaging-focused facilities perform image-guided biopsies and fluid drainage with radiologist oversight.
- Specialty Clinics:Cardiology and oncology focused practices integrate interventional procedures into disease-specific care pathways.
Hospitals retain the high-acuity core. Outpatient clinics are gaining share fastest as CMS national coverage determinations eliminate prior inpatient stay requirements.
Application:
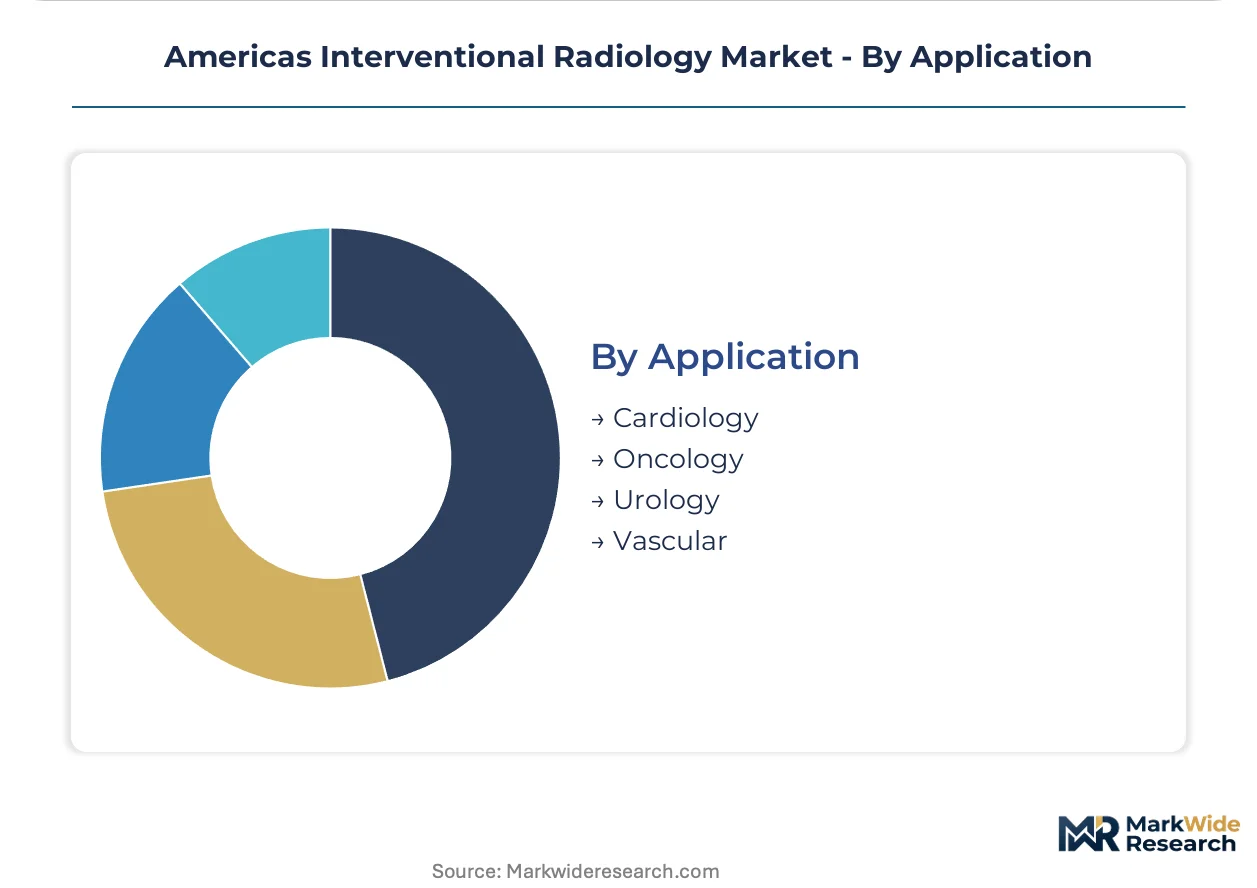
Clinical indication segmentation aligns device selection with anatomical target and therapeutic objective, with regulatory pathways varying by disease area.
- Cardiology:Coronary and peripheral arterial interventions drive guidewire and stent utilization, with CMS same-day discharge coverage for peripheral cases eliminating two-decade-old inpatient requirements. Device manufacturers face outcome documentation pressure to maintain coverage eligibility.
- Oncology:Tumor ablation and embolization procedures command premium navigation system utilization, with CT-guided three-dimensional mapping justifying higher reimbursement in complex cases.
- Vascular:Venous access and thrombus management procedures utilize catheter-directed therapies across hospital and ambulatory settings.
- Urology:Nephrostomy and ureteral interventions address obstructive pathologies with drainage and stent placement protocols.
Cardiology anchors procedural volume. Oncology applications are expanding most quickly as minimally invasive tumor ablation protocols penetrate ambulatory surgical centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing leverage concentrates in the United States while procurement standardization spreads through Canadian health networks, creating a two-tier margin structure across the Americas interventional radiology landscape.
United States
Integrated delivery networks in Texas and Florida are building dedicated interventional radiology service lines with standalone outpatient facilities to capture CMS reimbursement shifts. The Inflation Reduction Act's Medicare price negotiation provisions pressure departments to document outcome metrics and expand qualifying procedure volumes. California and Massachusetts academic medical centers pilot robotic catheter manipulation platforms for neurointerventional applications.
Canada
CADTH health technology assessment reviews for same-day discharge procedures create tailwind for ambulatory surgical centers adopting minimally invasive tumor ablation protocols. Health Canada imposes clinical evidence requirements that diverge from FDA pathways, fragmenting regulatory strategy for manufacturers entering the market. Ontario and Quebec hospital procurement consortiums consolidate contract volumes into multi-year agreements that exchange price concessions for demand visibility.
Brazil
Convergence between ANVISA and FDA clinical evidence requirements creates pathway for US-validated devices to enter Latin American markets with reduced duplicate trials. Private hospital networks in São Paulo and Rio de Janeiro expand catheterization lab capacity to serve growing demand for vascular recanalization procedures. The country's national pharmaceutical regulator maintains parallel but divergent standards that complicate market entry timelines.
Mexico
Hospital networks in Mexico City and Monterrey modernize imaging infrastructure to support CT-guided interventions capturing margin pools in complex ablation cases. Federal health programs expand access to minimally invasive procedures through public-private partnerships with equipment vendors. The central region concentrates private investment while northern border states align procurement standards with US reference pricing.
Americas Interventional Radiology Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in guidewire and catheter manufacturing where backward integration determines supply security. The vendor base stratifies across imaging hardware bundlers, drug-eluting platform engineers, and commodity consumables assemblers. Three archetypes dominate: integrated device manufacturers with captive production, imaging system vendors with software attachment strategies, and mid-tier catheter specialists dependent on second-source wire supply. Competitive moves concentrate on multi-year sole-source procurement agreements and AI-powered navigation software subscriptions.
Among US-based integrated device manufacturers, Boston Scientific Corporation and Medtronic occupy positions at the platform tier, while Siemens Healthineers represents the imaging-hardware-with-software-bundling archetype. These three exemplify how competitive positioning diverges between device-centric and system-centric revenue models across the Americas market.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic |
| Abbott Laboratories |
| GE HealthCare |
| Siemens Healthineers |
| Philips Healthcare |
| Stryker Corporation |
| Cook Medical |
| Terumo Corporation |
| Others |
Value Chain & Pricing Dynamics
Nitinol wire production concentrates in a handful of specialized metallurgical facilities across the United States and Japan, anchoring margin capture for guidewire assemblers who command premium positioning through captive supply arrangements while mid-tier catheter manufacturers absorb cost volatility from spot-market polymer sourcing.
Pricing Analysis
Configured-to-order pricing for drug-eluting stent platforms commands spreads exceeding standard balloon catheter pricing by multiples reflecting FDA PMA pathway investments and surface engineering complexity. Three-tier pricing structure across premium, standard, and economy levels segments by clinical outcome documentation and 23-hour complication rate thresholds. Cost compression in commodity catheters is intensifying because group purchasing organizations have consolidated contract volumes into multi-year sole-source agreements. Ambulatory surgery centers exhibit highest price sensitivity, while academic medical centers prioritize outcome metrics over unit cost.
Supply Chain Analysis
Contract manufacturing for polymer extrusion and hydrophilic coating application concentrates in Costa Rica, Mexico, and select US border states serving catheter assembly operations. Nitinol core wire draws from specialized titanium-nickel alloy foundries, polymer shafts rest on medical-grade polyurethane suppliers, and hydrophilic coatings hinge on proprietary surface chemistry providers. Single-source vulnerability runs through nitinol wire supply where backward integration by dominant manufacturers has eliminated second-source options. Distribution runs through direct sales infrastructure for premium platforms and distributor networks for commodity consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CT-guided ablation systems represent a direct substitute threat to fluoroscopy-based interventions, forcing incumbents to defend procedural volume through outcome documentation and capital efficiency improvements that preserve hospital network relationships.
For Market Incumbents: Entrench position through backward integration into nitinol wire production and AI-powered navigation software subscriptions that lock recurring revenue. Secure multi-year sole-source agreements with Texas and Florida integrated delivery networks before ambulatory surgery center expansion accelerates. Counter CT-guided substitution by demonstrating fluoroscopy dose reduction and real-time three-dimensional overlay capabilities that compress community hospital learning curves. For New Entrants and Emerging Players: Pursue white-space opportunities in Brazil and Mexico where ANVISA-FDA convergence reduces duplicate clinical trial requirements for US-validated devices. Target mid-tier catheter assembly where second-source wire supply constraints have weakened incumbent cost structures. Enter through contract manufacturing partnerships with Costa Rican and Mexican facilities serving US hospital networks seeking nearshore supply resilience. For Investors and Strategic Acquirers: Capital is best deployed toward imaging-hardware-with-software-bundling archetypes capturing recurring revenue through AI-powered procedural planning subscriptions attached to system leases. Long-term viability favors platform integrators with installed base density in Texas and Florida outpatient networks. Monitor FDA breakthrough device designations for robotic catheter manipulation as inflection signal for training requirement shifts and capital allocation toward community hospital retention strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Multi-year sole-source agreements with Texas and Florida IDNs secure demand visibility and bypass distributor markups. |
| Software Companion Development | AI-powered navigation subscriptions attached to fluoroscopy leases generate recurring revenue streams beyond hardware sales. |
| Reimbursement Strategy | CMS national coverage determination alignment for same-day discharge protocols preserves eligibility and procedural volume. |
| Backward Integration | Captive nitinol wire production eliminates second-source vulnerability and defends margin position against mid-tier competitors. |
| Regulatory Harmonization | ANVISA-FDA convergence exploitation accelerates Latin American market entry with reduced duplicate clinical evidence requirements. |
Study Parameters
The analysis maps catheter, guidewire, stent, and imaging system sub-sectors, each validated through interventional radiologists, hospital purchasing committees, GPO contracts managers, and biomedical engineers. Primary interviews with clinicians and procurement stakeholders combined with secondary validation from FDA 510(k) and PMA filings, CMS national coverage determinations, hospital procurement databases, and GPO contract repositories. Bottom-up device shipment modeling and top-down reimbursement flow analysis triangulate market sizing across the Americas.
Assumptions held fixed include CMS reimbursement parity between inpatient and outpatient settings, ANVISA-FDA regulatory convergence trajectory, and polymer raw material supply continuity from Costa Rican and Mexican contract manufacturers. Segmentation dimensions modeled span product type, imaging modality, end-user facility category, and clinical application across the projection horizon. CAGRs derived from procedural volume trends, reimbursement differential capture, and capital expenditure patterns in Texas and Florida integrated delivery networks.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement rates, nitinol alloy pricing, or trade policy affecting Costa Rican medical device exports would shift the trajectory. Forecasts reflect these assumptions without certainty guarantees. Quarterly review of FDA breakthrough device designations, CMS national coverage determinations, and GPO contract award announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South America CT Market
Medical Imaging
India Mammography Market
Medical Imaging
South America Mammography Market
Medical Imaging
Perfusion Radiology Market
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Pre-Clinical Imaging System Market
Medical Imaging
Global Medical Imaging Phantoms Market
Medical Imaging
Quantitative Pathology Imaging Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
US Magnetic Resonance Imaging Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
Dental Imaging Market
Medical Imaging
Middle East and Africa Clinical Trial Imaging Market