
 Precision Fermentation Ingredient Supplier Market | 2026-2036
Precision Fermentation Ingredient Supplier Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Fermentation Ingredient Supplier Market Insights
Downstream formulation partnerships is reconfiguring how ingredient suppliers capture value across the value chain. Perfect Day leverages captive production of whey proteins to anchor long-term supply agreements with CPG brands. Geltor differentiates through bioactive collagen peptides, sustaining premium positioning in cosmetics and personal care channels.
Precision fermentation ingredient suppliers deploy genetically engineered microbial hosts in bioreactor systems to synthesize target molecules such as proteins, enzymes, and lipids with purity levels exceeding conventional extraction methods. The process typically operates at 30–37°C with pH control between 6.5 and 7.5, yielding functional ingredients for food fortification and pharmaceutical excipient applications. Enzymes and proteins dominate current revenue pools, while amino acids and lipids represent the fastest-expanding categories as feed and biofuel applications mature. Fed-batch fermentation retains the largest installed base, though continuous fermentation systems are gaining traction for high-volume contract manufacturing.
FDA novel food consultations and EFSA regulatory science requirements shape product approval timelines and capital allocation decisions for suppliers targeting transatlantic markets. REACH compliance and EU Green Deal biomanufacturing incentives further condition facility siting and feedstock sourcing strategies in Europe. Stakeholders must monitor evolving strain classification protocols and carbon accounting standards to preserve market access and secure offtake agreements.
Market Dynamics
Downstream formulation partnerships are reconfiguring value capture across the precision fermentation value chain, as captive production of functional proteins enables long-term supply anchoring with CPG brands and premium positioning in cosmetics channels.
Growth Catalysts
- EFSA Novel Food Framework:Harmonized safety assessment pathways for fermentation-derived proteins are reducing regulatory fragmentation across EU member states, accelerating cross-border ingredient approvals.
- Plant-based dairy analogs:Food processing companies in the United States are scaling procurement of whey and casein alternatives, creating sustained offtake demand for precision fermentation suppliers.
- Continuous fermentation systems:High-volume contract manufacturers are adopting perfusion-based bioreactor configurations, improving volumetric productivity and reducing batch-to-batch variability for enzymes and bioactive peptides.
Market Restraints
- Feedstock cost volatility:Glucose and nitrogen source prices fluctuate with agricultural commodity cycles, compressing gross margins for fermentation operators without long-term supply contracts.
- San Francisco Bay Area supplier concentration:Venture-backed biotech firm clustering creates geographic risk exposure for CPG brands dependent on single-region production networks.
- FDA novel food consultation timelines:Extended pre-submission review periods for GRAS determinations delay commercial launches and tie up working capital in inventory hold.
Strategic Opportunities
- EU Green Deal biomanufacturing incentives:Carbon accounting standards and renewable energy integration subsidies are conditioning facility siting decisions toward Iberian and Nordic markets with low-carbon grid profiles.
- Pharmaceutical excipient applications:High-purity lipids and recombinant proteins for drug delivery systems represent an emerging demand vertical with pricing premiums above food-grade equivalents.
- CRISPR-Cas9 strain engineering convergence:Integration of gene editing with automated bioreactor control systems is opening new molecular targets previously inaccessible to conventional metabolic engineering.
Industry Challenges
- Strain classification protocol uncertainty:Evolving GMO disclosure requirements under REACH and national biotechnology frameworks complicate inventory labeling and customer communication strategies.
- Downstream processing capex intensity:Chromatography and membrane filtration infrastructure for purity specification consumes disproportionate capital relative to upstream fermentation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Fermentation Ingredient Supplier Market |
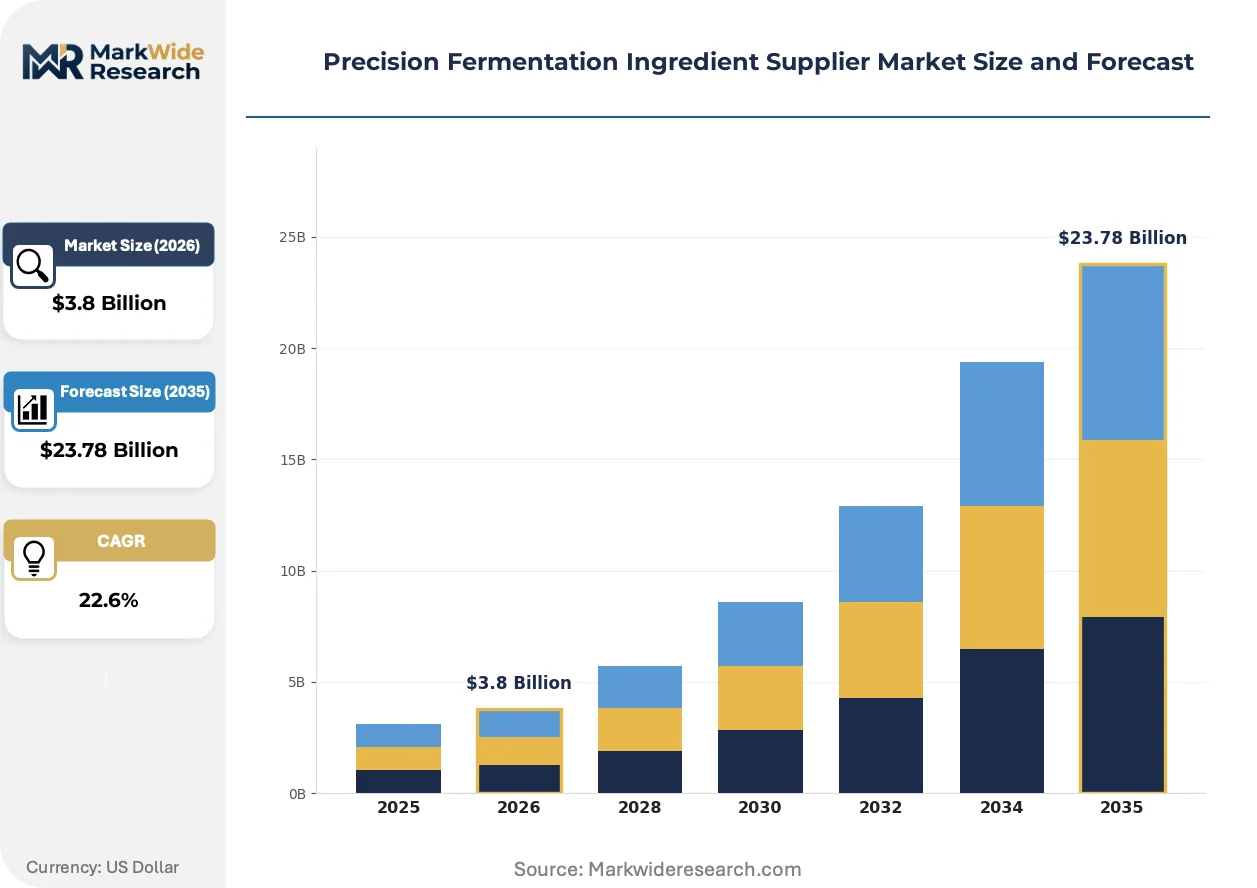
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $23.78 Billion |
| CAGR (2026 – 2036) | 22.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Enzymes, Proteins, Vitamins, Amino Acids, Organic Acids, Lipids Application: Food & Beverage, Animal Nutrition, Pharmaceuticals, Cosmetics, Biofuels, Agriculture Production Technology: Fed-Batch Fermentation, Continuous Fermentation, Solid-State Fermentation, Submerged Fermentation, Co-Fermentation, Photofermentation End User Industry: Food Processing Companies, Feed Manufacturers, Drug Formulators, Personal Care Product Makers, Renewable Energy Firms, Crop Protection Businesses |
| Companies Covered | Perfect Day, Geltor, The EVERY Company, Impossible Foods, Imagindairy, Shiru, Formo Foods, Change Foods, Vivici, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Fermentation Ingredient Supplier Market Trends and Innovations
Bioprocess intensification and regulatory science advancement are compressing development timelines while expanding the molecular scope of commercially viable fermentation targets beyond established protein categories.
Continuous fermentation technology is hybridizing with single-use bioreactor designs to enable flexible manufacturing footprints. Mid-scale CPG brands are adopting these systems at pilot scale to de-risk supply chain transitions. The hybridizing architecture is compressing facility build-out timelines from thirty-six to eighteen months for high-value peptide production.
EU Green Deal biomanufacturing incentives are reshaping facility siting economics across European fermentation networks. Renewable energy integration mandates and carbon border adjustment mechanisms are favoring Nordic and Iberian production locations with verified low-carbon grid profiles. Suppliers are responding by securing power purchase agreements with offshore wind operators in Denmark and Portugal.
CPG procurement patterns are consolidating around long-term offtake agreements with embedded volume commitments and quality specifications. This displaces spot-market purchasing for functional proteins in North American plant-based dairy channels. The shift is most visible in United States contract negotiations, where five-year supply agreements now dominate whey protein analog sourcing.
Precision Fermentation Ingredient Supplier Market Segmentation
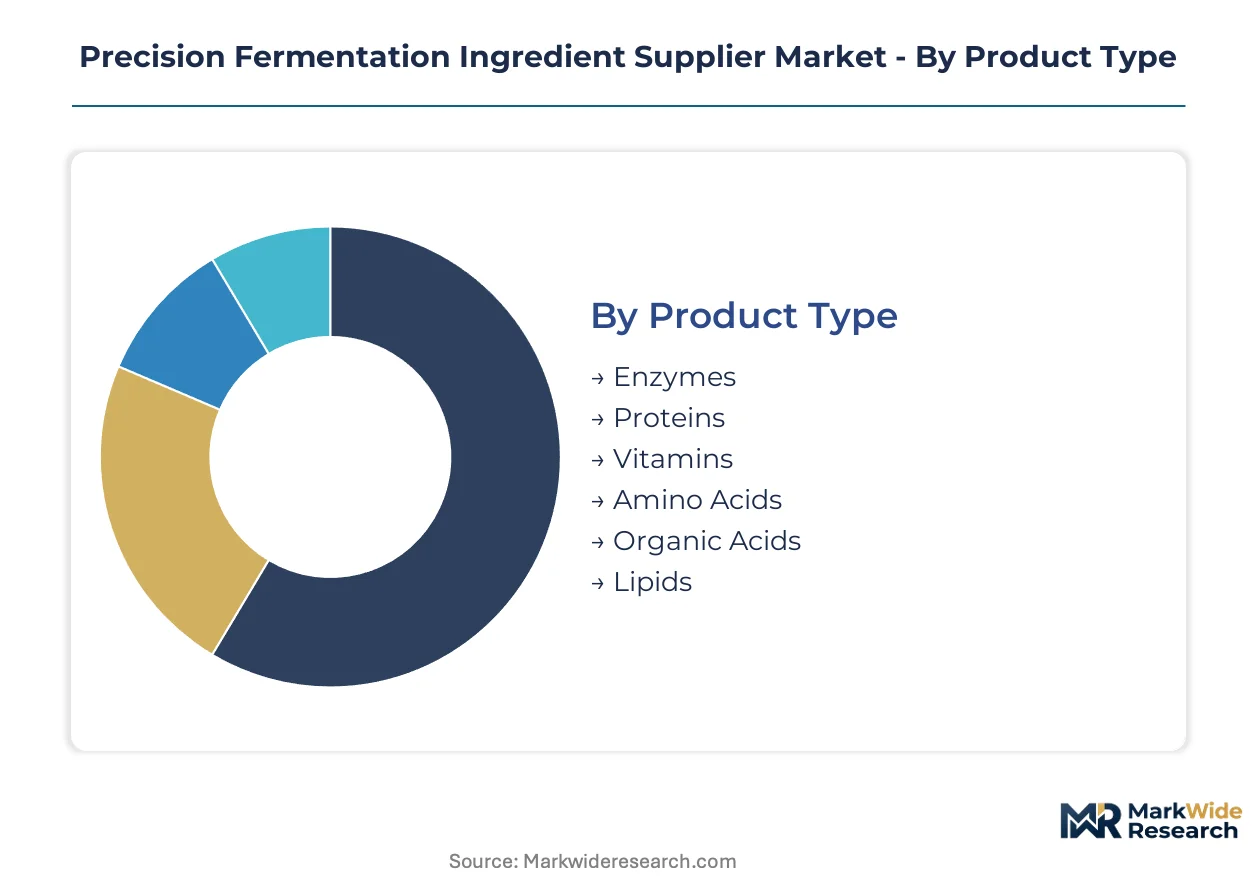
Segmentation in precision fermentation ingredient supply reveals how technical specifications, production scale, and end-use requirements fragment procurement patterns across divergent value chains. Suppliers must align bioreactor configurations and downstream processing investments with the purity thresholds and volume profiles of distinct customer categories.
Product Type:
Mature commodity proteins and enzymes dominate installed revenue bases, while emerging lipid and amino acid categories capture capital allocation for novel applications.
- Enzymes:Catalytic proteins engineered for industrial biocatalysis operate at high turnover rates with thermal stability specifications tailored to food processing and detergent manufacturing. Demand concentrates in United States food processing corridors where thermostable amylases and proteases anchor long-term supply contracts with CPG brands facing enzyme cost volatility.
- Proteins:Whey and casein analogs synthesized through recombinant yeast or fungal hosts achieve functional parity with dairy-derived equivalents for emulsification and gelling. United States plant-based dairy formulators scale procurement most aggressively, though EFSA novel food consultations extend approval timelines for European market entry.
- Vitamins:Riboflavin and cobalamin produced via engineered bacterial strains meet fortification specifications for human and animal nutrition.
- Amino Acids:Lysine, methionine, and tryptophan for feed fortification represent high-volume, price-sensitive categories with thin margins.
- Organic Acids:Citric and lactic acid fermentation supplies preservative and pH-adjustment functions across food and industrial applications.
- Lipids:Structured fats and omega-3 fatty acids from oleaginous yeasts target pharmaceutical excipient and premium nutrition channels.
Enzymes handle the majority of throughput; lipids are expanding most quickly on share.
Application:
Volume concentration separates mass-market nutrition from premium-priced specialty channels, with biofuels and agriculture representing nascent demand verticals.
- Food & Beverage:Dairy alternatives, meat analogs, and functional beverages absorb the bulk of fermentation-derived protein supply, with formulation partnerships locking in multi-year offtake agreements.
- Animal Nutrition:Feed-grade amino acids and enzymes displace synthetic additives and fishmeal in aquaculture and livestock rations, with pricing indexed to agricultural commodity cycles.
- Pharmaceuticals:High-purity recombinant proteins and lipids for drug delivery command 3-5x premiums over food-grade equivalents, with FDA GRAS determinations and EMA quality certifications gating market access.
- Cosmetics:Bioactive collagen peptides and ceramides from precision fermentation sustain premium positioning in anti-aging and skin barrier formulations.
- Biofuels:Lipid and alcohol outputs from engineered algae and yeast strains feed renewable diesel and aviation fuel pathways, with EU Green Deal incentives conditioning facility siting toward low-carbon grid regions.
- Agriculture:Microbial biostimulants and biopesticides represent an emerging application with unstandardized efficacy protocols and elongated customer adoption curves.
Food & Beverage commands the dominant revenue share; Pharmaceuticals climbs the fastest on margin contribution.
Production Technology:
Process intensification divides established fed-batch infrastructure from next-generation continuous and hybrid systems competing on productivity and capital efficiency.
- Fed-Batch Fermentation:Intermittent substrate addition with discrete harvest cycles retains the largest installed base across contract manufacturing networks, with proven scalability for enzymes and proteins.
- Continuous Fermentation:Perfusion-based bioreactor configurations with cell retention enable steady-state operation and improved volumetric productivity, attracting investment from high-volume peptide manufacturers.
- Solid-State Fermentation:Fungal cultivation on moist solid substrates serves traditional enzyme production with lower water intensity and simplified downstream recovery.
- Submerged Fermentation:Conventional liquid culture in stirred-tank bioreactors dominates vitamin and organic acid manufacturing.
- Co-Fermentation:Multi-strain systems for complex metabolite synthesis remain largely at pilot scale with unresolved metabolic engineering challenges.
- Photofermentation:Light-driven hydrogen and lipid production from photosynthetic bacteria occupies niche research applications with unfavorable energy economics.
Fed-Batch Fermentation handles the majority of throughput; Continuous Fermentation is gaining share fastest.
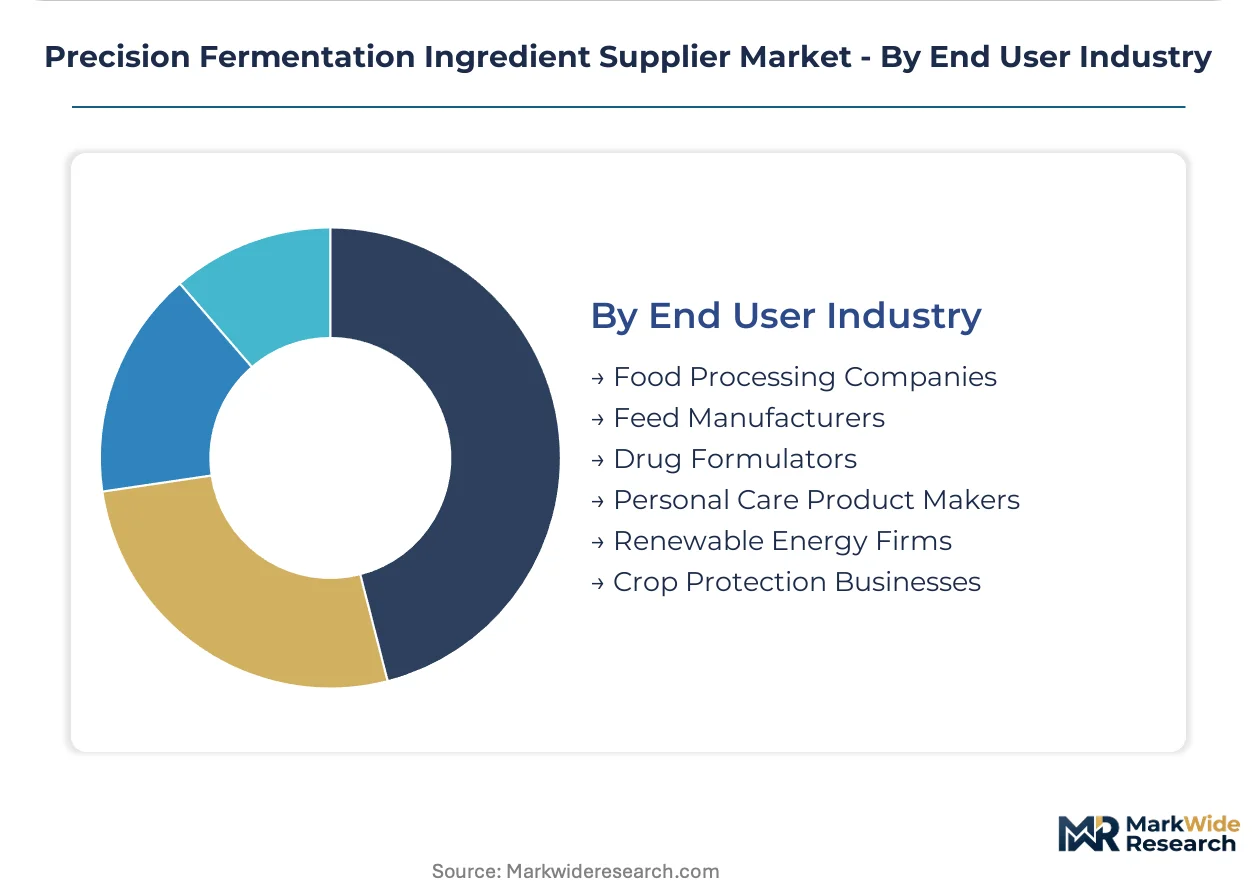
End User Industry:
Customer concentration patterns reflect consolidation in food processing against fragmentation in personal care and renewable energy procurement functions.
- Food Processing Companies:Large CPG brands and emerging plant-based specialists negotiate multi-year supply agreements with embedded volume floors and quality specifications, displacing spot-market purchasing.
- Feed Manufacturers:Integrated livestock and aquaculture operations procure amino acids and enzymes through tender processes with price sensitivity and specification standardization.
- Drug Formulators:Pharmaceutical excipient buyers enforce stringent purity and documentation requirements with audit-intensive supplier qualification protocols.
- Personal Care Product Makers:Cosmetics brands source bioactive peptides through specialized distributors with marketing claims dependent on INCI nomenclature and regulatory substantiation.
- Renewable Energy Firms:Biofuel offtakers contract for lipid and alcohol feedstocks with carbon intensity certifications under EU and California low-carbon fuel standards.
- Crop Protection Businesses:Agricultural biologicals companies pilot fermentation-derived biostimulants with performance validation timelines extending across multiple growing seasons.
Food Processing Companies anchor the dominant procurement volume; Drug Formulators show the steepest expansion trajectory on pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States absorb premium-priced whey analogs with limited price elasticity, while European procurement teams enforce stringent cost benchmarks tied to carbon accounting metrics. Asian feed manufacturers operate at the opposite extreme, where amino acid sourcing decisions pivot on glucose feedstock indices with minimal specification tolerance.
United States
Venture-backed biotech firms cluster around the San Francisco Bay Area and Greater Boston, securing multi-year offtake agreements with plant-based dairy formulators. FDA novel food consultation timelines for GRAS determinations extend pre-market review periods, compressing working capital efficiency. Boston-area contract manufacturers deploy continuous fermentation systems at pilot scale to de-risk supply chain transitions for mid-market CPG brands.
Germany
Industrial enzyme demand from detergent and food processing corridors anchors steady procurement volumes for thermostable biocatalysts. REACH compliance and EU Green Deal biomanufacturing incentives condition facility siting decisions toward renewable energy-integrated production networks. The North Rhine-Westphalia chemical cluster hosts downstream processing infrastructure for high-purity recombinant proteins targeting pharmaceutical excipient specifications.
Denmark
Offshore wind power purchase agreements enable verified low-carbon grid profiles that satisfy EU carbon border adjustment mechanisms for fermentation-derived lipids. EFSA novel food harmonization reduces cross-border approval fragmentation for suppliers targeting pan-European distribution. Copenhagen-area biotech incubators specialize in CRISPR-Cas9 strain engineering for previously inaccessible metabolic targets.
Singapore
Strategic government biomanufacturing initiatives attract precision fermentation capacity serving Asia-Pacific pharmaceutical and nutrition markets. The national food agency maintains streamlined novel food assessment pathways that compress regulatory timelines relative to EU equivalents. Tuas Biomedical Park hosts integrated fermentation and downstream processing facilities with dedicated pharmaceutical-grade infrastructure.
Brazil
Aquaculture feed manufacturers scale procurement of fermentation-derived amino acids to displace fishmeal in shrimp and salmon rations. Agricultural commodity cycle volatility in domestic glucose and nitrogen source markets compresses margins for operators without long-term supply contracts. São Paulo-state integrated livestock operations pilot enzyme-supplemented rations through tender processes with price-indexed specifications.
Precision Fermentation Ingredient Supplier Market Competitive Landscape
Capability concentration sits with gene-editing specialists and strain engineering platforms; scale advantage sits with contract manufacturing networks and captive production facilities. The supplier base organizes around three strategic archetypes: biotechnology platform companies with proprietary microbial hosts, integrated CPG players with backward fermentation capacity, and specialized downstream processors with chromatography infrastructure. Dominant competitive moves include long-term offtake agreement anchoring with embedded volume commitments and geographic expansion through renewable energy-integrated facility construction.
Within the biotechnology platform tier, Perfect Day and Geltor exemplify divergent value capture strategies—one leveraging captive whey protein production for CPG supply anchoring, the other sustaining premium positioning in cosmetics channels through bioactive collagen peptides. The EVERY Company occupies a position bridging food-grade and pharmaceutical-grade protein specifications. These three entities represent the dominant archetypes: captive supply integration, premium channel specialization, and cross-grade specification spanning.
| Leading Market Players |
|---|
| Perfect Day |
| Geltor |
| The EVERY Company |
| Impossible Foods |
| Imagindairy |
| Shiru |
| Formo Foods |
| Change Foods |
| Vivici |
| Others |
Pricing and Supply Chain Analysis
Feedstock cost volatility in agricultural commodity markets determines both the spread between contract and spot pricing tiers and the geographic shape of fermentation supply networks. Glucose and nitrogen source price swings compress margins for operators without long-term supply agreements, forcing consolidation around integrated production geographies with captive feedstock sourcing.
Pricing Analysis
After-sales revenue from technical service contracts and formulation support drives lifetime value capture for precision fermentation suppliers. Three-tier pricing structure across premium pharmaceutical-grade, standard food-grade, and economy feed-grade specifications anchors contract negotiations. Price differentiation hinges on EFSA novel food certification status and volumetric scale commitments in offtake agreements. Cost compression in feed-grade amino acids is intensifying because Asian aquaculture buyers index procurement to agricultural spot markets. Pharmaceutical excipient buyers exhibit the least price sensitivity, while feed manufacturers operate with minimal specification tolerance and maximum cost pressure.
Supply Chain Analysis
Extended payment terms from CPG brands and supply-chain finance facilities strain working capital for mid-scale fermentation operators. Production gravity centers on the United States, Denmark, and Singapore, with each hub serving distinct regulatory and customer proximity requirements. Raw material dependencies on corn-derived glucose, soy nitrogen sources, and pharmaceutical-grade filtration media expose margins to agricultural and specialty chemical supply shocks. Single-source vulnerability concentrates in San Francisco Bay Area strain engineering platforms, where venture-backed biotech clustering creates geographic risk for CPG procurement functions. Distribution runs through long-term offtake agreements with embedded volume floors rather than spot-market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation ingredient supply is approaching a platform-economics inflection where microbial host strain interoperability and downstream processing standardization will determine competitive boundaries. CRISPR-Cas9 editing platforms and automated bioreactor control systems are converging to create ecosystem lock-in effects previously absent in commodity biochemical markets.
For Market Incumbents: Entrench position through captive strain engineering platforms and backward integration into renewable energy-integrated production facilities. Perfect Day's whey protein supply anchoring with CPG brands demonstrates how long-term offtake agreements defend against emerging platform competitors. Prioritize EFSA novel food certification investments to extend regulatory moats across European distribution networks. For New Entrants and Emerging Players: Pharmaceutical excipient applications for high-purity lipids and recombinant proteins represent the most penetrable entry point, with pricing premiums 3-5x above food-grade equivalents and less consolidated incumbent control. Nordic and Iberian facility locations with verified low-carbon grid profiles offer geographic differentiation under EU carbon border adjustment mechanisms. Pursue joint development agreements with drug formulators seeking alternative supply sources to established fermentation networks. For Investors and Strategic Acquirers: The market sits at a scale-up phase that favors contract manufacturing networks with chromatography infrastructure and proven regulatory submission track records. Long-term viability over the next decade hinges on consolidation of fragmented downstream processing capacity and standardization of carbon accounting protocols. Watch for EFSA strain classification protocol finalization as the signal indicating regulatory clarity sufficient for accelerated capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Five-year offtake contracts with CPG brands lock in volume commitments and reduce working capital volatility. |
| Renewable Energy Integration | Power purchase agreements with offshore wind operators in Denmark satisfy EU carbon border adjustment requirements. |
| Regulatory Approval Pathway | FDA GRAS determinations and EFSA novel food consultations gate commercial access to North American and European markets. |
| Backward Integration | In-house glucose feedstock production from agricultural waste streams insulates margins from commodity price cycles. |
| Platform Integration | CRISPR-Cas9 strain engineering convergence with automated bioreactor control opens previously inaccessible metabolic targets. |
Research Methodology
Cross-validation between primary executive interviews and secondary regulatory filings anchors the qualitative findings in documented approval pathways and commercialization timelines. Conversations with strain engineering scientists, CPG procurement directors, pharmaceutical excipient buyers, and contract manufacturing operators combined with FDA GRAS notifications, EFSA novel food applications, and EU Green Deal incentive disclosures. Bottom-up volume modeling from disclosed bioreactor capacity and top-down market sizing from CPG ingredient procurement budgets triangulate demand estimates.
Calibration against historical approval timelines and capacity build-out rates validates the projection framework across the analysis window. Segmentation dimensions include product type, application vertical, production technology configuration, and end-user industry concentration. CAGRs derive from fitted growth curves incorporating disclosed offtake agreement volumes and announced facility expansion timelines. Feedstock cost indices and carbon accounting standard evolution serve as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, renewable energy build-out rates, or biotechnology regulatory stringency would shift the trajectory. Forecasts reflect documented assumptions about approval pathway durations and capacity scaling efficiency. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Non-GMO Oil Market
Ingredients
Proteose Peptone Market
Ingredients
Liquid Feed Market
Ingredients
Carotenoids Market
Ingredients
Ahiflower Oil Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Mediterranean Barley Beta-Glucan Ingredients Market
Ingredients
Cocoa Based Polyphenols Market
Ingredients
Seaweed Derivatives Market
Ingredients
India Soy Protein Market
Ingredients
Marine Protein Market
Ingredients
Whey Permeate Market
Ingredients
Global Pulse Flours Market
Ingredients
Pea Hull Fiber Market
Ingredients
Soy Peptones Market
Ingredients
Chickpea Protein Market