
 Marine Protein Market | 2026-2036
Marine Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Protein Market Analytics
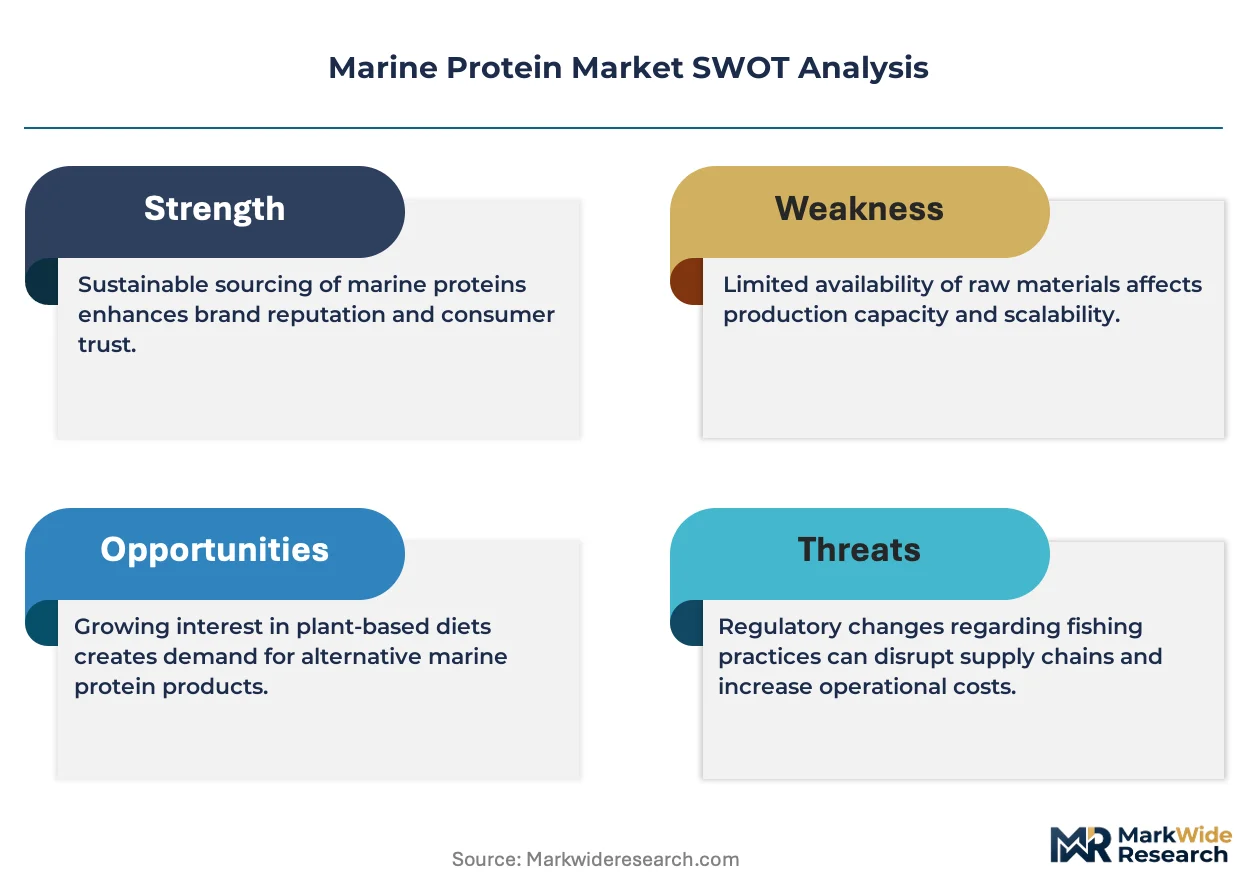
Norway is narrowing the gap between wild-capture supply and aquaculture demand through controlled fishery quotas and processing infrastructure expansion. Aker BioMarine leverages Antarctic krill harvesting to secure a differentiated marine phospholipid position. DSM sustains its synthetic astaxanthin and omega-3 technology leadership alongside natural extraction capabilities. Cargill competes through backward integration into Peruvian anchovy supply chains, anchoring volume security for premium fish meal customers.
Marine protein encompasses concentrated nutritional extracts derived from fish, crustaceans, mollusks, and microalgae, typically processed through rendering, enzymatic hydrolysis, or solvent extraction to achieve protein contents ranging from sixty-five to ninety percent dry weight. These ingredients serve primarily as high-bioavailability amino acid sources in aquaculture diets, companion animal nutrition, and human dietary supplements. Fish oil commands the highest margin pool among product types due to concentrated EPA and DHA content for pharmaceutical-grade applications. Hydrolysates represent the fastest-growing product category as peptide-based formulations gain traction in functional foods and specialized pet nutrition. Algae-based sourcing is displacing wild-capture dependence among sustainability-focused formulators, though scale constraints limit near-term volume contribution.
EFSA and the EU Green Deal shape European marine protein standards through maximum contaminant thresholds and traceability mandates for fishery-derived ingredients. REACH and F-Gas Regulation indirectly constrain processing chemistry choices for European manufacturers. In the United States, FDA and NOAA jointly oversee seafood safety and fishery management, creating dual compliance pathways for imported marine ingredients. Stakeholders must monitor evolving quotas under regional fishery management organizations and assess algae cultivation partnerships as a hedge against wild-stock volatility.
Market Dynamics
The EU Green Deal's traceability mandates are compressing supply chain opacity, forcing marine protein processors to document fishery origins through blockchain-verified systems or risk exclusion from European premium channels.
Growth Catalysts
- Fish oil pharmaceutical applications:Concentrated EPA and DHA extraction for cardiovascular therapeutics pulls volume from nutraceutical into prescription-grade manufacturing, expanding margin pools for certified processors.
- REACH compliance automation:European processors investing in solvent recovery systems gain preferential access to EFSA-approved supply chains, locking out competitors dependent on legacy chemistry.
- Norway:Salmon farming quotas under the country's fisheries directorate sustain premium fish meal offtake, anchoring demand concentration for North Atlantic suppliers.
Market Restraints
- Wild-stock volatility:Peruvian anchovy catch fluctuations tied to El Niño cycles create input cost instability for hydrolysate manufacturers dependent on South Pacific sourcing.
- Algae cultivation scale constraints:Photobioreactor capex intensity and lipid extraction yields below sixty percent dry weight limit near-term displacement of krill and fish oil in volume applications.
- F-Gas Regulation:European solvent-based processors face refrigerant chemistry restrictions that increase operating costs for cold-chain marine ingredient storage.
Strategic Opportunities
- India aquaculture expansion:Shrimp farming operations under the country's PLI scheme for marine products create unserved demand for peptide-based hatchery feeds.
- Pet nutrition functionalization:Hydrolysate inclusion in veterinary-prescribed renal diets opens prescription-tier pricing for manufacturers with AAFCO nutritional adequacy verification.
- CSRD disclosure requirements:Mandatory Scope 3 emissions reporting for European corporates creates procurement preference for marine protein suppliers with MSC chain-of-custody certification.
Industry Challenges
- Enzymatic hydrolysis engineering:Specialized protein biochemist scarcity constrains process optimization for manufacturers scaling from pilot to commercial peptide recovery.
- Multi-jurisdictional approval timelines:Novel algae strains require sequential FDA GRAS, EFSA novel food, and Health Canada safety assessments, extending time-to-market by thirty-six to forty-eight months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Protein Market |
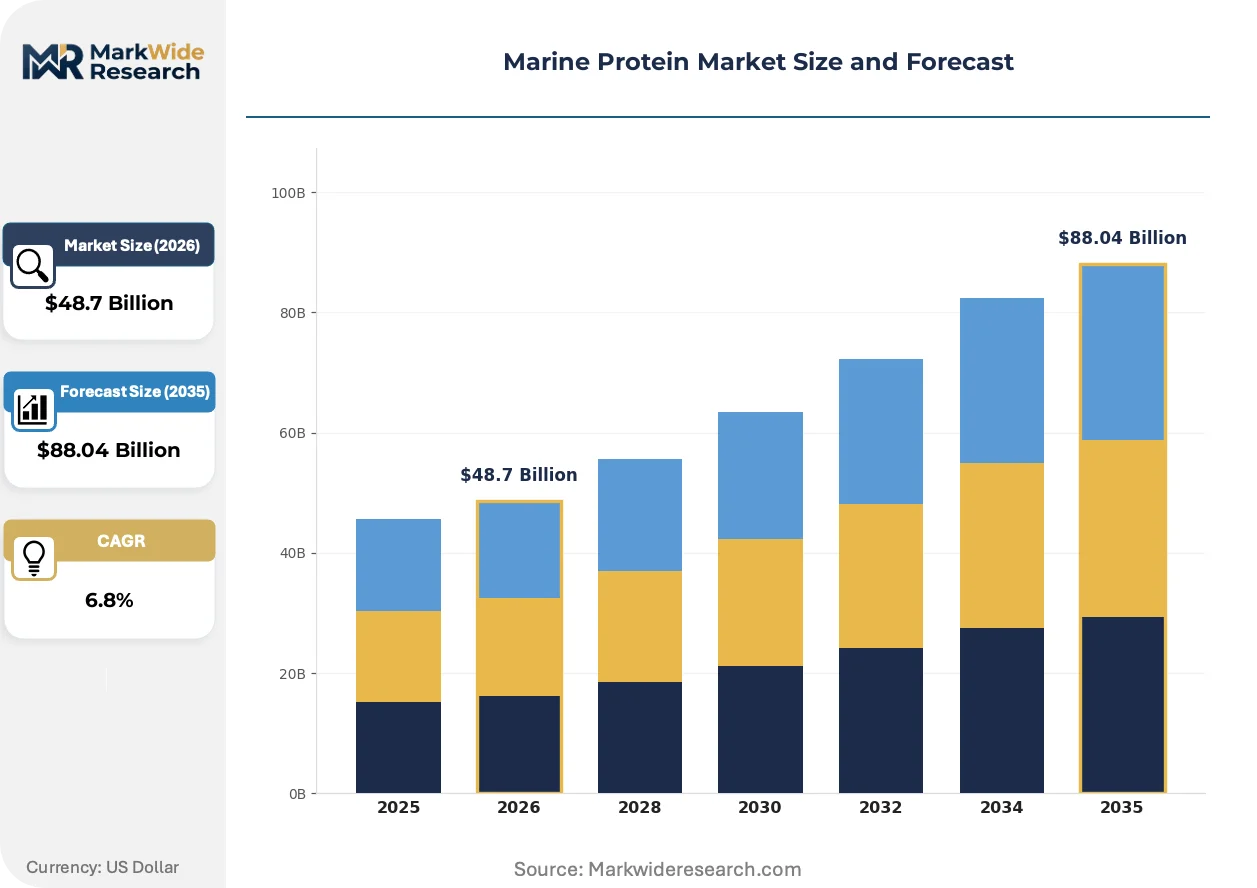
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fish Meal, Fish Oil, Hydrolysates, Whole Fish Source: Wild-caught, Farmed, Algae-based, Bycatch Application: Nutrition Supplements, Animal Feed, Pet Food, Functional Foods Form: Powder, Liquid, Granules, Paste |
| Companies Covered | Aker BioMarine, Biomega Group, Cargill, Gelita, Corbion, DSM, Hofseth BioCare, Golden Omega, Scanbio Marine Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Protein Market Evolving Landscape
Processing technology convergence and procurement specification tightening are compressing traditional competitive advantages in marine protein, rewarding operators with integrated quality verification systems.
Precision fermentation of omega-3 fatty acids from engineered thraustochytrid strains is collapsing the cost premium for DHA-alternative sourcing. Pharmaceutical formulators in Switzerland and Germany are qualifying these inputs for pediatric nutrition applications at commercial scale. The technology is collapsing wild-capture dependency among sustainability-mandated buyers, redirecting procurement budgets toward bioreactor capacity contracts.
EFSA's 2023 update to maximum levels for dioxins and dioxin-like PCBs in fish oils is tightening contaminant thresholds for European supply chain entry. Processors must deploy activated carbon filtration and molecular distillation to achieve sub-picogram toxicity standards. Norwegian and Icelandic rendering facilities are absorbing capex for compliance, while Peruvian exporters face exclusion from premium EU channels without equivalent treatment infrastructure.
Salmon farming operations are consolidating feed procurement through direct long-term contracts with hydrolysate manufacturers, bypassing traditional trading houses. Cargill and Skretting are negotiating five-year peptide supply agreements with fixed volume floors and indexed pricing. This concentration is most visible in Scotland and British Columbia, where integrated aquaculture groups are capturing margin through captive ingredient sourcing.
Marine Protein Market Segmentation
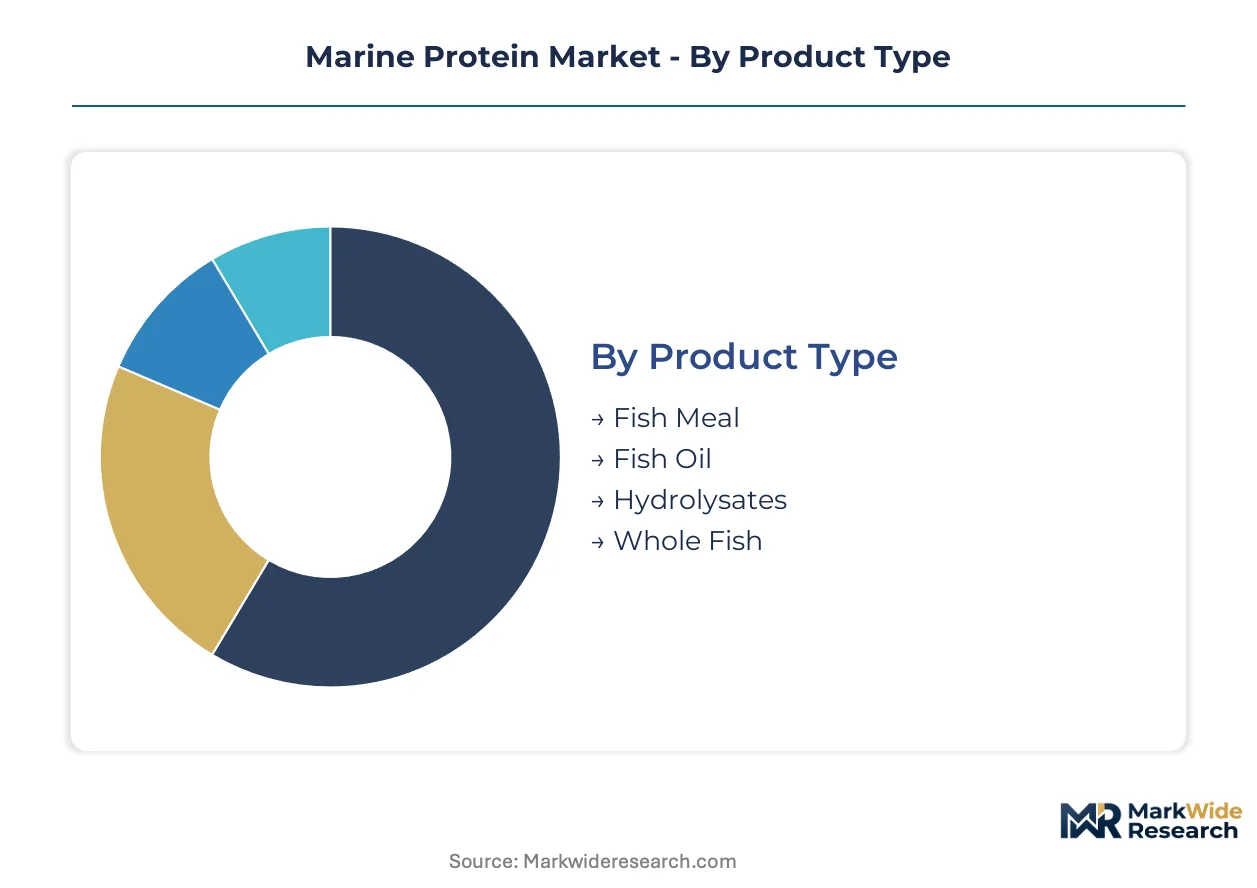
Marine protein segmentation reveals how processing intensity and bioavailability specifications split procurement budgets across aquaculture, pharmaceutical, and companion animal channels. Understanding these divides exposes where margin pools concentrate and where substitution threats emerge from novel sourcing technologies.
Product Type:
Mature commodity grades dominate volume flows while enzymatically refined fractions capture expanding premium tiers.
- Fish Meal:Rendered whole fish and trimmings yielding sixty-five to seventy-two percent crude protein serve as the baseline amino acid source for salmon and shrimp diets. Norwegian aquaculture operations under Directorate of Fisheries quotas anchor offtake for North Atlantic suppliers, though El Niño-driven Peruvian anchovy volatility injects cost instability.
- Fish Oil:EPA and DHA concentrates extracted through molecular distillation command pharmaceutical-grade margins for cardiovascular therapeutics. Swiss and German formulators are qualifying precision-fermented alternatives, threatening wild-capture dependency among sustainability-mandated buyers.
- Hydrolysates:Enzymatically cleaved peptide fractions with enhanced digestibility profiles gain traction in specialized pet nutrition and functional foods.
- Whole Fish:Minimally processed raw material for on-farm grinding in artisanal aquaculture operations, concentrated in Southeast Asian smallholder systems.
Fish meal retains volume leadership; hydrolysates hold the steepest expansion curve.
Source:
Supply security concerns are redirecting procurement toward controlled cultivation and verified bycatch recovery systems.
- Wild-caught:Peruvian anchovy and North Atlantic capelin fisheries supply the bulk of commodity fish meal, with RFMO quotas constraining annual harvest ceilings.
- Farmed:Salmon and trout processing trimmings provide traceable, contaminant-controlled inputs for premium feed formulators in Scotland and Norway.
- Algae-based:Thraustochytrid fermentation in photobioreactors yields DHA alternatives without wild-stock exposure, though extraction yields below sixty percent dry weight limit near-term scale.
- Bycatch:Regulatory-mandated recovery from demersal trawl operations supplies niche markets in the EU under discard ban compliance frameworks.
Wild-caught dominates current tonnage; algae-based sourcing climbs the fastest as bioreactor capacity contracts multiply.
Application:
End-use specifications fragment between bulk commodity pricing and prescription-tier certification requirements.
- Nutrition Supplements:Softgel and emulsion formats for human omega-3 consumption require sub-picogram dioxin thresholds under EFSA mandates, favoring processors with activated carbon and molecular distillation infrastructure.
- Animal Feed:Aquaculture diets absorb the majority of fish meal volume, with salmon farming consolidation driving direct long-term supply agreements bypassing traditional traders.
- Pet Food:Veterinary-prescribed renal diets incorporating hydrolysates open prescription-tier pricing for manufacturers with AAFCO nutritional adequacy verification.
- Functional Foods:Peptide-fortified beverages and bars target sports nutrition segments, constrained by novel food approval timelines in Europe.
Animal feed commands absolute volume; pet food functionalization offers the sharpest margin expansion trajectory.
Form:
Handling economics and shelf stability requirements determine processing investment priorities across distribution channels.
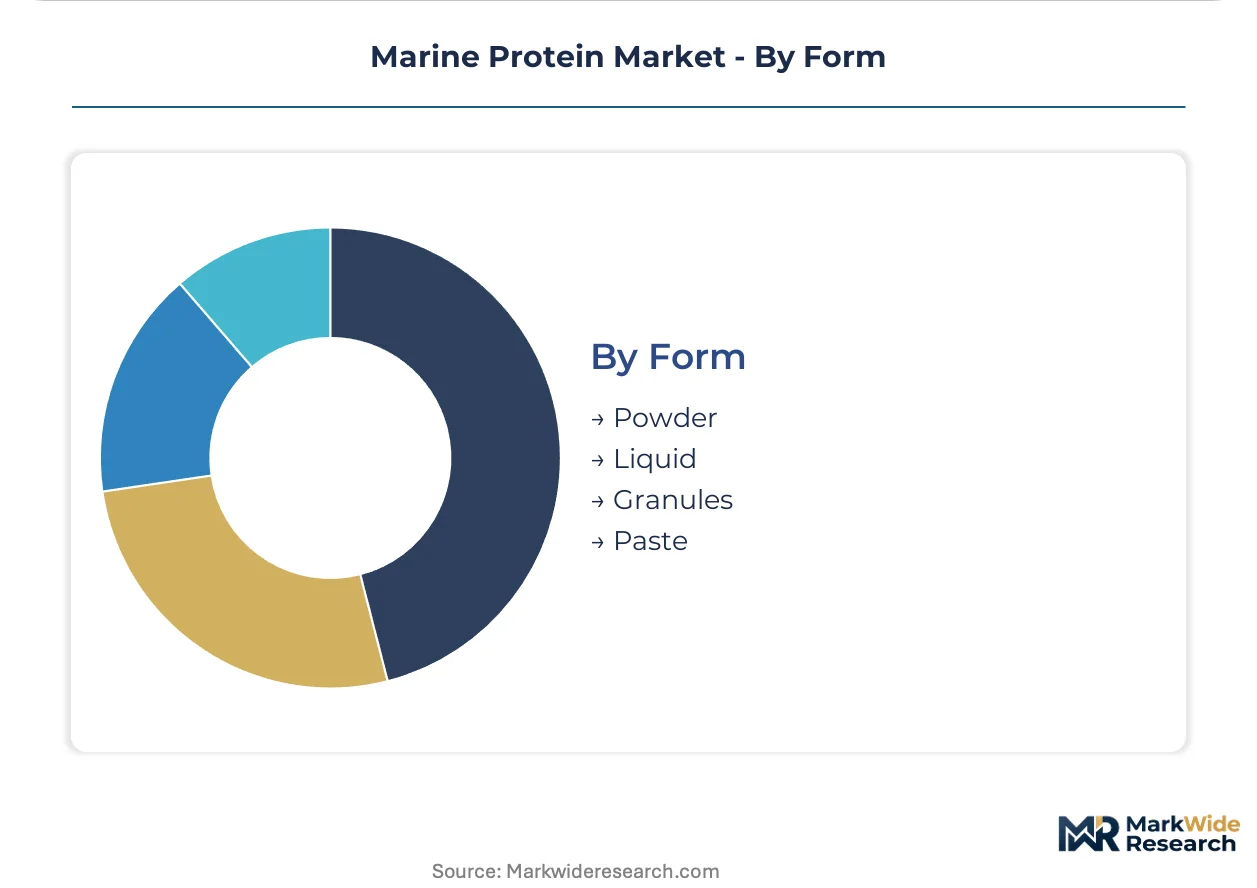
- Powder:Spray-dried fractions with low moisture content suit bulk aquaculture feed milling and extended storage in tropical climates.
- Liquid:Crude and refined oils for pharmaceutical encapsulation and direct feed top-dressing, requiring cold-chain integrity under F-Gas Regulation constraints in Europe.
- Granules:Agglomerated particles for slow-release aquaculture applications and automated feeding systems in intensive Norwegian operations.
- Paste:High-moisture hydrolysate preparations for hatchery live feeds and specialized pet palatability enhancement.
Powder maintains volume leadership; liquid formats sustain the steepest value-per-kilogram expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peruvian anchovy landings and Norwegian salmon farming operations concentrate raw material flows for marine protein processing. These supply nodes interact with regulatory frameworks in consuming markets that dictate entry thresholds for finished ingredients. The following countries anchor regional demand patterns and compliance pathways.
Norway
Salmon farming quotas under the Directorate of Fisheries sustain premium fish meal offtake for North Atlantic suppliers. EFSA contaminant thresholds shape import specifications for hydrolysates entering European formulations. Bergen and Ålesund processing clusters absorb capex for molecular distillation infrastructure serving pharmaceutical-grade fish oil extraction.
United States
FDA and NOAA joint oversight creates dual compliance pathways for imported marine ingredients entering nutraceutical channels. The country's pet nutrition manufacturers drive hydrolysate demand for veterinary-prescribed renal diets. Seattle and Boston metropolitan areas concentrate omega-3 softgel formulators qualifying precision-fermented alternatives.
Peru
North-central anchovy fishery fluctuations tied to El Niño cycles inject input cost instability for South Pacific-sourced fish meal. IMARPE research institute catch assessments directly determine annual export volumes. Chimbote and Paita processing hubs face exclusion from premium EU channels without activated carbon filtration infrastructure matching EFSA dioxin standards.
China
Aquaculture feed mill expansion under the country's marine economy development plans absorbs commodity-grade fish meal at volume scale. SAMR food safety regulations constrain import approvals for novel algae strains. Qingdao and Dalian port clusters handle bulk marine ingredient transshipment for domestic aquaculture operations.
Germany
REACH compliance automation for solvent recovery systems grants preferential access to EFSA-approved supply chains for domestic processors. The country's pharmaceutical formulators qualify precision-fermented DHA alternatives for pediatric nutrition applications. Hamburg and Bremerhaven logistics hubs coordinate cold-chain distribution under F-Gas Regulation constraints.
Marine Protein Market Competitive Landscape
Vertically integrated harvesters and specialized biotech developers split the market between volume security and technology differentiation. Consolidation concentrates around Antarctic krill operations and Peruvian anchovy supply chains. Three archetypes dominate: wild-capture quota holders with rendering infrastructure, fermentation-based omega-3 specialists, and aquaculture feed formulators with backward integration into ingredient sourcing. Competitive moves center on long-term supply agreements with fixed volume floors and bioreactor capacity contracts displacing wild-capture dependency.
Among Nordic marine harvesters, Aker BioMarine exemplifies the quota-integrated archetype through Antarctic operations. DSM occupies a position spanning synthetic and natural extraction capabilities for carotenoid and omega-3 applications. Cargill anchors the agribusiness-integrated tier with supply chain control into South Pacific fisheries. These three represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Aker BioMarine |
| Biomega Group |
| Cargill |
| Gelita |
| Corbion |
| DSM |
| Hofseth BioCare |
| Golden Omega |
| Scanbio Marine Group |
| Others |
Value Network & Pricing Analysis
Chimbote and Paita processing clusters in Peru anchor global fish meal pricing through their anchovy rendering capacity, with El Niño-driven catch volatility transmitting directly into spot market premiums for European aquaculture buyers. This supply concentration grants quota-holding harvesters asymmetric leverage over contract negotiations.
Pricing Analysis
EFSA contaminant thresholds dictate the pricing tier structure for European market entry, separating pharmaceutical-grade molecular distillation outputs from commodity fish meal. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale differentiation. Cost compression in standard-grade segments is intensifying because Peruvian exporters without activated carbon infrastructure face exclusion from premium EU channels. Aquaculture feed formulators exhibit highest price sensitivity due to bulk procurement volumes, while pharmaceutical softgel manufacturers accept premium pricing for sub-picogram dioxin compliance.
Supply Chain Analysis
El Niño exposure between Peru and Norway dominates supply chain risk architecture for marine protein processors. Raw material flows concentrate in Peru, Norway, and China, with Antarctic krill operations adding a third sourcing pole. The supply chain draws from wild-capture anchovy, farmed salmon trimmings, and thraustochytrid fermentation feedstocks. Single-source vulnerability persists for hydrolysate manufacturers dependent on South Pacific anchovy landings. Distribution runs through direct long-term contracts with aquaculture integrators, bypassing traditional trading houses in Scotland and British Columbia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Marine protein procurement is evolving into a certification-attach business, with MSC chain-of-custody verification and Scope 3 emissions disclosure expanding faster than base ingredient volumes. Recurring revenue from compliance documentation services now outpaces commodity margin capture for leading processors.
For Market Incumbents: Harden supply security through backward integration into Peruvian quota holdings or Antarctic krill harvesting licenses, defending against precision-fermented omega-3 displacement. Invest in activated carbon and molecular distillation infrastructure to lock EFSA-approved channel access. Prioritize five-year peptide supply agreements with fixed volume floors to capture salmon farming consolidation value.
For New Entrants and Emerging Players: Algae-based DHA sourcing for pediatric nutrition applications in Switzerland and Germany represents the most penetrable entry point, bypassing wild-capture quota constraints. India's shrimp farming operations under PLI scheme incentives offer unserved peptide-based hatchery feed demand. A go-to-market angle targeting veterinary-prescribed renal diets with AAFCO nutritional adequacy verification unlocks prescription-tier pricing.
For Investors and Strategic Acquirers: Long-term, this sits as a bioreactor capacity play because precision fermentation is collapsing wild-capture dependency among sustainability-mandated buyers. Acquisition targets should feature photobioreactor infrastructure and novel strain IP portfolios. The signal to watch is Swiss and German pharmaceutical formulators qualifying thraustochytrid-derived DHA for commercial pediatric applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Quota Holdings | Peruvian anchovy quota access secures volume certainty for premium fish meal customers. |
| Molecular Distillation Infrastructure Deployment | Activated carbon filtration achieves EFSA sub-picogram dioxin thresholds for EU channel entry. |
| Precision Fermentation Scale-Up | Thraustochytrid bioreactor contracts displace wild-capture dependency among sustainability-mandated buyers. |
| MSC Chain-of-Custody Certification | CSRD-mandated Scope 3 reporting creates procurement preference for verified sustainable sourcing. |
| Direct Long-Term Supply Agreements | Five-year peptide contracts with salmon farming integrators bypass traditional trading house margins. |
Research Methodology
The analysis maps fish meal, fish oil, hydrolysates, and algae-based alternatives, each validated through procurement directors at aquaculture feed formulators, regulatory affairs leads at marine ingredient processors, and sustainability officers at pet nutrition manufacturers. Primary interview findings triangulate against IMARPE catch assessments, EFSA contaminant threshold documentation, RFMO quota filings, and customs trade data for Peruvian anchovy exports. Bottom-up volume modeling and top-down market sizing converge through iterative stakeholder validation.
Forecast assumptions hold regulatory frameworks stable while varying El Niño cycle intensity, algae cultivation yield improvements, and precision fermentation cost curves across the projection horizon. Segmentation dimensions include product type, source origin, application channel, and geographic regulatory cluster. CAGRs derive from historical volume trajectories adjusted for quota constraints and substitution elasticity between wild-capture and fermentation-derived inputs. Modeled inputs incorporate salmon farming stocking densities and pharmaceutical softgel formulation growth.
Macroeconomic conditions sit as an overlay; deviation in aquaculture feed commodity indices or marine fuel logistics costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and bioreactor capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
APAC Savoury Ingredients Market
Ingredients
North America Brewing Enzymes Market
Ingredients
Yeast Flakes Market
Ingredients
Global Natural Gum Market
Ingredients
Feed Premix Market
Ingredients
Wheat Germ Oil Market
Ingredients
Canola Meal Market
Ingredients
Animal and Marine Fats and Oils Market
Ingredients
Canada Whey Protein Ingredients Market
Ingredients
Cosmetic Bioactive Ingredients Market
Ingredients
Global Distillers Grains Market
Ingredients
Birch Sap Market
Ingredients
Global Egg Yolk Oil Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Europe Agar Market
Ingredients
Europe Corn Glucose Market