
 India Soy Protein Market | 2026-2036
India Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
India Soy Protein Market Foresight
Food technologist shortages across India's protein processing sector is reorganizing how manufacturers scale extraction and formulation capabilities. Bunge India leverages its integrated crushing and refining infrastructure to dominate bulk soy protein supply to institutional buyers. Sonic Biochem Extractions specializes in high-purity isolates for pharmaceutical and nutraceutical channels. Patanjali Foods anchors its position through Ayurveda-aligned branding and deep rural distribution networks.
India soy protein encompasses defatted soybean meal processed into flour, concentrate, isolate, or textured forms, typically containing 50% to 90% protein by weight depending on extraction method, with isolate achieving the highest purity through alkaline extraction and isoelectric precipitation. The ingredient serves primarily as a functional emulsifier, gelling agent, and economical protein fortifier across food systems. Textured soy protein leads volume consumption due to its direct substitution utility in institutional meat analogue production. Soy isolate commands premium positioning in nutritional supplements and clinical nutrition where protein digestibility-corrected amino acid scores determine formulation value. Dairy alternatives represent the fastest-expanding application channel, driven by lactose-intolerant demographics and urban café culture adoption.
FSSAI protein labeling norms and the Food Safety and Standards (Health Supplements, Nutraceuticals) Regulations govern product claims, while BIS certification requirements for soy-based ingredients shape import and domestic manufacturing standards. The PLI scheme for food processing infrastructure is channeling capital toward solvent extraction and extrusion capacity expansion. Stakeholders must monitor evolving FSSAI thresholds for heavy metal contaminants and genetically modified organism traceability, as these will determine which processing technologies and sourcing geographies remain viable for scaled supply to India's food manufacturing ecosystem.
Market Dynamics
FSSAI's tightening protein fortification standards and the PLI scheme for food processing infrastructure are restructuring how manufacturers configure extraction capacity and compliance systems across Maharashtra and Gujarat processing clusters.
Growth Catalysts
- PLI scheme incentives:Capital subsidies for solvent extraction and extrusion equipment are accelerating capacity expansion among domestic processors seeking import substitution.
- Flexitarian diet adoption:Urban consumers in metropolitan centers are driving institutional procurement of textured soy protein for meat analogue formulations in quick-service restaurant supply chains.
- Maharashtra-Gujarat corridor concentration:Overlapping soybean cultivation zones and food processing infrastructure create integrated supply advantages for regional manufacturers.
Market Restraints
- Hexane price volatility:Solvent extraction dependence exposes processors to petrochemical input cost swings that compress margin structures.
- Food technologist scarcity:Specialized protein formulation expertise concentrates in Mumbai and Ahmedabad, constraining scale-up for tier-2 facility operators.
- FSSAI GMO traceability thresholds:Evolving genetically modified organism detection standards threaten import sourcing flexibility from key supplier origins.
Strategic Opportunities
- Pharmaceutical-grade isolate demand:CDSCO-aligned nutraceutical manufacturers seek high-purity soy protein for clinical nutrition applications with protein digestibility-corrected amino acid score certification.
- Rural distribution channel penetration:Ayurveda-aligned branding creates positioning white space in tier-3 and tier-4 cities beyond existing urban retail concentration.
- Dairy alternative café culture:Lactose-intolerant demographics and metropolitan beverage service expansion drive isolate demand for plant-based milk formulations.
Industry Challenges
- BIS certification timeline compression:Standards body approval delays for new soy-based ingredient specifications bottleneck product launch schedules for reformulated offerings.
- Legacy equipment integration:Retrofitting solvent extraction lines with isoelectric precipitation capability for isolate production demands capital reconfiguration without guaranteed offtake.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Soy Protein Market |
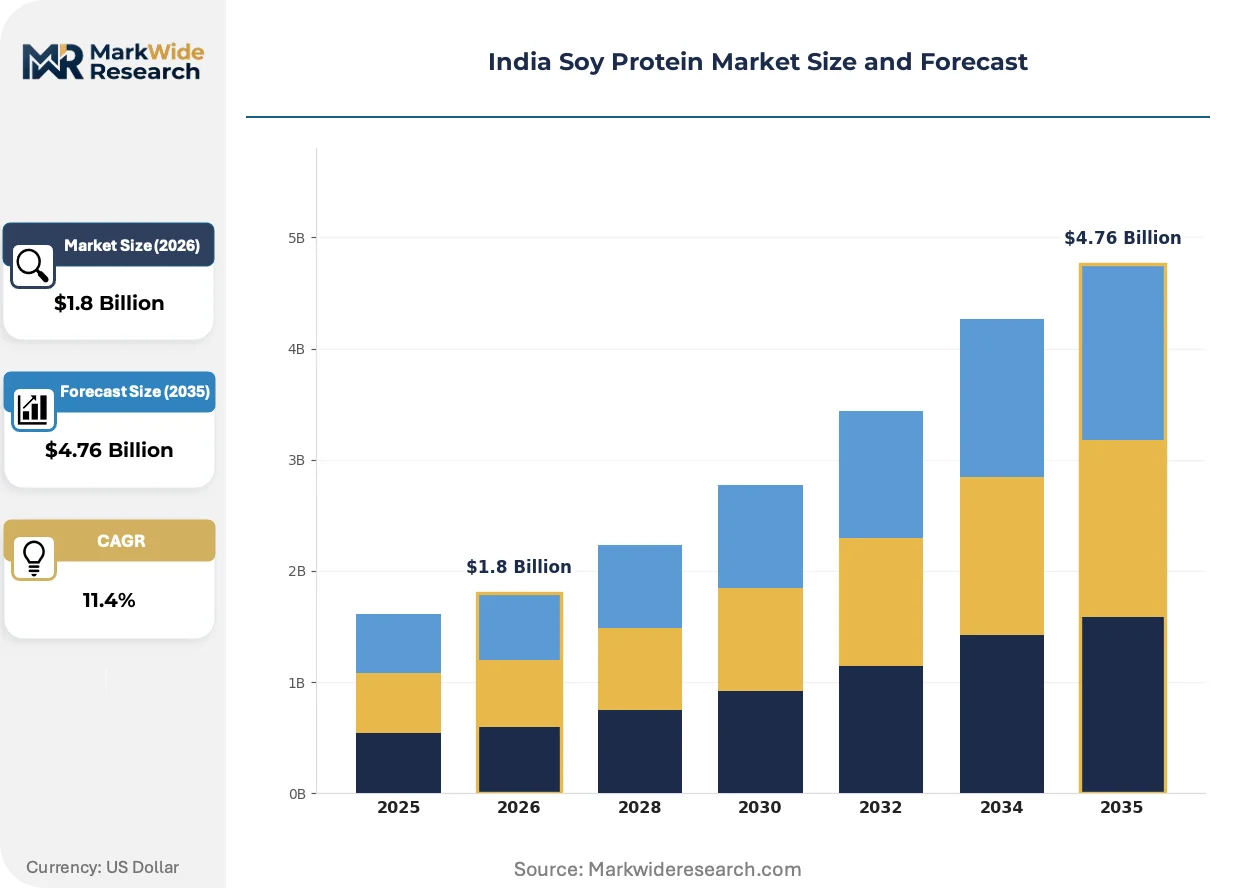
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Flour, Soy Isolate, Soy Concentrate, Textured Soy Protein Application: Meat Alternatives, Dairy Alternatives, Bakery Products, Nutritional Supplements Customer Type: Retail Consumers, Food Service Providers, Manufacturers, Health Clubs Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales |
| Companies Covered | Bunge India, Anand Agro, Patanjali Foods, Zydus Wellness, Agro Solvent Products, Sonic Biochem Extractions, Marico, Tata Consumer Products, Cargill India, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Soy Protein Market Shifts & Advancements
Membrane filtration and precision fermentation are converging with traditional mechanical extraction, compressing purity thresholds and enabling novel protein ingredient categories that bypass conventional processing economics.
Alkaline extraction coupled with membrane filtration is miniaturizing the capital footprint required for isolate-grade production. Mid-scale processors in Surat and Indore are adopting skid-mounted systems that achieve 90% protein purity without full-scale precipitation infrastructure. This technology is miniaturizing barrier-to-entry economics, fragmenting supply concentration previously held by integrated crushing-refining operations.
FSSAI's proposed heavy metal contaminant thresholds under the Food Safety and Standards Act are forcing solvent source verification and extraction residue monitoring protocols. Manufacturers sourcing from Madhya Pradesh and Rajasthan cultivation belts face elevated testing cadences. The isolate segment bears disproportionate compliance burden given its pharmaceutical and infant nutrition end-uses.
Ingredient specification contracts are compressing from annual to quarterly renewal cycles as quick-service restaurant chains and nutraceutical formulators demand batch-level certificate of analysis documentation. Direct procurement relationships between Maharashtra processing facilities and institutional buyers are displacing traditional trader-mediated spot market transactions. This pattern concentrates most visibly in Mumbai-Pune logistics corridors serving western India food manufacturing clusters.
India Soy Protein Market Segmentation
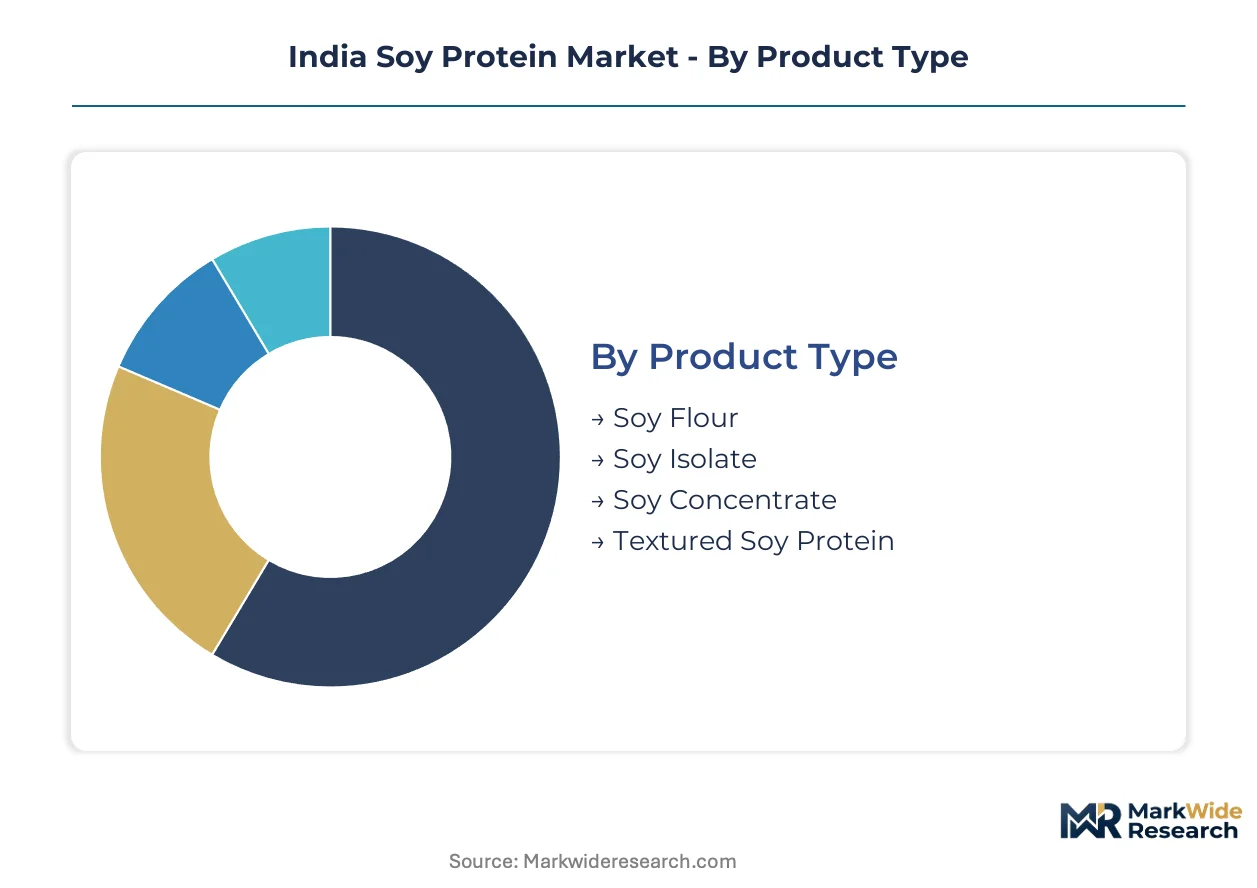
Soy protein processors in India configure product portfolios around extraction technology tiers and end-use purity requirements. Substitution dynamics from pea and rice protein alternatives are compressing margins in lower-concentration categories while accelerating investment in isolate-grade capabilities.
Product Type:
Soy flour faces the most acute substitution pressure from domestic pulse protein alternatives, while isolate commands defensible positioning through pharmaceutical-grade certification barriers.
- Soy Flour:Defatted meal ground to 20-100 mesh particle size with 50-54% protein content serves as the lowest-cost fortification option. Maharashtra-based bakery and extruded snack manufacturers absorb the bulk of volume, though price competition from chickpea flour is eroding share in traditional applications.
- Soy Isolate:Alkaline extraction followed by isoelectric precipitation yields 90%+ protein purity with minimal oligosaccharide residue. CDSCO-aligned nutraceutical formulators in Mumbai and Ahmedabad drive demand, paying premiums for protein digestibility-corrected amino acid score documentation that plant competitors rarely match.
- Soy Concentrate:Aqueous alcohol washing removes soluble carbohydrates to achieve 65-70% protein concentration. Institutional meat analogue producers in Gujarat leverage this grade for cost-optimized textured applications.
- Textured Soy Protein:Thermoplastic extrusion of defatted flour or concentrate creates fibrous structures for direct meat substitution. Quick-service restaurant supply chains across Pune and Surat represent the dominant offtake channel.
Textured soy protein retains volume leadership; soy isolate holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity food manufacturing from clinical nutrition, with pricing spreads widening between institutional and pharmaceutical-grade end-uses.
- Meat Alternatives:Textured soy protein serves as the backbone for institutional vegetarian product lines across western India quick-service restaurants. Flexitarian menu expansion in Mumbai-Pune corridors is accelerating textured volume requirements beyond traditional temple food and railway catering applications.
- Dairy Alternatives:Soy isolate provides emulsion stability and neutral flavor profiles for plant-based milk and café beverage formulations. Lactose-intolerant demographics in Bengaluru and Hyderabad metro zones are driving isolate procurement for specialty coffee chain supply.
- Bakery Products:Soy flour functions as an economical egg replacement and moisture retention agent in mass-market bread and biscuit production. FSSAI protein fortification mandates for school feeding programs are sustaining baseline demand.
- Nutritional Supplements:Isolate and hydrolyzed concentrates target sports nutrition and clinical dietetic applications. CDSCO registration requirements and heavy metal testing protocols create compliance moats that filter out lower-grade suppliers.
Meat alternatives command the largest volume position; dairy alternatives are climbing the fastest.
Customer Type:
Procurement patterns diverge sharply between specification-driven institutional buyers and price-sensitive retail channels.
- Retail Consumers:Urban households in tier-1 cities purchase branded soy chunks and flour through modern trade. Ayurveda-aligned positioning from domestic packaged food companies is penetrating tier-3 markets previously dependent on unbranded commodity sourcing.
- Food Service Providers:Central kitchens and contract catering operations specify textured protein for standardized vegetarian protein portions. Institutional procurement contracts increasingly demand batch-level certificate of analysis documentation.
- Manufacturers:Processed food companies integrate soy ingredients across bakery, confectionery, and extruded snack formulations. Direct sourcing relationships with Maharashtra crushing facilities are displacing trader-mediated spot purchases.
- Health Clubs:Gyms and fitness centers distribute branded protein supplements to members. This channel remains fragmented, with most volume flowing through established nutraceutical retail networks rather than dedicated fitness procurement.
Manufacturers absorb the dominant volume share; health clubs are expanding most quickly as a dedicated channel.
Distribution Channel:
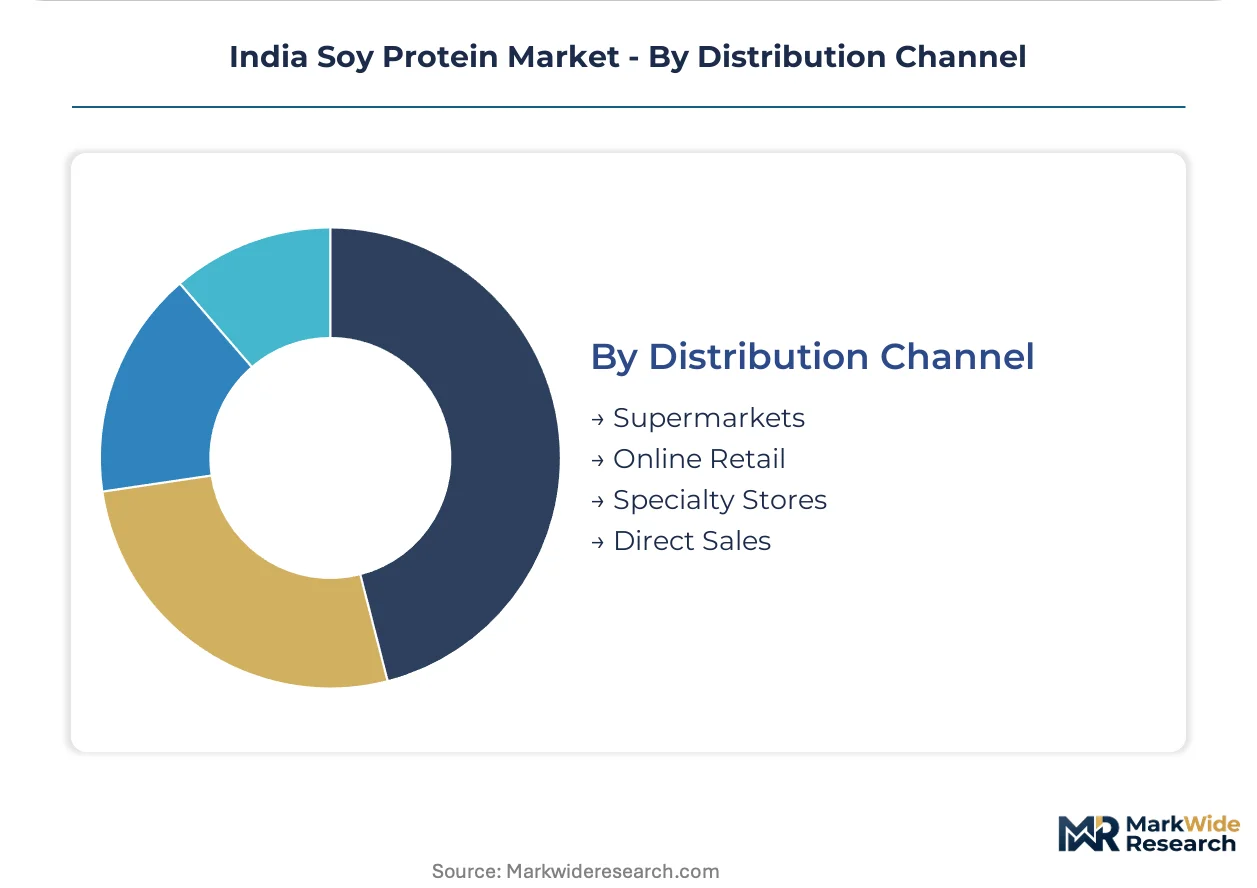
Supply concentration in Gujarat and Maharashtra processing clusters shapes logistics economics across channel types.
- Supermarkets:Organized retail chains in Mumbai, Pune, and Ahmedabad stock branded soy chunks and flour for urban household procurement. Shelf space allocation favors Ayurveda-positioned domestic brands over imported alternatives facing GMO traceability scrutiny.
- Online Retail:E-commerce platforms aggregate isolate and specialty concentrate sales for nutraceutical and fitness segments. Direct-to-consumer fulfillment bypasses traditional distributor margins but intensifies price transparency.
- Specialty Stores:Organic and health food retailers in metropolitan centers curate non-GMO and identity-preserved soy protein lines. Premium positioning targets lactose-intolerant and flexitarian demographics with higher willingness-to-pay.
- Direct Sales:Institutional manufacturers and food service operators procure bulk textured protein and flour through direct contracts with Gujarat and Maharashtra processing facilities. Quarterly specification contracts are compressing from annual renewal cycles.
Supermarkets retain volume leadership; online retail holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSSAI's regulatory framework anchors Maharashtra as the dominant processing geography, with Gujarat, Karnataka, Tamil Nadu, and Telangana forming complementary demand and supply nodes across India's soy protein ecosystem.
Maharashtra
Mumbai-Pune logistics corridors absorb the bulk of textured soy protein volume for quick-service restaurant supply chains. FSSAI protein fortification mandates for school feeding programs sustain institutional procurement from Solapur and Nagpur crushing facilities. Solvent extraction clusters in Latur and Akola districts are retrofitting isoelectric precipitation capability under PLI scheme capital subsidies.
Gujarat
Institutional meat analogue manufacturers in Surat and Ahmedabad drive concentrate-grade demand for cost-optimized formulations. BIS certification requirements for soy-based ingredients shape import substitution timelines for domestic processors. Vadodara-based extraction facilities are integrating membrane filtration skids to miniaturize isolate-grade production footprints.
Karnataka
Bengaluru metro zone demand for dairy alternatives accelerates isolate procurement for plant-based milk formulations. CDSCO-aligned nutraceutical formulators in the city seek protein digestibility-corrected amino acid score documentation. Mysuru food processing parks are attracting mid-scale processors with Ayurveda-aligned branding capabilities for tier-3 market penetration.
Tamil Nadu
Chennai's central kitchen infrastructure specifies textured protein for standardized vegetarian protein portions in contract catering. FSSAI heavy metal contaminant thresholds force elevated testing cadences for processors sourcing from cross-state cultivation belts. Coimbatore extrusion equipment fabricators are supplying skid-mounted systems to Surat and Indore mid-scale operators.
Telangana
Hyderabad's lactose-intolerant demographics and specialty coffee chain expansion drive isolate demand for café beverage formulations. DGFT import policy frameworks influence GMO traceability compliance costs for processors reliant on external soybean sourcing. Genome Valley pharmaceutical corridors are attracting CDSCO-registered nutraceutical formulators seeking clinical-grade isolate supply.
India Soy Protein Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across India's soy protein sector. Integrated crushing-refining operations dominate bulk supply through economies of scale, while specialized extraction firms command premium tiers through purity certification. Three archetypes define competitive positioning: multinational agribusiness integrators, domestic Ayurveda-aligned consumer brands, and mid-scale isolate specialists. Capacity expansion under PLI scheme incentives and direct procurement relationship formation are displacing trader-mediated spot market transactions.
Among multinational agribusiness integrators, Bunge India and Cargill India represent the scale-driven archetype with captive crushing and refining infrastructure. Domestic Ayurveda-aligned players Patanjali Foods and Zydus Wellness occupy positioning white space in tier-3 and tier-4 markets through rural distribution depth. Sonic Biochem Extractions exemplifies the specialist tier, anchoring high-purity isolate supply for pharmaceutical and nutraceutical channels where protein digestibility-corrected amino acid score documentation creates compliance moats.
| Leading Market Players |
|---|
| Bunge India |
| Anand Agro |
| Patanjali Foods |
| Zydus Wellness |
| Agro Solvent Products |
| Sonic Biochem Extractions |
| Marico |
| Tata Consumer Products |
| Cargill India |
| Others |
Supply & Pricing Matrix
Quarterly specification contracts with batch-level certificate of analysis documentation lock in both supply access and price visibility for institutional buyers sourcing from Maharashtra and Gujarat processing clusters. This contracting pattern compresses procurement cycles while binding processors to FSSAI heavy metal testing protocols that elevate cost structures for isolate-grade production.
Pricing Analysis
Maharashtra-Gujarat corridor pricing spreads widen against Madhya Pradesh and Rajasthan sourcing belts due to logistics premiums and testing cadence differentials. Three-tier pricing structure across pharmaceutical-grade isolate, institutional concentrate, and economy flour segments separates CDSCO-registered nutraceutical formulators from quick-service restaurant supply chains and school feeding programs. Cost compression in soy flour runs through chickpea flour substitution pressure in bakery applications. Quick-service restaurant chains exhibit highest price sensitivity; CDSCO-aligned clinical nutrition formulators show lowest.
Supply Chain Analysis
India anchors soybean crushing and extraction infrastructure while Argentina and Brazil feed raw bean imports subject to DGFT GMO traceability compliance costs. Solvent extraction lines draw from petrochemical hexane supplies; membrane filtration skids source precision pump and ceramic membrane components from European and Japanese vendors. Single-source vulnerability concentrates in hexane supply channels exposed to crude oil price volatility. Distribution runs through direct procurement relationships displacing trader-mediated spot transactions in Mumbai-Pune corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certificate of analysis documentation and technical formulation support services attach recurring revenue layers expanding faster than commodity isolate and concentrate sales. After-sales compliance consulting for FSSAI and CDSCO alignment creates stickier customer relationships than transactional ingredient supply.
For Market Incumbents: Secure backward integration into Madhya Pradesh and Rajasthan cultivation belts to control identity-preserved soybean sourcing against GMO traceability threshold tightening. Lock in food technologist talent pools in Mumbai and Ahmedabad through specialized extraction training partnerships with regional engineering institutes. Patanjali Foods' rural distribution depth demonstrates channel control leverage that Bunge India's scale advantages cannot replicate in tier-3 markets.
For New Entrants and Emerging Players: Anchor in Karnataka's Bengaluru dairy alternative formulation cluster where isolate demand for plant-based milk outpaces domestic supply. Target Ayurveda-aligned branding white space in Telangana and Tamil Nadu tier-3 cities beyond Patanjali Foods' current penetration. Lead with CDSCO-registered isolate supply to Genome Valley pharmaceutical corridors as the go-to-market angle bypassing commodity competition.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among CDSCO-registered isolate specialists with protein digestibility-corrected amino acid score certification capabilities. Five-to-ten year viability favors mid-scale processors with membrane filtration skids and direct institutional contracts over legacy solvent extraction operations dependent on hexane price stability. Acquisition target archetype: Surat or Indore-based isolate specialists with pharmaceutical channel penetration. Signal to watch: FSSAI finalization of heavy metal contaminant thresholds forcing consolidation among sub-scale testing facilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Capacity Addition | Skid-mounted systems miniaturize isolate production barriers for mid-scale Surat and Indore processors. |
| CDSCO Registration Investment | Pharmaceutical-grade certification creates compliance moats filtering out lower-purity competitors. |
| Backward Integration into Cultivation | Identity-preserved soybean sourcing hedges DGFT GMO traceability compliance cost escalation. |
| Direct Institutional Contracting | Quarterly specification agreements displace trader-mediated spot markets in Mumbai-Pune corridors. |
| Ayurveda-Aligned Brand Extension | Rural distribution penetration captures tier-3 and tier-4 demand beyond urban retail concentration. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FSSAI regulatory filings, BIS certification databases, and PLI scheme disbursement records. Food technologists at Maharashtra and Gujarat extraction facilities, procurement managers at quick-service restaurant central kitchens, CDSCO regulatory affairs leads, and Solvent Extractors Association representatives provided operational perspective. Trade data from DGFT, customs records, and SEC filings of listed agribusiness parents supplied volume and capacity benchmarks. Bottom-up installation counts triangulate against top-down consumption estimates from institutional procurement patterns.
Segmentation dimensions modeled span product type hierarchy from flour through isolate, application channels from meat alternatives through clinical nutrition, customer archetypes from retail consumers through manufacturers, and distribution structures from supermarkets through direct sales. CAGRs derive from installed capacity expansion trajectories under PLI incentives and per-capita protein consumption elasticity assumptions. Forecast inputs include flexitarian diet adoption curves in metropolitan centers and lactose-intolerant demographic expansion rates across southern India.
Decision-makers should treat outputs as directional under assumptions of stable FSSAI regulatory timelines and continued PLI scheme capital subsidy availability; material deviation in hexane price volatility or GMO traceability threshold stringency would warrant model refresh. Recalibration cycles align with material shifts in PLI disbursement patterns and FSSAI final rule publications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Orange Powder Market
Ingredients
Gluten-Free Flour Market
Ingredients
Asia-Pacific Soy Protein Market
Ingredients
Ice Cream Bases Market
Ingredients
Valerian Root Oil Market
Ingredients
Spelt Flour Market
Ingredients
Chickpea Flour Market
Ingredients
Europe Soy Protein Market
Ingredients
Birch Sap Market
Ingredients
Bertholletia Excelsa Seed Oil Market
Ingredients
Buckwheat–Mediterranean Grain Blend Ingredients Market
Ingredients
Food Amino Acids Market
Ingredients
Europe Dairy Ingredients Market
Ingredients
Freeze-Dried Pea Isolates Market
Ingredients
European Brewing Enzymes Market
Ingredients
Carica Papaya Seed Oil Market