
 Ahiflower Oil Market | 2026-2036
Ahiflower Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Ahiflower Oil Market Outlook
Pharmaceutical-grade ahiflower oil certification is redrawing competitive boundaries in specialty lipids. Natures Crops International anchors global seed supply through proprietary cultivation networks. Bioriginal Food & Science Corp. leverages extraction scale to dominate bulk ingredient contracts. Evonik Nutrition & Care GmbH differentiates through omega profile standardization for medical nutrition.
Ahiflower oil is a pressed seed oil containing stearidonic acid and gamma-linolenic acid in a plant-derived omega-3,6,9 profile, produced through cold-press or supercritical CO2 extraction for dietary supplement and cosmetic formulations. The oil extract segment leads volume due to bulk manufacturing demand, while softgel formats capture concentrated margin pools in clinical nutrition. Nutraceutical applications outpace personal care growth as clinicians validate ahiflower's fatty acid bioavailability against marine alternatives.
EFSA novel food approvals and FDA GRAS notifications govern ingredient market access in Europe and the United States, with REACH compliance shaping supply chain chemistry standards for European cosmetic use. USDA organic certification and Non-GMO Project verification increasingly filter retail channel eligibility in North America. Stakeholders must monitor evolving omega-3 health claim regulations to anticipate reformulation cycles and geographic licensing priorities.
Market Dynamics
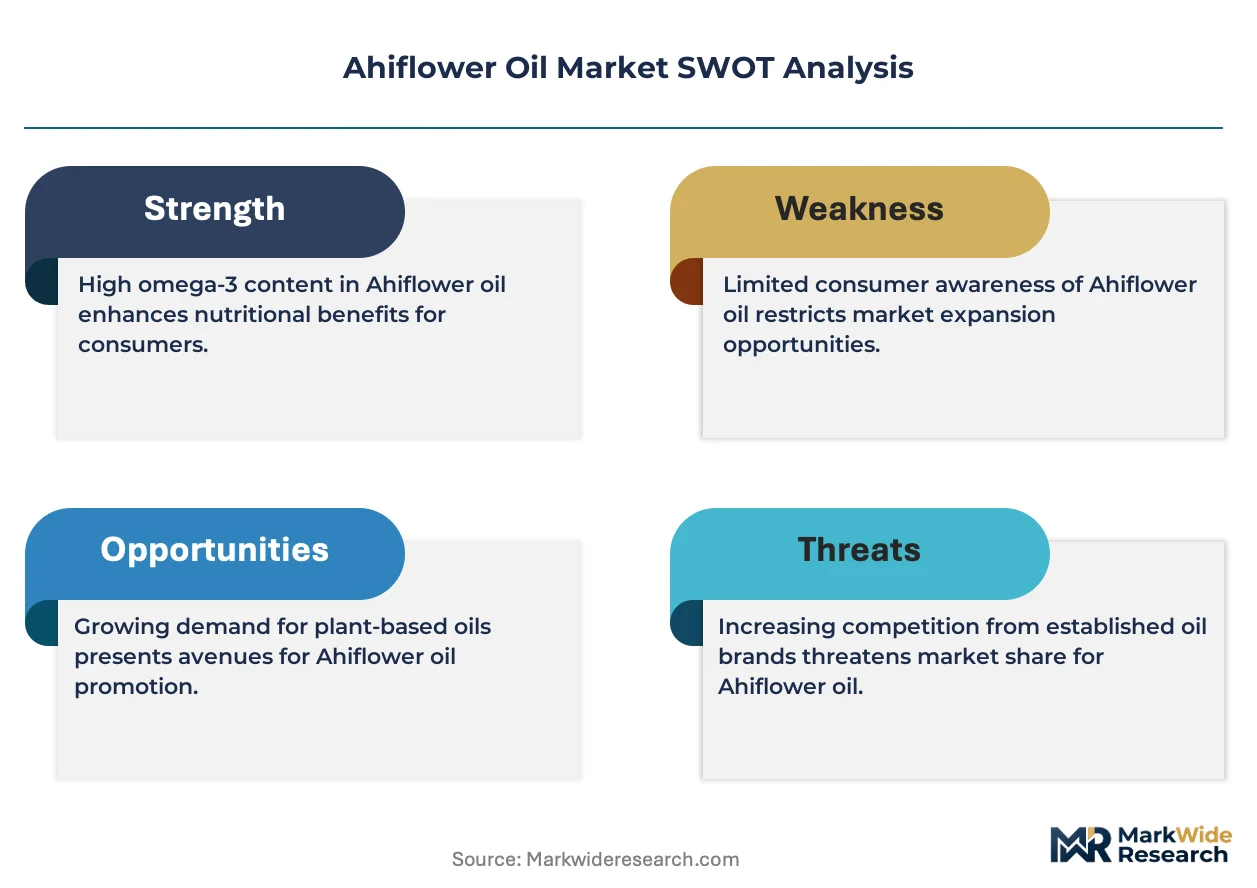
Clean-label tightening across the European Union is forcing nutraceutical formulators to abandon marine omega sources for plant-derived alternatives with traceable supply chains and carbon-verified credentials.
Growth Catalysts
- EFSA Novel Food Pathway:Streamlined approvals for ahiflower-derived ingredients accelerate European market entry for specialty lipid suppliers seeking differentiated positioning.
- Clinical Nutrition Demand:Hospital feeding protocols and medical nutrition manufacturers validate stearidonic acid bioavailability against fish oil in parenteral and enteral applications.
- Supercritical CO2 Extraction:Solvent-free processing technology eliminates thermal degradation of polyunsaturated fatty acids while meeting cosmetic-grade purity thresholds.
Market Restraints
- Seed Supply Concentration:Proprietary cultivation networks in the United Kingdom and Canada create single-source dependency for global ahiflower seed stock.
- REACH Compliance Burden:European chemical registration requirements impose documentation costs and timeline delays for cosmetic ingredient market access.
- Marine Omega Price Compression:Anchovy and krill oil oversupply from Peruvian and Antarctic fisheries undercuts plant-derived premium positioning in bulk supplement channels.
Strategic Opportunities
- German Functional Food Integration:Bakery and dairy processors in Bavaria and North Rhine-Westphalia seek omega-enriched formulations for aging-population nutrition products.
- USDA Organic Certification Gap:Limited certified-organic ahiflower acreage creates first-mover advantage for suppliers securing transitional land contracts.
- Direct-to-Practitioner Channels:Functional medicine clinics and registered dietitians bypass retail markup through practitioner-exclusive softgel formats.
Industry Challenges
- Pharmaceutical-Grade Validation Timeline:FDA drug master file preparation and current good manufacturing practice audits extend certification cycles beyond typical nutraceutical development windows.
- Omega-3 Oxidation Control:Packaging engineers struggle with oxygen barrier integrity for high-PUFA oils across extended distribution networks in variable climates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ahiflower Oil Market |
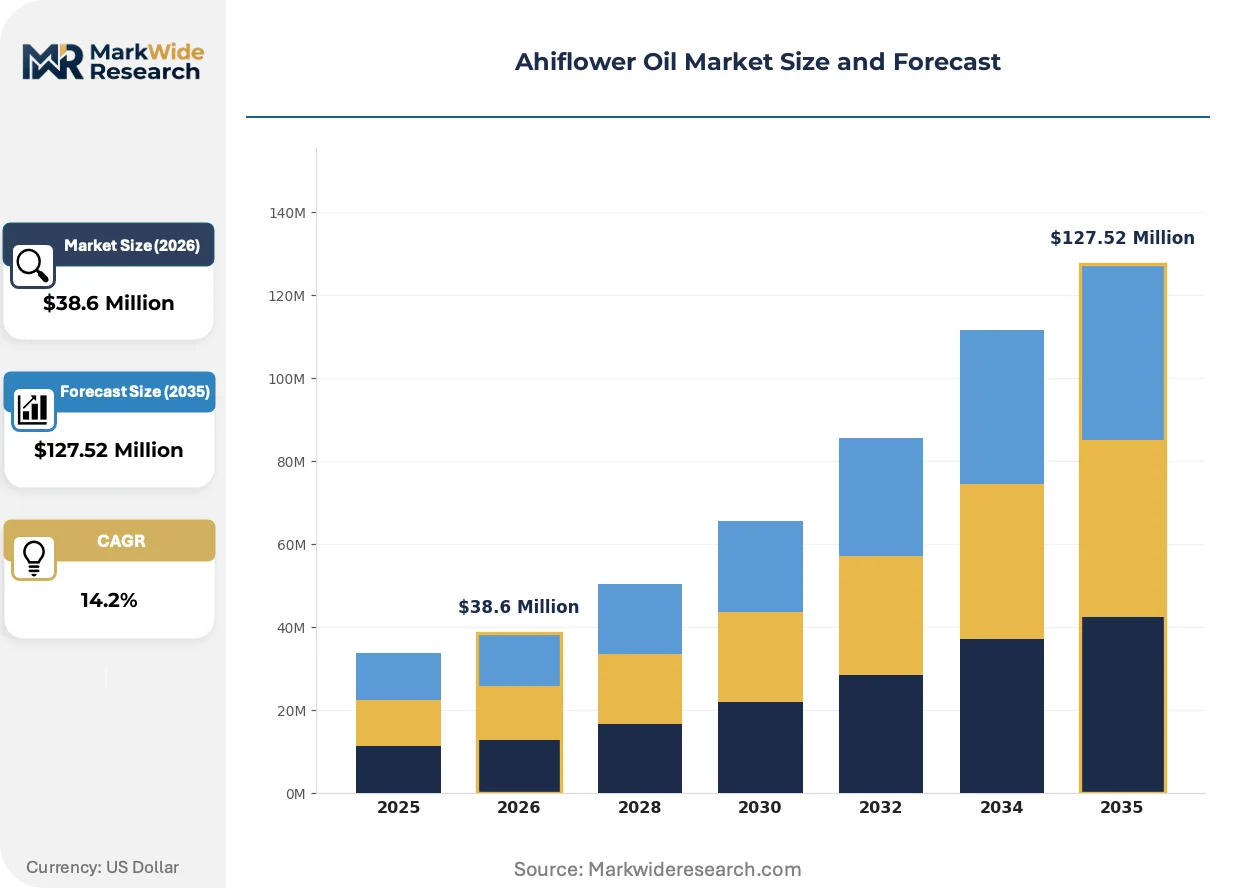
| Market Size in 2026 | $38.6 Million |
| Market Size in 2035 | $127.52 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oil Extract, Powder, Softgel, Capsule Application: Food Supplement, Personal Care, Nutraceutical, Pharmaceuticals End User: Retail Consumers, Health Professionals, Manufacturers, Distributors Distribution Channel: Online, Supermarkets, Health Stores, Wholesale |
| Companies Covered | Bioriginal Food & Science Corp., Source Naturals, Natures Crops International, Aromaland, Ahiflower, Henry Lamotte Oils GmbH, Technology Crops International Ltd., Evonik Nutrition & Care GmbH, Connoils LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ahiflower Oil Market Strategic Shifts
Extraction technology maturation and regulatory pathway clarification are compressing development cycles for novel plant lipid ingredients while fragmenting buyer power across specialized channels.
Supercritical CO2 extraction systems with integrated fractionation capabilities are displacing traditional cold-press methods in premium ahiflower oil production. Specialty lipid manufacturers in Germany and Switzerland deploy these systems to achieve selective stearidonic acid concentration for medical nutrition contracts. The technology is displacing solvent-based refining infrastructure across European cosmetic ingredient suppliers seeking REACH-compliant process chemistry.
EFSA health claim substantiation requirements for polyunsaturated fatty acids have tightened evidentiary standards for omega-3 marketing in the European Union. Supplement and food manufacturers must now demonstrate dose-response relationships for cardiovascular and cognitive benefit claims. German and United Kingdom brands are responding with reformulated serving sizes and clinical trial investments to maintain label differentiation.
Practitioner-directed dispensing models are capturing margin pools previously held by mass-market retail channels. Functional medicine networks in the United States and integrative health clinics in the United Kingdom now source ahiflower oil through professional-exclusive distribution agreements. This channel rotation is most visible in California and London metropolitan clusters where patient co-payment models favor premium-priced clinical formats over commodity softgels.
Ahiflower Oil Market Segmentation
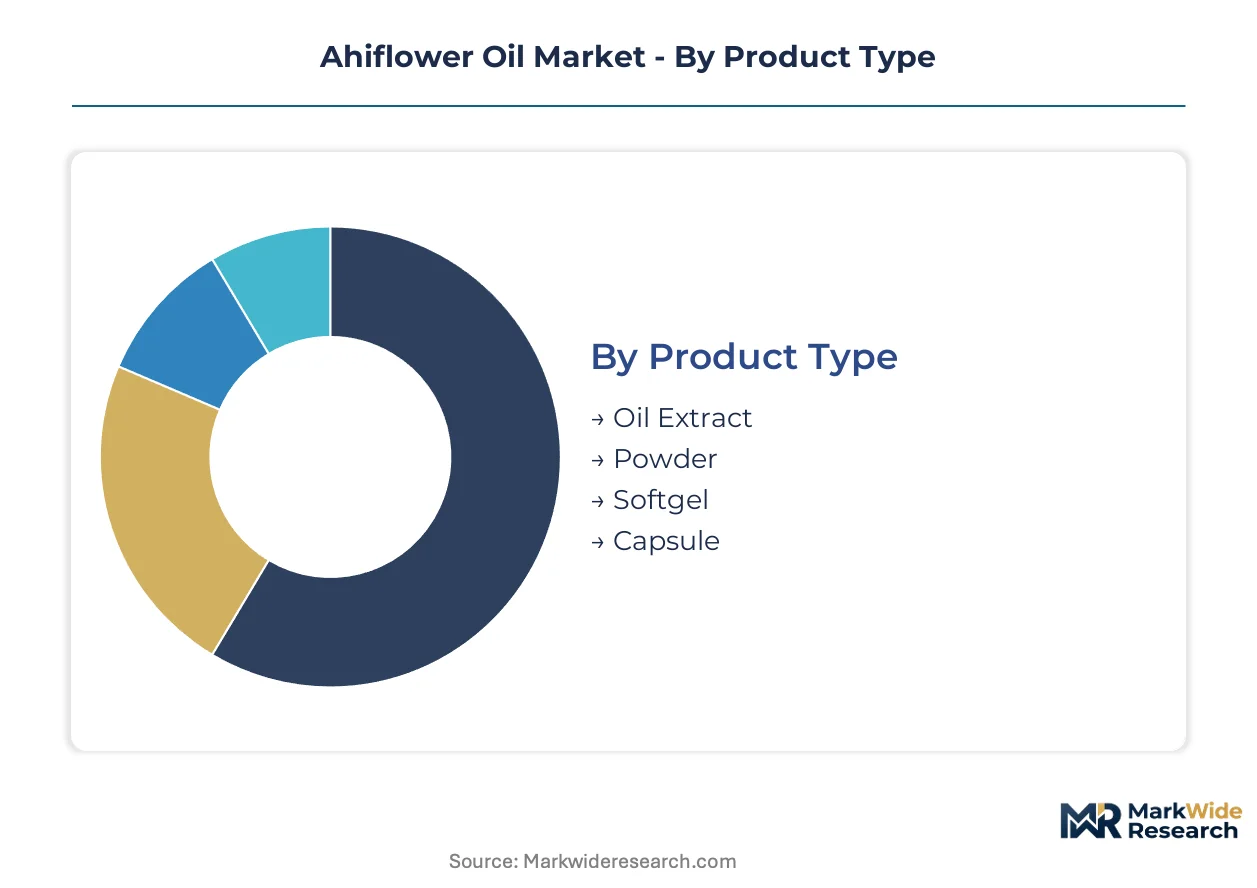
Ahiflower oil's commercial trajectory fragments across four critical dimensions: physical formulation, end-use application, buyer archetype, and route to market. Each segmentation layer reveals distinct margin structures, regulatory exposure, and geographic concentration patterns that suppliers must navigate.
Product Type:
Domestic production in the United Kingdom and Canada concentrates on bulk oil extract for export, while softgel and capsule manufacturing gravitates toward contract finishers in Germany and the United States.
- Oil Extract:Cold-pressed or supercritical CO2-extracted crude oil with standardized stearidonic acid content serves bulk nutraceutical compounders and cosmetic formulators. German functional food manufacturers in Bavaria drive European demand for unrefined extract in omega-enriched bakery applications.
- Softgel:Encapsulated oil in gelatin or plant-based shells delivers precise dosing for clinical nutrition and practitioner channels. California functional medicine clinics and London integrative health networks source practitioner-exclusive softgel formats through direct distribution agreements.
- Powder:Microencapsulated oil powder enables dry-blend integration into protein supplements and meal replacements. Sports nutrition brands in the United States leverage powder format for shelf-stable omega fortification.
- Capsule:Hard-shell gelatin or HPMC capsules target mass-market retail positioning with lower per-unit cost structures. United Kingdom health food retailers stock capsule formats for price-sensitive consumer segments.
Oil extract holds the largest share; momentum sits with softgel as practitioner channels expand.
Application:
Cost tier differentiation separates premium pharmaceutical-grade validation from commodity supplement positioning.
- Nutraceutical:Dietary supplement formulations leverage ahiflower's plant-derived omega profile for clean-label positioning against marine alternatives. EFSA novel food approvals and FDA GRAS notifications govern ingredient access in Europe and the United States.
- Food Supplement:Omega-enriched functional foods target aging-population nutrition in Germany and the United Kingdom. Bakery and dairy processors in Bavaria and North Rhine-Westphalia seek stearidonic acid integration for cardiovascular health positioning.
- Personal Care:Cosmetic-grade oil with REACH-compliant process chemistry enters European skincare formulations. Swiss and German cosmetic ingredient suppliers deploy supercritical CO2 extraction for selective fatty acid concentration.
- Pharmaceuticals:Medical nutrition and parenteral feeding applications require drug master file preparation and current good manufacturing practice audits. Hospital feeding protocols in the United States validate stearidonic acid bioavailability against fish oil.
Nutraceutical captures the dominant revenue pool; food supplement climbs fastest as German functional food integration accelerates.
End User:
Customer type determines pricing power, with health professionals commanding premium margins through exclusive distribution.
- Health Professionals:Functional medicine physicians and registered dietitians prescribe clinical-grade softgels through direct-to-practitioner channels. Patient co-payment models in California and London metropolitan clusters favor premium formats.
- Manufacturers:Bulk compounders and finished goods producers source oil extract and powder for private-label and branded product lines. Contract manufacturers in Germany and the United States blend ahiflower oil into multi-ingredient formulations.
- Retail Consumers:Mass-market purchasers select capsule and softgel products through supermarkets and online channels. USDA organic certification and Non-GMO Project verification filter retail eligibility in North America.
- Distributors:Ingredient brokers and wholesale intermediaries aggregate supply for smaller nutraceutical brands. Inventory risk concentrates with distributors managing omega-3 oxidation control across variable climates.
Manufacturers represent the largest procurement volume; health professionals deliver the steepest margin expansion.
Distribution Channel:
Supply concentration in proprietary seed networks shapes channel economics, with direct online models bypassing traditional wholesale markups.
- Online:Direct-to-consumer and practitioner-exclusive e-commerce platforms capture margin pools previously held by retail intermediaries. California and London digital health networks drive subscription-based replenishment models.
- Health Stores:Specialty retailers in the United Kingdom and United States stock premium-positioned softgel and capsule formats. Staff-trained recommendation environments support higher price points.
- Wholesale:Bulk ingredient supply to compounders and contract manufacturers runs through established nutraceutical distributors. Documentation burdens for REACH compliance and organic certification concentrate with wholesale intermediaries.
- Supermarkets:Mass-market retail placement demands price-competitive capsule formats and consumer education investments. German and United Kingdom grocery chains trial omega-enriched functional food positioning.
Wholesale dominates volume throughput; online gains share fastest as direct-to-practitioner models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Proprietary seed stock concentrates in the United Kingdom and Canada, creating geographic dependency for global supply. Formulation demand clusters in Germany and the United States. Regulatory divergence between FDA GRAS pathways and EFSA novel food approvals shapes regional entry strategies.
United Kingdom
Domestic ahiflower cultivation in East Anglia supplies proprietary seed networks for global export. EFSA novel food approvals govern ingredient access for European nutraceutical formulators. London integrative health clinics drive practitioner-exclusive softgel demand through direct distribution agreements.
Germany
Bavarian and North Rhine-Westphalian functional food processors seek omega-enriched bakery and dairy formulations. REACH compliance requirements impose documentation burdens for cosmetic ingredient market access. Supercritical CO2 extraction systems in Swiss and German facilities achieve selective stearidonic acid concentration for medical nutrition contracts.
United States
California functional medicine networks bypass retail markup through practitioner-exclusive channels. FDA GRAS notifications and USDA organic certification filter retail eligibility. Hospital feeding protocols validate stearidonic acid bioavailability against fish oil in parenteral applications.
Canada
Prairie province cultivation networks anchor North American seed supply for bulk oil extract production. Health Canada and PMRA regulate cosmetic and food ingredient safety standards. Contract finishers in Ontario and Quebec concentrate softgel manufacturing for US export.
Switzerland
Swissmedic pharmaceutical-grade certification requirements shape medical nutrition ingredient validation timelines. Swiss cosmetic ingredient suppliers deploy supercritical CO2 fractionation for REACH-compliant process chemistry. Zurich and Basel specialty lipid manufacturers serve German and French formulator demand.
Ahiflower Oil Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the ahiflower oil value chain. The market structure concentrates upstream around proprietary seed supply while fragmenting downstream across formulation and distribution tiers. Two strategic archetypes dominate: cultivation-integrated suppliers controlling genetic stock and extraction-scale compounders serving bulk ingredient contracts. Competitive moves center on pharmaceutical-grade certification investments and direct-to-practitioner channel expansion.
Within the cultivation-integrated tier, Natures Crops International and Technology Crops International Ltd. represent proprietary seed network control. Bioriginal Food & Science Corp. exemplifies the extraction-scale archetype, occupying a position in bulk compounder supply. These three entities anchor the competitive structure without full vertical integration across all value chain stages.
| Leading Market Players |
|---|
| Bioriginal Food & Science Corp. |
| Source Naturals |
| Natures Crops International |
| Aromaland |
| Ahiflower |
| Henry Lamotte Oils GmbH |
| Technology Crops International Ltd. |
| Evonik Nutrition & Care GmbH |
| Connoils LLC |
| Others |
Value Chain & Pricing Dynamics
Cold-press and supercritical CO2 extraction capacity utilization in Canadian and United Kingdom facilities shapes both supply concentration and minimum viable price floors for ahiflower oil across pharmaceutical-grade and nutraceutical tiers. Scale economies at Natures Crops International's proprietary cultivation networks anchor upstream cost structures while downstream formulators absorb certification premiums for EFSA novel food and FDA GRAS compliance.
Pricing Analysis
EFSA novel food and FDA GRAS regulatory tiers dictate the pricing structure across pharmaceutical, nutraceutical, and cosmetic grades. Three-tier pricing stratifies across premium pharmaceutical-grade stearidonic acid concentrates, standard nutraceutical softgels, and economy bulk oil extract for compounders. Price differentiation hinges on certification investment depth and volume scale, with per-unit costs compressing at bulk offtake volumes above metric-ton thresholds. Pricing pressure stems from Peruvian anchovy oil oversupply undercutting plant-derived premiums in mass-market supplement channels. Retail consumers through supermarket and online channels exhibit highest price sensitivity, while health professionals in California and London functional medicine networks absorb premium markups for practitioner-exclusive formats.
Supply Chain Analysis
East Anglia cultivation networks and Canadian prairie province seed stock create dual-hemisphere chokepoints for global ahiflower oil supply. Raw material flows draw from proprietary germplasm, agricultural land contracts, and cold-chain logistics infrastructure for PUFA preservation. Single-source dependency on Natures Crops International and Technology Crops International germplasm repositories concentrates supply chain risk around genetic stock vulnerability and climate exposure. Distribution runs through wholesale nutraceutical distributors for bulk compounders, direct-to-practitioner e-commerce for clinical formats, and health store retail for premium consumer positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ahiflower oil's competitive structure rewards regulatory entrenchment as the primary defensive moat. EFSA novel food and FDA GRAS approval timelines create switching costs that lock in formulator relationships and deter rapid competitive displacement.
For Market Incumbents: Fortify proprietary seed network control through expanded cultivation contracts in Canadian prairie provinces and United Kingdom East Anglia regions. Deepen backward integration into supercritical CO2 extraction capacity to capture margin pools currently held by German and Swiss toll processors. Marine omega price compression from Peruvian fisheries threatens bulk supplement positioning; respond with pharmaceutical-grade certification investments that anchovy oil cannot replicate.
For New Entrants and Emerging Players: Anchor in USDA organic certification gaps across transitional acreage in North American prairie provinces, where limited certified-organic supply creates first-mover pricing power. Target German functional food processors in Bavaria and North Rhine-Westphalia seeking omega-enriched bakery and dairy formulations with REACH-compliant ingredient documentation. Pursue direct-to-practitioner channel partnerships with California functional medicine networks and London integrative health clinics as the most penetrable high-margin entry vector.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cultivation-integrated suppliers with captive germplasm and extraction-scale compounders serving medical nutrition contracts. Long-term viability rests on clinical validation of stearidonic acid bioavailability against fish oil in parenteral applications, expanding addressable market beyond nutraceutical into pharmaceutical-grade validation. Watch EFSA health claim substantiation rulings on polyunsaturated fatty acid cardiovascular and cognitive benefits as the critical inflection signal for European market access expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | FDA drug master file preparation unlocks parenteral nutrition contracts beyond nutraceutical reach. |
| Proprietary Cultivation Network Expansion | Canadian and United Kingdom acreage growth secures germplasm control against climate and supply shocks. |
| Supercritical CO2 Extraction Scale-Up | German and Swiss facility investments capture REACH-compliant cosmetic and medical nutrition margin pools. |
| Direct-to-Practitioner Channel Development | California and London clinic partnerships bypass retail markup erosion in mass-market supplement channels. |
| USDA Organic Certification Acquisition | Transitional land contracts in North America create scarcity premium for clean-label retail eligibility. |
Study Parameters
The analysis maps oil extract, softgel, powder, and capsule formulation sub-sectors, each validated through seed cultivation managers, extraction technology specialists, nutraceutical formulators, and functional medicine practitioners. Primary interviews with contract manufacturers in Germany and Ontario, cosmetic ingredient procurement leads at Swiss and German suppliers, and registered dietitians in California and London integrative health networks combined with secondary validation from EFSA novel food registers, FDA GRAS notifications, REACH compliance databases, and USDA organic certification records. Bottom-up volume modeling across product type, application, end user, and distribution channel segments triangulated against top-down specialty lipid market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include physical formulation state, end-use application tier, buyer archetype pricing power, and route-to-market margin capture, with geographic regulatory clusters for Europe, North America, and United Kingdom-specific pathways. CAGRs derived from historical trajectory analysis and forward-looking uptake assumptions for clinical nutrition validation, supercritical CO2 extraction technology maturation, and practitioner channel expansion. Industry-specific forecast inputs incorporated EFSA health claim substantiation timelines and German functional food processor adoption curves for omega-enriched aging-population nutrition.
Underlying assumptions cover regulatory approval continuity, seed supply stability from proprietary cultivation networks, and marine omega price compression persistence, with deviation risk concentrated in REACH documentation burden escalation and pharmaceutical-grade validation timeline extension. Practitioners should keep alternative scenarios live as EFSA polyunsaturated fatty acid health claim rulings and FDA medical nutrition policy evolution reshape market access conditions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
North America Soy Protein Market
Ingredients
Tapioca Pearls Market
Ingredients
Europe Feed Yeast Market
Ingredients
Corn Steep Liquor Market
Ingredients
Asia Pacific Feed Yeast Market
Ingredients
Vitex Agnus Castus Extract Market
Ingredients
China Cane Sugar Market
Ingredients
Specialty Malt Market
Ingredients
Anti-Aging Ingredients Market
Ingredients
Africa Sodium Reduction Ingredients Market
Ingredients
Cocoa Fiber Market
Ingredients
Bran Market
Ingredients
Gluten-Free Flour Market
Ingredients
MCT Oil Market
Ingredients
Lupin Flour Market
Ingredients
Home Baking Ingredients Market