
 Asia Pacific Feed Yeast Market | 2026-2036
Asia Pacific Feed Yeast Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Feed Yeast Market Outlook
Project finance for industrial fermentation capacity is reconfiguring competitive entry barriers across the Asia Pacific Feed Yeast Market. Angel Yeast Co., Ltd. leverages captive molasses supply chains to anchor cost positions in China's interior provinces. Lallemand Inc. competes through specialized thermotolerant strains engineered for tropical ruminant applications. Lesaffre sustains technical service density across Indonesian poultry operations through decentralized blending facilities.
Feed yeast comprises dried or processed biomass of Saccharomyces cerevisiae and related species, typically containing 40-55% crude protein with B-vitamin complexes and beta-glucan cell wall fractions, manufactured through aerobic fermentation on molasses or grain-based substrates for use as a functional protein and gut-modulating additive in animal diets. Live yeast dominates ruminant applications for rumen pH stabilization, while yeast derivatives capture accelerating share in aquaculture as immunostimulant replacements for antibiotic growth promoters. Powder form leads volume across smallholder channels, though liquid formulations gain traction in automated feed mill systems.
China's SAMR enforces GB standards on yeast product labeling and heavy metal limits, while India's FSSAI mandates feed additive registration with substrate origin disclosure. Thailand's Department of Livestock Development aligns import protocols with ASEAN harmonized standards for microbial feed ingredients. Stakeholders must monitor regulatory divergence on genetically modified yeast strains and novel fermentation substrates as regional trade integration deepens.
Market Dynamics
Fermentation substrate traceability mandates across China and India are compressing supply chain flexibility and forcing integrators to requalify yeast suppliers against origin-disclosure protocols.
Growth Catalysts
- Vietnam's Mekong Delta aquaculture belt:Shrimp farmers are substituting fishmeal with autolyzed yeast derivatives as immunostimulants, creating concentrated demand pull for yeast processors with aquaculture-formulation capabilities.
- China's GB standards tightening:SAMR enforcement of heavy metal limits and labeling requirements is accelerating consolidation toward certified domestic producers with captive molasses supply chains.
- Probiotic yeast programs:Poultry integrators across Southeast Asia are expanding live yeast inclusion in broiler diets for rumen pH stabilization and antibiotic growth promoter replacement.
Market Restraints
- Molasses price volatility:Sugar crop fluctuations in Thailand and India directly compress yeast production margins, particularly for non-integrated processors lacking long-term supply contracts.
- Substrate concentration risk:China's interior provinces dominate cane and beet molasses output, creating geographic supply vulnerability for regional formulators dependent on single-origin fermentation feedstock.
- Thermotolerant strain limitations:Tropical ruminant applications in Indonesia and Malaysia require specialized Saccharomyces cerevisiae variants with limited commercial availability outside proprietary breeding programs.
Strategic Opportunities
- India's FSSAI registration pathway:The mandated feed additive disclosure framework creates first-mover advantage for yeast suppliers with documented substrate traceability systems already operational.
- Automated feed mill liquid formulations:Powder-to-liquid conversion in Thailand's commercial poultry sector opens channel expansion for yeast processors with dosing-equipment partnerships.
- Yeast derivatives in antibiotic-free aquaculture:Beta-glucan cell wall fractions are capturing share as immunostimulant replacements in Vietnam and Indonesia shrimp operations ahead of ASEAN harmonized standards.
Industry Challenges
- Fermentation technologist scarcity:Industrial-scale aerobic yeast production requires specialized process engineers in short supply across Southeast Asian manufacturing hubs.
- Dual certification timelines:Thailand's Department of Livestock Development alignment with ASEAN microbial feed standards creates parallel compliance burdens for exporters serving multiple member states.
- Legacy feed mill integration:Smallholder-channel powder formulations resist liquid-system retrofitting, constraining adoption of automated dosing technologies in Vietnam and Philippines backyard operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Feed Yeast Market |
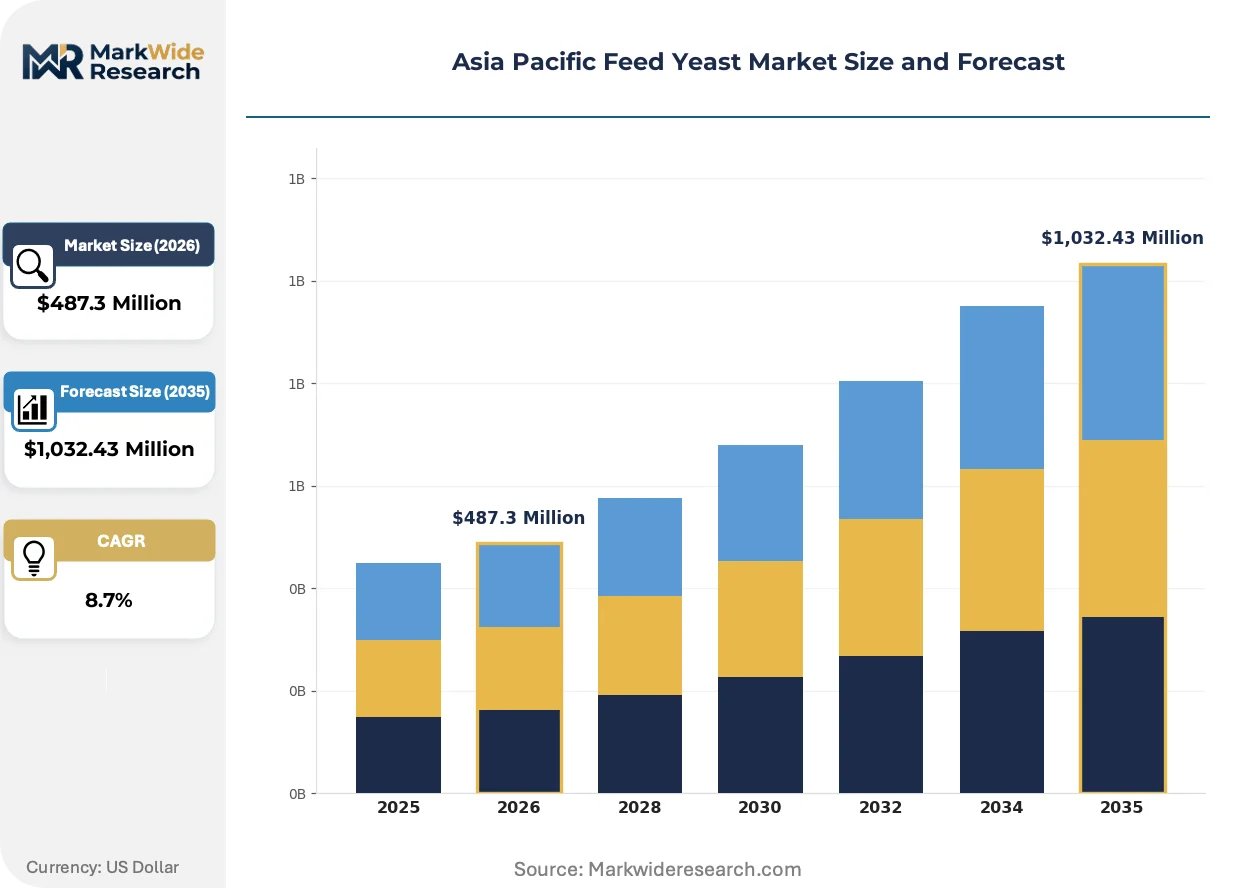
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Live Yeast, Dead Yeast, Yeast Extract, Yeast Derivatives Application: Poultry, Ruminants, Swine, Aquaculture Form: Powder, Liquid, Granules, Pellets End User: Farmers, Feed Manufacturers, Livestock Producers, Aquaculture Operators |
| Companies Covered | Alltech Inc., Associated British Foods plc, Angel Yeast Co., Ltd., DSM, Chr. Hansen, Lesaffre, Cargill, Leiber GmbH, Lallemand Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Feed Yeast Market Strategic Shifts
Bioprocessing automation and regulatory disclosure requirements are converging to reshape yeast manufacturing economics and customer qualification protocols across Asia Pacific feed additive channels.
Solid-state fermentation systems for yeast derivative production are migrating from batch to continuous processing architectures. Indonesian and Vietnamese aquafeed compounders are adopting these systems to reduce autolysis-cycle variability. The technology shift is compressing capital recovery timelines for mid-scale processors while raising technical service barriers for equipment suppliers.
China's SAMR has implemented sequential lot-tracking requirements for yeast products under revised GB standards, mandating substrate origin documentation from fermentation through finished goods. This regulatory architecture is disqualifying traders without captive supply chains. Thai and Malaysian import protocols are converging toward this documentation density, forcing regional exporters to reconfigure quality management systems.
Shrimp farmers in Vietnam's Mekong Delta are consolidating procurement through cooperative buying groups rather than independent distributor relationships. These aggregators are negotiating direct supply contracts with yeast processors, disintermediating traditional feed additive traders. The channel restructuring is most visible in Bac Lieu and Ca Mau provinces, where farmer associations now specify immunostimulant yeast derivatives by beta-glucan concentration rather than brand designation.
Asia Pacific Feed Yeast Market Segmentation
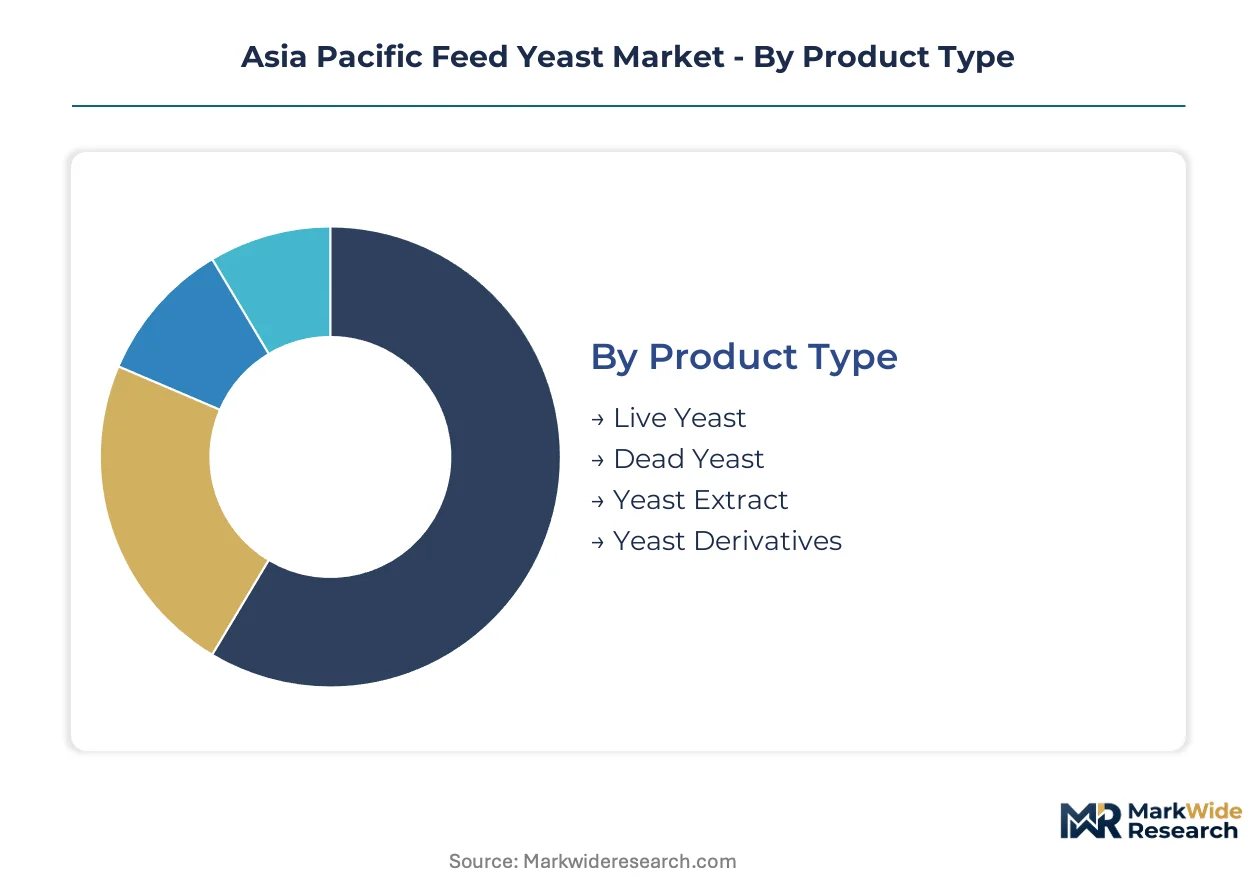
Feed yeast segmentation in Asia Pacific reflects divergent technical requirements across livestock species and supply chain tiers. Product functionality, application environment, and end-user scale each create distinct purchasing criteria that reshape supplier positioning.
Product Type:
Functional differentiation in yeast biomass processing creates four distinct cost-performance tiers for feed compounders.
- Live Yeast:Viable Saccharomyces cerevisiae cultures maintain metabolic activity in rumen environments, delivering pH stabilization through lactic acid consumption. Demand concentrates in Indonesian and Malaysian dairy operations where heat stress compromises rumen function, with procurement shifting toward thermotolerant strain suppliers.
- Yeast Derivatives:Cell wall fractions rich in beta-glucans and mannan-oligosaccharides function as immunostimulants without live-cell handling complexity. Vietnam's Mekong Delta shrimp farmers are substituting these for antibiotic growth promoters, creating concentrated demand pull for processors with autolysis capabilities.
- Dead Yeast:Heat-inactivated biomass provides protein and B-vitamin supplementation without probiotic functionality, serving price-sensitive poultry operations in Philippines backyard systems.
- Yeast Extract:Soluble hydrolysates with high nucleotide content support palatability in aquafeed and young animal diets, penetrating Thailand's commercial shrimp hatcheries.
Live yeast holds installed capacity in ruminant channels. Yeast derivatives is rotating up the share rankings through aquaculture immunostimulant substitution.
Application:
Species-specific digestive physiology and regulatory pressure create divergent formulation requirements across livestock categories.
- Aquaculture:Shrimp and finfish operations require immunostimulant yeast derivatives to replace banned antibiotic growth promoters under tightening ASEAN standards. Vietnam's Mekong Delta belt leads procurement volume, with farmer cooperatives in Bac Lieu specifying beta-glucan concentration thresholds directly with processors.
- Poultry:Broiler integrators across Southeast Asia deploy live yeast for gut health management in antibiotic-free programs, with Thailand's CP Group and Indonesia's Japfa Comfeed expanding inclusion rates in starter diets.
- Ruminants:Dairy and beef operations in tropical climates utilize thermotolerant strains for rumen pH buffering, constrained by limited commercial availability outside proprietary breeding programs.
- Swine:Post-weaning diarrhea control drives yeast derivative inclusion in nursery diets, with Chinese commercial farms leading formulation sophistication under GB standards compliance pressure.
Poultry commands current volume leadership. Aquaculture is climbing the fastest through shrimp sector immunostimulant conversion.
Form:
Physical presentation determines compatibility with feed mill infrastructure and smallholder distribution economics.
- Powder:Dried fine-ground biomass dominates smallholder channels across Vietnam and Philippines backyard operations, compatible with manual mixing and resistant to liquid-system retrofitting constraints.
- Liquid:Suspension formulations enable automated dosing in Thailand's integrated poultry feed mills, requiring equipment partnerships that raise technical service barriers for yeast suppliers.
- Granules:Agglomerated particles reduce dust handling in Indonesian decentralized blending facilities, supporting Lesaffre's technical service density model.
- Pellets:Compressed forms with enhanced flowability serve aquafeed extrusion processes in Vietnam and Indonesia, though thermal processing risks partial activity loss in live yeast variants.
Powder retains channel breadth. Liquid is gaining share through Thailand feed mill automation.
End User:
Customer scale and technical capability create distinct procurement patterns from cooperative buying to integrated manufacturing.
- Feed Manufacturers:Commercial compounders in Thailand and Indonesia require documented substrate traceability under tightening GB and FSSAI alignment pressures, disqualifying traders without captive supply chains.
- Aquaculture Operators:Mekong Delta shrimp farmer cooperatives in Ca Mau and Bac Lieu provinces negotiate direct yeast derivative contracts, disintermediating traditional feed additive distributors through aggregated procurement.
- Farmers:Smallholder poultry and swine producers across Philippines and Vietnam rely on distributor networks for powder formulations, constrained by legacy infrastructure resisting liquid conversion.
- Livestock Producers:Integrated poultry and dairy operations in Malaysia and China specify strain performance metrics directly with yeast processors, leveraging volume for technical service access.
Feed manufacturers hold formulation control. Aquaculture operators is rotating up the share rankings through cooperative consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Asia Pacific feed yeast trade flows reveal pronounced import dependency in Southeast Asian markets against China's dominant export capacity. Molasses substrate availability and fermentation infrastructure concentration create divergent supply security profiles across the region.
China
Angel Yeast Co., Ltd. leverages captive molasses supply chains from interior cane and beet processing zones to anchor cost positions. SAMR enforces GB standards on heavy metal limits and substrate origin documentation. Yangtze River Delta fermentation clusters supply processed yeast derivatives to Vietnam and Thailand aquafeed compounders.
Vietnam
Shrimp farmers in the Mekong Delta belt substitute fishmeal with autolyzed yeast derivatives as immunostimulants, generating concentrated demand pull. The Ministry of Agriculture and Rural Development aligns import protocols with ASEAN microbial feed standards. Bac Lieu and Ca Mau provinces host farmer cooperatives negotiating direct supply contracts with regional processors.
India
Poultry integrators expand probiotic yeast inclusion in broiler diets for antibiotic growth promoter replacement. FSSAI mandates feed additive registration with substrate origin disclosure requirements. Maharashtra and Gujarat house decentralized blending facilities serving smallholder distribution networks.
Indonesia
Tropical dairy operations deploy thermotolerant yeast strains for rumen pH buffering under heat stress conditions. The Ministry of Agriculture regulates microbial feed ingredient imports through veterinary certification pathways. Java-based poultry operations drive live yeast procurement through integrated feed mill channels.
Thailand
Commercial poultry feed mills automate liquid yeast dosing systems, displacing powder formulations in integrated operations. The Department of Livestock Development harmonizes import protocols with ASEAN standards for microbial ingredients. Central Plains feed manufacturing clusters require documented substrate traceability from yeast suppliers.
Asia Pacific Feed Yeast Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with strain development and substrate control capabilities. Market structure tilts toward consolidation as GB and FSSAI traceability mandates disqualify trader intermediaries without captive supply chains. Three archetypes dominate: integrated fermenters with molasses backward integration, specialized strain developers with thermotolerant breeding programs, and technical service deployers with decentralized blending networks. Capacity expansion and substrate supply security represent the dominant competitive vectors.
Among Asia-Pacific headquartered fermenters, Angel Yeast Co., Ltd. exemplifies integrated substrate control, while Lallemand Inc. and Lesaffre occupy positions emphasizing specialized strain portfolios and technical service density respectively. These anchors illustrate how regulatory disclosure requirements favor players with documented supply chain architectures over trading intermediaries.
| Leading Market Players |
|---|
| Alltech Inc. |
| Associated British Foods plc |
| Angel Yeast Co., Ltd. |
| DSM |
| Chr. Hansen |
| Lesaffre |
| Cargill |
| Leiber GmbH |
| Lallemand Inc. |
| Others |
Value Chain & Pricing Dynamics
China's interior molasses belt concentrates substrate supply for yeast fermentation, anchoring margin pools with integrated processors possessing captive cane and beet processing networks while forcing non-integrated formulators into price-taking positions.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-tiered discounts. Price differentiation hinges on certification grade under SAMR GB standards and captive molasses integration. Cost compression in standard-grade live yeast is intensifying because trader intermediaries face disqualification under origin-disclosure mandates. Smallholder poultry operations in Philippines backyard channels exhibit highest price sensitivity; integrated Thai poultry feed mills show lowest.
Supply Chain Analysis
Molasses feedstock draws from China's interior provinces, Thailand's central cane belt, and India's Maharashtra-Gujarat sugar zones. Saccharomyces cerevisiae seed cultures and autolysis processing equipment constitute critical component dependencies. Single-source vulnerability concentrates in molasses supply contracts lacking multi-origin hedging. Distribution runs through decentralized blending facilities serving Indonesian poultry integrators and direct-procurement cooperatives in Vietnam's Mekong Delta.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial-scale aerobic fermentation expertise remains scarce across Southeast Asian manufacturing hubs, constraining capacity expansion and favoring players with documented process engineering pipelines.
For Market Incumbents: Insulate margin positions by deepening backward integration into molasses supply chains and accelerating FSSAI registration documentation ahead of India's substrate disclosure deadlines. Thermotolerant strain development represents the critical R&D lever against emerging competition from specialized breeding programs. For New Entrants and Emerging Players: Vietnam's Mekong Delta aquaculture belt offers the most penetrable white-space, where farmer cooperatives in Bac Lieu and Ca Mau provinces bypass traditional distributors for direct yeast derivative procurement. Automated liquid dosing partnerships with Thai feed mill operators provide the strongest go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional feed additive traders facing disqualification under tightening GB and FSSAI traceability mandates. Long-term viability centers on substrate control and strain IP over trading relationships. Monitor SAMR enforcement intensity on heavy metal limits as the inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Molasses Supply | Captive substrate control anchors cost positions against sugar crop volatility in Thailand and India. |
| Thermotolerant Strain Development | Specialized Saccharomyces cerevisiae variants unlock Indonesian and Malaysian tropical ruminant applications. |
| FSSAI Registration Acceleration | First-mover documentation advantage secures access to India's expanding probiotic yeast poultry programs. |
| Liquid Dosing Equipment Partnerships | Automated feed mill integration in Thailand displaces powder formulations through technical service barriers. |
| Direct Cooperative Supply Contracts | Bypassing distributors in Vietnam's Mekong Delta captures aggregated shrimp farmer procurement volume. |
Study Parameters
Initial hypotheses were tested against primary input from fermentation plant managers, poultry integrator procurement leads, aquafeed compounder technical directors, and regulatory affairs specialists at yeast processors, then refined through customs trade data, SAMR GB standard filings, FSSAI registration databases, and ASEAN microbial feed harmonization protocols. Bottom-up capacity assessments and top-down demand modeling were triangulated to validate volume estimates.
Demand-supply balance modeling across the projection horizon incorporated segmentation by product type, application species, physical form, and end-user scale. CAGRs were derived from installed fermentation capacity expansion schedules and species-specific inclusion rate trajectories. Molasses price volatility indices and regulatory enforcement timelines served as key forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive substrate acquisition moves by non-integrated processors would shift outcomes beyond modeled ranges. Cross-checking against ASEAN agricultural commodity trade flows and national sugar crop forecasts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Animal Protein Market
Ingredients
Cold Pressed Oil Market
Ingredients
Cold-Pressed Citrus Seed Oil Ingredients Market
Ingredients
Plant Based Premix Market
Ingredients
Yeast Autolysates Market
Ingredients
Sunflower Protein Market
Ingredients
North America and Europe Coconut Derivatives Market
Ingredients
Self-Rising Flour Market
Ingredients
Dill Seed Oil Market
Ingredients
North America Feed Yeast Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
India Starch and Starch Derivative Market
Ingredients
Non-PHO Ingredients Market
Ingredients
Pea Flour Market
Ingredients
2'-Fucosyllactose (2'-FL) Market