
 Whey Permeate Market | 2026-2036
Whey Permeate Market Size, Share, and Industry Trends Forecast 2026-2036
Whey Permeate Market Insights
European whey processing capacity is shifting toward higher-value permeate fractions as energy costs reshape dryer's economics. Arla Foods Ingredients leverages its Danish cooperative network to sustain consistent permeate supply across Northern Europe. LACTALIS Ingredients anchors its position through backward integration into cheese-making streams that feed permeate extraction. Milk Specialties Global competes on manufacturing scale, operating multiple drying facilities that convert liquid permeate into shelf-stable powder.
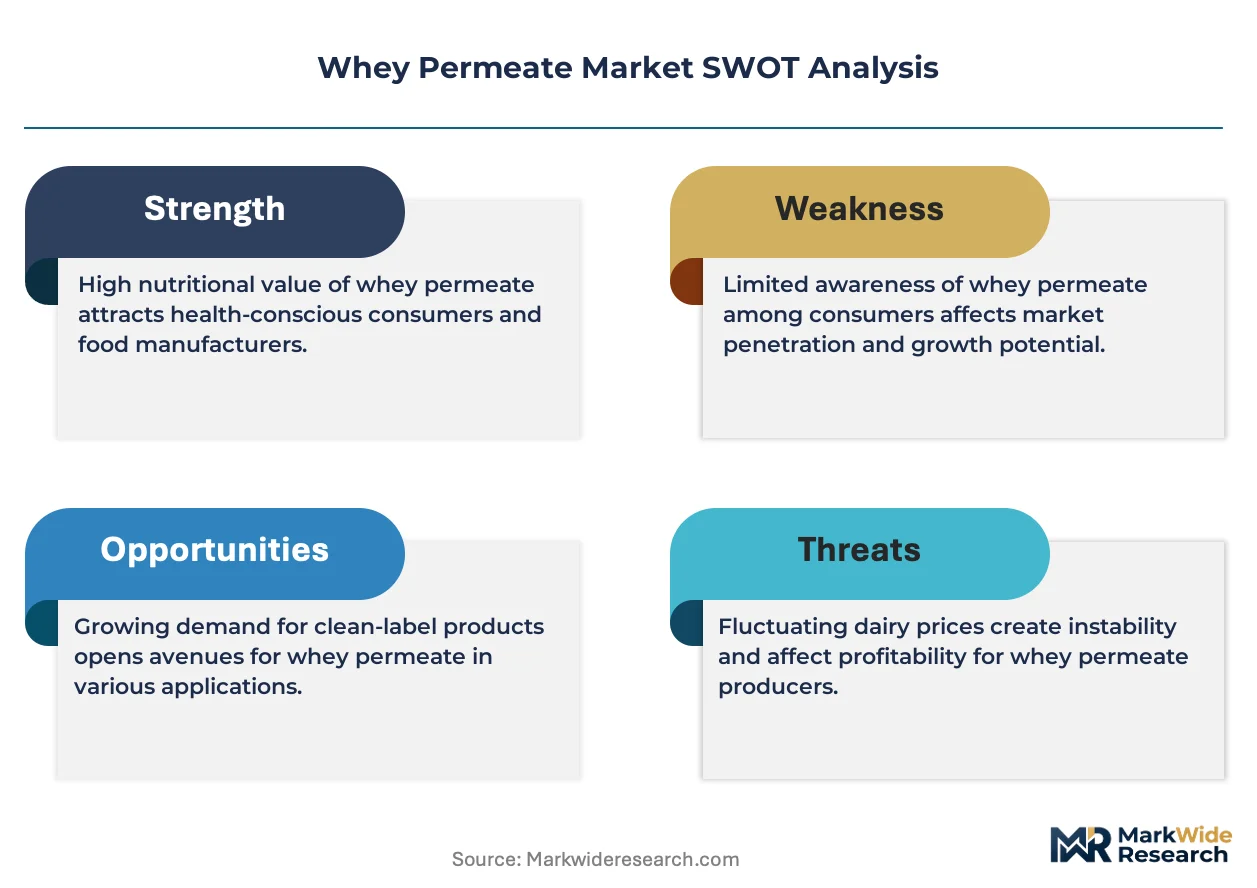
Whey permeate is the lactose-rich, protein-depleted liquid remaining after ultrafiltration separates whey protein concentrates from whole whey, typically containing 75-85% lactose on a dry basis alongside minerals and trace nitrogenous compounds. Food and feed manufacturers value it as a cost-effective carbohydrate source, dairy solids extender, and browning agent in baked applications. Powder dominates product type revenue due to superior logistics economics and year-round formulation flexibility for animal nutrition buyers. Bakery end use is expanding fastest as clean-label demands push manufacturers toward permeate-derived Maillard browning instead of synthetic caramel colorants.
FDA oversees whey permeate as a GRAS substance in human food while USDA's FSIS monitors its inclusion in meat product binders. The EU F-Gas Regulation indirectly shapes processing economics by restricting refrigerants used in lactose crystallization and spray drying operations. REACH compliance requirements for imported dairy ingredients create documentation burdens for non-European suppliers seeking market access. Stakeholders must monitor how evolving carbon border adjustments and feed-to-food traceability mandates reshape sourcing strategies across the value chain.
Market Dynamics
Energy-intensive spray drying economics are forcing whey processors to consolidate capacity around lactose crystallization hubs that can arbitrage regional electricity price spreads. This structural concentration is reshaping procurement relationships between permeate buyers and dairy cooperative networks.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandates tighter circular economy utilization of dairy byproducts, compelling compound feed formulators to standardize protein content with whey permeate fractions.
- Precision livestock farming adoption:Calf milk replacer manufacturers in Denmark and the Netherlands are specifying permeate-derived lactose for osmolality control in automated feeding systems.
- Bakery sector clean-label reformulation:Maillard browning requirements are displacing synthetic caramel colorants with permeate solids in artisan and industrial bread production.
Market Restraints
- Natural gas price volatility:Spray drying operations consume substantial thermal energy, exposing processors to input cost swings that compress margin buffers on standard-grade permeate powder.
- Supply concentration in Northern European dairy belts:Denmark, northern Germany, and the Netherlands dominate liquid whey availability, creating geographic single-source risk for buyers outside these catchment areas.
- Substitution by dextrose and maltodextrin:Cost-sensitive animal nutrition buyers in Eastern European markets can switch to plant-based carbohydrate sources when permeate logistics premiums widen.
Strategic Opportunities
- Underpenetrated Southeast Asian feed markets:Vietnam and Indonesia aquaculture sectors lack established permeate supply chains, presenting first-mover positioning for processors with ocean freight capabilities.
- EU F-Gas Regulation compliance services:Refrigerant transition requirements for lactose crystallization create advisory and retrofit revenue streams for equipment-integrated ingredient suppliers.
- Direct-to-bakery distribution platforms:Specialty ingredient e-procurement channels are bypassing traditional distributor markups for mid-sized European artisan bakeries.
Industry Challenges
- REACH documentation burdens:Non-European suppliers face extended compliance timelines for imported dairy ingredient registrations, delaying market entry by quarters.
- Feed-to-food traceability system integration:Compound feed manufacturers must retrofit legacy ERP systems to capture permeate lot genealogy for EU Green Deal audit requirements.
- Spray dryer operator skill scarcity:Specialized knowledge of lactose glass transition temperatures and caking prevention commands wage premiums that inflate fixed production costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Whey Permeate Market |
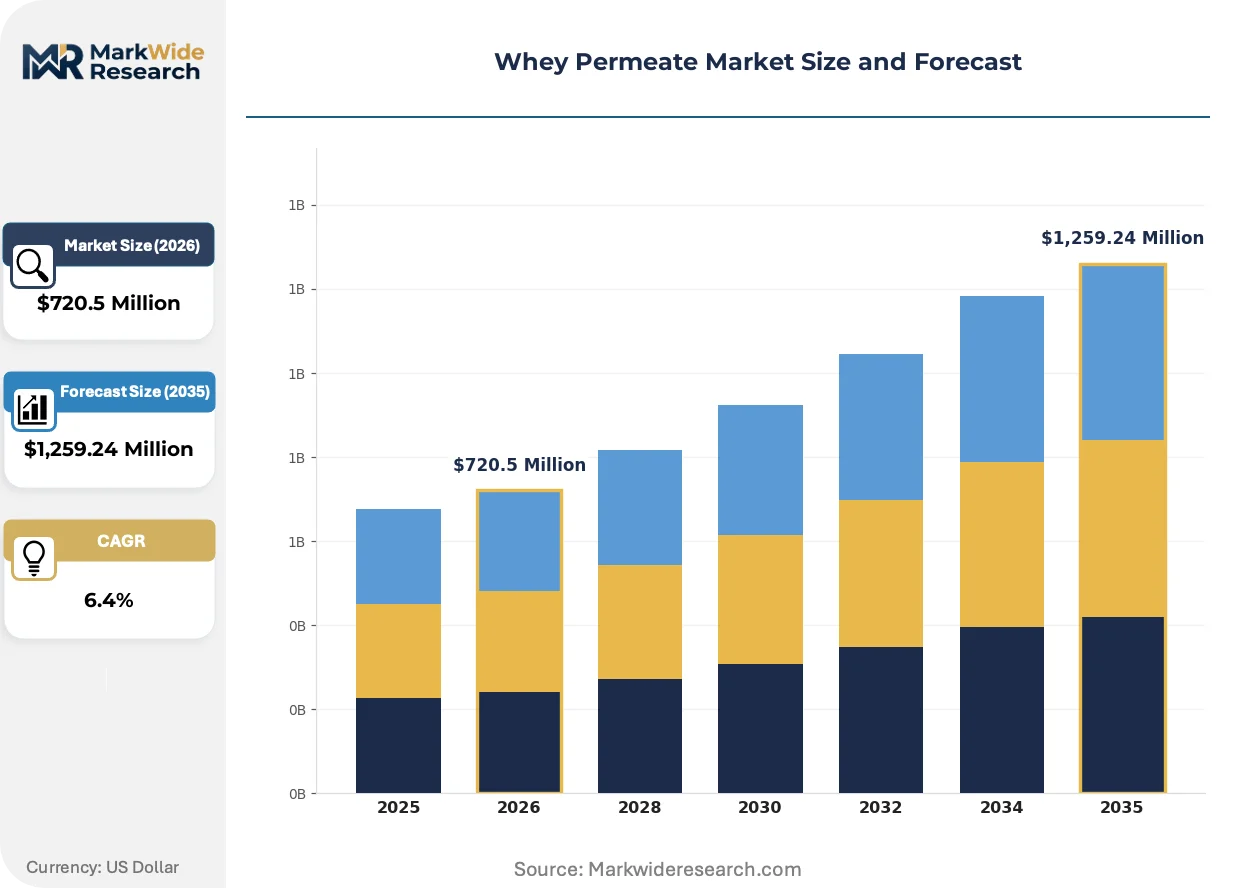
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $1,259.24 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrate, Powder, Liquid, Granules End Use Industry: Dairy Products, Bakery, Confectionery, Animal Feed Packaging Type: Bulk Bags, Cartons, Drums, Sachets Distribution Channel: Online, Wholesalers, Retailers, Direct Sales |
| Companies Covered | Idaho Milk Products, Arion Dairy Products, Arla Foods Ingredients, Proliant Dairy, Havero Hoogwegt, LACTALIS Ingredients, Milk Specialties Global, Armor Proteines, Agropur Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Whey Permeate Market Trends and Innovations
Membrane filtration advances and regulatory carbon accounting are converging to redefine how whey permeate is fractionated, positioned, and procured across food and feed value chains.
Integrated membrane systems combining nanofiltration with electrodialysis is unifying mineral removal and lactose concentration into single-pass operations. Dairy processors in the Netherlands are retrofitting existing ultrafiltration lines with this configuration to reduce thermal drying loads. The technology is compressing capital requirements for permeate fractionation by eliminating intermediate crystallization stages.
REACH registration deadlines for imported dairy ingredients are tightening documentation standards for non-European suppliers. The regulation requires full substance characterization and safety data sheet harmonization before customs release. Chinese and Argentine permeate exporters are responding by establishing EU-based toll processing partnerships to circumvent direct registration liability.
Bakery procurement teams are consolidating supplier panels around dual-source permeate contracts with fixed-price lactose equivalency clauses. This behavior is displacing spot-market purchasing for Maillard browning applications in industrial bread production. German and French industrial bakeries are most visible in this shift, driven by margin protection needs against dairy commodity volatility.
Whey Permeate Market Segmentation
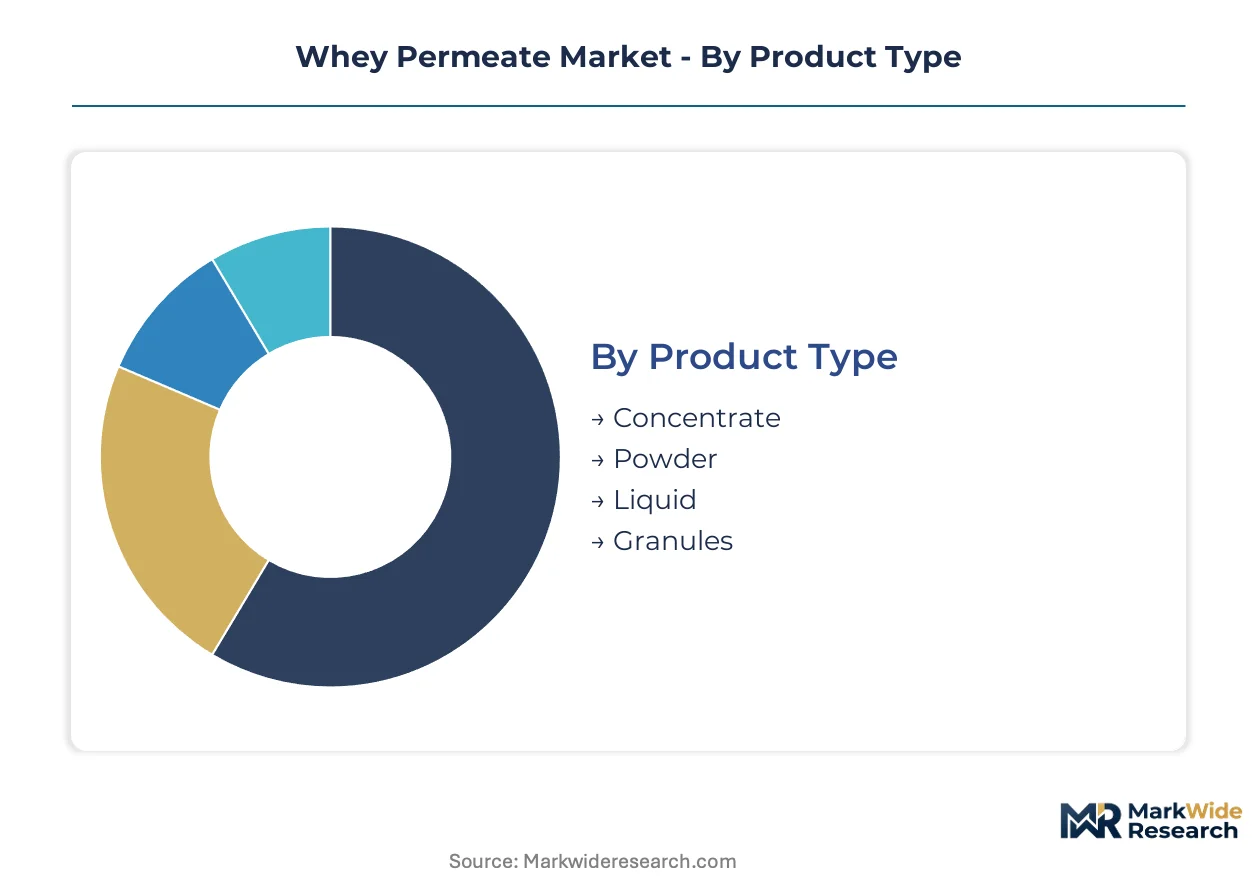
Whey permeate segmentation reveals how physical form, end-use application, and logistics configuration determine value capture across dairy byproduct value chains. Product type and packaging choices directly shape energy exposure and shelf stability economics for buyers and processors alike.
Product Type:
Spray dryer capacity concentration in Denmark, northern Germany, and the Netherlands dictates which permeate formats achieve cost-competitive supply.
- Powder:Spray-dried permeate with 75-85% lactose content on a dry basis dominates commercial volumes due to superior logistics economics and year-round formulation flexibility. Animal feed manufacturers in Germany source powder for protein standardization in calf milk replacers, though natural gas price volatility compresses processor margins on standard-grade production.
- Liquid:Unconcentrated permeate straight from ultrafiltration lines offers the lowest unit cost for buyers within 200 kilometers of dairy processing clusters. Dutch compound feed formulators with proximity to cheese-making cooperatives leverage liquid permeate for osmolality control in precision livestock feeding systems, constrained by spoilage risk beyond short-haul distribution radii.
- Concentrate:Partially dewatered liquid permeate reduces transport costs for mid-distance procurement.
- Granules:Agglomerated powder variants improve flowability for automated bakery dosing equipment.
Today's leader: Powder. Tomorrow's challenger: Liquid.
End Use Industry:
Application-driven demand splits between feed formulation scale and food manufacturing margin protection.
- Animal Feed:Calf milk replacer manufacturers and precision livestock operations in Denmark and the Netherlands specify permeate-derived lactose for osmolarity management in automated feeding systems. The EU Green Deal's Farm to Fork Strategy tightens dairy byproduct utilization standards, compelling compound feed producers to document permeate inclusion for circular economy compliance.
- Bakery:Artisan and industrial bread producers deploy permeate solids for Maillard browning as clean-label reformulation displaces synthetic caramel colorants. German and French industrial bakeries are consolidating supplier panels around fixed-price lactose equivalency contracts to hedge dairy commodity volatility.
- Dairy Products:Permeate extends dairy solids in processed cheese and standardizes protein in recombined milk.
- Confectionery:Lactose crystallization properties support browning and texture modification in caramel applications.
Animal Feed commands current volume. Bakery claims the steepest expansion trajectory.
Packaging Type:
Handling efficiency and contamination risk shape packaging selection across feed and food grade specifications.
- Bulk Bags:One-ton flexible intermediate bulk containers dominate powder permeate shipments to compound feed mills, minimizing per-kilogram handling costs for high-volume animal nutrition buyers.
- Drums:Steel or fiber drums serve liquid and concentrate formats for food manufacturers requiring sealed containment and lot traceability.
- Cartons:Multi-wall paperboard suits smaller bakery and confectionery procurement lots.
- Sachets:Pre-weighed small format targets artisan bakery trial quantities and R&D sampling.
Bulk Bags anchor feed sector procurement. Drums defend food safety premiums.
Distribution Channel:
Channel structure reflects buyer scale sophistication and geographic distance from Northern European production belts.
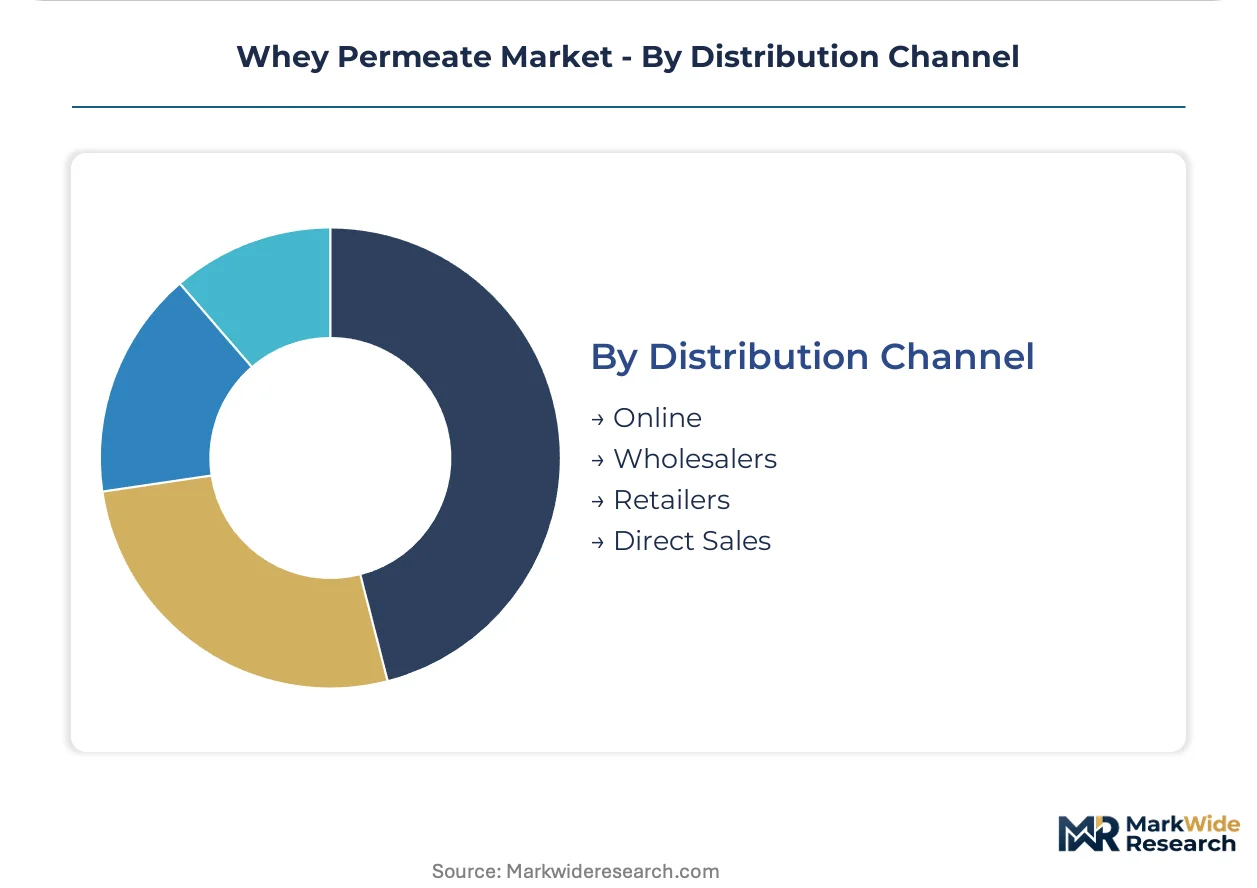
- Direct Sales:Large compound feed manufacturers and industrial bakeries negotiate directly with Arla Foods Ingredients and LACTALIS Ingredients for contracted volumes, bypassing distributor markups. These relationships concentrate procurement power among buyers with sufficient scale to justify dedicated logistics arrangements.
- Wholesalers:Regional dairy ingredient distributors aggregate permeate lots from multiple processors for mid-sized feed mills and bakeries lacking direct supplier access.
- Online:Specialty ingredient e-procurement platforms are emerging for European artisan bakeries seeking smaller lot sizes with transparent pricing.
- Retailers:Limited presence in niche foodservice and small-scale agricultural supply contexts.
Direct Sales secures volume concentration. Online gains traction among fragmented buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping whey permeate production geography as energy costs and environmental compliance burdens diverge across jurisdictions. Processors migrate capacity toward jurisdictions with subsidized renewable electricity and streamlined dairy byproduct handling permits.
Germany
Compound feed manufacturers in Lower Saxony and Bavaria drive permeate procurement for calf milk replacer protein standardization. The EU Green Deal's Farm to Fork Strategy mandates circular economy documentation for dairy byproduct utilization, compelling feed mills to upgrade traceability systems. The Münsterland dairy cluster anchors spray-drying capacity serving domestic and Benelux buyers.
Netherlands
Precision livestock farming adoption concentrates demand for permeate-derived lactose in automated calf-feeding systems across Friesland and Gelderland. The EU F-Gas Regulation restricts refrigerants used in lactose crystallization, prompting processors to retrofit equipment. The Noord-Holland cheese-making corridor feeds ultrafiltration lines that supply liquid permeate to nearby feed formulators.
Denmark
Cooperative dairy networks sustain consistent permeate supply for Northern European animal nutrition buyers. REACH compliance requirements for imported ingredients create documentation advantages for domestic processors over non-European competitors. The Jutland Peninsula hosts membrane filtration facilities integrated with Arla Foods Ingredients' cooperative supply base.
United States
FDA GRAS designation for whey permeate in human food underpins bakery sector clean-label reformulation demand. Natural gas price volatility exposes spray-drying operations to margin compression, favoring processors with captive energy supply. Idaho's Magic Valley dairy belt concentrates production capacity serving West Coast feed and food manufacturers.
France
Industrial bakeries in Île-de-France and Hauts-de-France deploy permeate solids for Maillard browning as synthetic caramel colorant replacement. ANSM and DGCCRF monitor food safety compliance for dairy ingredient applications. The Brittany dairy processing zone supplies liquid permeate to regional compound feed mills under short-haul distribution economics.
Whey Permeate Market Competitive Landscape
European producers anchor the premium-tier supply base; North American operators hold scale-driven positions in powder exports. Market structure concentrates around dairy cooperative networks with backward integration into cheese-making streams and independent processors competing on drying capacity utilization. Three archetypes dominate: cooperative-affiliated ingredient divisions, private-label toll processors, and multinational dairy conglomerates with captive permeate extraction. Competitive moves center on membrane filtration technology licensing and geographic expansion into underpenetrated Asian feed markets.
Within the cooperative-affiliated tier, Arla Foods Ingredients and LACTALIS Ingredients exemplify players leveraging dairy cooperative networks for feedstock security. Milk Specialties Global occupies a position among scale-focused processors operating multiple drying facilities. These three entities represent distinct strategic postures: cooperative-backed supply assurance, multinational dairy integration, and manufacturing-scale competition.
| Leading Market Players |
|---|
| Idaho Milk Products |
| Arion Dairy Products |
| Arla Foods Ingredients |
| Proliant Dairy |
| Havero Hoogwegt |
| LACTALIS Ingredients |
| Milk Specialties Global |
| Armor Proteines |
| Agropur Ingredients |
| Others |
Pricing and Supply Chain Analysis
The EU Green Deal's Farm to Fork Strategy gates qualified supply and premium-tier pricing access by mandating circular economy documentation for dairy byproduct utilization. Feed manufacturers sourcing permeate for calf milk replacers must demonstrate traceability compliance, creating a bifurcated market where certified supply commands structural premiums over uncertified alternatives.
Pricing Analysis
Distributor margins compress pricing power for mid-sized compound feed mills lacking direct processor relationships. Three-tier pricing structure across premium, standard, and economy levels separates EU-certified permeate with full Farm to Fork documentation from standard-grade powder and uncertified liquid alternatives. Cost compression in standard-grade powder is intensifying because natural gas price volatility exposes spray-drying operations to margin erosion. Animal nutrition buyers in Eastern European markets exhibit highest price sensitivity, switching to dextrose substitutes when logistics premiums widen.
Supply Chain Analysis
Regional distribution centers in Denmark, northern Germany, and the Netherlands anchor hub-and-spoke patterns for Northern European feed and food manufacturers. Supply draws from cooperative cheese-making corridors in the Netherlands and Denmark, with secondary sourcing from Germany's Münsterland cluster. Single-source vulnerability concentrates in Jutland Peninsula membrane filtration facilities serving Arla Foods Ingredients' network. Distribution runs through bulk bag shipments to compound feed mills and drum-format deliveries to food manufacturers requiring sealed containment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Whey permeate offers margin-expansion potential as energy cost pressures force consolidation around lactose crystallization hubs with subsidized renewable electricity access.
For Market Incumbents: Anticipate substitution pressure from plant-based carbohydrate sources in Eastern European feed markets by deepening backward integration into cheese-making cooperatives. Lock in calf milk replacer contracts with fixed-price lactose equivalency clauses before dextrose price volatility narrows the permeate premium. Prioritize EU F-Gas Regulation compliance investments to defend positioning in Dutch precision livestock feeding systems. For New Entrants and Emerging Players: Mid-sized European artisan bakeries represent an underserved buyer archetype seeking transparent e-procurement channels for Maillard browning applications. Southeast Asian aquaculture feed formulators in Vietnam and Indonesia lack established permeate supply chains, presenting first-mover positioning for processors with ocean freight capabilities. Deploy specialty ingredient platform partnerships to bypass traditional distributor markups in fragmented bakery procurement. For Investors and Strategic Acquirers: Roll-up economics work for regional toll processors because spray dryer capacity scarcity in Northern Europe creates pricing power for consolidated platforms with lactose crystallization capabilities. Target membrane filtration facilities with existing ultrafiltration retrofits and cooperative supply agreements. Watch for EU carbon border adjustment implementation as inflection indicator for import-competitive processing capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cheese-Making Cooperatives | Arla Foods Ingredients leverages Danish cooperative networks to secure consistent liquid whey feedstock for permeate extraction. |
| Membrane Filtration Retrofit Investment | Dutch processors combining nanofiltration with electrodialysis reduce thermal drying loads and capital requirements. |
| EU F-Gas Regulation Compliance Services | Equipment-integrated suppliers capture advisory revenue from refrigerant transition requirements in lactose crystallization. |
| Direct-to-Bakery E-Procurement Platform Launch | Specialty ingredient channels bypass distributor markups for German and French industrial bakeries hedging commodity volatility. |
| Southeast Asian Feed Market Entry | First-mover processors with ocean freight capabilities target Vietnam and Indonesia aquaculture sectors lacking established supply chains. |
Research Methodology
Direct dialogue with dairy cooperative procurement managers, compound feed formulation scientists, bakery R&D directors, and membrane filtration equipment engineers grounded qualitative findings. Secondary validation drew from EU F-Gas Regulation implementation reports, REACH registration databases for imported dairy ingredients, and customs trade data on whey derivative flows. Bottom-up volume modeling triangulated against top-down dairy processing capacity assessments across the analysis window.
Segmented outputs across product type, end-use industry, packaging configuration, and distribution channel dimensions informed the projection framework. CAGRs derived from historical dairy byproduct utilization trends, energy cost elasticity assumptions for spray-drying operations, and regulatory compliance timeline modeling. Forecast inputs incorporated EU Green Deal Farm to Fork traceability mandate adoption curves and precision livestock farming penetration rates in Denmark and the Netherlands.
Underlying measurement precision varies by segment; powder format and animal feed end-use carry tighter precision than liquid concentrate and emerging bakery applications due to established trade flow documentation. Forecasts reflect documented assumptions on energy price trajectories and regulatory enforcement intensity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Camelina Oil Market
Ingredients
Vegan Baking Ingredients Market
Ingredients
Microbial Food Ingredients Market
Ingredients
Cocoa Solids Market
Ingredients
Mulberry Leaf Extract Market
Ingredients
Edible Oils and Fats Market
Ingredients
Asia-Pacific Gelatin Market
Ingredients
Fucoidan Extract Market
Ingredients
Lime Seed Oils Market
Ingredients
France Soy Protein Market
Ingredients
South America Plant Protein Ingredients Market
Ingredients
Global Cocoa Products Market
Ingredients
Organic Starch Market
Ingredients
Cooking Coconut Milk Market
Ingredients
North America Phytosterols Market
Ingredients
Terminalia Extract Market