
 Carotenoids Market | 2026-2036
Carotenoids Market Size, Share, and Industry Trends Forecast 2026-2036
Carotenoids Market Analysis
Pharmaceutical-grade carotenoid specifications is bifurcating the competitive landscape into premium validated supply and commodity-grade volume channels. BASF SE leverages its integrated petrochemical feedstock position to sustain synthetic beta-carotene cost structures. DSM-Firmenich AG anchors its portfolio on fermentation-derived astaxanthin for aquaculture and human nutrition. Kemin Industries differentiates through lutein and zeaxanthin extraction from marigold oleoresin, occupying the eye health segment with clinically substantiated formulations.
Carotenoids comprise a class of lipid-soluble terpenoid pigments—typically C40 tetraterpenoids synthesized via the mevalonate or methylerythritol phosphate pathways—characterized by conjugated polyene chains that confer antioxidant activity, provitamin A conversion potential, and colorant properties. Industrial production employs chemical synthesis, solvent extraction from plant biomass, or microbial fermentation with engineered strains such as Blakeslea trispora or Haematococcus pluvialis. Natural-source astaxanthin from algal cultivation commands premium positioning in dietary supplements and cosmetics, while synthetic beta-carotene dominates food coloring and animal feed volumes due to cost scalability. Powder formulations lead across feed and supplement applications, though emulsion and liquid forms are gaining share in beverage fortification where dispersibility determines functionality.
Food and drug regulators in the United States, the European Union, and China enforce divergent purity and labeling standards that fragment market access requirements. FDA GRAS self-affirmation governs US ingredient entry, while EFSA Novel Food authorizations and China's NMPA blue-hat registration impose extended qualification timelines for new sources and claims. Japan's FOSHU system and Health Canada's NHPD further complicate multi-jurisdictional product strategies. Stakeholders must monitor evolving natural-source authentication protocols and synthetic-to-natural substitution thresholds as procurement policies in premium channels harden against petrochemical-derived inputs.
Market Dynamics
The European Union's Novel Food regulation is fragmenting ingredient qualification pathways, forcing suppliers to maintain parallel dossiers for synthetic and natural-source carotenoids while algal-origin certification requirements tighten procurement standards.
Growth Catalysts
- EFSA Novel Food authorization pathway:Fermentation-derived astaxanthin from Blakeslea trispora has secured expanded food additive approvals, unlocking human nutrition applications beyond aquaculture feed.
- China's traditional medicine crossover:Domestic fermentation capacity in Shandong and Jiangsu provinces is accelerating local procurement for lutein and zeaxanthin extracts positioned within TCM-derived supplement formulations.
- Marigold oleoresin extraction scale-up:Automated solvent recovery systems in Indian processing clusters are reducing lutein production costs for eye health supplement formulators.
Market Restraints
- Petrochemical feedstock dependency:Synthetic beta-carotene production remains tethered to benzene and acetone pricing volatility, compressing margin buffers for chemical synthesis operators.
- Haematococcus pluvialis cultivation concentration:Natural-source astaxanthin supply clusters in Hawaii and Israel expose premium channels to climate disruption and water access constraints.
- Provitamin A conversion threshold variability:Beta-carotene bioavailability differs significantly across population genetics, limiting standardized dosing claims in pharmaceutical applications.
Strategic Opportunities
- India's underpenetrated dietary supplement retail:Direct-to-consumer e-commerce platforms are bypassing traditional pharmacy distribution for lutein and zeaxanthin eye health formulations.
- CSRD supply chain disclosure mandates:Corporate sustainability reporting requirements are creating procurement preference for fermentation-derived carotenoids with verified carbon footprints over petrochemical alternatives.
- Beverage fortification emulsion technology:Cold-water dispersible astaxanthin nanoemulsions are opening functional drink applications previously blocked by lipid-solubility barriers.
Industry Challenges
- Multi-jurisdictional dossier management:FDA GRAS self-affirmation, EFSA Novel Food timelines, and NMPA blue-hat registration run on non-harmonized data requirements, straining regulatory affairs capacity.
- Algal authentication protocol gaps:Synthetic-to-natural substitution detection methods remain contested between mass spectrometry and carbon isotope approaches, complicating certification integrity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotenoids Market |
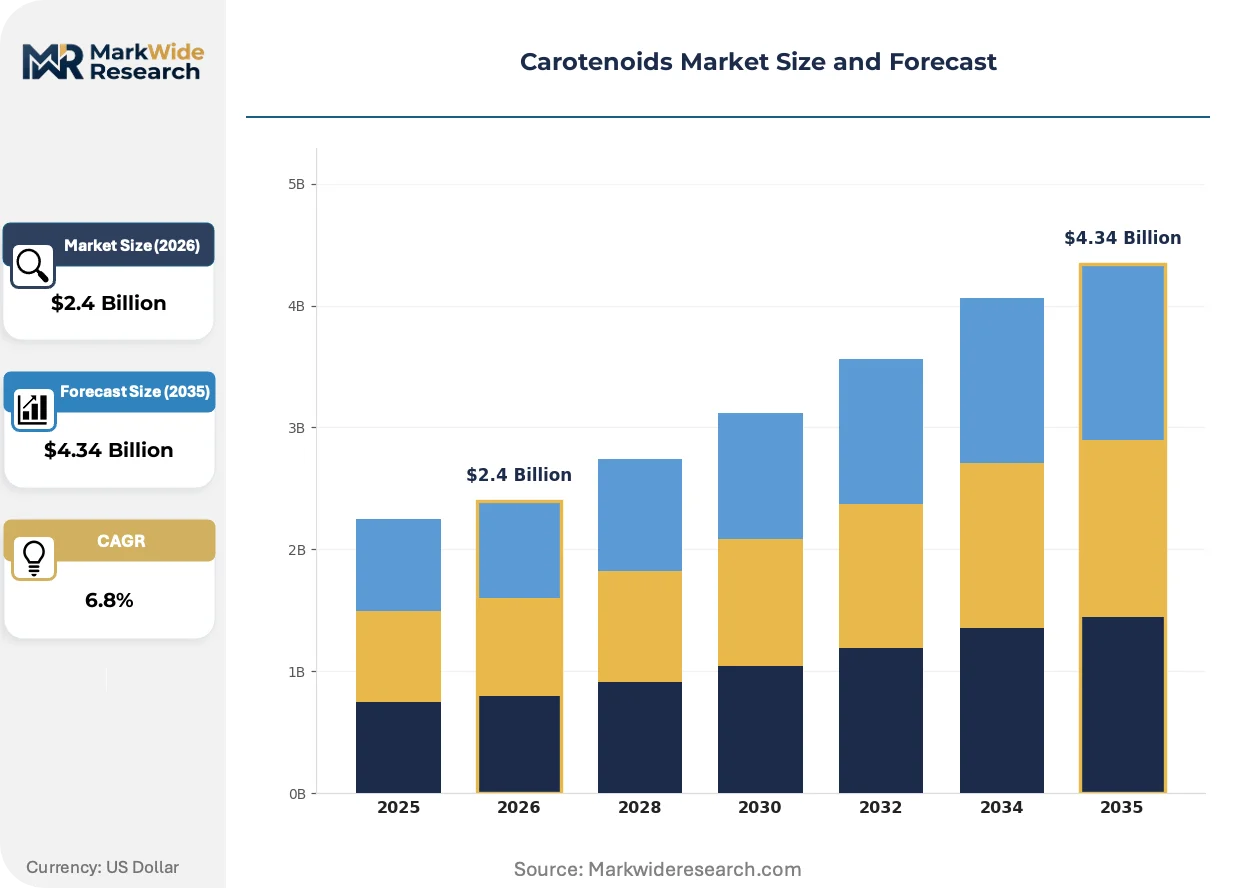
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta-Carotene, Lutein, Astaxanthin, Zeaxanthin Application: Food Coloring, Dietary Supplements, Cosmetics, Animal Feed Source: Natural, Synthetic, Algal, Microbial Form: Powder, Liquid, Emulsion, Suspension |
| Companies Covered | BASF SE, DSM-Firmenich AG, Kemin Industries, Chr. Hansen Holding A/S, Döhler Group SE, Givaudan SA, Allied Biotech Corporation, Cyanotech Corporation, Lycored Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotenoids Market Emerging Trajectories
Fermentation technology advances and regulatory disclosure mandates are compressing the synthetic-natural cost gap while reshaping how buyers verify ingredient provenance across supplement and food coloring channels.
Precision fermentation using CRISPR-engineered Yarrowia lipolytica strains is decomposing the historical yield advantage of chemical synthesis for beta-carotene production. Nutraceutical contract manufacturers in Germany and the Netherlands are piloting these platforms at 10,000-liter scale. The technology is decomposing the premium pricing power that petrochemical-derived carotenoids held in food coloring applications.
REACH substance evaluation dossiers for synthetic carotenoid intermediates are tightening impurity disclosure thresholds for benzene-derived residuals. ECHA's 2024-2026 rolling action plan specifically targets food additive precursors with updated toxicological endpoints. European feed compounders are accelerating natural-source qualification to preempt authorization uncertainty for synthetic beta-carotene in layer hen diets.
Buyer consolidation among multinational supplement brands is compressing supplier qualification cycles from 18 months to 8 months. Third-party certification bodies such as NSF International and USP are displacing in-house vendor audit programs for astaxanthin and lutein sourcing. This pattern is most visible in North American direct-to-consumer eye health brands streamlining their approved supplier lists to three fermentation-derived and three plant-extracted sources.
Carotenoids Market Segmentation
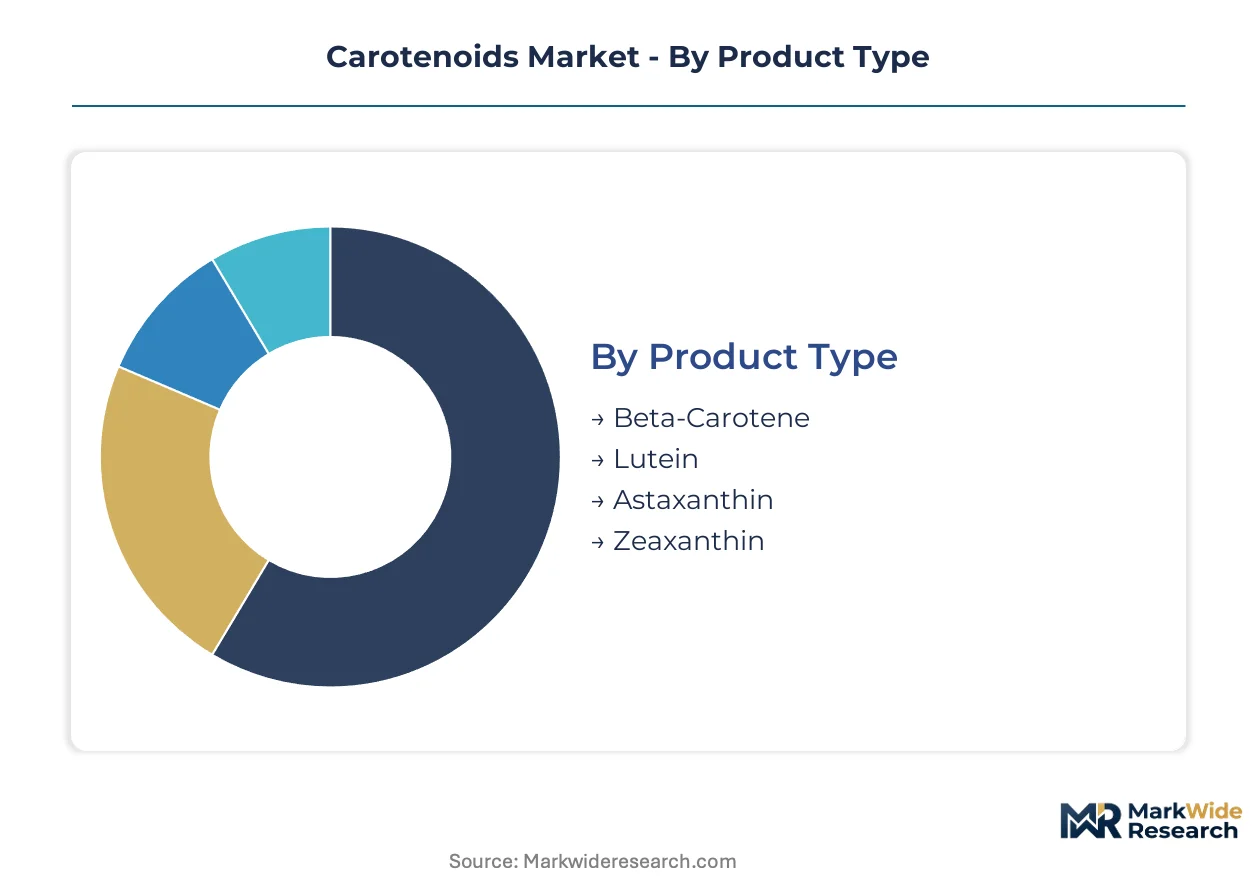
Carotenoid suppliers must navigate divergent technical specifications across food coloring, pharmaceutical, and feed applications where purity thresholds and dispersibility requirements reshape procurement priorities. Segmentation clarity determines which production platforms—chemical synthesis, solvent extraction, or precision fermentation—capture margin in each channel.
Product Type:
Domestic fermentation capacity in China and India supplies lutein and astaxanthin for local supplement formulators, while synthetic beta-carotene production concentrates in European and US petrochemical corridors serving export-led food coloring demand.
- Beta-Carotene:C40 tetraterpenoid synthesized via chemical condensation of retinal precursors or extracted from palm oil and algae. Food coloring applications in the United States and Brazil absorb volume from synthetic production, though EFSA Novel Food scrutiny on petrochemical residuals is redirecting some European procurement toward fermentation-derived alternatives.
- Astaxanthin:Ketocarotenoid with superior antioxidant potency produced via Haematococcus pluvialis cultivation or Blakeslea trispora fermentation. Aquaculture feed demand in Norway and Japan anchors synthetic supply, while dietary supplement brands in Germany and California premium-price natural-source algal extracts with carbon-13 isotope verification.
- Lutein:Xanthophyll pigment concentrated in marigold oleoresin from Indian and Chinese cultivation. Eye health positioning drives US and European supplement procurement, with automated solvent recovery in Karnataka processing clusters reducing cost structures for export markets.
- Zeaxanthin:Stereoisomer of lutein co-extracted from marigold or produced via microbial fermentation. Macular health claims in Japanese and South Korean functional foods concentrate demand, though supply remains tethered to lutein extraction economics.
Beta-carotene holds the largest share; momentum sits with astaxanthin as aquaculture expansion and cosmetic antioxidant positioning accelerate fermentation capacity investment.
Application:
Cost tier stratification separates commodity-grade feed and food coloring volumes from pharmaceutical-grade supplement and cosmetic specifications requiring extended dossier qualification.
- Food Coloring:Synthetic beta-carotene dominates beverage and confectionery applications where cost-per-unit color intensity determines procurement. FDA GRAS self-affirmation enables rapid US market entry, while China's SAMR maintains stricter residual solvent limits on imported synthetic batches.
- Dietary Supplements:Lutein-zeaxanthin combinations for eye health and astaxanthin for antioxidant claims command premium positioning. USP verification and NSF International certification displace in-house supplier audits as buyer consolidation compresses qualification cycles.
- Cosmetics:Topical antioxidant and UV-protection formulations utilize astaxanthin nanoemulsions and beta-carotene provitamin A activity. REACH substance evaluation dossiers for benzene-derived residuals are accelerating natural-source qualification among European formulators.
- Animal Feed:Layer hen yolk pigmentation and aquaculture salmonid coloration absorb synthetic beta-carotene and astaxanthin volumes. ECHA's 2024-2026 rolling action plan targeting food additive precursors is creating authorization uncertainty for petrochemical-derived inputs in European compound feeds.
Food coloring captures the greatest volume throughput; dietary supplements generate the steepest margin expansion as clinical substantiation requirements filter out commodity suppliers.
Source:
Supply concentration varies sharply: petrochemical corridors for synthetic, marigold cultivation belts for plant-extracted, and photobioreactor clusters for algal production each face distinct climate and regulatory exposures.
- Synthetic:Chemical synthesis from benzene and acetone feedstocks yields standardized purity at scale. Margin compression from volatile aromatic hydrocarbon pricing and REACH impurity disclosure mandates is eroding cost advantage in European food additive applications.
- Natural:Solvent extraction from marigold, carrot, and palm biomass supplies lutein and beta-carotene. Indian processing clusters in Tamil Nadu and Andhra Pradesh dominate oleoresin refinement, with automated extraction lines reducing solvent recovery costs for export markets.
- Algal:Haematococcus pluvialis cultivation in closed photobioreactors or open raceways yields high-purity astaxanthin. Hawaii and Israel host concentrated production, exposing premium channels to water access constraints and climate disruption risks.
- Microbial:Fermentation with engineered Blakeslea trispora or Yarrowia lipolytica strains decomposes synthetic cost advantages. Shandong and Jiangsu provinces in China are scaling fermentation capacity for domestic supplement procurement and TCM-crossover positioning.
Synthetic sources retain volume leadership; microbial fermentation is climbing the fastest as CRISPR-engineered strains and CSRD carbon footprint disclosure reshape buyer preferences.
Form:
Functional requirements across feed milling, tablet compression, and beverage fortification dictate dispersibility, stability, and bioavailability specifications that segment manufacturing capabilities.
- Powder:Spray-dried or crystalline formats dominate feed and supplement applications where flowability and shelf stability determine handling economics. Dry blending compatibility with vitamin premixes anchors demand in US and Brazilian compound feed operations.
- Liquid:Oil-soluble suspensions in medium-chain triglycerides or sunflower oil serve softgel encapsulation and direct feed addition. Cold-weather crystallization risks limit northern European storage logistics without heated handling infrastructure.
- Emulsion:Cold-water dispersible nanoemulsions open beverage fortification applications previously blocked by lipid-solubility barriers. German and Dutch contract manufacturers are piloting astaxanthin emulsions at 10,000-liter scale for functional drink brands.
- Suspension:Aqueous or oil-based dispersions with stabilizing agents for specific pH and temperature ranges. Cosmetic serum and topical delivery systems in South Korea and France utilize astaxanthin suspensions with enhanced dermal penetration claims.
Powder formulations maintain the greatest installed base; emulsion technology is gaining share fastest as beverage fortification bypasses traditional supplement delivery formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation clusters export astaxanthin and lutein to European supplement brands and North American aquaculture feed compounders, while Indian marigold processors supply oleoresin to US eye health formulators.
China
Domestic supplement consumption and TCM-crossover formulations drive lutein demand in Shandong and Jiangsu provinces. NMPA blue-hat registration requirements extend qualification timelines for imported finished goods, favoring local production. Fermentation capacity in Weifang and Yantai scales CRISPR-engineered strains for astaxanthin output.
Germany
Nutraceutical contract manufacturers pilot precision fermentation platforms at industrial scale for beta-carotene alternatives. ECHA's REACH substance evaluation dossiers tighten impurity disclosure thresholds for benzene-derived residuals. The Cologne-Düsseldorf corridor hosts third-party certification bodies streamlining supplier qualification for multinational brands.
United States
Direct-to-consumer eye health brands consolidate approved supplier lists for lutein and zeaxanthin sourcing. FDA GRAS self-affirmation enables rapid ingredient market entry compared to European authorization pathways. Softgel encapsulation clusters in New Jersey and California absorb oil-soluble astaxanthin suspensions.
India
Underpenetrated dietary supplement retail channels bypass traditional pharmacy distribution through e-commerce platforms. FSSAI regulations govern residual solvent limits in marigold oleoresin imports. Automated extraction lines in Karnataka processing clusters reduce production costs for export markets.
Japan
Functional food applications for macular health claims concentrate zeaxanthin demand in Tokyo-Osaka corridors. PMDA and FOSHU systems impose extended substantiation requirements for novel carotenoid sources. Aquaculture feed compounders in Nagasaki Prefecture secure synthetic astaxanthin for salmonid coloration.
Carotenoids Market Vendor Landscape
Listed leaders compete with private specialists across fermentation technology and extraction scale. The vendor base segments into petrochemical-integrated synthetics, algal-cultivation purists, and precision-fermentation entrants. Three archetypes dominate: cost-scaled commodity suppliers, premium natural-source validators, and biotech-platform disruptors. Capacity expansion and strategic partnerships represent the dominant competitive moves as qualification cycles compress.
Within the integrated chemical synthesis tier, BASF SE anchors petrochemical-derivative production. DSM-Firmenich AG and Kemin Industries occupy positions across fermentation-derived and plant-extracted specializations. These three exemplify how scale, vertical integration depth, and clinical substantiation capabilities stratify competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich AG |
| Kemin Industries |
| Chr. Hansen Holding A/S |
| Döhler Group SE |
| Givaudan SA |
| Allied Biotech Corporation |
| Cyanotech Corporation |
| Lycored Limited |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between algal astaxanthin cultivators in Hawaii and dietary supplement brands lock in both supply access and price visibility, insulating premium channels from spot market volatility in petrochemical-derived beta-carotene.
Pricing Analysis
Synthetic-to-natural technology-generation pricing gaps stratify procurement decisions across the carotenoid market. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates astaxanthin nanoemulsions for cosmetics from commodity beta-carotene for layer hen diets. Cost compression in synthetic beta-carotene intensifies because benzene feedstock volatility erodes margin buffers for European chemical synthesis operators. Feed compounders exhibit the highest price sensitivity, while cosmetic formulators purchasing carbon-13 verified algal extracts demonstrate the least.
Supply Chain Analysis
Strait of Hormuz transit underwrites solvent shipments to Indian marigold processing clusters, exposing lutein supply chains to geopolitical disruption risks. Production gravity centers on China for fermentation-derived astaxanthin, India for marigold oleoresin extraction, and Germany for precision fermentation piloting. Raw material dependencies encompass benzene and acetone for synthetic routes, hexane for solvent extraction, and glucose feedstocks for microbial fermentation. Single-source vulnerability concentrates in Haematococcus pluvialis cultivation where Hawaii and Israel host limited photobioreactor capacity. Distribution runs through nutraceutical contract manufacturers in Germany and the Netherlands before reaching North American supplement brands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against precision fermentation platforms that decompose historical cost advantages of petrochemical-derived carotenoids.
For Market Incumbents: Compound defensive moats by securing backward integration into marigold cultivation belts in Karnataka and Andhra Pradesh, insulating against Indian oleoresin export cost fluctuations. Accelerate carbon footprint verification protocols to preempt CSRD procurement preference shifts away from benzene-derived inputs. Capacity addition in Shandong fermentation clusters anchors supply security for TCM-crossover supplement positioning. For New Entrants and Emerging Players: NSF International certification fast-track unlocks entry into North American direct-to-consumer eye health brands that have compressed supplier qualification cycles from eighteen months to eight. Underpenetrated Indian dietary supplement retail channels accessed through e-commerce platforms bypass entrenched pharmacy distribution. Beverage fortification emulsion technology offers the most penetrable application white-space as functional drink brands seek cold-water dispersible astaxanthin formats. For Investors and Strategic Acquirers: Capital is best deployed toward precision fermentation platform operators with CRISPR-engineered strain libraries, given the technology's trajectory to erode synthetic cost advantages across the analysis window. Fermentation-derived astaxanthin specialists with validated EFSA Novel Food dossiers represent the priority acquisition archetype. Monitor algal authentication protocol standardization between mass spectrometry and carbon isotope approaches as the signal indicating premium channel integrity inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | CRISPR-engineered Yarrowia lipolytica strains decompose synthetic beta-carotene cost advantages in food coloring. |
| EFSA Novel Food Dossier Completion | Authorization for Blakeslea trispora-derived astaxanthin unlocks human nutrition beyond aquaculture feed. |
| Carbon Footprint Verification Program | CSRD-compliant disclosure protocols secure procurement preference from European multinational supplement brands. |
| Marigold Cultivation Backward Integration | Captive supply of Indian oleoresin reduces exposure to solvent recovery cost volatility in Karnataka clusters. |
| Emulsion Technology Partnership | Cold-water dispersible nanoemulsions open beverage fortification applications previously blocked by lipid-solubility barriers. |
Methodological Framework
The analysis maps synthetic beta-carotene, fermentation-derived astaxanthin, marigold-extracted lutein, and algal-source carotenoids, each validated through fermentation technologists, extraction plant managers, supplement brand procurement leads, and regulatory affairs specialists. Primary interviews with industry stakeholders combine with secondary validation from EFSA Novel Food registers, FDA GRAS notifications, REACH substance evaluation dossiers, and customs trade data. Bottom-up capacity modeling and top-down demand triangulation cross-verify volume estimates across production platforms.
Consistency checks against external benchmarks validate projection outputs against disclosed fermentation capacity expansions and extraction facility utilization rates. The analytical framework segments by source technology, application purity tier, formulation dispersibility, and regional regulatory cluster across the modeling period. CAGRs derive from segment-level supply-demand balance modeling incorporating ECHA authorization timelines and NMPA registration velocity as industry-specific forecast inputs.
Underlying assumptions cover EFSA Novel Food approval continuity, benzene feedstock price band stability, and algal cultivation climate conditions, with deviation risk concentrated in REACH impurity threshold tightening and Haematococcus pluvialis harvest disruption. Practitioners should keep alternative scenarios live as precision fermentation yield improvements and carbon disclosure mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cold-Pressed Coconut Oil Market
Ingredients
Global Vitamin Ingredients Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
Mung Bean Protein Market
Ingredients
Ice Cream Bases Market
Ingredients
Mineral Premix Market
Ingredients
Corn Peptide Market
Ingredients
China Beer Adjuncts Market
Ingredients
Icing Shortening Market
Ingredients
Botanical Ingredients Market
Ingredients
Cacao Bean Market
Ingredients
Quark Powder Market
Ingredients
Savory Ingredients Market