
 Proteose Peptone Market | 2026-2036
Proteose Peptone Market Size, Share, and Industry Trends Forecast 2026-2036
Proteose Peptone Market Analytics
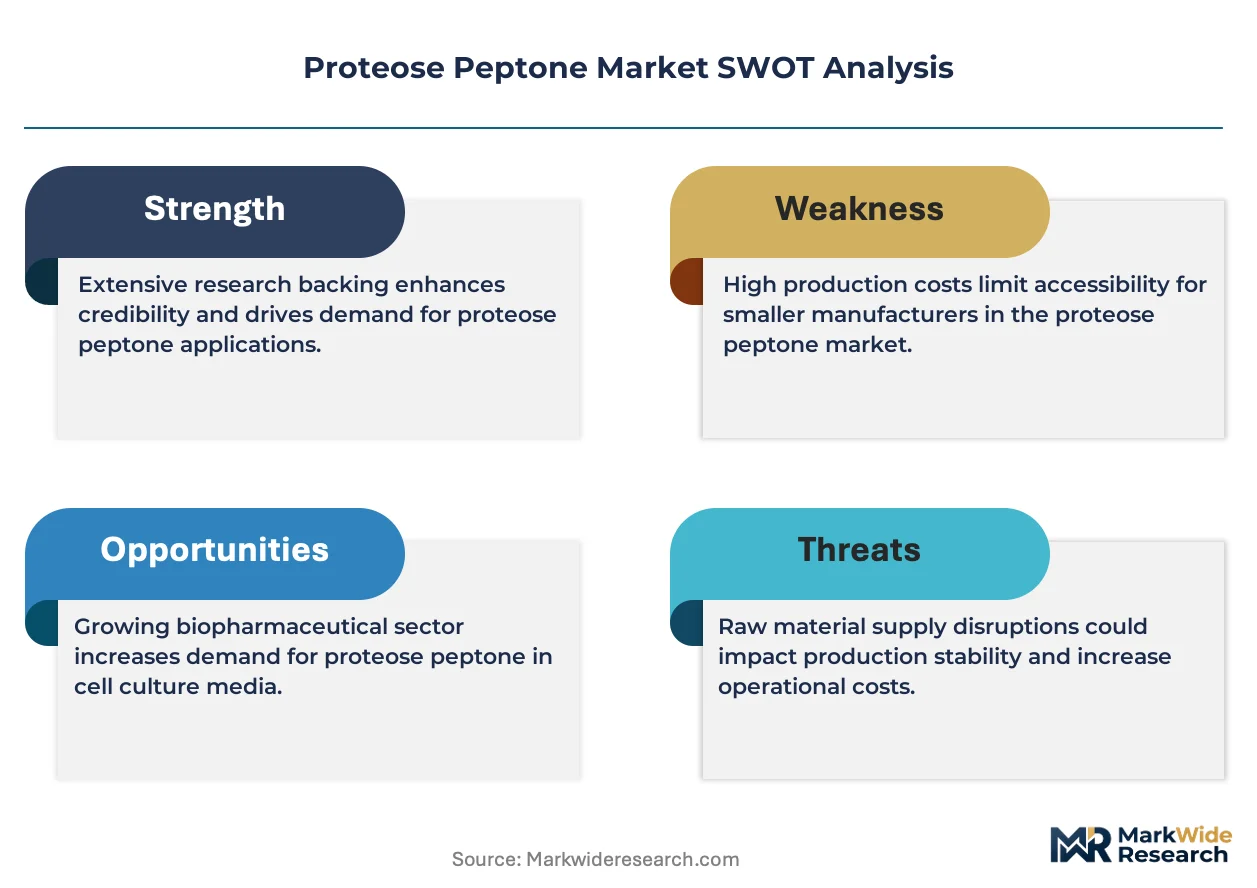
Plant-derived hydrolysates is repositioning proteose peptone economics in cell culture applications. Thermo Fisher Scientific leverages its global distribution network to sustain supply chain continuity for pharmaceutical-grade peptone. Merck KGaA anchors its position through backward integration into raw material sourcing. BD Biosciences differentiates via specialized formulations for vaccine production workflows.
Proteose peptone is a complex mixture of peptides and amino acids derived from enzymatic digestion of animal tissue, typically containing nitrogen levels between 12% and 15% and serving as a nitrogen source in microbial growth media and mammalian cell culture. Casein hydrolysate dominates product type demand due to its established performance in fermentation processes, while yeast extract segments expand fastest driven by plant-based media trends in biotechnology. Application demand clusters in microbiology for quality control testing, with cell culture segments capturing premium margins from serum-free media adoption.
FDA enforces current Good Manufacturing Practice standards for peptone used in pharmaceutical applications, while EMA's REACH compliance requirements shape import specifications for European biopharmaceutical manufacturers. ISO 11133 standards for culture media quality create baseline performance benchmarks that filter market access for regional suppliers. Stakeholders must monitor regulatory divergence between plant-derived and animal-derived peptone certification pathways as sustainability mandates reshape raw material sourcing decisions.
Market Dynamics
Plant-derived peptone alternatives are compressing the addressable market for traditional animal-sourced proteose peptone as biopharmaceutical manufacturers face mounting pressure from ESG disclosure requirements and supply chain traceability mandates.
Growth Catalysts
- Serum-free media mandates:Vaccine manufacturers in Germany and the United States are eliminating fetal bovine serum from upstream processes, creating pull for peptone-based nutrient formulations that replicate serum performance without animal origin concerns.
- FDA cGMP enforcement:The agency's tightened inspection protocols for raw material suppliers are disqualifying uncertified peptone producers, concentrating volume among pharmaceutical-grade certified manufacturers.
- Cell therapy manufacturing scale-up:CAR-T and stem cell production facilities require nitrogen sources with batch-to-batch consistency that proteose peptone delivers, expanding addressable demand beyond traditional microbial applications.
Market Restraints
- Animal tissue input volatility:Bovine spongiform encephalopathy surveillance protocols in Europe disrupt raw material availability for tissue-derived peptone, forcing manufacturers to maintain dual-source inventory buffers.
- Supplier concentration in Midwestern US:Three rendering facilities supply the majority of North American starting material, creating geographic vulnerability to climate-driven livestock supply shocks.
- Peptide hydrolysate substitution:Chemically defined media components from synthetic peptide suppliers are capturing premium cell culture segments where regulatory filing simplicity outweighs cost considerations.
Strategic Opportunities
- Indian biopharmaceutical manufacturing expansion:CDSCO's streamlined approval pathways for imported cell culture raw materials are opening access to vaccine producers in Hyderabad and Bengaluru clusters.
- Precision fermentation nutrient customization:Engineered microbial strain producers require peptone formulations with specific amino acid profiles, creating specification-driven premium tiers beyond commodity grades.
- EU Green Deal bio-based procurement mandates:Publicly funded research institutions must source sustainable-certified media components, advantaging peptone suppliers with mass-balance chain of custody documentation.
Industry Challenges
- ISO 11133 proficiency testing failures:Culture media manufacturers struggle to demonstrate lot-to-lot consistency across enzymatic digestion batches, delaying certification renewals and freezing new customer onboarding.
- Cross-contamination control capex:Dedicated production lines for animal-origin-free peptone require segregated facilities that smaller suppliers cannot finance without strategic partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proteose Peptone Market |
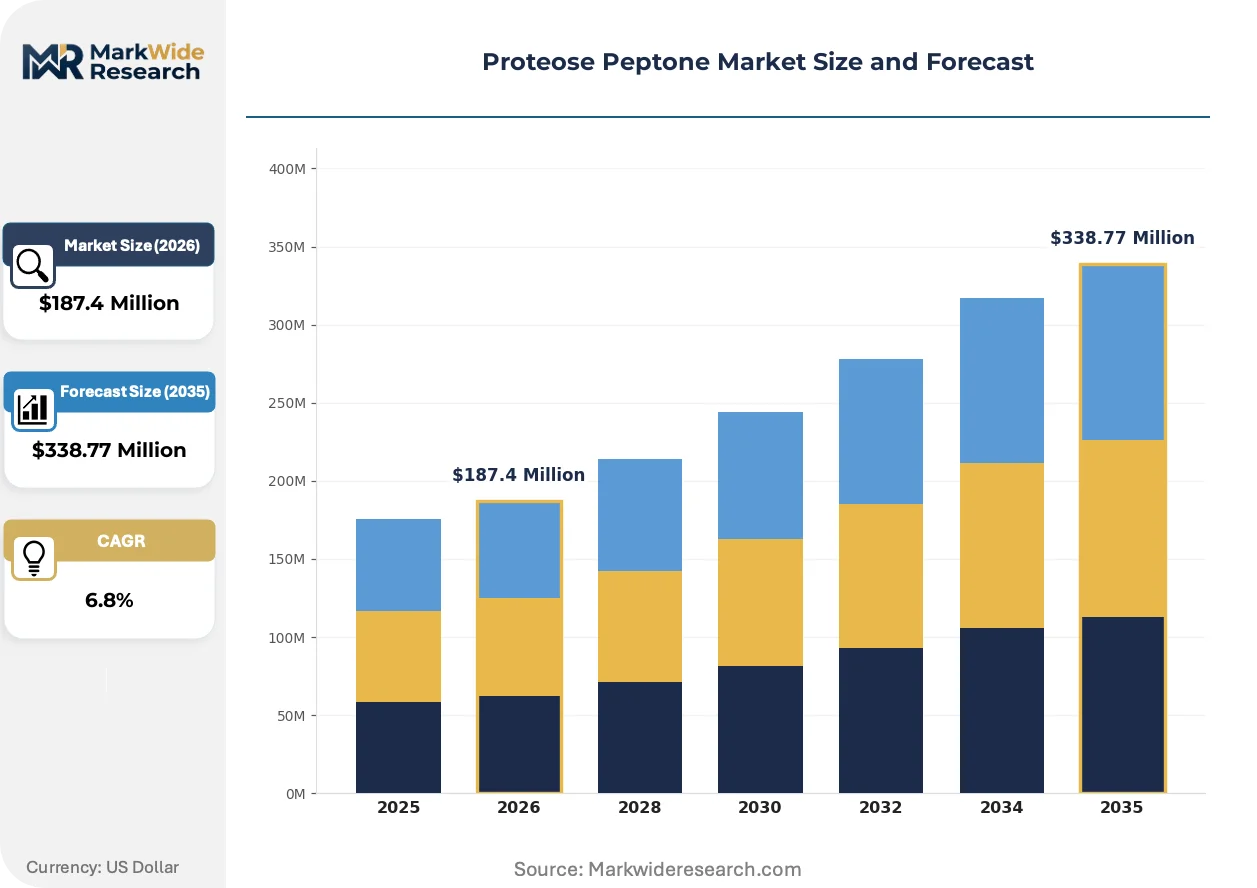
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Extract, Casein Hydrolysate, Peptic Digest of Animal Tissue, Hydrolyzed Vegetable Protein Application: Microbiology, Pharmaceutical Formulations, Nutritional Supplements, Cell Culture End User: Research Laboratories, Pharmaceutical Companies, Biotechnology Firms, Food Industry Distribution Channel: Online Retail, Direct Sales, Distributors, Resellers |
| Companies Covered | BD Biosciences, Titan Biotech, Thermo Fisher Scientific, Biotecnica, Condalab, Merck KGaA, Solabia, BioSpringer, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proteose Peptone Market Evolving Landscape
Enzymatic processing precision and alternative protein feedstocks are redefining what constitutes pharmaceutical-grade peptone, while regulatory frameworks race to catch up with manufacturing capabilities.
Recombinant enzyme digestion systems are absorbing market share from traditional pancreatic enzyme processes in peptone production. Contract manufacturers in Switzerland and Singapore are adopting these systems to eliminate batch variability associated with animal-derived enzyme sources. The technology is absorbing quality control costs by reducing out-of-specification rates and compressing release testing timelines for GMP-grade material.
REACH Annex XIV authorization requirements for processed animal proteins are forcing European peptone importers to document full supply chain traceability. The regulation is redirecting procurement toward suppliers with vertically controlled rendering operations. German and Dutch biopharmaceutical manufacturers are responding by qualifying alternative nitrogen sources and negotiating multi-year supply agreements with certified vendors.
Direct procurement relationships between peptone manufacturers and cell therapy developers are displacing traditional distribution through laboratory supply catalogs. Large-scale gene therapy producers in Massachusetts and North Carolina are negotiating specification-lock contracts that guarantee amino acid composition ranges. This pattern is most visible in the United States where CDMO consolidation has concentrated purchasing power among fewer buyers with precise formulation requirements.
Proteose Peptone Market Segmentation
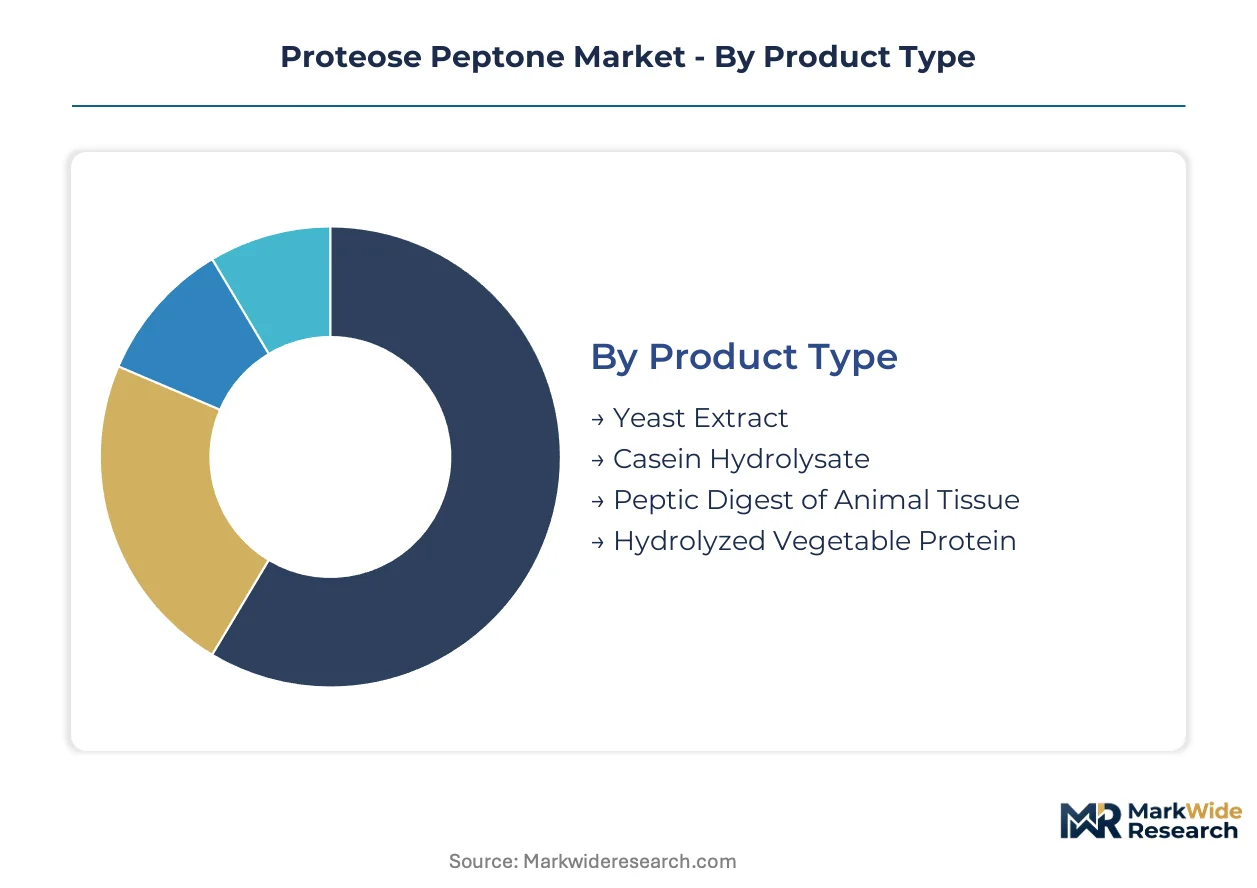
Proteose peptone segmentation reflects divergent purity requirements between microbial quality control and cell therapy manufacturing. Buyers select grades based on regulatory filing status, batch documentation depth, and amino acid profile precision rather than commodity pricing alone.
Product Type:
Buyers differentiate primarily by nitrogen content consistency and origin documentation for downstream regulatory submissions.
- Casein Hydrolysate:Enzymatic digestion of milk protein yields 12-15% total nitrogen with predictable peptide distribution. Vaccine manufacturers in Germany and the United States specify this grade for fermentation seed trains where lot-to-lot reproducibility determines batch release timelines.
- Yeast Extract:Autolyzed Saccharomyces cerevisiae provides B-vitamin cofactors alongside nitrogen. Plant-based media formulations in precision fermentation facilities are absorbing volumes here as ESG disclosure requirements harden against animal-derived inputs.
- Peptic Digest of Animal Tissue:Traditional pancreatic enzyme digestion of bovine or porcine tissue generates complex peptide mixtures. BSE surveillance protocols in Europe constrain raw material availability for this segment.
- Hydrolyzed Vegetable Protein:Acid or enzymatic treatment of soy, wheat, or pea proteins creates allergen-flagged alternatives. Food industry applications dominate current offtake pending pharmaceutical-grade certification expansion.
Casein hydrolysate leads volumes today; yeast extract is gaining share fastest.
Application:
Margin structures separate commodity testing applications from premium therapeutic manufacturing segments.
- Cell Culture:Serum-free media adoption in CAR-T and stem cell production demands peptone with defined molecular weight distributions and endotoxin documentation. Massachusetts and North Carolina gene therapy clusters negotiate specification-lock contracts with amino acid composition guarantees.
- Microbiology:Quality control testing for pharmaceutical water systems and environmental monitoring consumes standard-grade peptone in high volume. FDA cGMP inspection protocols for raw material suppliers are disqualifying uncertified producers from this base.
- Pharmaceutical Formulations:Direct incorporation into parenteral or oral products requires excipient-grade certification with elemental impurity profiles. ICH Q3D compliance documentation extends supplier qualification timelines.
- Nutritional Supplements:Sports nutrition and clinical enteral feeding applications value peptone for rapid amino acid bioavailability. FSSAI and FDA labeling requirements for allergen disclosure shape formulation choices.
Microbiology commands absolute volume; cell culture delivers steepest expansion trajectory.
End User:
Procurement sophistication ranges from catalog purchasing to multi-year supply agreements with audit rights.
- Pharmaceutical Companies:Integrated vaccine and biologics manufacturers conduct on-site supplier audits and require dedicated production lines for animal-origin-free material. CDMO consolidation in the United States has concentrated purchasing power among fewer buyers with precise formulation requirements.
- Biotechnology Firms:Cell therapy developers and precision fermentation startups prioritize flexible minimum order quantities and rapid custom formulation turnaround. Direct procurement relationships are displacing traditional laboratory supply distribution.
- Research Laboratories:Academic and government institutions operate on grant-funded procurement cycles with price sensitivity. EU Green Deal bio-based procurement mandates for publicly funded research are redirecting specifications toward sustainable-certified alternatives.
- Food Industry:Flavor enhancement and nutritional fortification applications tolerate broader compositional variation than pharmaceutical grades. Mass-balance chain of custody documentation is becoming a tender requirement for major manufacturers.
Pharmaceutical companies dominate contract value; biotechnology firms are expanding order frequency fastest.
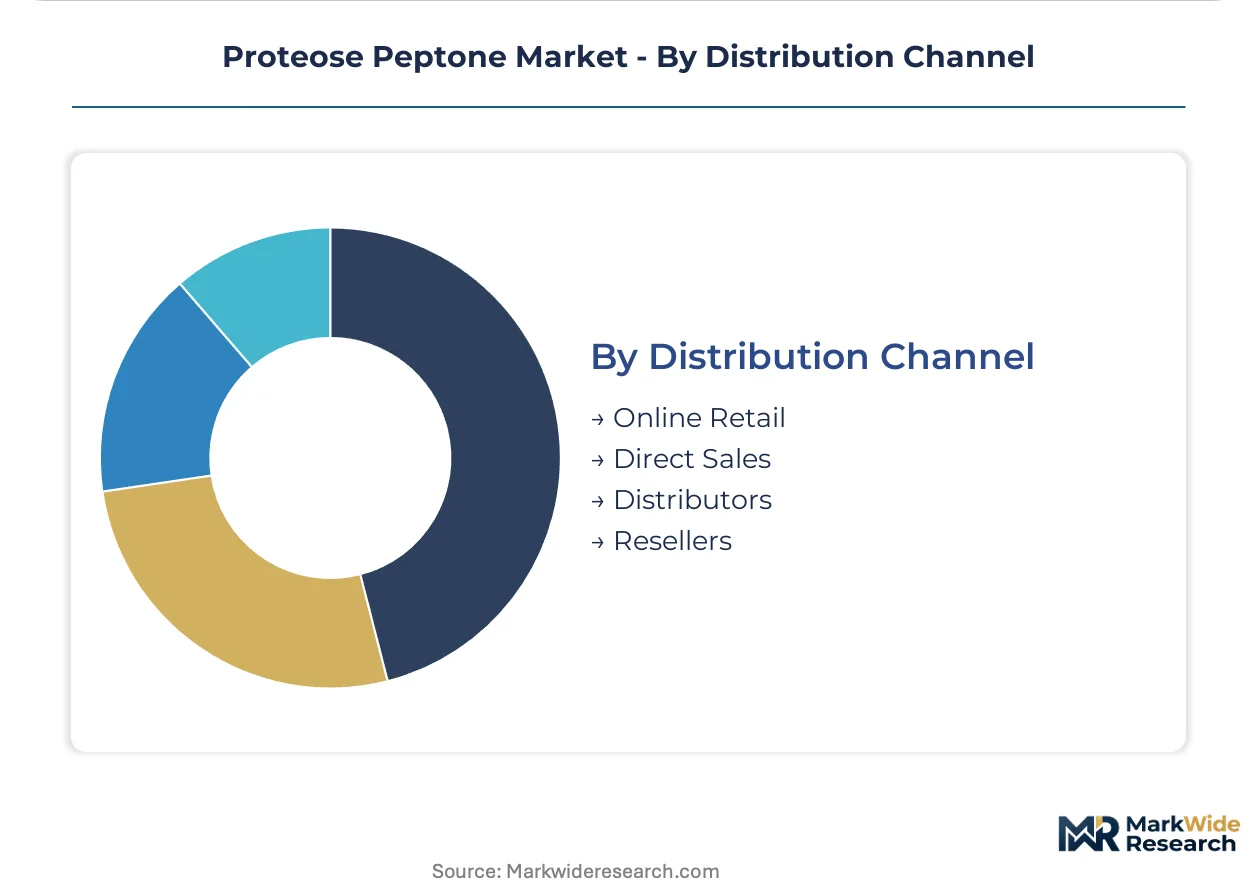
Distribution Channel:
Channel selection tracks order size, technical support requirements, and geographic proximity to manufacturing.
- Direct Sales:Large-scale gene therapy and vaccine producers negotiate specification-lock contracts directly with peptone manufacturers. Thermo Fisher Scientific and Merck KGaA field technical sales teams for pharmaceutical-grade accounts.
- Distributors:Regional laboratory supply houses inventory standard grades for research laboratories and smaller biotechnology firms. REACH Annex XIV documentation requirements are filtering distributor portfolios toward vertically integrated suppliers.
- Online Retail:E-commerce platforms serve urgent small-volume orders from research laboratories with credit card purchasing authority. ISO 11133 certification status is increasingly displayed as a search filter.
- Resellers:Independent agents broker specialized formulations for niche applications with limited manufacturer direct support. Reseller margins compress as manufacturers build proprietary e-commerce capabilities.
Direct sales capture the largest transaction sizes; distributor relationships are expanding geographic coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts gene therapy clusters drive the steepest demand trajectory for pharmaceutical-grade peptone, while regulatory divergence between FDA cGMP and EMA REACH protocols fragments supplier qualification requirements across manufacturing hubs.
United States
CAR-T production facilities in Massachusetts and North Carolina negotiate specification-lock contracts with amino acid composition guarantees. FDA tightened inspection protocols for raw material suppliers disqualify uncertified peptone producers, concentrating volume among pharmaceutical-grade certified manufacturers. Three rendering facilities in the Midwest supply the majority of North American starting material, creating geographic vulnerability to climate-driven livestock supply shocks.
Germany
Vaccine manufacturers in Marburg and Dresden eliminate fetal bovine serum from upstream processes, creating pull for peptone-based nutrient formulations. EMA REACH Annex XIV authorization requirements for processed animal proteins force importers to document full supply chain traceability. German biopharmaceutical manufacturers respond by qualifying alternative nitrogen sources and negotiating multi-year supply agreements with certified vendors.
India
CDSCO streamlined approval pathways for imported cell culture raw materials open access to vaccine producers in Hyderabad and Bengaluru clusters. Precision fermentation startups prioritize flexible minimum order quantities and rapid custom formulation turnaround. Direct procurement relationships are displacing traditional laboratory supply distribution channels across Indian biotechnology firms.
Switzerland
Contract manufacturers adopt recombinant enzyme digestion systems to eliminate batch variability associated with animal-derived enzyme sources. Swissmedic enforces stringent purity standards for biopharmaceutical raw materials that exceed baseline ISO 11133 requirements. Basel-area CDMOs absorb quality control costs by reducing out-of-specification rates and compressing release testing timelines for GMP-grade material.
Singapore
Biologics manufacturing investments from global pharmaceutical companies create demand for nitrogen sources with batch-to-batch consistency. The country's national pharmaceutical regulator aligns inspection protocols with FDA cGMP and EMA standards to facilitate export qualification. Tuas Biomedical Park hosts production facilities that require dedicated supply lines for animal-origin-free peptone with segregated facilities.
Proteose Peptone Market Competitive Landscape
Global majors compete with regional champions across distribution reach and certification depth. The vendor base stratifies between integrated life science conglomerates with backward integration into raw material sourcing and specialized fermentation media suppliers with formulation agility. Three archetypes dominate: scale-driven distributors with global logistics networks, precision formulators serving cell therapy developers, and regional champions with cost-optimized commodity grades. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers build captive supply of certified starting materials.
Among scale-driven distributors, Thermo Fisher Scientific leverages its global logistics infrastructure to sustain supply chain continuity for pharmaceutical-grade peptone. Merck KGaA anchors the integrated tier through upstream control over raw material sourcing. BD Biosciences occupies a position within the precision formulation segment, differentiating via specialized grades for vaccine production workflows. These three exemplify how competitive positioning depends on certification depth and customer technical support capabilities rather than commodity pricing alone.
| Leading Market Players |
|---|
| BD Biosciences |
| Titan Biotech |
| Thermo Fisher Scientific |
| Biotecnica |
| Condalab |
| Merck KGaA |
| Solabia |
| BioSpringer |
| Kerry Group |
| Others |
Value Network & Pricing Analysis
Midwestern rendering facility operating costs cascade through three distinct pricing tiers as bovine tissue availability fluctuates with climate-driven livestock cycles. Pharmaceutical-grade certification absorbs upstream quality control investments, compressing margins for uncertified suppliers while concentrating pricing power among GMP-validated manufacturers serving Massachusetts gene therapy clusters.
Pricing Analysis
Input-cost pass-through from enzymatic digestion enzyme prices operates on contract-based long-term offtake agreements with annual adjustment clauses. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and research-grade levels reflects certification depth and batch documentation rigor. Pricing pressure stems from yeast extract substitution in plant-based media formulations, eroding traditional animal-sourced peptone premiums. Research laboratories exhibit highest price sensitivity, while CAR-T manufacturers prioritize specification-lock contracts over unit cost.
Supply Chain Analysis
Reverse-logistics flows for temperature-deviated shipments return to Swiss contract manufacturers for re-qualification testing, compressing effective yield rates. Supply concentrates in the United States, Germany, and India, with raw material dependencies on Midwestern rendering facilities, European dairy processing streams, and Indian precision fermentation feedstocks. Single-source vulnerability in North American bovine tissue supply creates exposure to BSE surveillance protocol disruptions. Distribution runs through direct sales for pharmaceutical accounts and regional distributors for research laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds value through regulatory ratchets, with FDA cGMP enforcement tightening supplier qualification thresholds and disqualifying uncertified producers from vaccine manufacturing workflows.
For Market Incumbents: Hedge against peptide hydrolysate substitution by deepening backward integration into recombinant enzyme production and securing dedicated animal-origin-free production lines. Certify alternative nitrogen source portfolios before EMA REACH Annex XIV authorization requirements harden procurement specifications for European biopharmaceutical manufacturers. For New Entrants and Emerging Players: Launch via direct procurement relationships with Indian precision fermentation startups in Hyderabad and Bengaluru, bypassing established laboratory supply distribution channels. Target specification-driven premium tiers for engineered microbial strain producers requiring customized amino acid profiles with flexible minimum order quantities. For Investors and Strategic Acquirers: Consolidation pressure builds where CDSCO streamlined approval pathways concentrate demand among vaccine producers lacking backward integration into raw material sourcing. Five-to-ten year viability favors suppliers with mass-balance chain of custody documentation aligned with EU Green Deal bio-based procurement mandates. Monitor ISO 11133 proficiency testing failure rates as early signals of supplier distress.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | CDSCO streamlined approvals open Indian vaccine cluster access for imported cell culture raw materials. |
| Backward Integration | Captive rendering operations insulate against BSE surveillance protocol disruptions in European supply chains. |
| Long-term Supply Agreement | Specification-lock contracts with Massachusetts gene therapy producers guarantee amino acid composition ranges. |
| Joint Venture | Swiss-Singaporean partnerships combine recombinant enzyme digestion with Tuas Biomedical Park segregated facilities. |
| Green Certification Program | Mass-balance chain of custody documentation satisfies EU Green Deal bio-based procurement mandates for public research. |
Research Methodology
Direct dialogue with fermentation media procurement managers, cell therapy manufacturing directors, regulatory affairs specialists at peptone suppliers, and quality control leads at CDMOs grounds qualitative findings. Secondary validation draws from FDA cGMP inspection records, EMA REACH Annex XIV authorization databases, CDSCO import approval registries, and ISO 11133 proficiency testing results. Bottom-up and top-down triangulation cross-checks segment-level demand against aggregate market sizing.
Bottom-up modeling tracks peptone consumption by application across cell culture, microbiology, pharmaceutical formulations, and nutritional supplements. Segmentation dimensions include product type, application, end user, and distribution channel with regional regulatory cluster overlays. CAGRs derive from trend extrapolation of serum-free media adoption rates and precision fermentation facility buildouts. Forecast inputs incorporate ESG disclosure requirement trajectories and vaccine manufacturing capacity expansion pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between FDA cGMP and EMA REACH protocols. Practitioners should monitor CDSCO approval velocity, BSE surveillance protocol stringency shifts, and synthetic peptide hydrolysate cost curves for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Polydextrose Ingredients Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Africa Plant Protein Ingredients Market
Ingredients
Global Arabinoxylan Fiber Market
Ingredients
Spray-Dried Isolate Market
Ingredients
United States Corn Glucose Market
Ingredients
Sunflower Protein Market
Ingredients
Potato Protein Market
Ingredients
North America Cocoa Products Market
Ingredients
Global Distillers Grains Market
Ingredients
Food Ingredients Market
Ingredients
China Protein Market
Ingredients
Chewing Gum Base Market
Ingredients
Textured Soy Flour Market
Ingredients
Desiccated Coconut Powder Market
Ingredients
Horny Goat Weed Extract Market