
 Chickpea Protein Market | 2026-2036
Chickpea Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Chickpea Protein Market Analysis
ISO 22000 certification is bifurcating the supplier base between food-grade isolate producers and commodity flour traders. AGT Food and Ingredients leverages its Canadian prairie sourcing network to anchor premium isolate supply. ChickP Protein Ltd. specializes in extrusion-ready concentrates with enhanced emulsification properties. InnovoPro Ltd. controls Israeli R&D partnerships that extend functional protein applications into egg-replacement formulations.
Chickpea protein denotes the extracted protein fraction from Cicer arietinum, typically comprising 80-90% protein content in isolate form via alkaline extraction-isoelectric precipitation, valued for its neutral flavor profile and balanced essential amino acid composition suitable for plant-based meat analogs and sports nutrition. Isolates command the deepest margin pools due to solubility specifications required by European food manufacturers, while concentrates gain volume traction in nutritional bars where cost thresholds dominate formulation decisions. The food industry application segment leads absolute consumption, though dietary supplements exhibit the fastest structural expansion as athletes and vegans drive clean-label protein diversification.
EU Green Deal protein transition frameworks and EFSA novel food approval pathways shape product standard requirements for European market access, while India's FSSAI fortification guidelines and PLI scheme disbursement rules determine which domestic processors qualify for subsidized isolate expansion. FDA GRAS self-determination protocols in the United States create a separate compliance track for ingredient suppliers targeting North American CPG brands. Stakeholders must monitor divergence between EU novel food dossier requirements and U.S. self-affirmation pathways, as this regulatory asymmetry will determine which suppliers can serve both jurisdictions without redundant toxicology investments.
Market Dynamics
EU Green Deal protein diversification mandates are compressing formulation timelines for plant-based meat developers, forcing rapid qualification of chickpea isolates as soy alternatives face sustainability scrutiny.
Growth Catalysts
- EFSA novel food approval pathways:European food manufacturers accelerate chickpea protein dossier submissions to secure clean-label positioning ahead of 2030 Farm to Fork targets.
- India's PLI scheme for pulse value addition:Subsidized capital expenditure in Gujarat and Rajasthan processing corridors expands isolate capacity for export markets.
- Extrusion-ready concentrates:Enhanced emulsification properties enable direct substitution in high-moisture meat analog production lines.
Market Restraints
- Input cost volatility:Kabuli chickpea prices fluctuate with Black Sea shipping disruptions and Canadian prairie drought cycles.
- Supply concentration risk:Premium isolate production clusters in Saskatchewan and Alberta prairie networks, creating single-source dependency.
- Technical limitation:Alkaline extraction-isoelectric precipitation yields remain below 65% for desi varieties, constraining margin recovery.
Strategic Opportunities
- Brazil's underpenetrated sports nutrition sector:ANVISA regulatory harmonization with Codex standards opens clean-label protein diversification for athletic formulations.
- Regulatory tailwind from EU Green Deal:Protein transition frameworks mandate public procurement preferences for domestically sourced pulse proteins.
- Technology convergence:Precision fermentation partnerships with chickpea protein hydrolysates enable egg-replacement texture replication in bakery applications.
Industry Challenges
- ISO 22000 certification timelines:Food-grade isolate producers face 18-24 month audit cycles that commodity flour traders bypass.
- Capex intensity for isoelectric precipitation infrastructure:pH adjustment and centrifugation equipment requires specialized stainless steel configurations.
- Skill gaps in pulse protein functionalization:Formulation chemists with extrusion rheology expertise command premium compensation in plant-based meat R&D.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chickpea Protein Market |
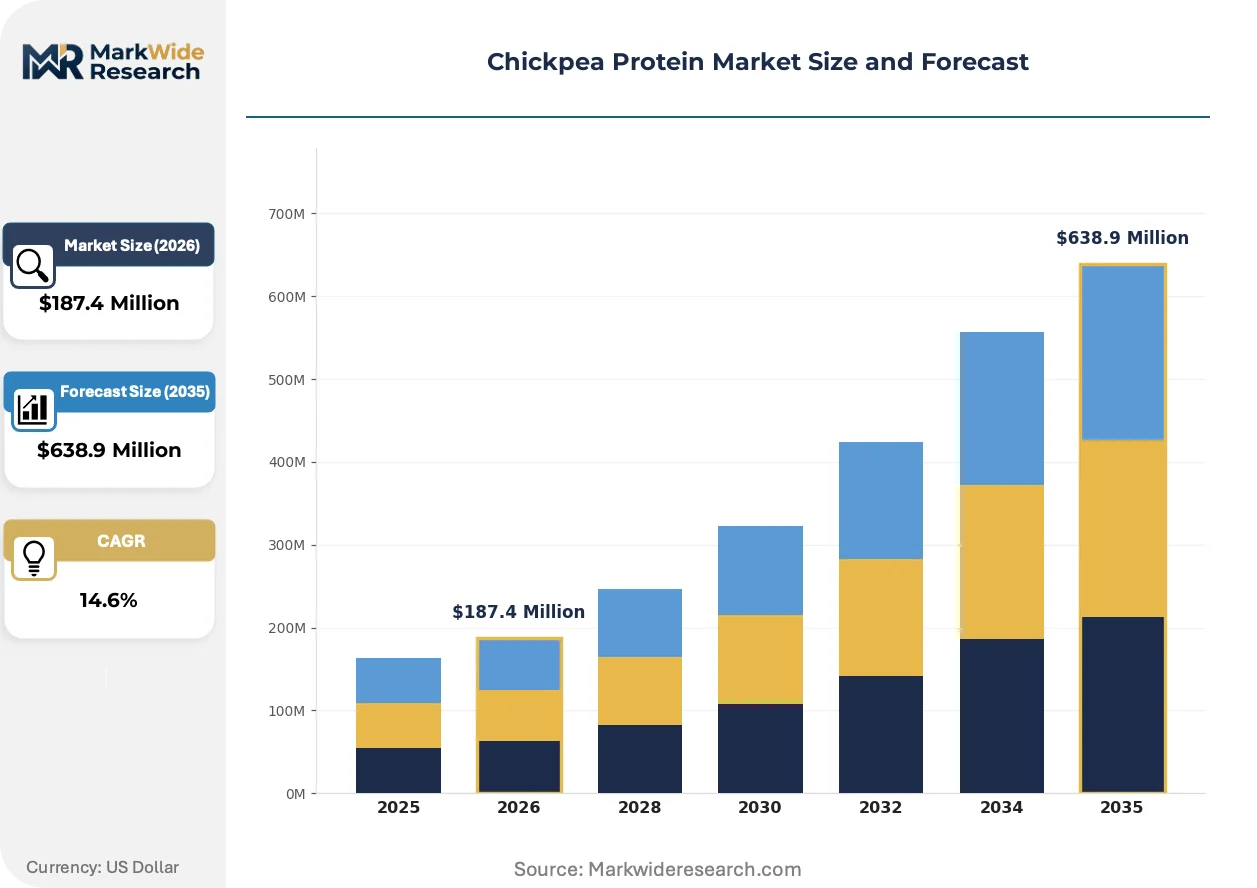
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolates, Concentrates, Flour, Whole Seeds Application: Food Industry, Dietary Supplements, Animal Feed, Nutritional Bars End User: Food Manufacturers, Health Conscious Consumers, Athletes, Vegans Distribution Channel: Retail Stores, Online Platforms, Wholesale, Direct Sales |
| Companies Covered | AGT Food and Ingredients, ChickP Protein Ltd., Ingredion Inc., Cambridge Commodities Ltd, PLT Health Solutions, Archer Daniels Midland Company, InnovoPro Ltd., Nutriati, Inc., Batory Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chickpea Protein Market Emerging Trajectories
Clean-label protein diversification is compressing traditional soy-dominant supply relationships, with chickpea isolates capturing formulation share through neutral flavor profiles and balanced essential amino acid compositions.
Membrane filtration technology is bifurcating the supplier base between high-purity isolate producers and standard concentrate processors. European plant-based meat formulators specify 90% protein content thresholds for texture replication in high-moisture analogs. This specification divergence is forcing capital reallocation toward ultrafiltration-diafiltration infrastructure.
EU Green Deal protein transition frameworks mandate 25% protein diversification in public food procurement by 2030. EFSA novel food approval pathways require chronic toxicology studies that extend market entry timelines by 24-36 months. German and Dutch food manufacturers front-load dossier investments to secure first-mover positioning in institutional catering contracts.
Direct-procurement relationships between CPG brands and prairie processors are displacing traditional ingredient distributor networks. North American sports nutrition companies negotiate long-term offtake agreements with Saskatchewan isolate producers. This channel compression is most visible in premium protein powder segments where lot traceability and allergen segregation command price premiums.
Chickpea Protein Market Segmentation
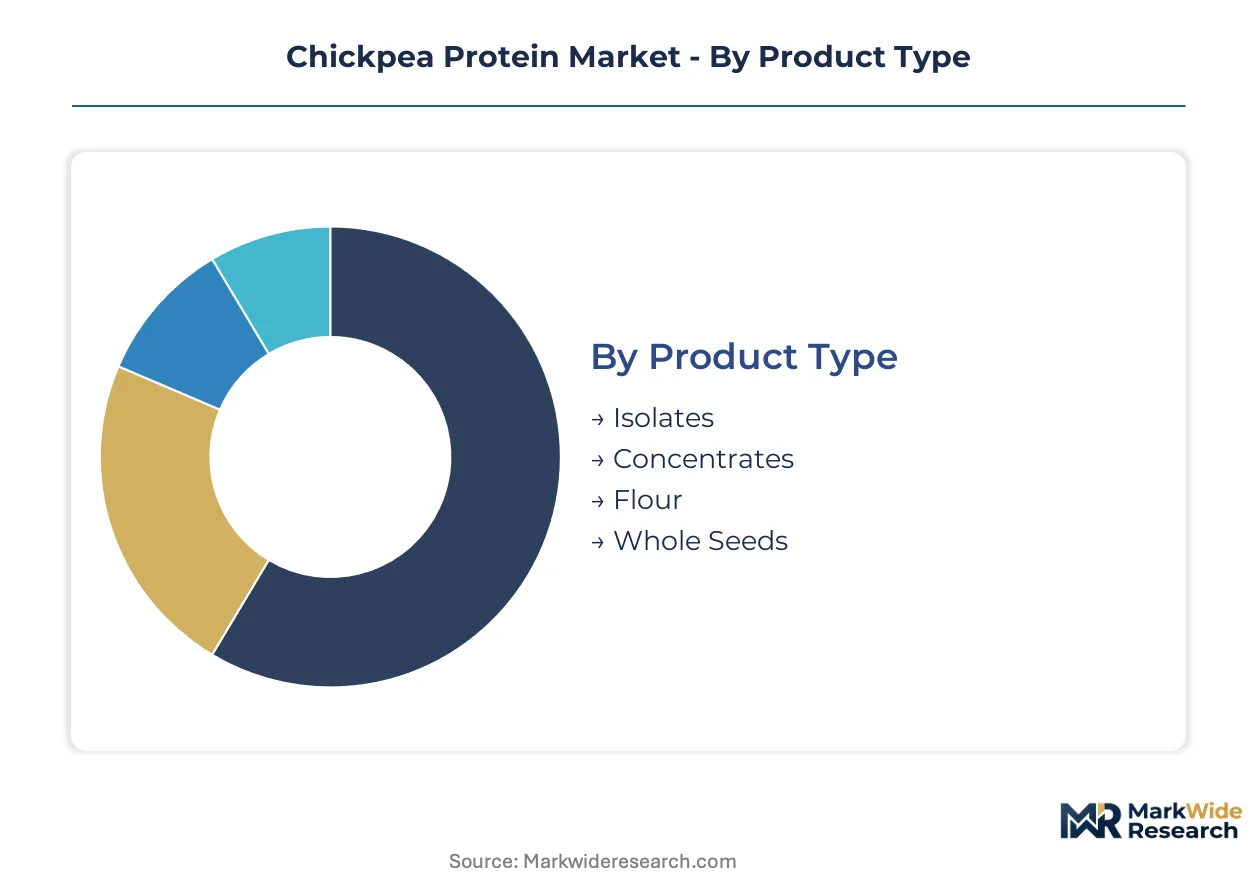
Chickpea protein segmentation reveals how extraction technology, end-use functionality, and channel economics partition value capture across the supply chain. Formulators prioritize isolates for texture-critical applications while cost-sensitive segments absorb concentrates and flour grades.
Product Type:
Substitution pressure from soy and pea protein isolates is most acute in the 80-90% protein tier, where functional equivalence determines procurement decisions.
- Isolates:Alkaline extraction-isoelectric precipitation yields protein fractions of 80-90% purity with neutral flavor profiles. European plant-based meat developers in Germany and the Netherlands specify these grades for high-moisture extrusion applications where EFSA novel food compliance is mandatory.
- Concentrates:Membrane filtration produces 60-70% protein fractions with enhanced emulsification properties. Sports nutrition brands in North America negotiate long-term offtake agreements for extrusion-ready concentrates that reduce formulation complexity in nutritional bars.
- Flour:Ground whole chickpea retains 20-25% protein with full fiber content; Indian FSSAI fortification guidelines drive institutional procurement for school feeding programs.
- Whole Seeds:Unprocessed kabuli and desi varieties serve traditional food applications and limited protein extraction feedstock; Black Sea shipping disruptions compress margins for commodity traders.
Concentrates anchor the volume base while isolates gain share at the steepest rate.
Application:
Cost tier stratification separates premium-positioned segments from commodity absorption channels.
- Food Industry:Plant-based meat analogs, dairy alternatives, and bakery applications demand ISO 22000-certified isolates with documented lot traceability. EU Green Deal protein diversification mandates in public procurement accelerate qualification timelines for chickpea-based formulations.
- Dietary Supplements:Protein powders and ready-to-drink formulations require solubility specifications above 85% at neutral pH. Athletes and vegan consumers in Brazil's ANVISA-regulated market drive clean-label diversification away from soy-dominant portfolios.
- Animal Feed:Aquaculture and pet food applications absorb lower-grade concentrates and processing byproducts; FAO Codex feed safety standards govern mycotoxin thresholds.
- Nutritional Bars:Cost thresholds dominate formulation decisions, with 50-60% protein concentrates substituting for isolates where texture requirements permit.
Food industry applications command the deepest margin pools while dietary supplements expand most quickly.
End User:
Customer type fragmentation separates specification-driven procurement from price-elastic consumption.
- Food Manufacturers:CPG brands in North America and Europe negotiate direct-procurement relationships with Saskatchewan and Alberta prairie processors to secure allergen-segregated supply.
- Health Conscious Consumers:Retail purchasers prioritize clean-label positioning and non-GMO verification; online platform reviews influence repeat purchase behavior.
- Athletes:Sports nutrition formulators specify amino acid completeness ratios; leucine content benchmarks against whey protein drive isolate selection.
- Vegans:Ethical positioning and sustainability credentials influence brand loyalty; EU Green Deal alignment provides procurement justification for institutional buyers.
Food manufacturers concentrate procurement volume while athletes generate the steepest specification premiums.
Distribution Channel:
Channel economics bifurcate between traceability-intensive direct sales and volume-maximizing wholesale routes.
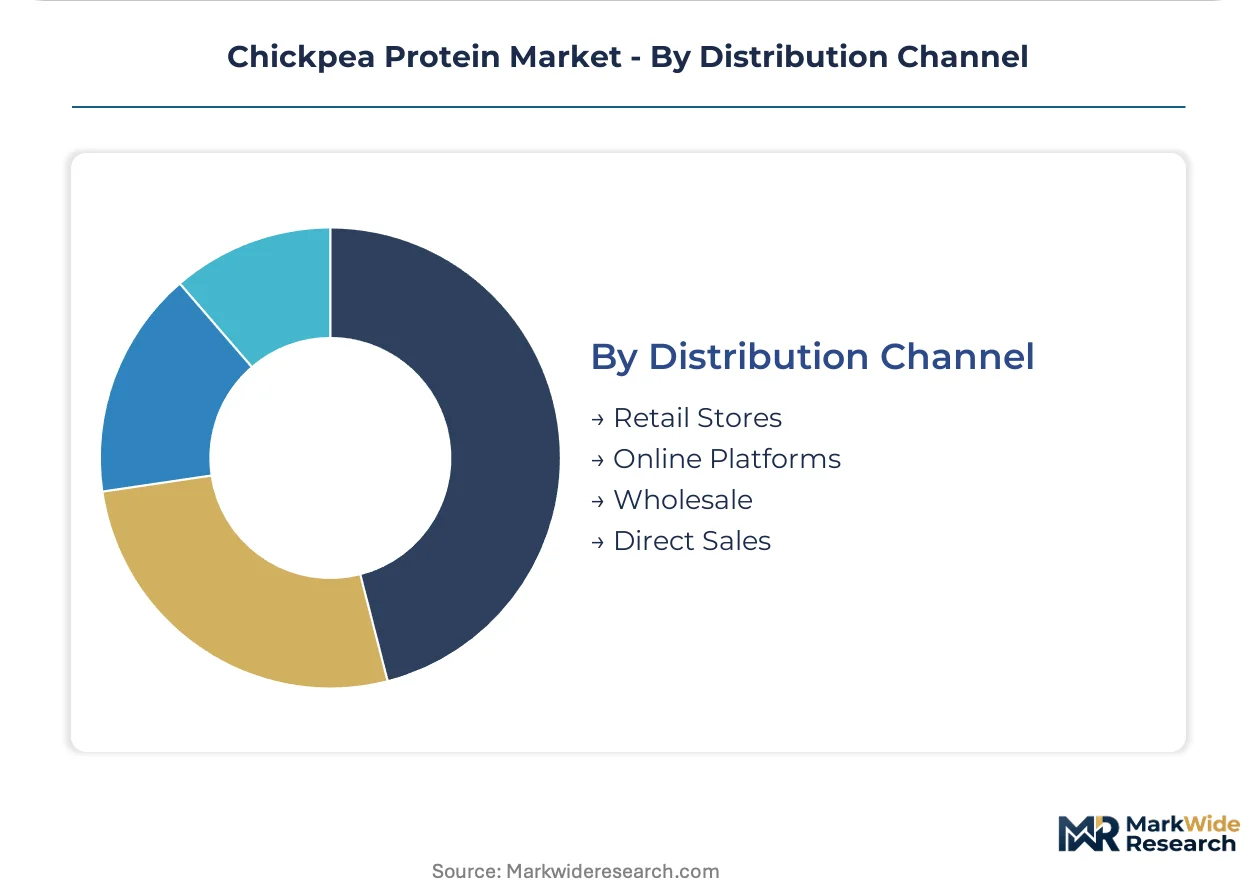
- Retail Stores:Mass-market protein powders and nutritional bars depend on shelf-space negotiations with consolidated grocery chains; private-label expansion compresses branded margins.
- Online Platforms:Direct-to-consumer subscriptions enable lot-level traceability marketing; subscription retention rates correlate with sustainability story transparency.
- Wholesale:Ingredient distributors serve mid-tier food manufacturers without ISO 22000 certification requirements; inventory pooling reduces working capital burdens for smaller processors.
- Direct Sales:Long-term offtake agreements between CPG brands and prairie processors displace traditional distributor networks in premium isolate segments.
Wholesale channels anchor volume throughput while direct sales capture the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for pulse value addition is accelerating isolate capacity buildouts in Gujarat and Rajasthan. Germany's EU Green Deal compliance deadlines compress formulation timelines for plant-based meat developers. Canada's prairie networks anchor premium isolate supply through Saskatchewan and Alberta processing corridors.
India
Gujarat and Rajasthan processing corridors absorb subsidized capital expenditure under the PLI scheme for pulse value addition. FSSAI fortification guidelines determine which domestic processors qualify for export-grade isolate expansion. Ahmedabad and Jaipur industrial zones witness capacity buildouts targeting European and North American CPG offtake agreements.
Germany
Plant-based meat formulators specify chickpea isolates to meet EU Green Deal protein diversification targets for 2030. EFSA novel food approval pathways require chronic toxicology studies that extend market entry timelines by 24-36 months. Cologne and Hamburg food technology clusters front-load dossier investments to secure first-mover positioning in institutional catering contracts.
Canada
Saskatchewan and Alberta prairie networks concentrate premium isolate production for North American sports nutrition companies. Health Canada and PMRA regulate mycotoxin thresholds and allergen segregation protocols. Regina and Calgary processing hubs negotiate long-term offtake agreements with direct-procurement CPG brands seeking lot traceability.
United States
FDA GRAS self-determination protocols create a separate compliance track for ingredient suppliers targeting domestic CPG brands. Athletes and vegan consumers in California and New York drive clean-label protein diversification away from soy-dominant portfolios. Chicago and Minneapolis distribution nodes witness channel compression as brands bypass traditional ingredient distributors.
Brazil
ANVISA regulatory harmonization with Codex standards opens clean-label protein diversification for athletic formulations in an underpenetrated sports nutrition sector. São Paulo and Rio de Janeiro metropolitan areas concentrate demand from health-conscious consumers seeking non-GMO verification. Local distributors face displacement pressure from direct-procurement relationships between global isolate producers and Brazilian CPG brands.
Chickpea Protein Market Vendor Landscape
Player mix skews toward integrated ingredient conglomerates with prairie sourcing networks and specialized isolate pure-plays with extrusion-ready formulations. Market structure exhibits moderate consolidation around ISO 22000-certified food-grade producers, with commodity flour traders occupying a distinct lower tier. Two strategic archetypes dominate: vertically integrated agricultural processors controlling upstream chickpea supply, and technology-licensing specialists partnering with precision fermentation platforms. Competitive moves center on direct-procurement relationship formation with CPG brands and membrane filtration infrastructure expansion for 90% protein isolate tiers.
Within the integrated processor archetype, AGT Food and Ingredients anchors Canadian prairie sourcing networks, while Archer Daniels Midland Company occupies a position spanning multiple plant protein categories. Among specialized pure-plays, ChickP Protein Ltd. and InnovoPro Ltd. exemplify the technology-driven tier focused on functional protein applications and egg-replacement formulations. These three companies represent the spectrum from scale-driven agricultural integration to R&D-intensive functional specialization.
| Leading Market Players |
|---|
| AGT Food and Ingredients |
| ChickP Protein Ltd. |
| Ingredion Inc. |
| Cambridge Commodities Ltd |
| PLT Health Solutions |
| Archer Daniels Midland Company |
| InnovoPro Ltd. |
| Nutriati, Inc. |
| Batory Foods |
| Others |
Supply Flow & Price Mechanics
Chickpea isolate substitution for soy protein in EU plant-based meat formulations simultaneously redraws procurement geography toward Saskatchewan prairie processors and compresses margin structures for commodity flour traders. This dual displacement concentrates pricing power among ISO 22000-certified isolate producers while forcing legacy distributors into volume-based defensive positioning.
Pricing Analysis
Certification level creates the primary spread between food-grade isolate premiums and commodity flour benchmarks. Three-tier pricing structure across premium isolates, standard concentrates, and economy flour grades anchors the market, with EU Green Deal compliance requirements widening the ISO 22000 premium. Cost compression in concentrate tiers is intensifying because membrane filtration infrastructure spreads among mid-tier processors. Food manufacturers exhibit the least price sensitivity due to traceability mandates, while institutional feeding programs absorb economy grades where fortification specifications permit.
Supply Chain Analysis
Inventory cycles for kabuli chickpea feedstock stretch 8-12 months from Canadian prairie harvest through Asian processing corridors, compressing working capital for traders. Supply concentrates in Canada, India, and Turkey, with Saskatchewan prairie networks anchoring premium isolate capacity and Gujarat processing corridors absorbing PLI-subsidized expansion. Raw material flows draw from Black Sea shipping routes, Canadian drought-exposed acreage, and Indian desi variety harvests. Single-source vulnerability in Saskatchewan isolate production creates concentration risk. Distribution runs through direct-procurement relationships displacing traditional ingredient distributors in premium tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU protein diversification mandates fragment procurement relationships, creating specialized niches for extrusion-ready concentrate developers and precision fermentation partners.
For Market Incumbents: Fortify Saskatchewan prairie sourcing networks through backward integration into kabuli chickpea acreage contracts, locking supply ahead of Black Sea volatility. Deepen ISO 22000 certification moats to repel commodity flour traders ascending into food-grade tiers. EFSA novel food dossier front-loading serves as the priority defensive lever against late-entrant formulation specialists. For New Entrants and Emerging Players: Lead with Brazil's ANVISA-regulated sports nutrition sector, where clean-label protein diversification lags European penetration by several years. Target precision fermentation partnerships for egg-replacement texture applications, leveraging chickpea hydrolysate functionality gaps. Direct-to-athlete subscription models bypass entrenched distributor relationships that block conventional wholesale entry. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors technology-licensing specialists over asset-heavy agricultural processors. Long-term viability hinges on functional protein application breadth rather than commodity scale. Acquisition targets should demonstrate extrusion rheology expertise and EFSA dossier progress. The signal to watch is ANVISA regulatory harmonization velocity, which would unlock Brazilian institutional capital flows.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Filtration Infrastructure Expansion | Ultrafiltration-diafiltration systems enable 90% protein isolate tiers for European meat analog specifications. |
| Precision Fermentation Partnership | Chickpea protein hydrolysate collaborations replicate egg-replacement textures in bakery applications. |
| Direct-Procurement Relationship Formation | Long-term offtake agreements with North American CPG brands displace traditional distributor networks. |
| EFSA Novel Food Dossier Investment | Chronic toxicology studies secure 24-36 month first-mover positioning in institutional catering contracts. |
| PLI Scheme Capacity Buildout | Subsidized capital expenditure in Gujarat and Rajasthan targets export-grade isolate expansion. |
Methodological Framework
Cross-validation between primary interviews with prairie processors and secondary trade data anchors the qualitative findings. Conversations with plant-based meat formulation chemists, pulse protein extraction engineers, EFSA regulatory consultants, and CPG procurement directors combined with customs records, FSSAI fortification guidelines, and EU Green Deal policy documents. Bottom-up capacity assessments and top-down protein transition demand models triangulate volume estimates.
Sensitivity analysis across kabuli chickpea price volatility scenarios and EFSA approval timeline distributions stress-tests the projection framework. Segmentation dimensions include extraction technology tier, end-use application, protein content specification, and regional regulatory cluster. CAGRs derive from compound growth trajectory fitting across the analysis window, with inputs from PLI scheme disbursement schedules and Black Sea shipping disruption frequencies.
The analysis sits within stated boundaries; outcomes outside sustained EU protein diversification policy commitment or severe Canadian prairie drought conditions would require recalibration. Forecasts reflect documented assumptions about regulatory harmonization velocity and membrane filtration yield improvements. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrogenated Palm Oil Market
Ingredients
Arachidonic Acid Market
Ingredients
Oat Ingredients Market
Ingredients
High Oleic Oil Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
Rose Hips Extract Market
Ingredients
Mineral Premix Market
Ingredients
Tryptose Market
Ingredients
Rice Starch Market
Ingredients
Milk Mineral Concentrate Market
Ingredients
Global Fruits and Vegetables Ingredients Market
Ingredients
Tannin Market
Ingredients
Baobab Ingredient Market
Ingredients
Olive Oil Market
Ingredients
Casein Hydrolysate Market
Ingredients
Rice Bran Oil Market