
 Non-GMO Oil Market | 2026-2036
Non-GMO Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Non-GMO Oil Market Analysis
Seed-crop agronomist availability is redrawing competitive boundaries in the Non-GMO Oil Market, as identity-preserved supply chains require specialized labor for segregation and testing. Cargill Inc. leverages its vertical grain handling infrastructure to maintain IP integrity from farm to refinery. EFKO Group anchors its position through sunflower oil specialization across Eastern European growing regions. NOW Foods competes via certified organic and non-GMO overlap in supplement-grade oil formulations.
Non-GMO oil denotes vegetable oils derived from crops developed without genetic engineering techniques, typically verified through PCR-based DNA testing showing absence of transgenic material below threshold limits, serving food manufacturers and retailers seeking clean-label positioning. Soybean oil retains volume leadership among product types due to its ubiquity in processed foods and biodiesel feedstock, though sunflower oil commands margin premiums in European retail channels. The food service application segment is maturing as large restaurant chains codify non-GMO procurement standards, while online distribution channels show structural expansion as direct-to-consumer oil brands bypass conventional wholesale markups.
The USDA oversees non-GMO verification through its Process Verified Program, while the EU enforces mandatory GMO labeling thresholds under Regulation (EC) No 1829/2003, compelling importers to maintain detailed chain-of-custody documentation. BIS in India is developing analogous standards for genetically unmodified food oils as export-oriented refining capacity expands. Stakeholders must monitor evolving detection methodologies and threshold harmonization between jurisdictions, as divergent regulatory baselines create compliance complexity for multinational oil traders.
Market Dynamics
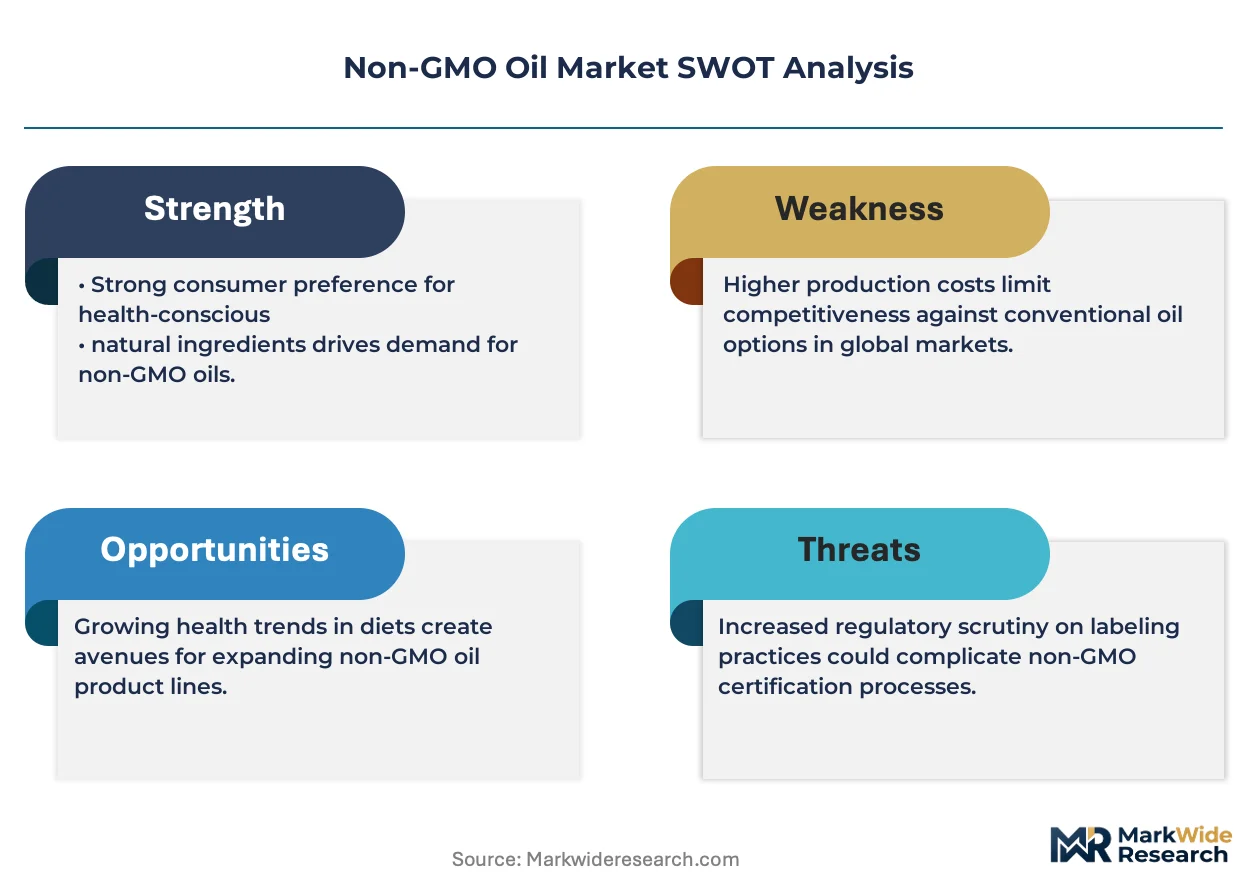
Identity-preserved supply chains for non-GMO oils require specialized agronomic labor and PCR testing infrastructure, creating bottlenecks that concentrate margin capture among vertically integrated handlers capable of farm-to-refinery traceability.
Growth Catalysts
- EU Green Deal Farm-to-Fork Strategy:Mandatory traceability protocols for genetically modified content compel food manufacturers to source verified non-GMO oils, tightening procurement standards across German retail chains and private-label cooking oil lines.
- Biodiesel feedstock diversification:Renewable fuel mandates in multiple jurisdictions designate non-GMO soybean oil as a qualifying feedstock, pulling volume through identity-preserved channels that command sustainability premiums.
- PCR-based DNA testing advancement:Detection thresholds below regulatory limits enable reliable verification at lower cost, expanding accessible certification to mid-tier oil refiners previously excluded from non-GMO positioning.
Market Restraints
- Seed-crop agronomist scarcity:Specialized labor for segregation and testing concentrates in Eastern European sunflower-growing regions, limiting expansion of identity-preserved acreage elsewhere.
- Input cost volatility:Non-GMO seed premiums and isolation distances raise farm-level production costs relative to commodity alternatives, compressing margins during commodity price troughs.
- Regulatory fragmentation:Divergent GMO labeling thresholds between USDA Process Verified Program and EU Regulation (EC) No 1829/2003 create compliance complexity for multinational traders.
Strategic Opportunities
- India export-oriented refining:BIS standards development for genetically unmodified food oils positions Indian refiners to capture European and North American demand as domestic crushing capacity expands.
- Direct-to-consumer channel emergence:Online distribution enables specialty oil brands to bypass wholesale markups, capturing margin through subscription models and clean-label storytelling.
- Organic-non-GMO overlap:Certified organic certification automatically satisfies non-GMO requirements, allowing supplement-grade oil formulators to serve dual-preference buyers with single verification.
Industry Challenges
- Chain-of-custody documentation burden:EU importers must maintain detailed records across multiple handlers, creating administrative overhead that disadvantages smaller traders lacking integrated IT systems.
- Detection methodology evolution:Stakeholders must monitor advancing PCR techniques and threshold harmonization negotiations between jurisdictions, requiring continuous compliance investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-GMO Oil Market |
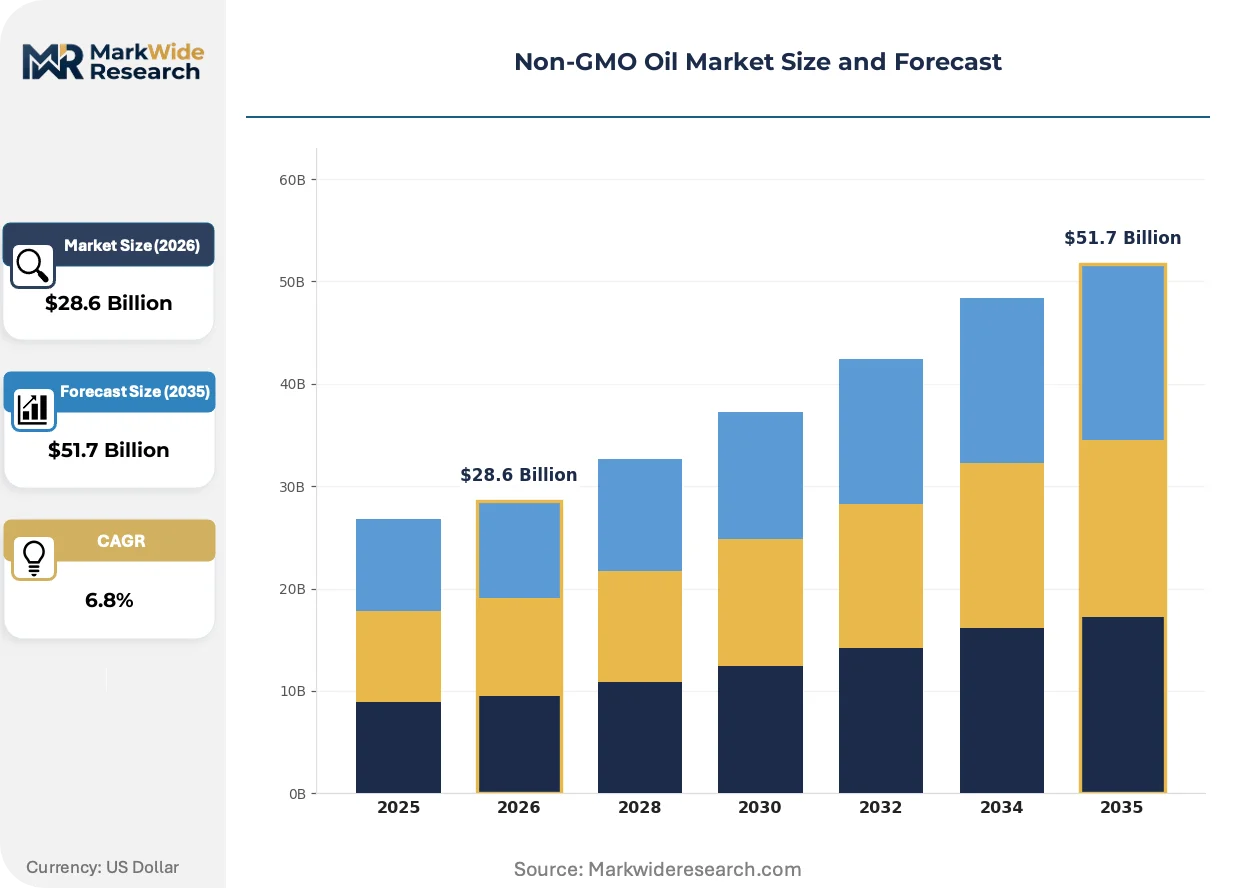
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Canola Oil, Sunflower Oil, Soybean Oil, Olive Oil Application: Cooking, Baking, Salad Dressings, Marinades Distribution Channel: Retail, Online, Wholesale, Food Service End User: Households, Restaurants, Food Manufacturers, Bakeries |
| Companies Covered | Cargill Inc., Chosen Foods LLC, Spectrum Organic Products LLC, Archer Daniels Midland Company, Bunge Limited, CHS Inc., EFKO Group, Nutiva, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-GMO Oil Market Emerging Trajectories
Digital traceability infrastructure and rapid genetic testing are compressing verification timelines while regulatory convergence pressures reshape competitive positioning across supply chain tiers.
Blockchain-enabled seed-to-bottle tracking is decomposing information asymmetries between farmers and end-buyers. Large restaurant chains now require real-time provenance data for codified non-GMO procurement standards. This transparency compression is enabling smaller regional crushers to compete for national accounts previously reserved for integrated agribusiness handlers.
REACH and associated EU chemical safety protocols are tightening purity specifications for processing aids used in oil refining. Refiners serving European markets must reformulate bleaching and deodorization chemistries to maintain non-GMO positioning. German retail chains have responded by tightening private-label supplier qualification protocols ahead of regulatory deadlines.
Clean-label preference is rotating demand toward single-origin and cold-pressed variants that command shelf-space premiums in premium grocery channels. Direct-to-consumer brands bypass conventional wholesale markups through subscription models. This channel disintermediation is most visible in North American urban markets where millennial household penetration for specialty oils exceeds conventional retail growth rates.
Non-GMO Oil Market Segmentation
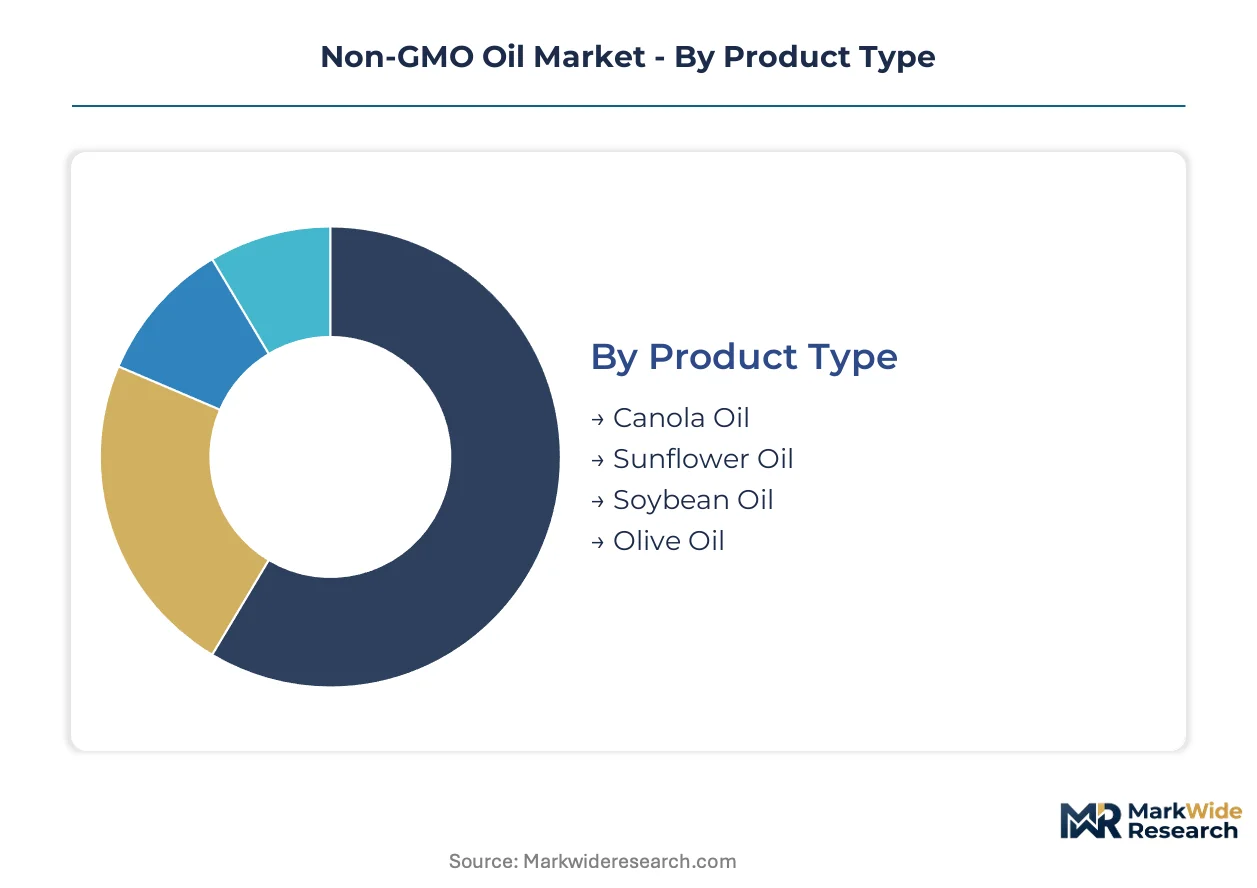
Non-GMO oil segmentation reflects divergent certification costs and traceability requirements across product categories. Substitution pressures vary sharply between commodity oils and specialty grades with distinct IP supply chain architectures.
Product Type:
Soybean oil faces the most acute substitution threat from conventional GMO varieties, squeezing margin capture for handlers lacking vertical grain infrastructure.
- Soybean Oil:Derived from identity-preserved non-GMO soybeans through PCR-verified supply chains. Food manufacturers in Germany and private-label retail chains in North America concentrate procurement here due to biodiesel feedstock qualification requirements under renewable fuel mandates.
- Sunflower Oil:Eastern European crushing corridors dominate output. EFKO Group anchors supply across Russian and Ukrainian growing regions, commanding margin premiums in European retail channels where clean-label positioning commands shelf-space allocation.
- Canola Oil:Canadian prairie production supplies North American food service channels with IP-verified seed lots.
- Olive Oil:Mediterranean basin origin provides automatic non-GMO status through traditional cultivation; Spanish and Italian cooperatives serve specialty retail tiers.
Soybean oil retains volume leadership; sunflower oil holds the steepest expansion curve.
Application:
Cost tier stratification separates commodity-scale industrial buyers from premium-positioned consumer segments with divergent price elasticity.
- Cooking:High-heat stability requirements favor refined oils with low free fatty acid content. German retail chains enforce strict private-label sourcing protocols here, driving consolidation among qualified suppliers.
- Baking:Functional fat properties determine substitution flexibility between non-GMO and conventional oils. Industrial bakeries in North America codify procurement standards as clean-label pressure intensifies.
- Salad Dressings:Cold-use applications favor cold-pressed and extra-virgin grades with flavor retention.
- Marinades:Flavor carrier functions tolerate broader oil specifications with lower certification premiums.
Cooking applications dominate volume throughput; salad dressings are climbing fastest on premiumization.
Distribution Channel:
Customer type fragmentation separates price-sensitive institutional buyers from direct-to-consumer brands capturing margin through subscription models.
- Retail:Supermarket and hypermarket shelf placement requires chain-of-custody documentation compliant with EU Regulation (EC) No 1829/2003. NOW Foods and comparable brands compete via certified organic overlap in supplement-grade formulations.
- Online:Direct-to-consumer platforms enable specialty oil brands to bypass wholesale markups. Millennial household penetration in North American urban markets exceeds conventional retail growth rates here.
- Wholesale:Bulk volume flows through integrated agribusiness handlers with farm-to-refinery traceability systems.
- Food Service:Large restaurant chains now codify non-GMO procurement standards, maturing this segment as national accounts consolidate supplier bases.
Retail channels maintain volume dominance; online distribution is gaining share fastest on channel disintermediation.
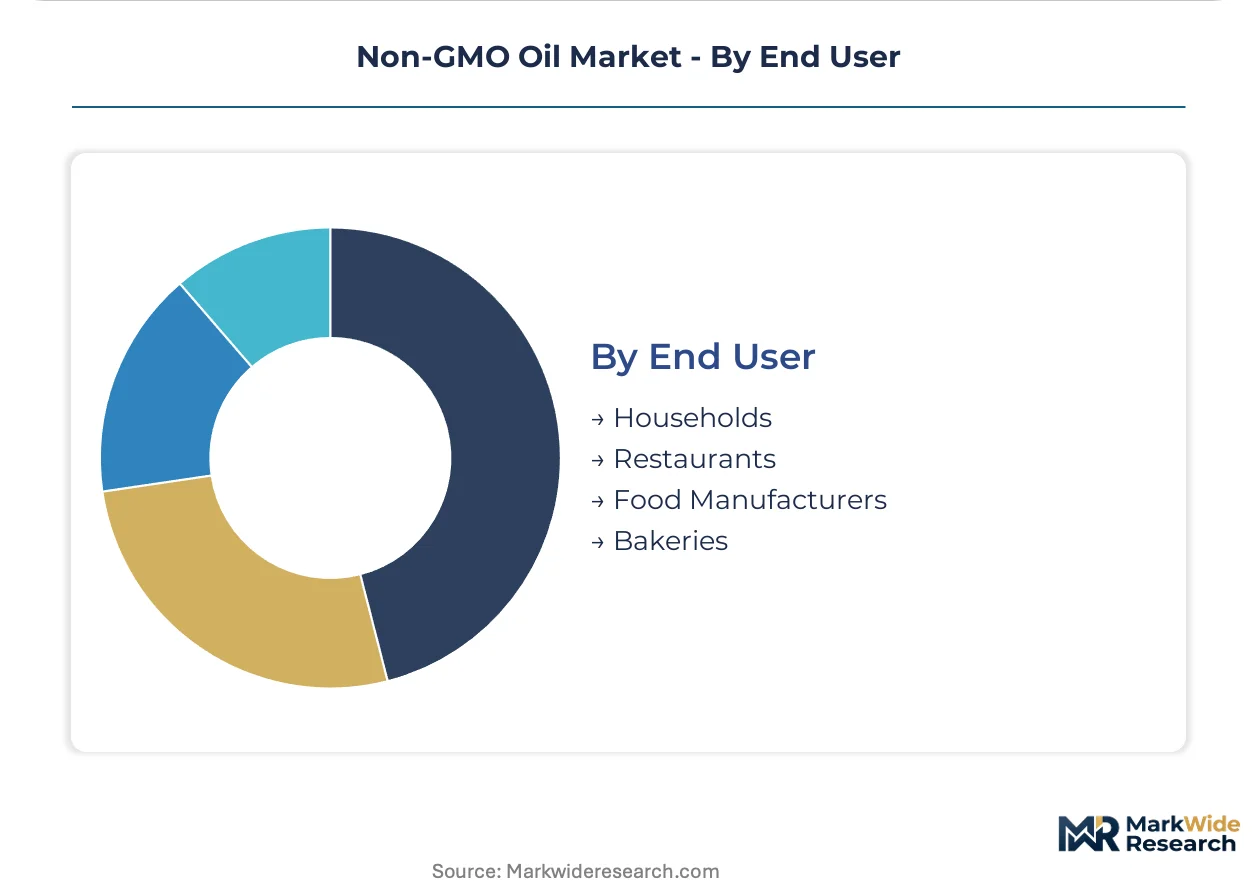
End User:
Supply concentration patterns favor vertically integrated handlers serving multinational food manufacturers over fragmented household demand.
- Food Manufacturers:Processed food and snack producers require consistent IP-verified supply with USDA Process Verified Program documentation. Cargill Inc. leverages its grain handling infrastructure to serve this tier with farm-to-refinery integrity.
- Restaurants:Chain operators with codified procurement standards pull volume through approved supplier networks with real-time provenance data.
- Households:Urban consumer segments in Germany and North America drive clean-label preference rotation toward single-origin and cold-pressed variants.
- Bakeries:Regional artisan and industrial operations represent fragmented demand with variable certification requirements.
Food manufacturers command the largest volume share; restaurants are expanding most quickly on procurement standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA traceability mandates under the EU Green Deal Farm-to-Fork strategy anchor European procurement standards, while USDA Process Verified Program documentation governs North American supply chains. Divergent GMO labeling thresholds between jurisdictions create compliance complexity for multinational oil traders serving multiple geographies simultaneously.
Germany
German retail chains enforce strict private-label sourcing protocols for cooking oils, driving consolidation among qualified suppliers. The EU Green Deal mandates detailed chain-of-custody documentation for genetically modified content below regulatory thresholds. The Hamburg-Bremen port cluster serves as the primary entry point for identity-preserved sunflower oil shipments from Eastern European crushing corridors.
United States
Food manufacturers expand procurement of non-GMO oils for clean-label product lines across processed food and snack categories. USDA Process Verified Program oversight requires PCR-based DNA testing documentation for farm-to-refinery traceability. The Midwest grain belt concentrates soybean crushing capacity, with Illinois and Iowa handling substantial identity-preserved volume for biodiesel feedstock qualification.
India
BIS standards development for genetically unmodified food oils positions domestic refiners to capture European and North American export demand. The central bank's trade finance protocols support expanding crushing capacity in Gujarat and Maharashtra. The Kandla-Mundra port corridor on the western coast enables bulk shipment of refined non-GMO oils to EU markets requiring Regulation (EC) No 1829/2003 compliance.
Canada
Canola oil production across the prairie provinces supplies North American food service channels with IP-verified seed lots. Health Canada maintains alignment with USDA verification protocols while monitoring EU threshold harmonization negotiations. The Saskatchewan-Alberta growing region concentrates identity-preserved acreage for crushers serving multinational restaurant chains with codified procurement standards.
Ukraine
Eastern European sunflower-growing regions dominate output for margin-premium European retail channels. EFKO Group anchors supply across Russian and Ukrainian growing regions with specialized agronomic labor for segregation and testing. The Black Sea port infrastructure enables bulk export of identity-preserved sunflower oil to German retail chains with strict non-GMO sourcing protocols.
Non-GMO Oil Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Non-GMO Oil Market. Vertically integrated agribusiness handlers capture margin through farm-to-refinery traceability systems that smaller traders cannot replicate. Three archetypes dominate: multinational grain handlers with captive oilseed infrastructure, regional crushers with geographic specialization, and direct-to-consumer brands leveraging subscription models. Competitive moves concentrate on backward integration into identity-preserved seed sourcing and geographic expansion into BIS-regulated Indian export corridors.
Among integrated agribusiness handlers, Cargill Inc. and Archer Daniels Midland Company occupy positions exemplifying vertical grain handling infrastructure. EFKO Group represents the regional specialist archetype with Eastern European sunflower oil concentration. NOW Foods sits within the direct-to-consumer tier, serving supplement-grade formulations where certified organic overlap satisfies dual-preference buyers.
| Leading Market Players |
|---|
| Cargill Inc. |
| Chosen Foods LLC |
| Spectrum Organic Products LLC |
| Archer Daniels Midland Company |
| Bunge Limited |
| CHS Inc. |
| EFKO Group |
| Nutiva |
| NOW Foods |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German retail chains and Eastern European crushers lock in supply access and price visibility for identity-preserved sunflower oil, insulating qualified suppliers from spot market volatility while compressing margins for handlers lacking farm-to-refinery traceability systems.
Pricing Analysis
Price spreads between Ukrainian-origin sunflower oil and commodity soybean alternatives widen during EU harvest shortfalls, reflecting supply scarcity in identity-preserved channels. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification stringency and volume commitment. Cost compression in the standard tier intensifies because mid-tier refiners face PCR testing infrastructure investments. Food manufacturers show highest price sensitivity due to thin formulation margins, while direct-to-consumer brands absorb premiums through subscription stickiness.
Supply Chain Analysis
Black Sea port congestion periodically chokes identity-preserved sunflower oil flows to Hamburg-Bremen, forcing German buyers into secondary sourcing from Argentine crushers. Supply concentrates in Ukraine, Russia, and Argentina for sunflower; the US Midwest and Brazil for non-GMO soybeans. Crushing capacity draws from specialized seed-crop agronomists, PCR testing laboratories, and IP-certified storage silos. Single-source vulnerability runs through Eastern European sunflower corridors where geopolitical disruption threatens European retail supply. Distribution runs through integrated agribusiness handlers with captive grain elevators and refinery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Non-GMO Oil Market rewards handlers with scarce capabilities in identity-preserved agronomy and chain-of-custody documentation, creating moats that commodity traders cannot easily cross.
For Market Incumbents: Compound traceability investments by backward integration into certified seed multiplication programs across Eastern European growing regions, defending against regional crushers with emerging PCR capabilities. Prioritize channel control through exclusive supply agreements with German retail chains facing EU Green Deal compliance deadlines. For New Entrants and Emerging Players: Real-time provenance data services represent an under-served layer where incumbent handlers rely on legacy documentation systems. Penetrate the North American direct-to-consumer segment through subscription-based specialty oil brands targeting millennial households in urban corridors. Deploy blockchain-enabled seed-to-bottle tracking as a differentiated go-to-market anchor. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated handlers with captive agronomic labor pools. Long-term viability hinges on regulatory threshold harmonization between USDA and EU protocols. Acquisition targets include regional crushers with Eastern European sunflower specialization and established BIS documentation for Indian export corridors. Watch for PCR testing cost curves as the inflection signal enabling mid-tier refiner market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Seed Programs | Cargill and ADM secure IP integrity from farm origination through captive multiplication networks. |
| Blockchain-Enabled Provenance Tracking | Restaurant chains with codified procurement standards demand real-time data previously reserved for integrated handlers. |
| Direct-to-Consumer Channel Launch | Specialty brands bypass wholesale markups through subscription models targeting North American urban millennials. |
| PCR Testing Infrastructure Investment | Mid-tier refiners gain certification access as detection thresholds drop below regulatory limits. |
| BIS Compliance Documentation Buildout | Indian refiners position for European export demand through genetically unmodified oil standards alignment. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with seed-crop agronomists, crushing facility managers, retail procurement directors, and regulatory compliance officers; and secondary validation through USDA Process Verified Program filings, EU Regulation documentation, BIS standard development records, and trade flow customs data. Bottom-up volume estimates from identity-preserved acreage and crushing capacity were triangulated against top-down demand aggregation from food manufacturer procurement disclosures.
Across the analysis window, forecasts model product type segmentation by oil source, application tier by heat stability requirements, distribution channel by customer type fragmentation, and end-user concentration patterns. CAGRs derive from supply-demand balance projections incorporating biodiesel mandate expansion, EU Farm-to-Fork traceability implementation timelines, and Indian refining capacity buildout curves. Industry-specific inputs include seed premium volatility, PCR testing cost trajectories, and port infrastructure utilization rates.
Underlying assumptions cover sustained EU Green Deal enforcement, stable Black Sea export corridor access, and gradual BIS-EU regulatory alignment, with deviation risk concentrated in geopolitical disruption to Ukrainian sunflower supply and threshold harmonization negotiation delays. Practitioners should keep alternative scenarios live as detection methodology advances and jurisdiction-specific compliance requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Asia Pacific Vegetable Oil Market
Ingredients
Plant Based Thickener Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Modified Soya Flour Market
Ingredients
Sea Salt Market
Ingredients
Bleached Flour Market
Ingredients
Seaweed Extracts Market
Ingredients
China Corn Glucose Market
Ingredients
North America Feed Yeast Market
Ingredients
Beef Concentrate Market
Ingredients
Bouillon Cubes Market
Ingredients
Soybean Meal Market
Ingredients
Fruit Powder Market
Ingredients
Sodium Caseinate Market
Ingredients
Europe Corn Glucose Market
Ingredients
Textured Soy Flour Market