
 Europe Newborn Screening Market | 2026-2036
Europe Newborn Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Newborn Screening Market Insights
Mass spectrometry-based multiplex testing is rewriting how European laboratories process dried blood spot panels, collapsing turnaround times from days to hours while expanding detectable disorder counts. Thermo Fisher Scientific leverages its instrument-platform dominance to anchor high-throughput screening contracts with national health services. PerkinElmer specializes in integrated assay-reagent workflows that reduce calibration drift across decentralized lab networks. Bio-Rad Laboratories competes through electrophoresis quality-control systems that sustain compliance with EMA post-market surveillance requirements.
Europe newborn screening comprises systematic biochemical, genetic, and audiological assessment of infants within 48-72 hours of birth, typically via heel-prick blood collection on filter paper cards analyzed through tandem mass spectrometry with cutoff thresholds measured in micromoles per liter. Blood spot screening occupies the largest volume share due to mandatory metabolic panel inclusion in nearly all European national programs, while genetic screening represents the fastest-expanding category as next-generation sequencing costs decline and rare-disease databases mature. Public health agencies command the dominant procurement channel, though diagnostic laboratories capture margin pools through specialized confirmatory testing and data management services.
EMA medical device oversight, EU Green Deal sustainable procurement mandates, and REACH chemical safety standards collectively shape reagent formulations, instrument disposal protocols, and supplier qualification criteria across member states. The MDR transition has forced manufacturers to rebuild technical documentation and clinical evidence packages, lengthening certification timelines and raising barriers for non-established entrants. Stakeholders must monitor how the proposed European Health Data Space regulation reshapes cross-border screening data sharing and algorithm validation requirements for AI-assisted disorder detection.
Market Dynamics
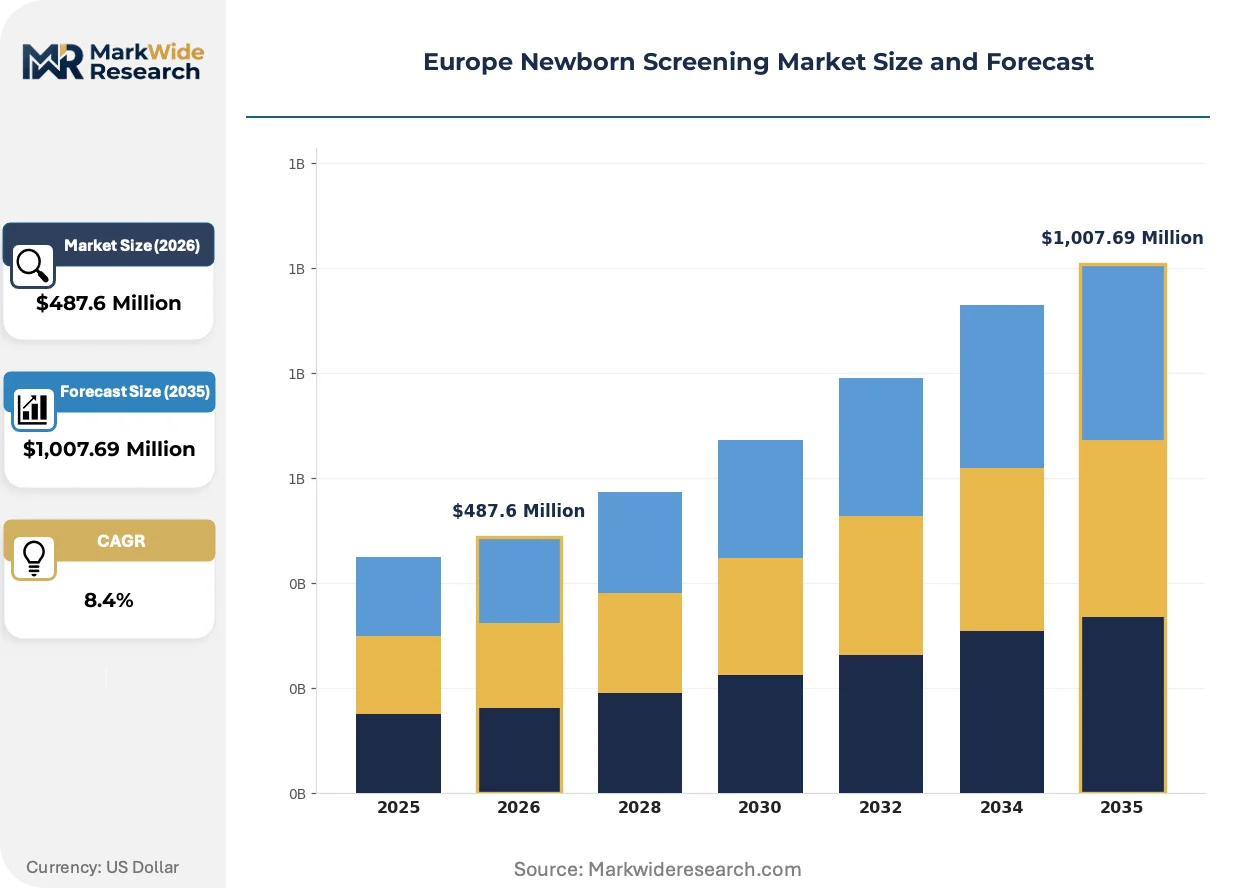
MDR certification timelines and REACH chemical safety mandates are compressing supplier qualification windows while national health services consolidate procurement around fewer high-throughput platform vendors. This regulatory squeeze favors established instrument manufacturers with pre-built clinical evidence packages.
Growth Catalysts
- EU Green Deal procurement mandates:Sustainable reagent formulations and instrument disposal protocols now carry weighted scoring in French and German national tender evaluations, tilting awards toward suppliers with circular economy certifications.
- Next-generation sequencing cost curves:Declining per-sample sequencing economics enable expanded genetic panel inclusion in Spanish and Italian regional screening programs previously limited to metabolic assays.
- Centralized laboratory networks:Denmark and the Netherlands have consolidated newborn screening into single national reference laboratories, creating volume concentration that justifies automation capital deployment.
Market Restraints
- Helium supply volatility:Mass spectrometry instruments depend on helium carrier gas where Russian supply disruptions have destabilized European pricing and availability.
- MDR technical documentation burdens:The transition from MDD to MDR has extended certification timelines for tandem mass spectrometry accessories, freezing product iterations for 18-24 month windows.
- Substitute platform emergence:Point-of-care genetic analyzers threaten to displace centralized laboratory workflows for secondary confirmatory testing in outpatient pediatric settings.
Strategic Opportunities
- Eastern European program expansion:Poland, Romania, and Bulgaria maintain partial coverage gaps for inherited metabolic disorders, creating first-mover advantage for platform vendors offering turnkey program implementation.
- AI-assisted disorder detection:Machine learning algorithms applied to spectral pattern recognition can expand detectable analyte panels without hardware replacement, opening software-as-a-service revenue streams.
- Cross-border data sharing architecture:The proposed European Health Data Space regulation will enable pooled rare-disease databases across member states, improving algorithm training sets and diagnostic accuracy.
Industry Challenges
- Specialized technician scarcity:Tandem mass spectrometry operation and maintenance require analytical chemistry expertise that national laboratory networks struggle to recruit and retain outside capital cities.
- Legacy LIS integration friction:Hospital information systems in France and Italy operate on decades-old architectures that resist API-based connectivity with modern screening data management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Newborn Screening Market |
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,007.69 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Spot Screening, Hearing Screening, Genetic Screening, Metabolic Screening End User: Hospitals, Pediatric Clinics, Diagnostic Laboratories, Public Health Agencies Technology: Mass Spectrometry, Immunoassay, PCR, Electrophoresis Application: Initial Screening, Follow-Up Testing, Carrier Screening, Diagnostic Testing |
| Companies Covered | Thermo Fisher Scientific Inc., PerkinElmer, Inc., Natus Medical Incorporated, General Electric, Medtronic, Bio-Rad Laboratories, Inc., Demant A/S, Covidien, Siemens Healthineers, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Newborn Screening Market Trends and Innovations
Digital pathology interfaces and cloud-based spectral libraries are collapsing the distance between collection sites and diagnostic expertise. Three developments merit particular attention.
Tandem mass spectrometry platforms equipped with automated sample prep robotics are digitizing the entire dried blood spot workflow from card receipt to result reporting. National reference laboratories in Sweden and Belgium have adopted these integrated systems, eliminating manual pipetting stages and reducing technician headcount requirements by half. The digitization of analytical protocols enables real-time quality monitoring and remote troubleshooting by instrument manufacturers.
MDR post-market surveillance requirements now mandate systematic vigilance reporting for all in-vitro diagnostic devices used in newborn screening, including trend analysis of false-positive and false-negative rates. German and French competent authorities have begun requesting annual periodic safety update reports that aggregate performance data across installed instrument fleets. Small reagent suppliers lacking dedicated regulatory affairs functions face outsourcing costs that erode margin structures.
Public procurement offices in the United Kingdom and Netherlands have moved from capital purchase models toward multi-year reagent rental agreements with guaranteed throughput commitments. National health services lock in predictable per-test costs while suppliers secure volume visibility and captive consumable revenue. This arrangement concentrates in markets where single vendors dominate installed instrument bases.
Europe Newborn Screening Market Segmentation
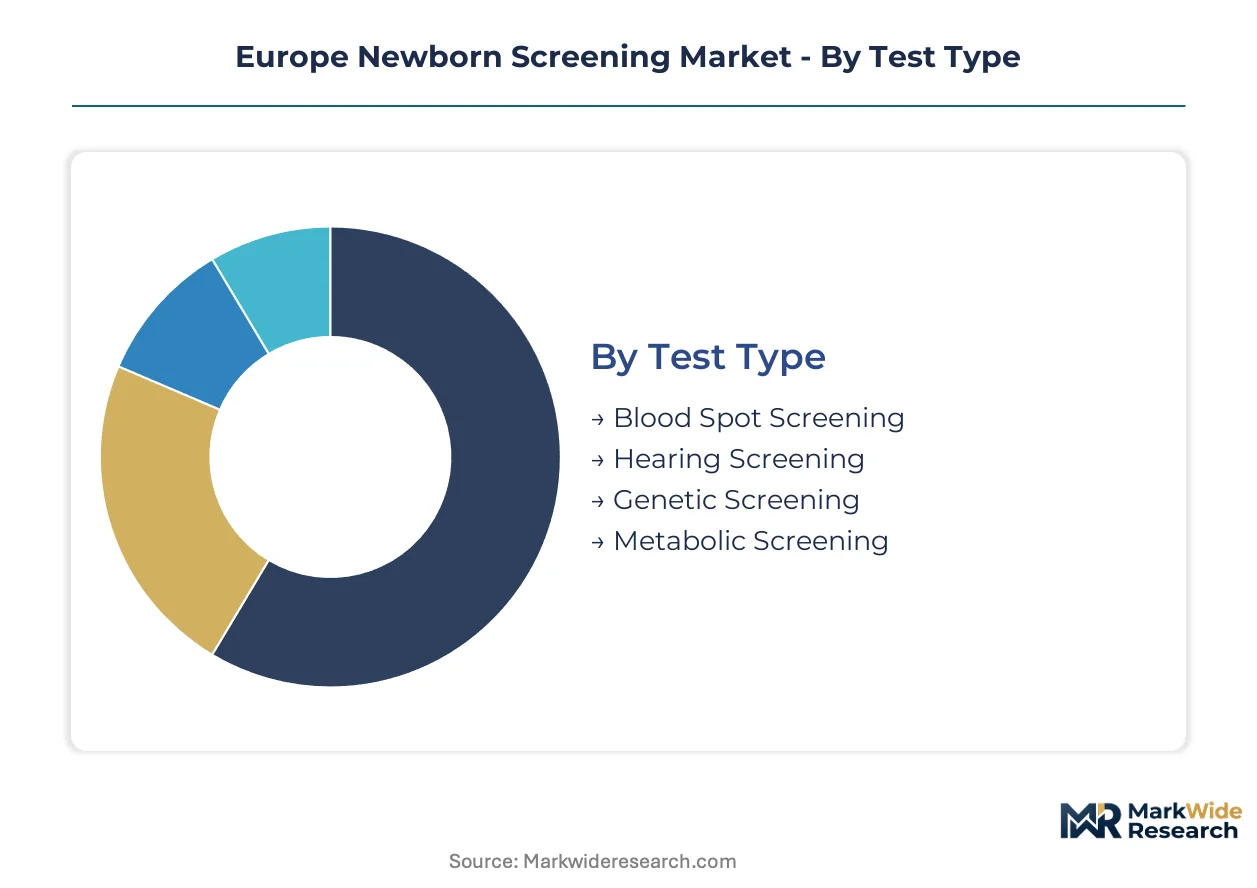
Segmentation of the Europe newborn screening market reveals how procurement concentration, technology substitution, and regulatory compliance reshape competitive positioning across distinct customer workflows and disorder detection methodologies.
Test Type:
Use-case spectrum spans mandatory metabolic panels, audiological assessment, and expanding genetic panels across national program mandates.
- Blood Spot Screening:Heel-prick dried blood spot collection on filter paper cards analyzed through tandem mass spectrometry remains the backbone of every European national program. Germany and France mandate 20+ analyte panels through centralized reference laboratories, creating volume concentration that justifies high-throughput automation capital.
- Genetic Screening:Next-generation sequencing panels detect cystic fibrosis, sickle cell disease, and spinal muscular atrophy with declining per-sample economics. Spain and Italy are expanding genetic inclusion in regional programs previously limited to metabolic assays, climbing the fastest among test categories.
- Hearing Screening:Automated otoacoustic emission testing occurs before hospital discharge, with Denmark and Sweden achieving near-universal coverage through midwife-administered protocols.
- Metabolic Screening:Tandem mass spectrometry quantifies amino acid and acylcarnitine profiles against micromolar-per-liter cutoff thresholds established by EQA providers.
Established volume favors blood spot screening; emerging adoption favors genetic screening.
End User:
Customer type determines procurement channel, margin structure, and compliance burden across divergent organizational capabilities.
- Public Health Agencies:National ministries and regional health authorities command dominant procurement through multi-year tender frameworks. The Netherlands and Denmark have consolidated screening into single national reference laboratories, creating captive volume for platform vendors.
- Diagnostic Laboratories:Specialized confirmatory testing and data management services capture margin pools through EQA participation and algorithm development. Private laboratory networks in Germany compete for secondary testing contracts.
- Hospitals:Maternity units perform initial sample collection and hearing screening, with reimbursement tied to DRG codes in France and England.
- Pediatric Clinics:Outpatient settings handle follow-up confirmatory testing and family counseling, particularly for positive screens requiring specialist referral.
Procurement concentration favors public health agencies; service margin depth favors diagnostic laboratories.
Technology:
Platform selection hinges on analyte multiplexing capability, throughput requirements, and MDR certification status.
- Mass Spectrometry:Tandem MS platforms equipped with automated sample prep robotics digitize entire dried blood spot workflows. Swedish and Belgian national laboratories have adopted these integrated systems, eliminating manual pipetting stages.
- PCR:Polymerase chain reaction enables targeted genetic variant detection with faster turnaround than sequencing for high-priority disorders. Italian regional programs deploy PCR for cystic fibrosis screening.
- Immunoassay:Enzyme-linked immunosorbent assays serve as backup confirmatory methods where mass spectrometry infrastructure is unavailable.
- Electrophoresis:Capillary electrophoresis quality-control systems sustain compliance with EMA post-market surveillance requirements for hemoglobinopathies.
Throughput scalability favors mass spectrometry; speed-to-result favors PCR.
Application:
Workflow stage determines sample volume, reimbursement rate, and regulatory scrutiny intensity.
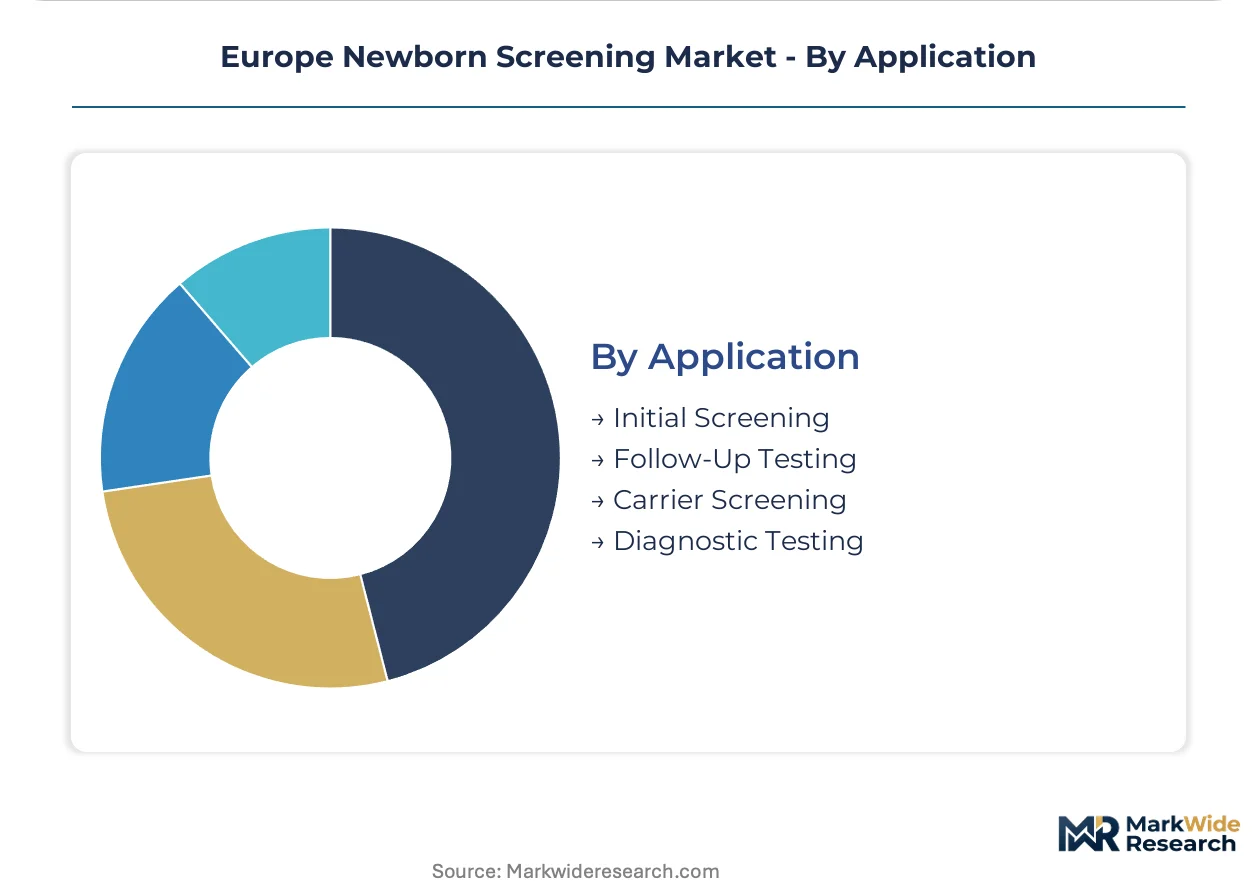
- Initial Screening:Population-wide testing of every newborn within 48-72 hours generates highest sample volumes at lowest per-test reimbursement. French and German national programs process 700,000+ annual samples through centralized pipelines.
- Follow-Up Testing:Secondary confirmatory testing of positive screens commands premium pricing and requires genetic counseling infrastructure. Diagnostic laboratories in England specialize in this high-margin segment.
- Diagnostic Testing:Symptomatic infants outside standard screening windows undergo extended metabolic or genetic panels.
- Carrier Screening:Family cascade testing of parents and siblings expands detectable at-risk pregnancies in subsequent births.
Volume concentration favors initial screening; margin per sample favors follow-up testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe newborn screening equipment and reagents flow primarily from German and Swiss manufacturing clusters toward Eastern European program expansions, with limited intra-regional trade in specialized consumables. Import dependency concentrates on helium carrier gas and certain reference standards, while export strength sits with mass spectrometry platforms and automated sample handling systems.
Germany
The Federal Joint Committee mandates 20+ analyte metabolic panels through centralized reference laboratories in Heidelberg and Berlin. MDR certification requirements under BfArM oversight have extended device approval timelines, favoring established manufacturers with pre-built technical documentation. Bavarian instrument clusters around Munich supply high-throughput tandem MS platforms to Dutch and Scandinavian national programs.
France
ANSM regulates screening program expansion under national health insurance reimbursement codes that cover universal newborn panels. The EU Green Deal sustainable procurement mandates now weight circular economy certifications in national tender evaluations. Greater Paris laboratory networks process 700,000+ annual samples through automated dried blood spot workflows.
United Kingdom
NHS England operates the NHS Newborn Blood Spot Screening Programme with 13-laboratory network coverage across England. MHRA post-market surveillance requirements align with MDR transition timelines, freezing certain product iterations. London-based diagnostic laboratories specialize in high-margin confirmatory testing and genetic counseling services for positive screens.
Netherlands
The National Institute for Public Health and the Environment consolidated all newborn screening into a single national reference laboratory in Bilthoven. REACH chemical safety standards shape reagent formulation requirements for Dutch tenders. Randstad procurement offices have shifted from capital purchase models toward multi-year reagent rental agreements with throughput guarantees.
Poland
Partial coverage gaps for inherited metabolic disorders persist in regional health programs outside Warsaw and Kraków. EU structural funds support laboratory infrastructure modernization in preparation for expanded panel inclusion. Polish health agencies represent first-mover opportunities for platform vendors offering turnkey program implementation with training and quality assurance packages.
Europe Newborn Screening Market Competitive Landscape
On the supply side, the industry is consolidating around instrument-platform vendors with MDR-certified product portfolios and captive consumable revenue streams. National health service procurement favors fewer high-throughput suppliers capable of multi-year service commitments. Three archetypes dominate: diversified life science conglomerates with screening divisions, specialized diagnostic reagent manufacturers, and hearing screening device specialists. Competitive dynamics center on MDR certification speed and multi-year reagent rental contract capture.
Among diversified laboratory technology providers, Thermo Fisher Scientific Inc. and PerkinElmer, Inc. occupy positions anchoring the high-throughput platform segment, while Bio-Rad Laboratories, Inc. exemplifies the quality-control and electrophoresis specialization archetype. These entities represent the established vendor base that national reference laboratories in Germany, France, and the Netherlands have consolidated procurement around. Siemens Healthineers and General Electric sit within broader healthcare technology portfolios where newborn screening constitutes a targeted application vertical rather than core revenue concentration.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| PerkinElmer, Inc. |
| Natus Medical Incorporated |
| General Electric |
| Medtronic |
| Bio-Rad Laboratories, Inc. |
| Demant A/S |
| Covidien |
| Siemens Healthineers |
| Others |
Pricing and Supply Chain Analysis
Helium supply volatility from Russian export disruptions determines both the pricing tier spreads across mass spectrometry platforms and the supply chain shape favoring vendors with captive gas reserves or alternative carrier technologies. Procurement offices in France and Germany now weight total cost of ownership metrics that incorporate helium security alongside instrument capital outlay.
Pricing Analysis
Technology-generation pricing gaps separate current-gen tandem MS platforms with automated robotics from prior-gen manual systems and next-gen AI-integrated spectrometry. Three-tier pricing structure across premium, standard, and economy levels reflects MDR certification status, throughput capacity, and bundled service contracts. Cost compression in economy-tier reagent rentals is intensifying because REACH compliance adds formulation overhead. Public health agencies in the Netherlands and Denmark exhibit lowest price sensitivity due to consolidated national laboratory structures, while regional hospitals in Poland and Romania face acute capital constraints.
Supply Chain Analysis
Tariff exposure between Germany and Eastern European member states dominates supply chain risk planning for instrument manufacturers serving Polish and Romanian program expansions. Manufacturing concentration sits in Bavarian clusters around Munich, Swiss precision component producers, and Danish automation subsystem specialists. Raw material dependencies include helium carrier gas, rare-earth magnets for mass analyzer assemblies, and specialized filter paper substrates. Single-source vulnerability concentrates in Russian helium supply channels. Distribution runs through national tender frameworks with multi-year reagent rental commitments replacing capital purchase models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where reagent rental agreements and remote maintenance contracts expand faster than hardware replacement cycles, with software-as-a-service layers for AI-assisted disorder detection representing the fastest-growing recurring revenue stream.
For Market Incumbents: Entrench platform dominance through MDR certification speed and captive consumable lock-in. Accelerate backward integration into helium recycling systems to neutralize supply volatility. Defend against point-of-care genetic analyzer substitution by embedding predictive maintenance algorithms that reduce technician headcount requirements for national reference laboratories. For New Entrants and Emerging Players: Pursue turnkey program implementation contracts in Poland, Romania, and Bulgaria where partial coverage gaps for inherited metabolic disorders create first-mover windows. Target regional health authorities with bundled training and quality assurance packages that incumbent vendors lack flexibility to match. Lead with AI-assisted spectral pattern recognition software that expands detectable analyte panels without requiring hardware displacement. For Investors and Strategic Acquirers: Specialized diagnostic reagent manufacturers with REACH-compliant formulation capabilities and dedicated regulatory affairs functions represent the most defensible acquisition archetype. Long-term viability hinges on the European Health Data Space regulation enabling pooled rare-disease databases that improve algorithm training sets. Watch MDR periodic safety update report aggregation capabilities as the inflection indicator separating scalable platform vendors from margin-eroded reagent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | MDR certification timelines determine vendor eligibility for French and German national tenders. |
| Hospital System Partnership | NHS England's 13-laboratory network creates volume concentration for integrated platform vendors. |
| Software Companion Development | AI-assisted disorder detection opens SaaS revenue streams without hardware replacement cycles. |
| Reimbursement Strategy | ANSM reimbursement code expansion in France enables genetic panel inclusion in universal coverage. |
| Reagent Rental Agreement Capture | Dutch and British procurement offices lock in predictable per-test costs through multi-year throughput guarantees. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EMA medical device registrations, national health service tender databases, and REACH chemical safety filings. Interviews with reference laboratory directors, biomedical engineers at national screening programs, regulatory affairs specialists, and GPO contracts managers informed operational assumptions. Secondary validation drew from BfArM device approvals, ANSM reimbursement bulletins, and EQA provider performance aggregations. Bottom-up instrument installation counts and top-down health expenditure allocations were triangulated to anchor market sizing.
Forecast inputs incorporate test volume projections by national birth cohorts, technology substitution curves for next-generation sequencing adoption, and MDR transition timeline impacts on product iteration cycles. Segmentation dimensions span test type, end user procurement channel, technology platform, and application workflow stage. CAGRs were derived from regression analysis of historical panel expansion rates and per-test cost trajectories across the analysis window. Model sensitivity parameters include helium price volatility bands and Eastern European program expansion acceleration scenarios.
Macroeconomic conditions sit as an overlay; deviation in EU structural fund disbursement timing or national health budget austerity measures would shift the trajectory for Eastern European infrastructure buildouts. Forecasts reflect assumptions about regulatory stability and supply chain continuity that continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Drug Screening Laboratory Service Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Adiponectin Testing Market
Testing Services
Syphilis Testing Market
Testing Services
Europe Esoteric Testing Market
Testing Services
Rapid Sterility Testing Market
Testing Services
Calprotectin Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Global Legionella Testing Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
United States Esoteric Testing Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Phenytoin Testing Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Europe Antimicrobial Susceptibility Testing Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market