
 Neuro-Auto-Immune Disease Diagnostics Market | 2026-2036
Neuro-Auto-Immune Disease Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Neuro-Auto-Immune Disease Diagnostics Market Foresight
Hospital laboratories is unwinding reliance on centralized reference labs as health systems build in-house neuro-auto-immune testing capacity. Roche Diagnostics leverages its installed base of immunoassay analyzers to anchor hospital accounts. Thermo Fisher Scientific sustains R&D intensity across mass spectrometry platforms for biomarker discovery. Siemens Healthineers competes through imaging-integrated diagnostic workflows that span detection to monitoring.
Neuro-auto-immune disease diagnostics encompasses laboratory and imaging methodologies that detect antibody-mediated, paraneoplastic, and inflammatory neurological disorders through serum biomarker quantification, tissue-based assays, and advanced neuroimaging protocols. ELISA and mass spectrometry technologies dominate current clinical throughput, with microarrays gaining adoption for multiplexed antibody profiling where simultaneous screening of multiple neural antigens reduces time-to-diagnosis. Biomarker segments command premium positioning due to proprietary antibody specificity requirements, while diagnostic kits standardize assay execution across hospital laboratories seeking workflow efficiency.
FDA premarket review shapes assay validation requirements for novel neural autoantibody tests, directly influencing commercialization timelines and clinical adoption curves. EMA's In Vitro Diagnostic Regulation imposes post-market surveillance obligations that elevate quality management costs for manufacturers serving European diagnostic laboratories. ISO 15189 accreditation standards govern laboratory competence in neuro-auto-immune testing, creating compliance thresholds that filter market participation. Stakeholders must weigh biomarker portfolio breadth against platform integration economics as health systems consolidate vendor relationships.
Market Dynamics
Hospital-based diagnostic laboratories are consolidating neuro-auto-immune testing workflows onto unified immunoassay platforms, compressing turnaround times and reducing send-out volumes to reference laboratories.
Growth Catalysts
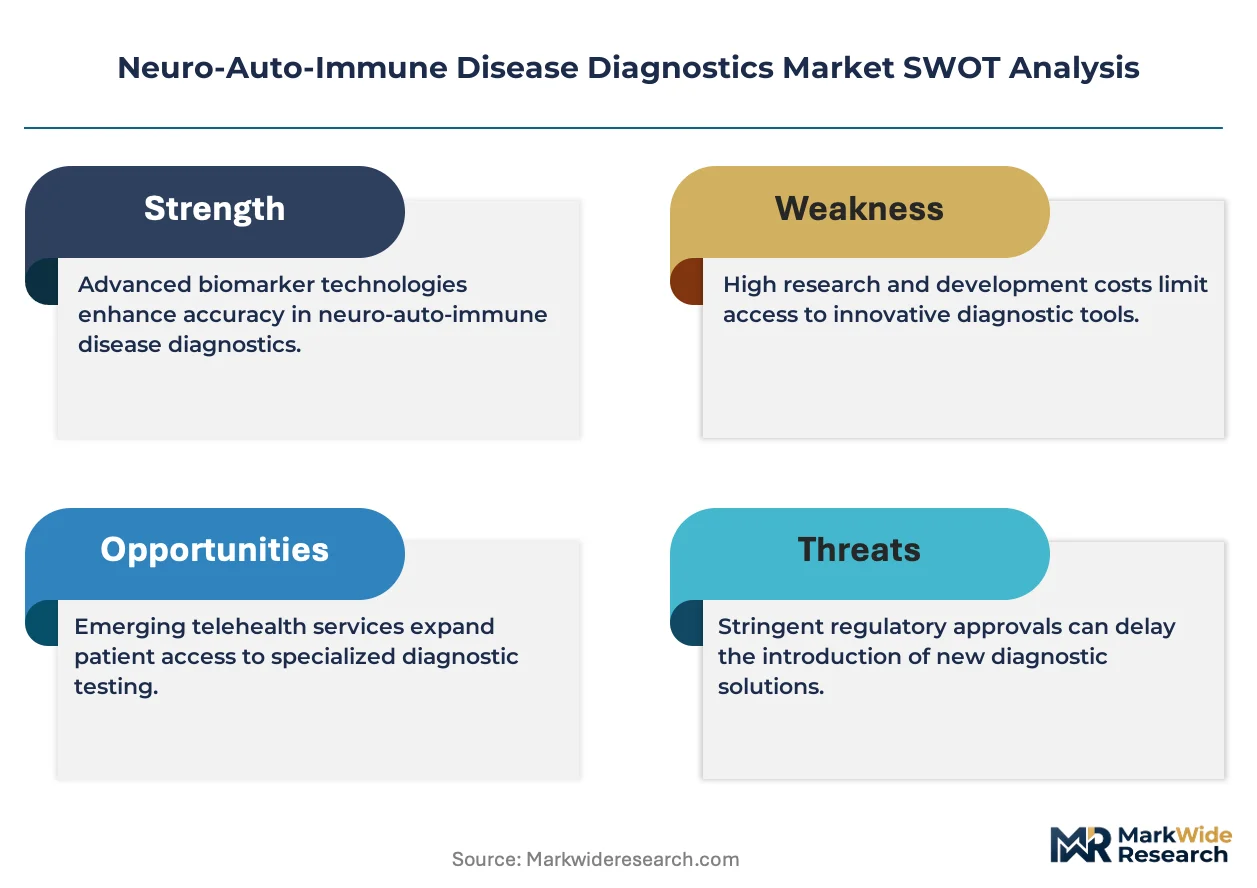
- FDA 510(k) Clearance Pathways:Expedited premarket review for novel neural autoantibody assays accelerates commercialization timelines for in vitro diagnostic manufacturers.
- Integrated Health Networks:Consolidated hospital systems in the United States centralize specialized testing capacity, creating captive demand for high-throughput autoimmune neurology panels.
- Multiplexed Microarray Technology:Simultaneous screening of multiple neural antigens reduces time-to-diagnosis from weeks to days in acute clinical settings.
Market Restraints
- Antibody Specificity Costs:Proprietary reagent development for rare neural autoantibodies drives per-test material costs substantially above standard immunoassay benchmarks.
- Reference Laboratory Concentration:Mayo Clinic Laboratories and ARUP Laboratories retain dominant positions in esoteric neuro-auto-immune testing, limiting hospital laboratory autonomy.
- EMA Post-Market Surveillance:In Vitro Diagnostic Regulation imposes ongoing quality management obligations that elevate European operational compliance burdens.
Strategic Opportunities
- Point-of-Care Expansion:Ambulatory neurology clinics in Germany and France present underpenetrated channels for rapid autoimmune antibody testing outside hospital settings.
- Imaging-Biomarker Convergence:Integration of advanced MRI protocols with serum antibody quantification enables longitudinal disease monitoring workflows.
- ISO 15189 Accreditation Demand:Laboratory competence standards create service revenue opportunities for quality management consultancies supporting hospital compliance.
Industry Challenges
- Specialized Pathologist Shortage:Interpretation of complex neural autoantibody profiles requires subspecialty expertise that academic medical centers struggle to recruit.
- Legacy Analyzer Integration:Hospital laboratories face workflow friction when embedding novel microarray platforms alongside established ELISA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuro-Auto-Immune Disease Diagnostics Market |
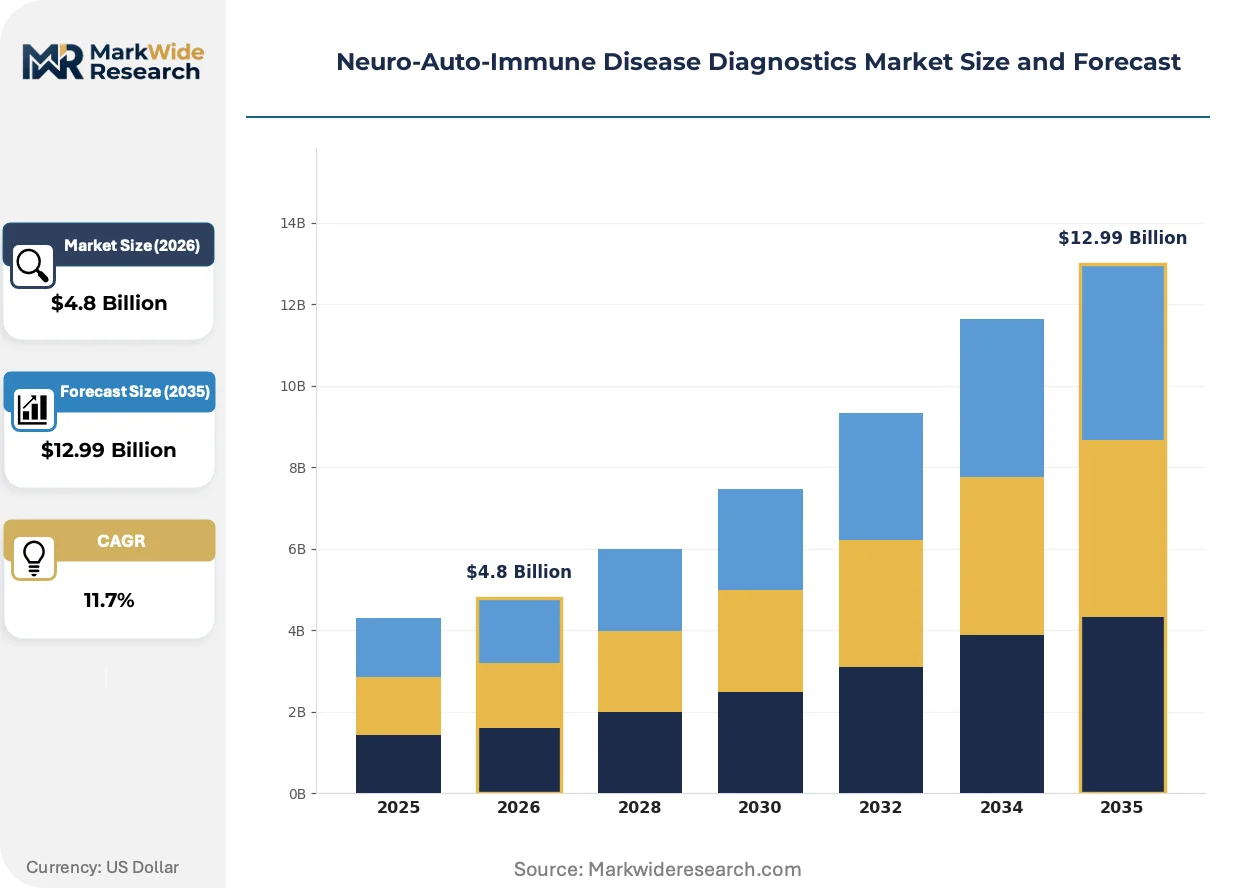
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Assays, Imaging Solutions, Diagnostic Kits Technology: ELISA, PCR, Mass Spectrometry, Microarrays Application: Research Laboratories, Clinical Diagnosis, Drug Development, Academic Institutions End User: Hospitals, Diagnostic Laboratories, Blood Banks, Clinics |
| Companies Covered | Bio-Rad Laboratories, Inc, Roche Diagnostics, Quest Diagnostics, Abbott Laboratories, Beckman Coulter, Inc, Siemens Healthineers, Thermo Fisher Scientific, bioMérieux, Inova Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuro-Auto-Immune Disease Diagnostics Market Shifts & Advancements
Diagnostic workflows are converging around platform consolidation and algorithmic interpretation, reducing dependence on manual pathologist review while expanding test menu breadth.
Multiplexed bead-based immunoassays are miniaturizing antibody detection workflows onto compact analyzers suitable for mid-volume hospital laboratories. Regional health systems in the United States are deploying these platforms across satellite facilities to retain testing revenue previously directed to centralized reference laboratories. This instrumentation shift is compressing the addressable market for standalone send-out testing while expanding in-house diagnostic autonomy.
EMA's In Vitro Diagnostic Regulation is mandating post-market performance surveillance for all novel biomarker assays entering European clinical use. Manufacturers must now maintain active safety monitoring systems that track analytical validity across distributed laboratory installations. Reagent suppliers serving diagnostic laboratories in France, Germany, and Italy are restructuring quality management organizations to satisfy these ongoing obligations.
Academic medical centers are unbundling after-sales technical support from analyzer procurement contracts, negotiating standalone service agreements with specialized field engineering providers. This purchasing pattern disrupts traditional vendor-captive maintenance relationships and opens competitive entry points for independent service organizations. The behavior is most pronounced in the United States, where hospital procurement departments leverage scale to fragment historically integrated equipment-service bundles.
Neuro-Auto-Immune Disease Diagnostics Market Segmentation
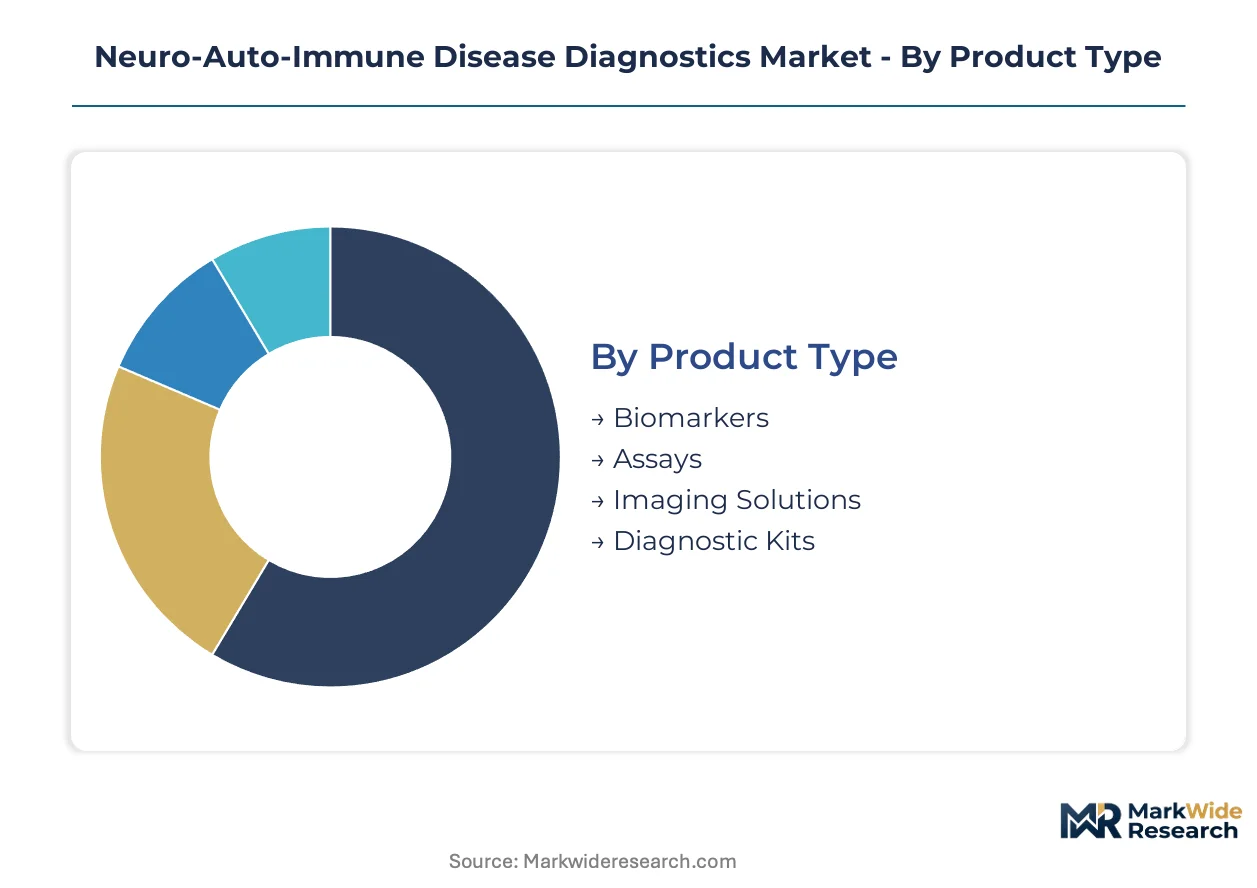
Segmentation in neuro-auto-immune diagnostics reveals how value pools distribute across technology platforms and customer workflows. Product architecture and testing volume concentration determine where manufacturers prioritize R&D investment and commercial resources.
Product Type:
Margin pools concentrate in proprietary reagent systems where antibody specificity creates pricing power and recurring revenue streams.
- Biomarkers:Serum and cerebrospinal fluid neural autoantibodies requiring highly specific antibody development. Academic medical centers in the United States drive premium demand for rare paraneoplastic panels where diagnostic confirmation alters oncology treatment pathways.
- Assays:Laboratory-developed and commercial immunoassay formats for quantitative antibody detection. Hospital laboratories in Germany favor automated ELISA workflows that integrate with existing chemistry analyzers to minimize capital expenditure.
- Imaging Solutions:MRI and PET protocols for inflammatory CNS lesion characterization.
- Diagnostic Kits:Standardized reagent-instrument bundles for decentralized testing.
The dominant share belongs to Biomarkers, while Diagnostic Kits are closing the gap fastest as health systems pursue platform consolidation.
Technology:
Volume throughput and capital intensity separate technologies suited for reference laboratories versus hospital-based deployment.
- ELISA:Enzyme-linked immunosorbent assay platforms dominate clinical throughput for single-analyte neural autoantibody quantification. Diagnostic laboratories across France deploy high-throughput ELISA systems for routine screening of common autoantibodies like anti-NMDA receptor and anti-LGI1.
- Mass Spectrometry:High-resolution protein identification for novel biomarker discovery and confirmatory testing. Research laboratories at academic medical centers in the United States leverage LC-MS/MS platforms to characterize post-translational modifications in target antigens.
- PCR:Molecular amplification for infectious mimic exclusion and paraneoplastic gene panel integration.
- Microarrays:Multiplexed bead-based simultaneous screening of 20-plus neural antigens.
ELISA retains the installed base majority, though Microarrays are expanding most quickly through mid-volume hospital laboratory adoption.
Application:
Customer procurement authority and reimbursement pathways fragment demand across fundamentally different purchasing organizations.
- Clinical Diagnosis:Patient-facing testing for acute neurological presentation and longitudinal monitoring. Integrated health networks in the United States centralize autoimmune neurology panels within system-wide laboratory formularies to capture reimbursement previously directed to external reference laboratories.
- Research Laboratories:Biomarker discovery and assay validation for novel neural autoantibody characterization. Academic institutions in Switzerland and the Netherlands maintain specialized facilities for rare antibody isolation and epitope mapping.
- Drug Development:Patient stratification and pharmacodynamic monitoring for neuro-immunology therapeutics.
- Academic Institutions:Training and reference standard development for emerging diagnostic modalities.
Clinical Diagnosis commands revenue concentration, while Drug Development shows the steepest expansion trajectory as pharmaceutical pipelines target neuro-inflammatory indications.
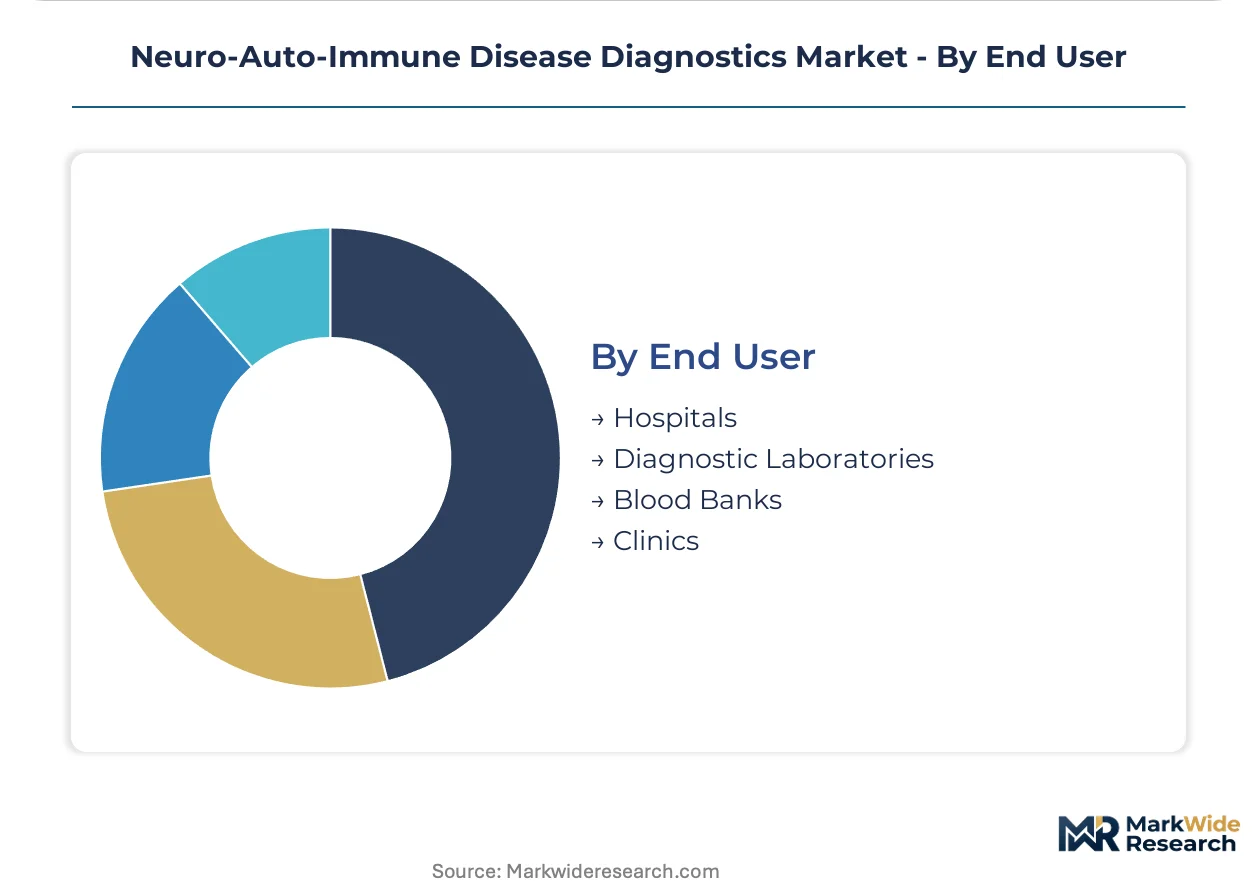
End User:
Consolidation dynamics and send-out economics reshape where testing physically occurs across the care continuum.
- Hospitals:Inpatient and emergency department testing for acute encephalitis and autoimmune epilepsy. Tertiary centers in the United States build dedicated neuro-immunology laboratory sections to reduce reliance on Mayo Clinic Laboratories and ARUP Laboratories for time-critical results.
- Diagnostic Laboratories:Centralized reference and health system core laboratory operations. National laboratory chains in Germany process regional hospital overflow while maintaining ISO 15189 accreditation for specialized antibody testing.
- Blood Banks:Pre-transfusion screening and donor deferral protocols for neurological risk factors.
- Clinics:Ambulatory neurology and rheumatology practice-based specimen collection.
Hospitals anchor current volume, though Diagnostic Laboratories are gaining share fastest as health system consolidation creates captive regional testing hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports neuro-auto-immune diagnostic reagents and analyzers to hospital laboratories across France, Italy, and the Netherlands, establishing the Rhine-Ruhr corridor as Europe's primary trade-flow hub for specialized immunoassay platforms.
United States
Integrated health networks in Texas and California centralize autoimmune neurology panels within system-wide laboratory formularies. FDA 510(k) clearance pathways compress commercialization timelines for novel neural autoantibody assays. Mayo Clinic Laboratories in Minnesota and ARUP Laboratories in Utah retain dominant positions in esoteric testing, limiting hospital laboratory autonomy for rare paraneoplastic panels.
Germany
Hospital laboratories in Bavaria and North Rhine-Westphalia favor automated ELISA workflows that integrate with existing chemistry analyzers. EMA's In Vitro Diagnostic Regulation imposes post-market surveillance obligations that elevate quality management costs for manufacturers serving diagnostic laboratories. The Rhine-Ruhr metropolitan region hosts specialized reference laboratories processing regional hospital overflow while maintaining ISO 15189 accreditation.
France
Diagnostic laboratories across Île-de-France deploy high-throughput ELISA systems for routine screening of common autoantibodies. ANSM regulates clinical trial frameworks for novel biomarker validation in neuro-auto-immune indications. The Paris-Saclay cluster concentrates academic medical centers developing multiplexed microarray platforms for simultaneous neural antigen screening.
Switzerland
Academic institutions in Zurich and Geneva maintain specialized facilities for rare antibody isolation and epitope mapping. Swissmedic oversees marketing authorization for in vitro diagnostics entering clinical use. The Basel pharmaceutical corridor drives demand for companion diagnostics supporting neuro-immunology therapeutic development pipelines.
United Kingdom
NHS England consolidates specialized testing capacity within regional pathology networks, creating captive demand for high-throughput autoimmune neurology panels. MHRA post-Brexit regulatory frameworks diverge from EMA requirements for novel assay validation. The Cambridge-Oxford-London golden triangle concentrates research laboratories leveraging mass spectrometry for biomarker discovery.
Neuro-Auto-Immune Disease Diagnostics Market Competitive Landscape
Player mix skews toward diversified diagnostic conglomerates with installed bases of immunoassay analyzers, creating tiered competition between platform-anchored incumbents and specialized reference laboratory operators. Market structure concentrates around three archetypes: multinational instrument-reagent bundlers, esoteric testing service providers, and niche biomarker developers. Dominant competitive moves include strategic partnerships for assay menu expansion and vertical integration into proprietary antibody development.
Among diversified diagnostic conglomerates, Roche Diagnostics and Siemens Healthineers occupy positions anchored by installed bases of hospital laboratory analyzers. Thermo Fisher Scientific exemplifies the R&D-intensive archetype sustaining investment across mass spectrometry platforms. Inova Diagnostics represents the specialized tier focused on autoimmune neurology panels. These three entities collectively illustrate how competitive positioning diverges between platform breadth and indication depth.
| Leading Market Players |
|---|
| Bio-Rad Laboratories, Inc |
| Roche Diagnostics |
| Quest Diagnostics |
| Abbott Laboratories |
| Beckman Coulter, Inc |
| Siemens Healthineers |
| Thermo Fisher Scientific |
| bioMérieux |
| Inova Diagnostics |
| Others |
Supply & Pricing Matrix
Ninety-day antibody reagent lead times from specialized biologics suppliers concentrate pricing power with manufacturers holding captive cell-line inventories, while hospital laboratories absorb cost volatility through multi-year analyzer lease commitments that embed consumable minimums.
Pricing Analysis
Next-generation multiplexed microarray platforms command 40-60% per-test premiums over legacy ELISA workflows, while prior-generation single-analyte assays face commoditization in high-volume screening applications. Three-tier pricing structure across premium, standard, and economy levels stratifies by antibody panel complexity and turnaround time guarantees. Pricing pressure stems from hospital procurement departments consolidating vendor relationships and demanding volume discounts for system-wide laboratory formularies. Reference laboratories exhibit lowest price sensitivity due to captive patient populations and reimbursement insulation, while mid-volume hospital laboratories negotiate aggressively on per-test costs.
Supply Chain Analysis
Specialized hybridoma cell-line repositories in the United States and Switzerland constitute critical chokepoints for rare neural autoantibody reagent production, with single-source dependencies for certain paraneoplastic panels creating vulnerability to contamination events or intellectual property disputes. Reagent manufacturing draws from biologics-grade fetal bovine serum suppliers concentrated in Australia and New Zealand, recombinant protein expression systems anchored in Germany, and synthetic peptide synthesis capacity in Switzerland. Tariff exposure on Chinese-sourced assay plastics and European-sourced diagnostic enzymes elevates landed costs for manufacturers without regional manufacturing footprints. Distribution runs through authorized distributor networks serving hospital systems and direct contracts with national laboratory chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital laboratory capital expenditure cycles are entering a recovery phase as health systems release pent-up demand deferred through pandemic-era budget freezes, with integrated network consolidation creating sustained procurement momentum for platform-standardization investments.
For Market Incumbents: Consolidate installed-base loyalty through exclusive reagent supply contracts that penalize analyzer switching, while acquiring specialized antibody development shops to secure proprietary biomarker portfolios against emerging multiplex competitors. Threat substitution from lower-cost Chinese microarray entrants demands defensive patent filings in key European jurisdictions. Backward integration into hybridoma cell-line banking reduces single-source supplier risk.
For New Entrants and Emerging Players: Lead with rapid point-of-care autoimmune antibody testing for ambulatory neurology clinics in Germany and France, where hospital-centric incumbents maintain weak distribution presence. White-space concentration exists in same-day result delivery for acute encephalitis workups outside tertiary referral networks. Go-to-market through specialized field engineering partnerships that unbundle service from equipment procurement addresses hospital procurement department preferences for fragmented vendor relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because reference laboratory economics favor scale concentration in esoteric testing, with Mayo Clinic Laboratories and ARUP Laboratories demonstrating durable margin structures that attract strategic buyer interest. Acquisition target archetype: mid-cap autoimmune neurology panel specialists with FDA-cleared assays and health system GPO contracts. Signal to watch: hospital laboratory send-out volume trends as in-house microarray adoption accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited premarket review compresses commercialization timelines for novel neural autoantibody assays entering US hospital laboratories. |
| Hospital System Partnership | Integrated health network laboratory formulary placement secures captive demand and reimbursement capture previously directed to external reference laboratories. |
| Multiplexed Microarray Launch | Simultaneous neural antigen screening reduces time-to-diagnosis and displaces sequential ELISA workflows in acute clinical settings. |
| Reimbursement Strategy | CPT code establishment and payer coverage determination unlocks commercial viability for novel biomarker panels in autoimmune neurology. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance enables European diagnostic laboratory market access with post-market surveillance obligations. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EMA In Vitro Diagnostic Regulation guidance documents, hospital procurement databases, and GPO contract disclosures. Primary interviews engaged laboratory directors at academic medical centers, diagnostic reagent procurement managers, biomedical engineers specializing in immunoassay platform integration, and regulatory affairs leads at IVD manufacturers. Secondary validation drew from SEC 10-K filings of publicly traded diagnostic conglomerates, ISO 15189 accreditation records, and CMS Medicare reimbursement data. Bottom-up test volume modeling triangulates against top-down health system expenditure analysis.
Segmentation dimensions modeled span product type, technology platform, application purpose, and end-user facility category, with geographic regulatory clusters treated as distinct market units. CAGRs derive from installed base expansion rates, test menu breadth additions, and reimbursement pathway maturation across the projection horizon. Industry-specific forecast inputs include hospital laboratory send-out volume migration patterns and reference laboratory market share trajectories.
Underlying assumptions cover health system consolidation continuity, FDA premarket review throughput stability, and European regulatory compliance cost absorption, with deviation risk concentrated in reimbursement rate compression and specialized pathologist workforce availability. Practitioners should keep alternative scenarios live as integrated network procurement centralization and point-of-care technology maturation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Urinary Protein Reagents Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Animal Auto-Immune Disease Diagnostics Market
Diagnostics
Global Coagulation Analyzers Market
Diagnostics
Fertility Test Market
Diagnostics
Companion Animal Diagnostic Services Market
Diagnostics
Direct Fluorescent Antibody Test Kits Market
Diagnostics
North America Non-Hodgkin Lymphoma Diagnostics Market
Diagnostics
Asia Pacific in Vitro Diagnostics Market
Diagnostics
Europe in Vitro Diagnostics (IVD) Market
Diagnostics
France in-Vitro Diagnostics Market
Diagnostics
Alzheimer's Diagnostics and Therapeutics Market
Diagnostics
Hospital Clinical Chemistry and Immunodiagnostics Market
Diagnostics
Global Serological Testing Market
Diagnostics
Hydrogen Breath Test Analyzer Market
Diagnostics
Autoimmunity Immunoassay Market