
 Heart Attack Diagnostics Market | 2026-2036
Heart Attack Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Heart Attack Diagnostics Market Intelligence
Software-defined ECG interpretation is recalibrating what cardiac diagnostic vendors sell, shifting transaction models toward per-test analytics licensing. GE Healthcare Technologies leverages its Edison AI platform to anchor hospital system contracts with algorithmic risk-scoring subscriptions. Abbott Laboratories sustains dominance in high-sensitivity troponin assays through captive supply of automated immunoanalyzers. Siemens Healthineers differentiates by integrating echocardiography with real-time hemodynamic monitoring in cath lab workflows.
Heart attack diagnostics encompass electrocardiographic, biochemical, and imaging modalities that detect acute myocardial infarction through ST-segment deviation, cardiac troponin elevation, or regional wall motion abnormalities, with contemporary systems achieving troponin-I detection thresholds below 5 ng/L to enable rule-out protocols within one hour. The primary commercial purpose centers on reducing door-to-balloon time and preventing misdiagnosis in atypical presentations. Blood tests command the deepest margin pools due to recurring reagent consumption and automated platform lock-in. Artificial Intelligence is displacing conventional equipment in emergency triage, where FDA-cleared algorithms interpret 12-lead ECGs for occlusion myocardial infarction without specialist presence.
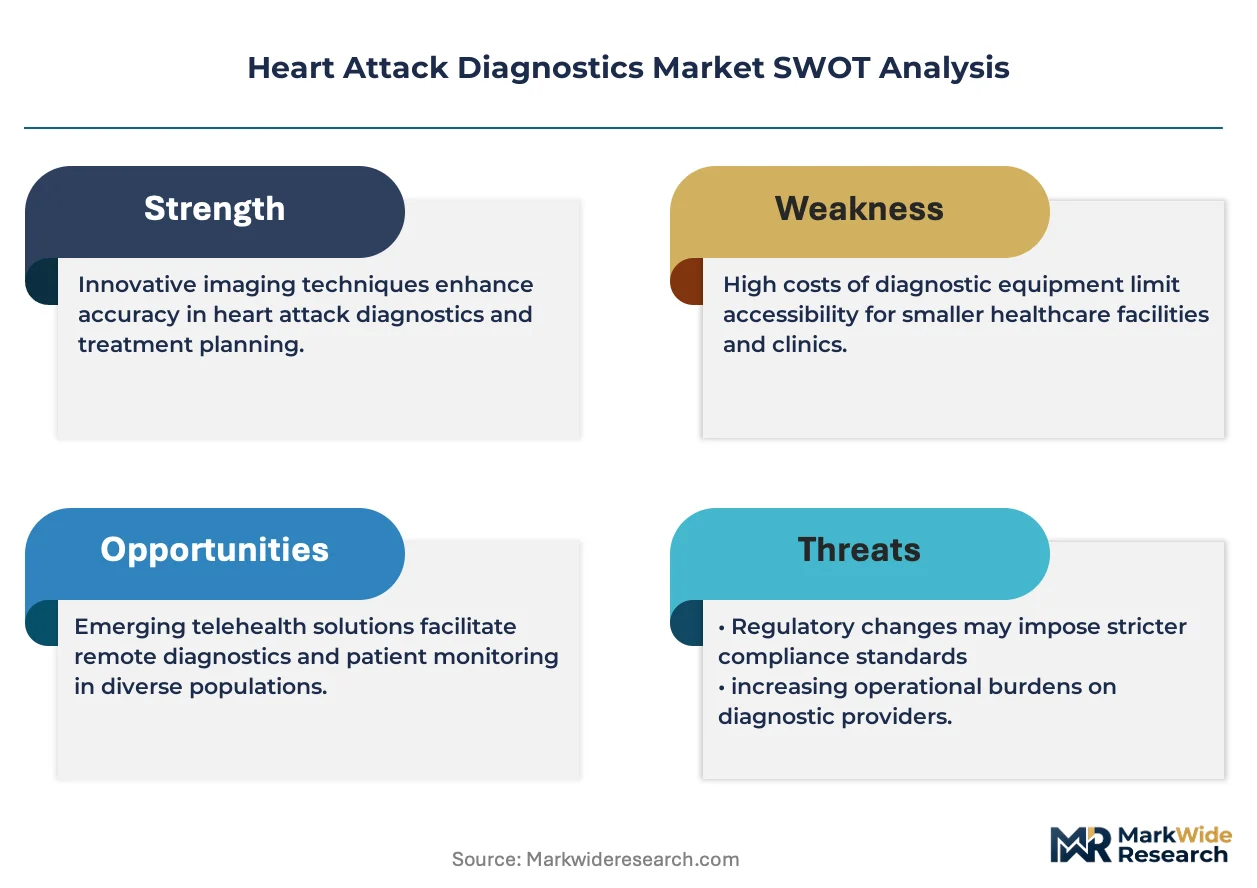
FDA breakthrough device designations and CLIA-waived test standards shape product development timelines and point-of-care market access for novel cardiac biomarkers. The European Union's Medical Device Regulation imposes clinical evidence requirements that favor established manufacturers with post-market surveillance infrastructure. Stakeholders must monitor reimbursement parity between AI-augmented and conventional diagnostic interpretations as payer evidence requirements mature.
Market Dynamics
Software-defined ECG interpretation is compressing specialist-dependent workflows into algorithmic triage protocols, forcing vendors to restructure revenue models around per-test analytics licensing rather than capital equipment sales.
Growth Catalysts
- AI-enabled ECG clearance:FDA breakthrough device designations compress regulatory timelines for machine-learning cardiac algorithms, accelerating emergency department adoption of automated occlusion detection.
- High-sensitivity troponin protocols:Tertiary hospital emergency departments are expanding one-hour rule-out testing to reduce door-to-balloon time and prevent misdiagnosis in atypical presentations.
- Integrated delivery network consolidation:United States health systems are centralizing diagnostic procurement across multiple facilities, creating volume commitments that favor platform-locked assay suppliers.
Market Restraints
- Automated immunoanalyzer lock-in:High-sensitivity troponin assays require proprietary hardware, creating switching costs that concentrate supply among incumbent manufacturers with installed base advantages.
- European clinical evidence burdens:EU Medical Device Regulation imposes post-market surveillance requirements that favor established manufacturers with regulatory infrastructure, raising barriers for novel biomarker entrants.
- Specialist interpretation dependency:Complex echocardiography and hemodynamic monitoring still require cardiologist presence, limiting point-of-care deployment outside tertiary settings.
Strategic Opportunities
- Point-of-care biomarker expansion:CLIA-waived test standards create pathways for novel cardiac markers to penetrate ambulatory settings and urgent care clinics beyond hospital laboratories.
- AI-ECG and echocardiography convergence:Real-time algorithmic interpretation of regional wall motion abnormalities during catheterization procedures enables integrated cath lab workflow automation.
- Reimbursement parity arbitrage:Payer evidence requirements for AI-augmented interpretations remain immature, creating temporary margin advantages for early algorithmic clearance holders.
Industry Challenges
- Algorithm validation complexity:FDA-cleared AI-ECG systems require continuous performance monitoring across diverse patient populations, straining quality assurance functions in smaller health systems.
- Legacy platform integration friction:Software-defined diagnostics must interface with existing PACS and EMR architectures, demanding custom interoperability work that delays deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heart Attack Diagnostics Market |
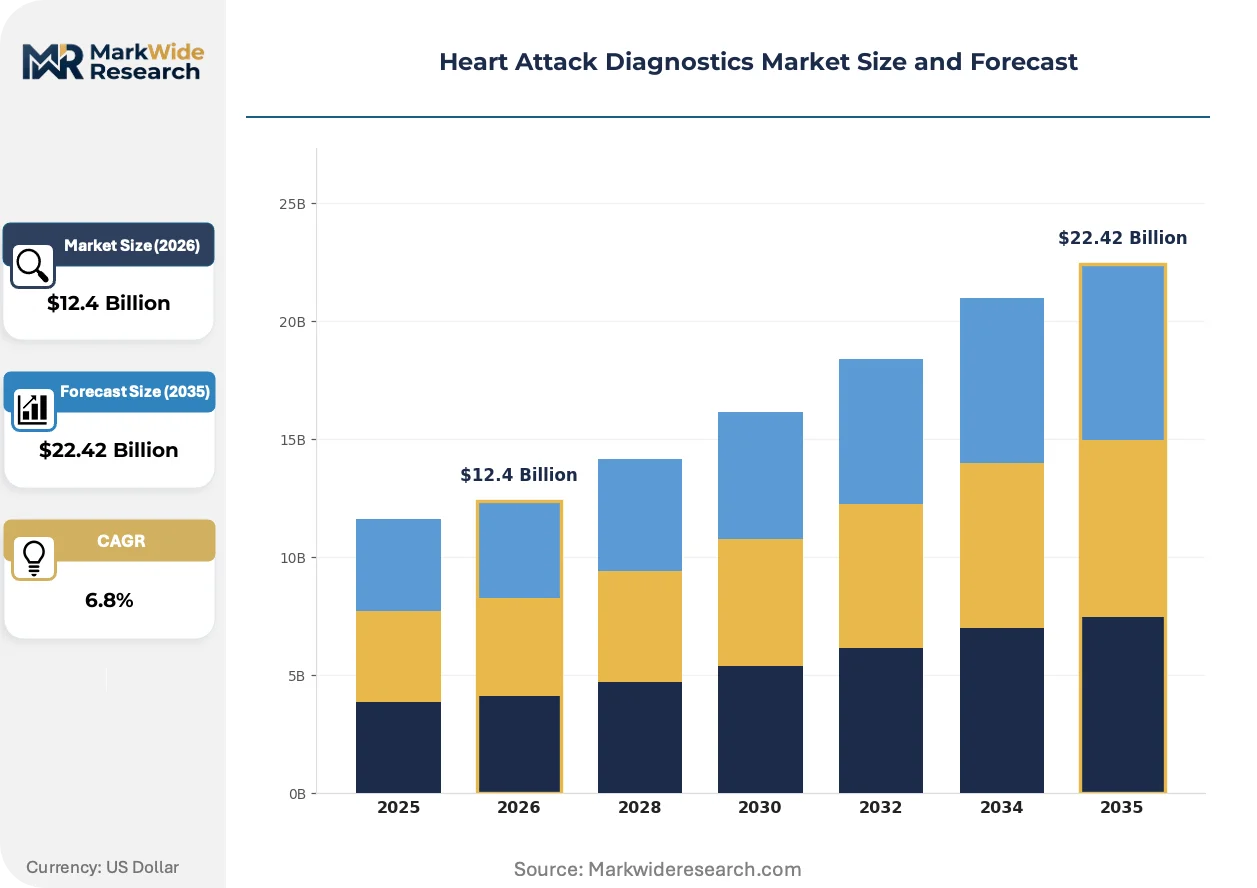
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrocardiogram, Blood Tests, Imaging Tests, Biomarkers Delivery Mode: Hospital Settings, Point-of-Care, Home Care, Laboratories Technology: Artificial Intelligence, Wearable Devices, Conventional Equipment, Mobile Applications End User: Cardiologists, General Practitioners, Emergency Services, Patients |
| Companies Covered | GE Healthcare Technologies, Koninklijke Philips NV, Abbott Laboratories, Bio-Rad Laboratories Inc., SCHILLER AG, F. Hoffmann-La Roche Ltd, Beckman Coulter Inc., Toshiba Corp., Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heart Attack Diagnostics Market Strategic Shifts & Innovations
Cardiac diagnostic workflows are fragmenting across hardware, software, and consumable layers, with value capture migrating toward algorithmic interpretation and away from device manufacturing.
High-sensitivity troponin-I detection platforms are unifying sample-to-answer automation with result transmission directly into electronic medical records. Emergency departments in United States tertiary hospitals are adopting these systems to meet one-hour protocol targets. This convergence is compressing laboratory turnaround time into a competitive differentiator for health system contracting.
EU Medical Device Regulation post-market surveillance requirements are extending clinical evidence obligations across the full product lifecycle. Manufacturers must maintain active safety monitoring infrastructure that smaller competitors cannot replicate. High-sensitivity cardiac biomarker submissions face the steepest evidentiary thresholds, consolidating clearance advantages among established European players.
Integrated delivery networks in the United States are unbundling diagnostic procurement from capital equipment budgets into recurring reagent and analytics contracts. Hospital systems negotiate multi-year commitments that lock in assay pricing across expanding troponin testing volumes. This purchasing model shift is most visible in states with concentrated health system consolidation such as California and Texas.
Heart Attack Diagnostics Market Segmentation
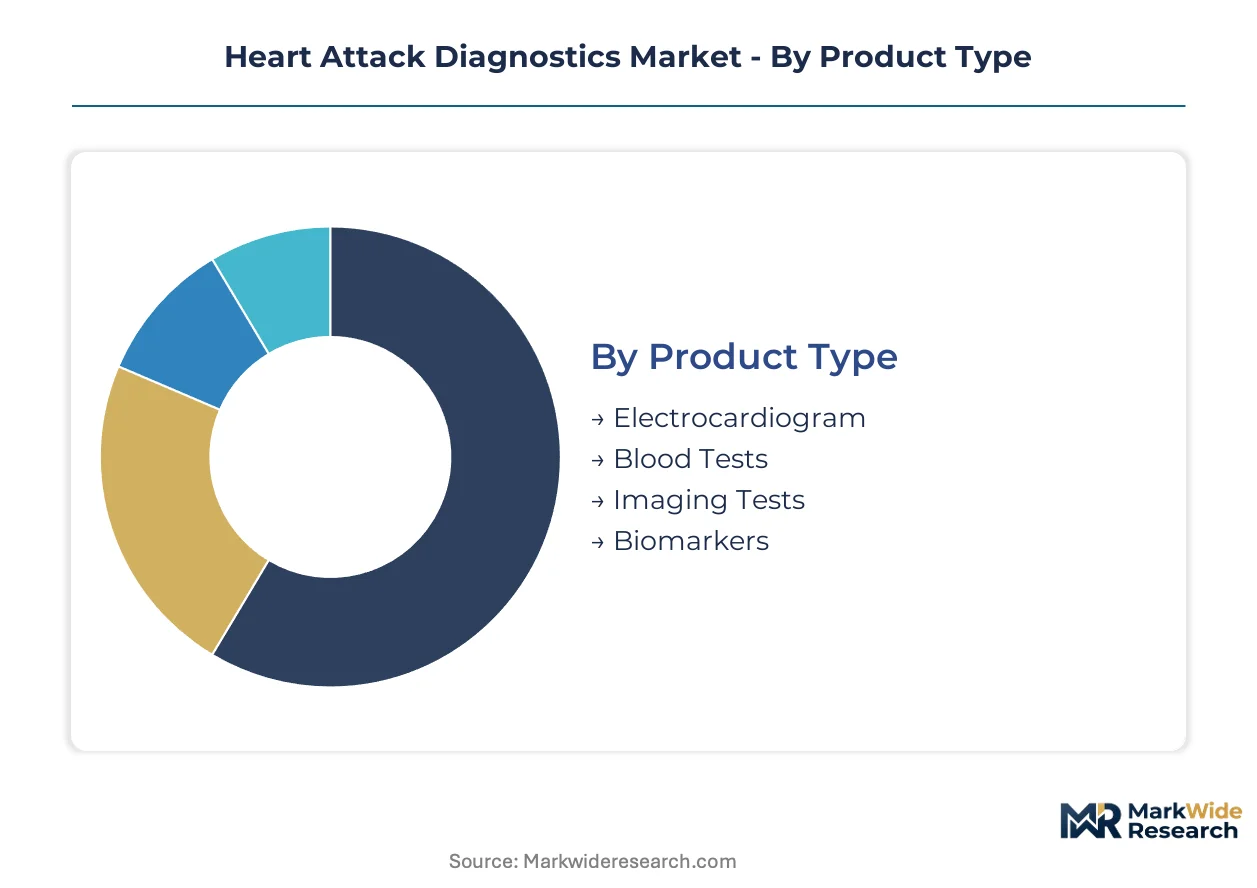
Diagnostic procurement patterns diverge sharply between emergency triage environments requiring immediate results and ambulatory settings prioritizing cost efficiency. Vendors must align product configurations with these distinct operational constraints rather than pursuing universal platform designs.
Product Type:
Hospital laboratories select platforms based on throughput capacity and reagent contract terms, while emergency departments prioritize speed-to-result over per-test economics.
- Blood Tests:High-sensitivity troponin assays detect cardiac injury below 5 ng/L thresholds, enabling one-hour rule-out protocols. United States tertiary hospitals concentrate procurement volume here as integrated delivery networks negotiate multi-year reagent commitments.
- Electrocardiogram:Twelve-lead systems remain the frontline screening standard, with software-defined interpretation displacing conventional hardware sales. FDA breakthrough device designations accelerate algorithmic clearance timelines for automated occlusion detection.
- Imaging Tests:Echocardiography and cardiac catheterization provide anatomical confirmation.
- Biomarkers:Novel protein markers supplement troponin panels in complex presentations.
Volume sits with Blood Tests; growth tilts toward Electrocardiogram algorithmic platforms.
Delivery Mode:
Site-of-care placement determines regulatory pathway complexity and reimbursement coding, with CLIA-waived standards unlocking access beyond hospital walls.
- Hospital Settings:Central laboratories and emergency departments anchor diagnostic volume through integrated workflows with cardiac catheterization labs. Siemens Healthineers and Abbott Laboratories compete for analyzer placement via captive reagent supply agreements.
- Point-of-Care:Bedside and urgent care deployment demands sample-to-answer automation under waived testing standards. Ambulatory clinics in California and Texas health systems expand procurement fastest.
- Laboratories:Reference labs process overflow and specialized panels.
- Home Care:Remote monitoring applications remain limited by interpretation complexity.
Revenue concentrates in Hospital Settings; expansion trajectory steepest in Point-of-Care.
Technology:
Intellectual property ownership separates vendors capturing recurring analytics revenue from equipment manufacturers locked into capital sales cycles.
- Artificial Intelligence:Machine-learning ECG interpretation achieves occlusion detection without cardiologist presence. GE Healthcare Technologies anchors hospital contracts through Edison platform risk-scoring subscriptions.
- Conventional Equipment:Hardware-centric modalities face margin compression as software layers capture diagnostic value. Established installed bases in United States health systems sustain residual demand.
- Wearable Devices:Consumer-grade sensors feed data into clinical algorithms.
- Mobile Applications:Patient-facing tools extend monitoring beyond clinical encounters.
Deployment tilts toward Artificial Intelligence; residual hardware demand stabilizes Conventional Equipment.
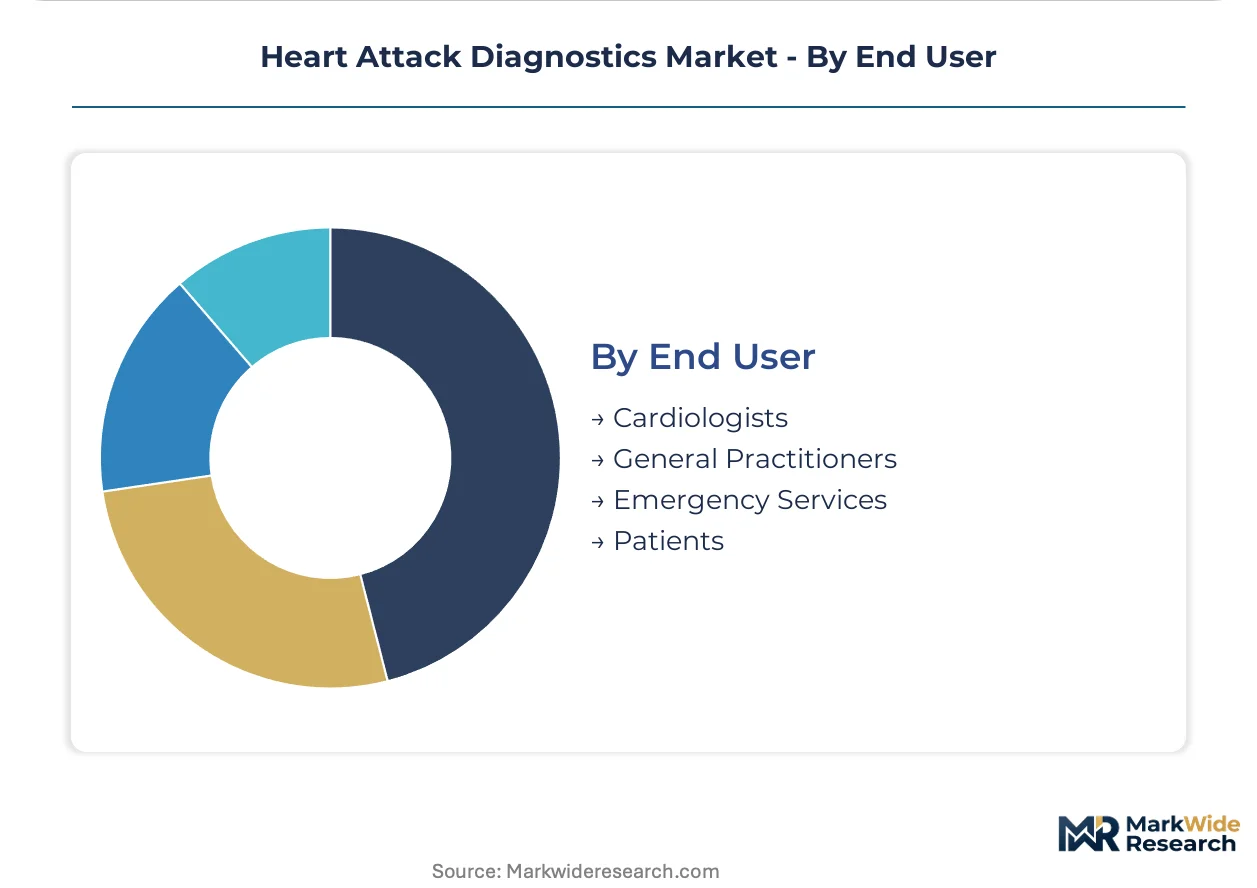
End User:
Clinical training depth dictates acceptable diagnostic uncertainty thresholds and platform complexity tolerance.
- Emergency Services:Paramedic and triage nurse users require definitive algorithmic outputs without specialist backstop. United States emergency medical services expand AI-ECG deployment to shorten door-to-balloon intervals.
- Cardiologists:Subspecialists demand granular anatomical and hemodynamic data for intervention planning. Academic medical centers concentrate this segment's procurement authority.
- General Practitioners:Primary care gatekeepers need rule-out certainty for referral decisions.
- Patients:Direct-access diagnostics remain constrained by interpretation liability.
Decision authority concentrates with Cardiologists; deployment expansion favors Emergency Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's Longwood Medical Area anchors emergency cardiac diagnostic deployment, with Massachusetts General Hospital and Brigham and Women's Hospital piloting AI-ECG triage protocols that compress door-to-balloon intervals below national benchmarks.
United States
Integrated delivery networks in California and Texas consolidate troponin procurement through multi-year reagent commitments. FDA breakthrough device designations accelerate AI-ECG clearance timelines for emergency department automation. The Cleveland Clinic cluster in Ohio deploys one-hour rule-out protocols across its 11-hospital system.
Germany
Baden-Württemberg's medical technology corridor concentrates echocardiography manufacturing alongside catheterization lab integration. EU Medical Device Regulation post-market surveillance requirements favor established manufacturers with active safety monitoring infrastructure. Siemens Healthineers anchors its European cardiac diagnostics operations from Erlangen.
China
Beijing-Tianjin-Hebei corridor hospitals expand high-sensitivity troponin testing capacity under national cardiovascular disease prevention mandates. NMPA regulatory pathways for novel cardiac biomarkers require domestic clinical trials that extend clearance timelines. Shanghai's Ruijin Hospital pilots AI-ECG interpretation for rural hospital network referral triage.
Japan
Kanto region academic medical centers concentrate demand for hemodynamic monitoring integration with interventional cardiology workflows. PMDA consultation procedures for software as a medical device shape AI-ECG development timelines for domestic manufacturers. Tokyo Women's Medical University advances real-time wall motion analysis algorithms for catheterization laboratories.
India
Maharashtra's tertiary hospital networks in Mumbai and Pune expand point-of-care troponin deployment under national health mission rural outreach programs. CDSCO regulatory harmonization with IMDRF standards accelerates import clearance for automated immunoanalyzers. Hyderabad's medical device manufacturing cluster produces ECG hardware for domestic hospital procurement.
Heart Attack Diagnostics Market Key Industry Players
Capital-heavy producers compete with asset-light algorithm developers for diagnostic value capture. Automated immunoanalyzer manufacturers lock in recurring reagent revenue through installed base advantages, while software vendors extract per-test analytics fees from cloud-deployed interpretation engines. Three archetypes dominate: integrated conglomerates with captive hospital system relationships, specialized biomarker assay suppliers, and AI-native diagnostic software platforms. Competitive moves center on strategic partnerships for EMR interoperability and geographic expansion through distributor networks in underserved health systems.
Among diversified health technology conglomerates, GE Healthcare Technologies, Koninklijke Philips NV, and Siemens Healthineers occupy positions spanning hardware manufacturing through algorithmic risk-scoring subscriptions. These entities exemplify the platform-locked archetype where diagnostic value migrates from device sales toward recurring analytics licensing. Abbott Laboratories and F. Hoffmann-La Roche Ltd represent the biomarker-specialist tier, anchoring troponin assay supply through automated analyzer captivity. Bio-Rad Laboratories Inc. and SCHILLER AG sit within the mid-scale equipment segment, serving regional hospital networks and ambulatory clinic chains with conventional ECG and immunoassay platforms.
| Leading Market Players |
|---|
| GE Healthcare Technologies |
| Koninklijke Philips NV |
| Abbott Laboratories |
| Bio-Rad Laboratories Inc. |
| SCHILLER AG |
| F. Hoffmann-La Roche Ltd |
| Beckman Coulter Inc. |
| Toshiba Corp. |
| Siemens Healthineers AG |
| Others |
Cost & Logistics Intelligence
Platform-locked diagnostic conglomerates with captive reagent supply agreements exercise pricing discipline through multi-year hospital system contracts that bundle hardware placement with recurring consumable commitments. Abbott Laboratories and Siemens Healthineers anchor troponin assay pricing to analyzer throughput guarantees, while GE Healthcare Technologies extracts per-test analytics fees from Edison platform subscriptions that resist direct price comparison.
Pricing Analysis
Throughput-based pricing anchors hospital laboratory contracts, with high-sensitivity troponin assays priced per-test against guaranteed annual volume minimums negotiated through integrated delivery network procurement. Price differentiation rests on CLIA-waived certification tier for point-of-care deployment and algorithmic risk-scoring sophistication for AI-ECG platforms. Cost compression in conventional ECG hardware intensifies as software-defined interpretation displaces capital equipment sales. Emergency services exhibit highest price sensitivity due to constrained municipal budgets, while tertiary hospital systems prioritize speed-to-result over per-test economics.
Supply Chain Analysis
Single-source vulnerability sits with specialized antibody suppliers for high-sensitivity troponin assays concentrated in the United States and Germany. Manufacturing draws from precision optical components sourced from Japan, semiconductor substrates from Taiwan, and rare earth magnets for analyzer motors from China. Tariff exposure on Chinese-sourced electronic components threatens margin stability for mid-scale equipment manufacturers. Distribution runs through distributor networks serving regional hospital systems and direct sales forces penetrating integrated delivery network procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Analyzer manufacturing capacity constraints prop pricing power for platform-locked incumbents, as multi-year reagent commitments lock hospital systems into captive supply relationships that resist competitive switching.
For Market Incumbents: Anchor troponin assay dominance through backward integration into precision antibody production and expanded CLIA-waived test portfolios for urgent care penetration. Defend against AI-native software entrants by embedding algorithmic interpretation into existing analyzer workflows to preserve platform lock-in. Prioritize EMR interoperability investments that raise switching costs for health system customers. For New Entrants and Emerging Players: Enter via point-of-care biomarker segments underserved by automated immunoanalyzer incumbents, targeting ambulatory clinics in California and Texas health systems with sample-to-answer devices under waived testing standards. Pursue FDA breakthrough device designation for novel cardiac markers to compress regulatory timelines. Partner with regional distributor networks to bypass direct sales force requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale AI-ECG developers with cleared algorithms but constrained commercial infrastructure in the United States. Long-term viability hinges on reimbursement parity achievement for algorithmic interpretation against conventional specialist reads. Monitor CMS coverage determinations for AI-augmented diagnostics as the inflection signal for valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Accelerates AI-ECG clearance timelines for emergency department automation under FDA priority review. |
| Hospital System Partnership | Locks multi-year reagent commitments through integrated delivery network procurement consolidation. |
| Software Companion Development | Enables real-time algorithmic interpretation of echocardiography during catheterization procedures. |
| CE Marking Pathway | Unlocks EU market access under MDR post-market surveillance requirements favoring established infrastructure. |
| Reimbursement Strategy | Secures payer parity for AI-augmented interpretations before evidence requirements mature. |
Research Approach
Multi-period observation of troponin testing volumes, AI-ECG deployment rates, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with emergency department directors, clinical laboratory managers, biomedical engineers, and GPO contracts specialists. Secondary validation drew from FDA 510(k) and breakthrough device designations, CMS Medicare reimbursement databases, hospital procurement records, and EU MDR notified body filings. Bottom-up analyzer placement estimates triangulated against top-down health system capital expenditure surveys.
Input-output matrices modeled reagent consumption against installed base expansion across product type, delivery mode, technology layer, and end-user clinical setting. CAGRs were derived from segmented volume projections calibrated to historical troponin assay growth and algorithmic platform adoption curves. Forecast inputs incorporated regulatory clearance timelines, integrated delivery network consolidation patterns, and payer coverage evolution for AI-augmented diagnostics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA reimbursement determination delays or EU MDR enforcement disruptions. Projections reflect documented assumptions regarding health system consolidation velocity and algorithmic performance validation requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Blood Culture Media Market
Diagnostics
Cognitive Diagnostics Market
Diagnostics
Antigen Kit Market
Diagnostics
Global Diagnostic Radiopharmaceuticals and Contrast Media Market
Diagnostics
GCC in-Vitro Diagnostics Market
Diagnostics
Fertility Testing Devices Market
Diagnostics
Haptoglobin Reagent Market
Diagnostics
IVD Antibody Market
Diagnostics
Molecular Diagnostics Market
Diagnostics
Multiplex Molecular Diagnostics Market
Diagnostics
Europe Breast Cancer Screening Tests Market
Diagnostics
Extraction Kits Market
Diagnostics
Global Pelvic Floor Diagnostic Testing Market
Diagnostics
Global Autoimmune Disease Diagnostics Market
Diagnostics
Vision Screeners Market
Diagnostics
Veterinary Chemistry Analyzers Market