
 Mycoplasma Diagnostics Market | 2026-2036
Mycoplasma Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Mycoplasma Diagnostics Market Outlook
A shift from outsourced reference lab testing toward in-house molecular screening is restructuring procurement patterns across biopharmaceutical quality control. Thermo Fisher Scientific leverages its integrated PCR and NGS platform portfolio to anchor high-volume contract manufacturing relationships. Lonza Group AG specializes in contamination control workflows that sustain its position in cell and gene therapy production services. Qiagen NV competes through sample preparation automation that extends its reach into mid-tier pharmaceutical quality labs.
Mycoplasma diagnostics encompasses the detection, identification, and quantification of cell-wall-deficient bacteria in biological samples, typically employing PCR amplification with species-specific primers, ELISA-based antibody detection, or direct culture on selective agar with metabolic indicator dyes. Its primary purpose is to prevent costly contamination events in biopharmaceutical manufacturing, cell therapy production, and vaccine development where sterility failures can destroy entire product batches. PCR Kits command the largest product segment due to their sensitivity and rapid turnaround, while Next-Generation Sequencing represents the fastest-growing technology dimension as multiplexed species identification becomes standard for advanced therapy medicinal products. Research Institutes and Pharmaceutical Companies constitute the most concentrated end-user margin pool, driven by regulatory mandates for release testing and in-process control.
FDA guidance on mycoplasma testing for cell substrates and EMA's GMP Annex 1 revisions on contamination control strategy both elevate molecular method acceptance, while ISO 17025 accreditation requirements shape laboratory capability investments. The country's national pharmaceutical regulator in India and China's NMPA are aligning pharmacopoeial standards with ICH Q5D expectations, expanding addressable demand for validated test kits. Stakeholders must monitor evolving regulatory acceptance of NGS-based release testing versus compendial methods to time platform transition investments.
Market Dynamics
Cell therapy production scale-up is compressing testing turnaround windows from weeks to hours, forcing biomanufacturers to abandon culture-based methods in favor of molecular platforms that deliver same-day contamination verdicts.
Growth Catalysts
- FDA guidance on mycoplasma testing for cell substrates:Explicit acceptance of nucleic acid amplification methods accelerates platform conversion among US-based gene therapy developers.
- Cell therapy manufacturing:Autologous and allogeneic production lines require continuous in-process monitoring, embedding diagnostic capacity directly into cleanroom workflows.
- EMA GMP Annex 1 revisions:Contamination control strategy mandates elevate molecular screening from optional to expected across European biopharmaceutical release protocols.
Market Restraints
- Capital intensity of NGS validation:Full regulatory qualification of next-generation sequencing for lot release demands multi-year investment timelines that freeze mid-tier laboratories in PCR-based workflows.
- Reference standard scarcity:Certified mycoplasma DNA calibrators concentrate among three specialized suppliers, creating single-source vulnerability for assay developers.
- Compendial method persistence:Pharmacopoeial authorities in multiple jurisdictions retain culture-based methods as arbitration standards, forcing dual-platform maintenance.
Strategic Opportunities
- India's CDSCO alignment with ICH Q5D:Pharmacopoeial harmonization opens validated kit demand among domestic vaccine and biosimilar producers previously reliant on informal testing arrangements.
- Point-of-need PCR miniaturization:Battery-operated thermal cyclers enable at-line testing within cell therapy cleanrooms, collapsing logistics chains that currently route samples to central labs.
- Multiplexed species identification:Next-generation sequencing convergence with CRISPR-based detection creates single-workflow solutions for contamination forensics beyond presence-absence screening.
Industry Challenges
- Bioinformatics specialist scarcity:NGS-based release testing requires personnel capable of interpreting complex sequence data, a competency gap particularly acute in emerging biomanufacturing clusters.
- Legacy LIMS integration:Molecular platforms must interface with decade-old laboratory information systems designed around culture-based batch records, generating validation documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mycoplasma Diagnostics Market |
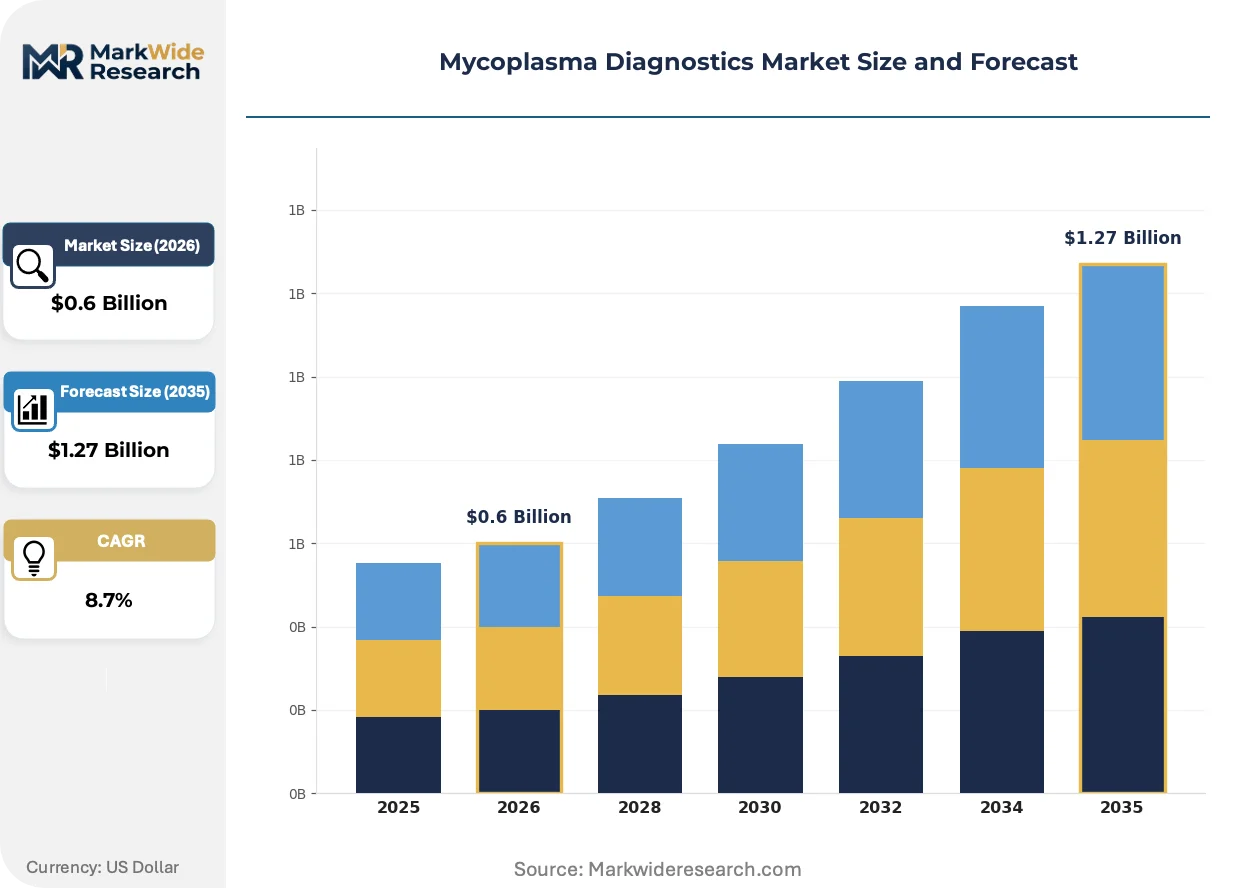
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR Kits, ELISA Kits, Culture Media, Nucleic Acid Probes Technology: Cell Culture, Molecular Diagnostics, Next-Generation Sequencing, Immunodiagnostics End User: Clinical Laboratories, Research Institutes, Pharmaceutical Companies, Blood Banks Application: Infectious Disease Diagnosis, Biopharmaceutical Production, Vaccine Development, Environmental Testing |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Roche Diagnostics, Lonza Group AG, Charles River Laboratories International, Inc., Qiagen NV, Bio-Rad Laboratories, Sartorius AG, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mycoplasma Diagnostics Market Strategic Shifts
Detection technology is bifurcating between rapid point-of-need systems for in-process control and comprehensive sequencing platforms for root-cause investigation, with procurement patterns fragmenting accordingly.
Digital PCR is absorbing the most demanding sensitivity requirements in cell therapy release testing. Gene therapy manufacturers with autologous product lines adopt this platform to detect single-copy contamination events in limited-volume patient samples. The technology is absorbing market share from quantitative PCR in applications where absolute quantification replaces relative threshold analysis.
EMA's 2022 GMP Annex 1 revision on contamination control strategy explicitly elevated rapid microbiological methods from supplementary to primary status when appropriately validated. European cell and gene therapy manufacturers now treat molecular mycoplasma screening as default rather than exception. CDMOs serving EU markets report accelerated client mandates for PCR or NGS-based release protocols.
Service unbundling is separating diagnostic reagent supply from validation consulting. Biopharmaceutical quality departments increasingly procure kits through distribution channels while engaging specialized consultancies for regulatory submission support. This pattern concentrates in North American markets where FDA pre-approval inspection timelines create premium demand for expedited qualification packages.
Mycoplasma Diagnostics Market Segmentation
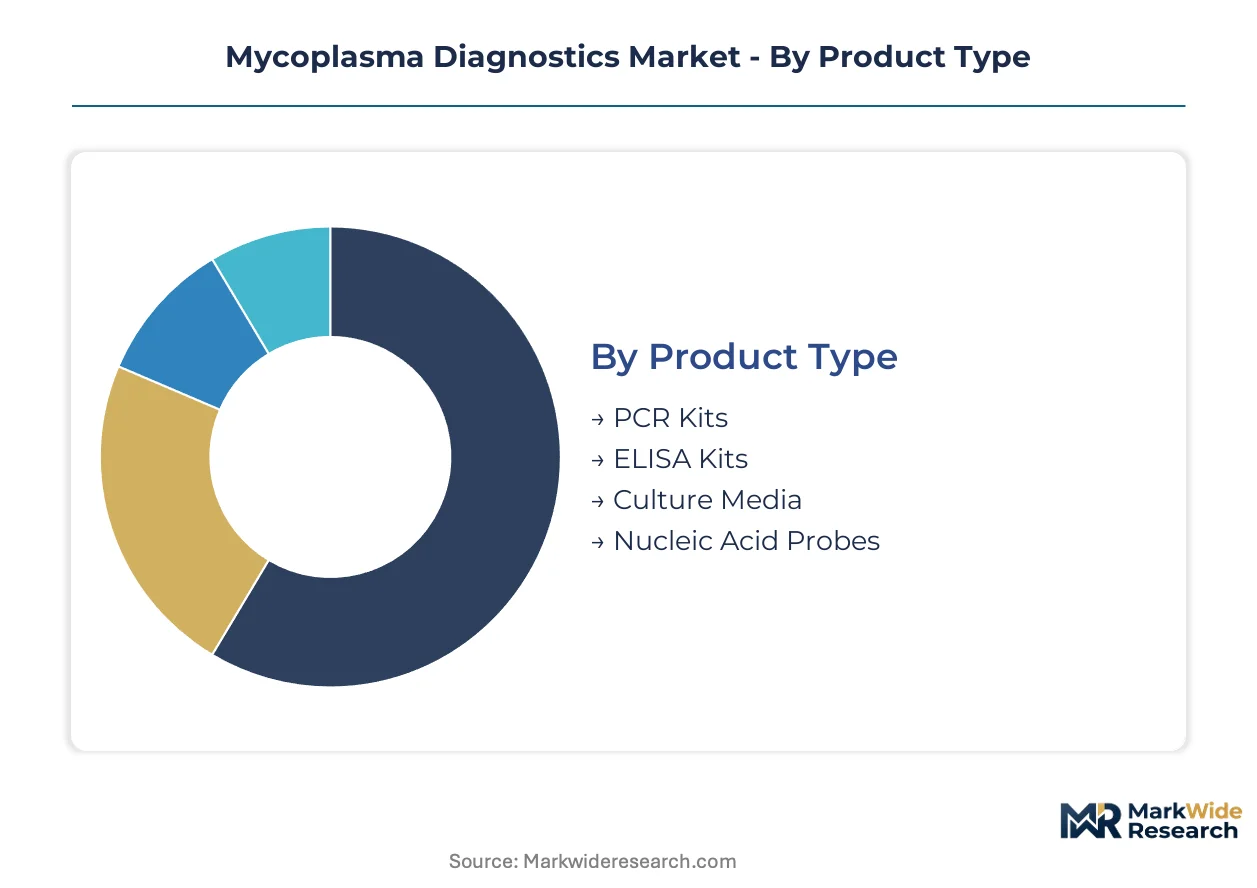
Mycoplasma diagnostics procurement splits across four independent decision axes. Product type determines assay sensitivity and regulatory acceptance. Technology choice reflects turnaround requirements versus forensic depth. End-user concentration shapes volume pricing and service bundling. Application context dictates validation burden and contamination risk tolerance.
Product Type:
Biopharmaceutical quality departments prioritize sensitivity specifications and lot-to-lot consistency when selecting assay formats.
- PCR Kits:Amplification-based detection with species-specific primers delivers results within hours rather than weeks. Demand concentrates among cell therapy manufacturers in the United States and Germany where FDA and EMA guidance explicitly accepts nucleic acid methods for release testing.
- ELISA Kits:Antibody-mediated detection targets protein antigens with lower capital equipment requirements. Pharmaceutical quality labs in India and Brazil favor this format where infrastructure constraints limit thermal cycler deployment.
- Culture Media:Metabolic indicator dyes on selective agar remain the pharmacopoeial reference standard. Blood banks and legacy vaccine producers maintain dual-platform workflows to satisfy compendial arbitration requirements.
- Nucleic Acid Probes:Hybridization-based detection offers intermediate sensitivity between culture and amplification methods. Research institutes employ probes for species confirmation in contamination forensics.
Volume sits with PCR Kits; growth tilts toward Nucleic Acid Probes as multiplexed workflows expand.
Technology:
Platform selection hinges on the trade-off between speed for in-process control and comprehensiveness for root-cause investigation.
- Cell Culture:Direct cultivation on specialized media detects viable organisms with pharmacopoeial authority. European vaccine manufacturers retain this capability for regulatory submissions despite 28-day turnaround limitations.
- Molecular Diagnostics:PCR and digital PCR platforms dominate biopharmaceutical release testing. Autologous gene therapy producers in Switzerland and the United Kingdom deploy these systems for same-day contamination verdicts in cleanroom-adjacent laboratories.
- Next-Generation Sequencing:Massively parallel sequencing enables multiplexed species identification beyond presence-absence screening. Cell therapy CDMOs adopt NGS for contamination forensics where strain-level resolution guides corrective actions.
- Immunodiagnostics:Antibody-based detection serves screening applications with moderate sensitivity requirements. Research institutes in Japan apply immunofluorescence for rapid preliminary assessment.
Molecular Diagnostics commands current spending; Next-Generation Sequencing climbs the fastest as advanced therapy production scales.
End User:
Procurement authority and volume concentration vary sharply across laboratory types.
- Clinical Laboratories:Hospital-based and independent reference labs process patient specimens for infectious disease diagnosis. Laboratories in the United States face CLIA complexity that favors validated kit systems over in-house assay development.
- Research Institutes:Academic and government laboratories pursue method development and species characterization. Institutes in Germany and the Netherlands concentrate demand for sequencing platforms in contamination ecology studies.
- Pharmaceutical Companies:In-house quality control departments drive premium pricing for regulatory-grade reagents. Manufacturers in India expand testing capacity as CDSCO aligns with ICH Q5D pharmacopoeial standards.
- Blood Banks:Transfusion services screen donor units for mycoplasma contamination. Blood collection centers in Brazil and Argentina maintain culture-based workflows for cost containment.
Pharmaceutical Companies anchor revenue; Research Institutes expand most quickly as cell therapy research proliferates.
Application:
Risk tolerance and regulatory scrutiny shape technology deployment across use cases.
- Infectious Disease Diagnosis:Clinical detection of mycoplasma pneumoniae and genitalium in patient specimens. Diagnostic laboratories in Japan apply multiplex PCR panels for respiratory pathogen differentiation.
- Biopharmaceutical Production:In-process and release testing for cell culture contamination. Gene therapy manufacturers in the United States embed digital PCR at production lines to detect single-copy events.
- Vaccine Development:Cell substrate validation and adventitious agent screening. Developers in India and China invest in molecular platforms as national regulators tighten GMP enforcement.
- Environmental Testing:Monitoring of cleanroom air and surfaces for viable mycoplasma. Contract manufacturing organizations in Switzerland deploy rapid methods for continuous environmental surveillance.
Biopharmaceutical Production dominates current deployment; Vaccine Development gains share fastest as mRNA and viral vector manufacturing expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell culture media production clusters in the United States, Germany, and Switzerland anchor the mycoplasma diagnostics supply chain. Quality control outsourcing patterns concentrate demand in biopharmaceutical manufacturing corridors.
United States
Gene therapy manufacturers in Massachusetts and California drive point-of-need PCR adoption for autologous cell lines. FDA guidance on nucleic acid amplification methods for cell substrate testing accelerates platform conversion. The Boston-Cambridge corridor embeds digital PCR systems directly into cleanroom workflows.
Germany
EMA GMP Annex 1 revisions elevate molecular screening to default status for European release protocols. Vaccine producers in Marburg and Dessau maintain dual-platform workflows to satisfy pharmacopoeial arbitration requirements. The Rhine-Main biotech cluster concentrates CDMO demand for validated test kits.
Switzerland
Cell therapy CDMOs in Basel and Zürich deploy next-generation sequencing for contamination forensics. Swissmedic aligns with EMA rapid microbiological method acceptance criteria. The Basel biopharma corridor sustains premium pricing for regulatory-grade reagents.
India
Domestic vaccine and biosimilar producers in Hyderabad and Bengaluru expand testing capacity as CDSCO harmonizes with ICH Q5D standards. The country's national pharmaceutical regulator tightens GMP enforcement on cell substrate validation. The Genome Valley cluster attracts molecular platform investments from multinational kit suppliers.
China
mRNA and viral vector manufacturers in Suzhou and Shanghai invest in molecular platforms as NMPA elevates contamination control requirements. The Yangtze River Delta biopharma corridor scales in-house testing capabilities to reduce reference lab dependency. Suzhou Industrial Park concentrates demand for automated sample preparation systems.
Mycoplasma Diagnostics Market Competitive Environment
Strategic partnerships dominate the current landscape as platform providers align with contract manufacturing networks. The vendor base concentrates around integrated life science conglomerates and specialized contamination control firms. Three archetypes define competitive positioning: full-service reagent-to-instrument integrators, workflow automation specialists, and regulatory consulting bundlers. Technology licensing and geographic expansion through distribution agreements constitute the primary competitive moves.
Among diversified life science conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions spanning reagent supply through analytical instrumentation. Lonza Group AG exemplifies the CDMO-anchored workflow specialist model. Qiagen NV represents the sample preparation automation tier targeting mid-tier pharmaceutical quality laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Roche Diagnostics |
| Lonza Group AG |
| Charles River Laboratories International, Inc. |
| Qiagen NV |
| Bio-Rad Laboratories |
| Sartorius AG |
| Eurofins Scientific |
| Others |
Value Chain & Pricing Dynamics
Certified mycoplasma DNA calibrator costs cascade from three specialized suppliers through assay developers into tiered kit pricing, with regulatory-grade reagents commanding substantial premiums over research-use-only alternatives in biopharmaceutical quality laboratories.
Pricing Analysis
Service bundling separates diagnostic reagent supply from validation consulting, with North American quality departments increasingly procuring kits through distribution channels while engaging specialized consultancies for FDA pre-approval inspection support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with pharmaceutical companies least price-sensitive due to batch failure costs while research institutes face tightening budgets. Cost compression in mid-tier PCR workflows is intensifying because digital PCR platforms absorb high-sensitivity applications. Price differentiation hinges on ISO 17025 accreditation status and after-sales regulatory submission support.
Supply Chain Analysis
India's PLI scheme for domestic pharmaceutical manufacturing and China's NMPA localization requirements are reshaping sourcing patterns for reference standards and thermal cycler components. Manufacturing concentrates in the United States, Germany, and Switzerland for regulatory-grade reagents, with Singapore and South Korea anchoring automated sample preparation system assembly. The supply chain draws from specialized fermentation media suppliers, optical detection component manufacturers, and synthetic oligonucleotide producers. Single-source vulnerability concentrates among certified DNA calibrator suppliers. Distribution runs through authorized distributors with regulatory documentation capabilities into biopharmaceutical quality departments and CDMO procurement offices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FDA guidance on mycoplasma testing for cell substrates and EMA GMP Annex 1 revisions erect substantial compliance barriers that protect validated incumbents while freezing out underqualified competitors unable to sustain multi-year qualification timelines.
For Market Incumbents: Lock in long-term kit supply agreements with cell therapy CDMOs before NGS platform conversions accelerate, insulating recurring revenue streams from digital PCR displacement. Deepen backward integration into certified reference standard production to neutralize single-source supplier vulnerability. Prioritize automated sample preparation R&D to defend Qiagen's automation-centric positioning against Thermo Fisher's integrated platform bundling. For New Entrants and Emerging Players: Begin with point-of-need PCR miniaturization for cleanroom-adjacent cell therapy workflows, where battery-operated thermal cyclers collapse logistics chains and bypass entrenched central lab relationships. India's CDSCO harmonization with ICH Q5D creates the most penetrable geography among domestic vaccine and biosimilar producers previously reliant on informal testing. Pursue regulatory consulting partnerships as the primary go-to-market angle, bundling expedited qualification packages with reagent supply. For Investors and Strategic Acquirers: Distressed-cycle entries favor workflow automation specialists with installed base density in European cell therapy clusters, where EMA rapid microbiological method acceptance has elevated molecular screening to default status. Long-term viability hinges on platform transition timing as NGS-based release testing displaces PCR in advanced therapy applications. Monitor CDSCO enforcement intensity in India's Genome Valley as the inflection indicator for emerging geography re-rating.| Strategic Initiative | Industry Significance |
|---|---|
| NGS Platform Regulatory Qualification | Full EMA and FDA acceptance of sequencing for lot release unlocks premium pricing in cell therapy CDMO contracts. |
| Point-of-Need PCR Miniaturization | Battery-operated thermal cyclers enable at-line testing within cleanroom workflows, collapsing central lab logistics chains. |
| Reference Standard Backward Integration | In-house production of certified DNA calibrators neutralizes single-source supplier vulnerability for assay developers. |
| Automated Sample Preparation Expansion | Robotic nucleic acid extraction extends reach into mid-tier pharmaceutical quality labs with legacy LIMS constraints. |
| India CDSCO Harmonization Positioning | Validated kit supply partnerships with domestic vaccine producers capture pharmacopoeial standardization tailwinds. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with biopharmaceutical quality control directors, regulatory affairs leads at gene therapy manufacturers, CDMO procurement managers, and clinical laboratory accreditation specialists. FDA guidance documents, EMA GMP Annex 1 revisions, CDSCO circulars, and NMPA pharmacopoeial announcements provided regulatory trajectory inputs. Bottom-up triangulation across product-level kit shipments and top-down validation against biopharmaceutical manufacturing capacity expansion combined to cross-check volume estimates.
Granularity-level modeling deployed product type, technology platform, end-user concentration, and application context as core segmentation dimensions, with regional regulatory cluster and contamination risk tolerance as cross-cutting analytical layers. CAGRs were derived from fitted growth curves across the projection horizon, calibrated to cell therapy manufacturing capacity announcements and vaccine production facility investments. Forecast inputs incorporated digital PCR adoption rates in autologous gene therapy workflows and NGS contamination forensics penetration in CDMO service offerings.
Underlying measurement precision varies by segment; Next-Generation Sequencing and digital PCR carry tighter precision than legacy culture-based methods due to clearer shipment visibility. Forecasts reflect assumptions regarding regulatory acceptance timelines and platform conversion rates that could shift with accelerated FDA guidance revisions or EMA enforcement intensity variations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Argentina in Vitro Diagnostics Market
Diagnostics
Non-Alcoholic Steatohepatitis (NASH) Biomarkers Market
Diagnostics
Livestock Diagnostics Market
Diagnostics
Asia-Pacific Womens Health Diagnostics Market
Diagnostics
Neuro-Auto-Immune Disease Diagnostics Market
Diagnostics
North America Molecular Diagnostics Market
Diagnostics
Bilirubin Blood Test Market
Diagnostics
HIV Diagnostics Market
Diagnostics
Critical Care Diagnostics Market
Diagnostics
Mexico in-Vitro Diagnostics Market
Diagnostics
Breast Cancer Diagnostics Market
Diagnostics
Global Chlamydia Infection Diagnostics Market
Diagnostics
Predictive Disease Analytics Market
Diagnostics
Asia-Pacific Syndromic Multiplex Diagnostic Market
Diagnostics
Europe Blood Screening Market
Diagnostics
Global Lyme Disease Diagnostic Market