
 Thin Wall Mould Market | 2026-2036
Thin Wall Mould Market Size, Share, and Industry Trends Forecast 2026-2036
Thin Wall Mould Market Outlook
REACH compliance is consolidating the cost-of-entry calculus for European thin wall mould suppliers, forcing investment in certified material traceability and documentation systems. Berry Global Inc. leverages its vertical integration across resin sourcing and mould fabrication to sustain margin control under tightening chemical disclosure rules. Greiner Packaging International anchors its competitive position through specialized high-cavitation injection mould systems designed for dairy and food service applications.
Thin wall moulds are precision tooling systems engineered to produce plastic parts with wall thicknesses below 0.8 millimetres, utilizing high-speed injection processes with fill rates exceeding 500 millimetres per second to achieve structural integrity in minimal material volumes. These moulds serve primarily to reduce per-part resin consumption while maintaining dimensional stability for disposable packaging, consumer electronics housings, and automotive interior components. Injection moulds occupy the dominant share of product type demand, driven by their compatibility with multi-cavity configurations that maximize throughput in mass production environments. Polypropylene leads material consumption due to its flow characteristics and compatibility with thin wall geometries, though post-industrial recycled content grades are gaining traction among sustainability-focused end users.
FDA food contact regulations, EU REACH substance restrictions, and China's GB standards for plastic food packaging collectively shape material selection, mould design validation, and market access protocols across major supply corridors. The European Commission's Packaging and Packaging Waste Regulation proposal extends producer accountability to mould specification choices, compelling converters to document lifecycle impacts. Stakeholders must monitor evolving extended producer responsibility frameworks and recycled content mandates to align capital allocation with compliance trajectories.
Market Dynamics
Thin wall moulding economics hinge on resin-to-tooling cost ratios that REACH compliance and high-cavitation tooling investments are compressing simultaneously. European converters now face dual pressure: documenting full material provenance while justifying capital outlays for faster cycle-time equipment that offsets per-part resin savings erosion.
Growth Catalysts
- High-cavitation tooling:Dairy and food service packagers deploy 96- to 128-cavity mould systems to amortize tooling costs across billion-unit annual volumes. Fill-rate engineering above 500 millimetres per second enables structural integrity at sub-0.8 millimetre wall thicknesses.
- China's supply chain localization:Domestic appliance and electronics OEMs are qualifying local mould fabricators to reduce lead times and tariff exposure. This concentrates demand in Guangdong and Zhejiang tooling clusters.
- EU Packaging and Packaging Waste Regulation:Extended producer responsibility frameworks are forcing converters to document lifecycle impacts at mould specification stage, creating first-mover advantage for certified material traceability systems.
Market Restraints
- Engineering resin volatility:Polypropylene homopolymer and random copolymer grades face price swings tied to propylene monomer supply disruptions. Converters cannot fully pass through material cost spikes in fixed-price packaging contracts.
- Tooling supply concentration:Precision thin wall mould fabrication concentrates among German and Austrian specialist shops with multi-decade IP accumulation. New entrants face 18-24 month qualification timelines with major food packagers.
- Substitution by fibre-based packaging:Paperboard and molded fibre alternatives capture shelf-ready food service applications where barrier requirements permit. This erodes addressable volume in single-serve dairy and ready-meal segments.
Strategic Opportunities
- Post-industrial recycled polypropylene:Food-grade rPP with verified chain-of-custody documentation commands price premiums in European and North American markets. Mould designs accommodating higher viscosity recycled streams open new customer segments.
- Automotive interior lightweighting:EV manufacturers specify thin wall structural components for dashboard carriers and door panels to offset battery mass. This diversifies revenue beyond commoditized food packaging.
- Direct-to-moulder digital platforms:Online tooling specification and quoting systems compress procurement cycles from 12 weeks to 48 hours for standard cavity configurations. Early adopters capture mid-volume customers bypassing traditional distributor networks.
Industry Challenges
- Hot runner system integration:Maintaining thermal uniformity across 128+ drop manifolds requires specialized commissioning expertise that outstrips available field engineering capacity in emerging manufacturing regions.
- GB standard harmonization:China's SAMR food contact material approvals operate on timelines misaligned with EU REACH and US FDA clearance cycles, forcing parallel dossier preparation for exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thin Wall Mould Market |
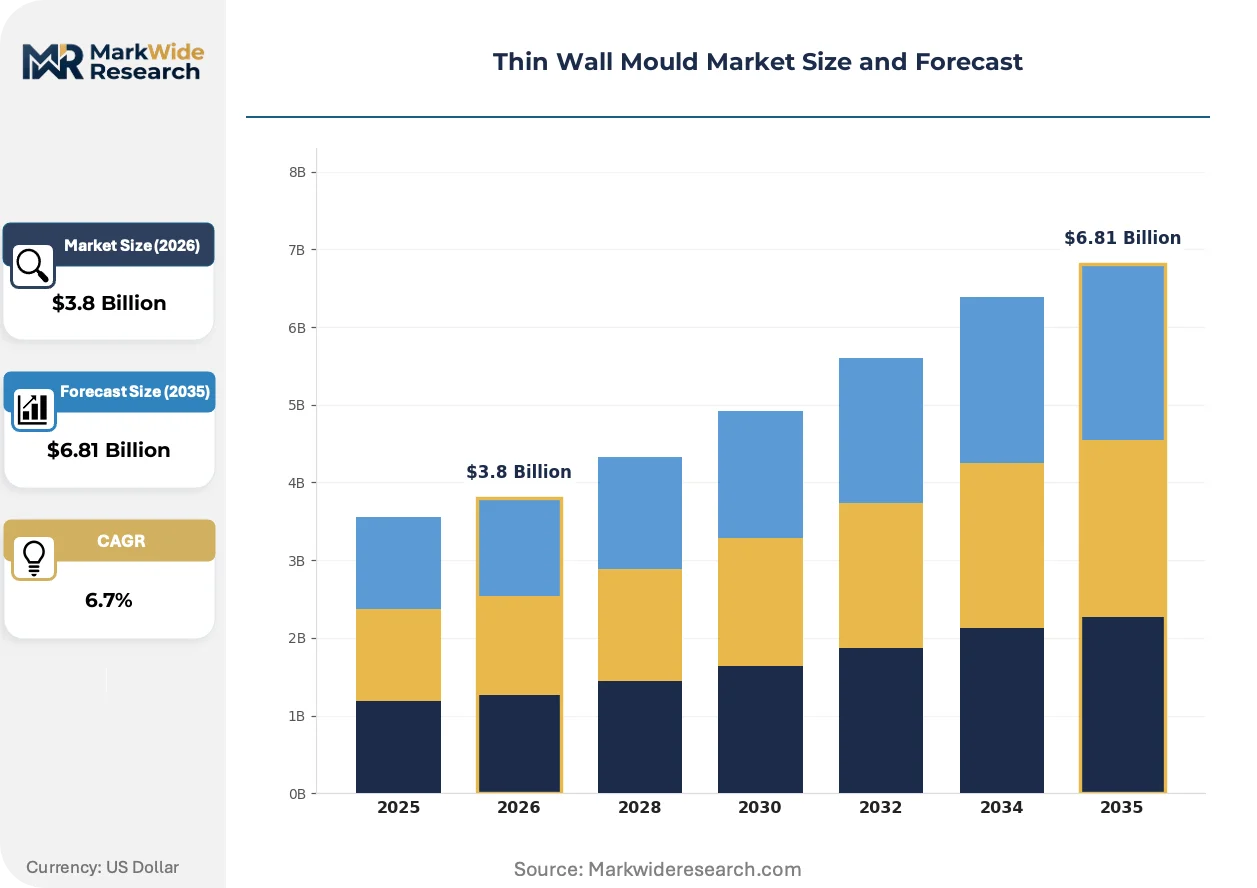
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Injection Moulds, Compression Moulds, Blow Moulds, Extrusion Moulds Material: Thermoplastic, Polypropylene, Polyethylene, Polystyrene End User: Packaging, Consumer Goods, Automotive Parts, Electronics Manufacturing Stage: Prototype Development, Mass Production, Post-Processing, Quality Control |
| Companies Covered | Berry Global Inc., EVCO Plastics, Otto Männer GmbH, Mold-Tek Packaging, Greiner Packaging International, Dahl-Tech, Inc., BEWI, Matrix Tool, Holly Plastic Parts, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thin Wall Mould Market Strategic Shifts
Active cooling channel geometries and in-mould sensors are compressing cycle-time benchmarks while regulatory disclosure requirements reshape material specification workflows. These intersecting forces favor capital-rich tooling specialists capable of simultaneous mechanical and digital innovation.
Conformal cooling channels produced through metal additive manufacturing are integrating into high-cavitation thin wall mould bases. Food packaging converters in Germany and the Netherlands adopt these designs to achieve 15-20% cycle time reductions on polypropylene dairy containers. The technology is integrating thermal management directly into cavity geometry, eliminating the performance ceiling of straight-drilled water lines.
REACH Article 33 substance disclosure thresholds are tightening across the EU supply chain. Mould specification now requires full SVHC screening of all contact materials and surface treatments. European dairy converters are responding by consolidating supplier bases to reduce documentation fragmentation, privileging vertically integrated resin-to-tooling providers.
Specification authority is migrating from brand owners to retail private-label procurement teams. Discounters and supermarket chains in France and the UK now mandate mould design validation against their own sustainability scorecards. This compresses converter margins while rewarding tooling investments that demonstrably reduce per-unit carbon footprints through material minimization.
Thin Wall Mould Market Segmentation
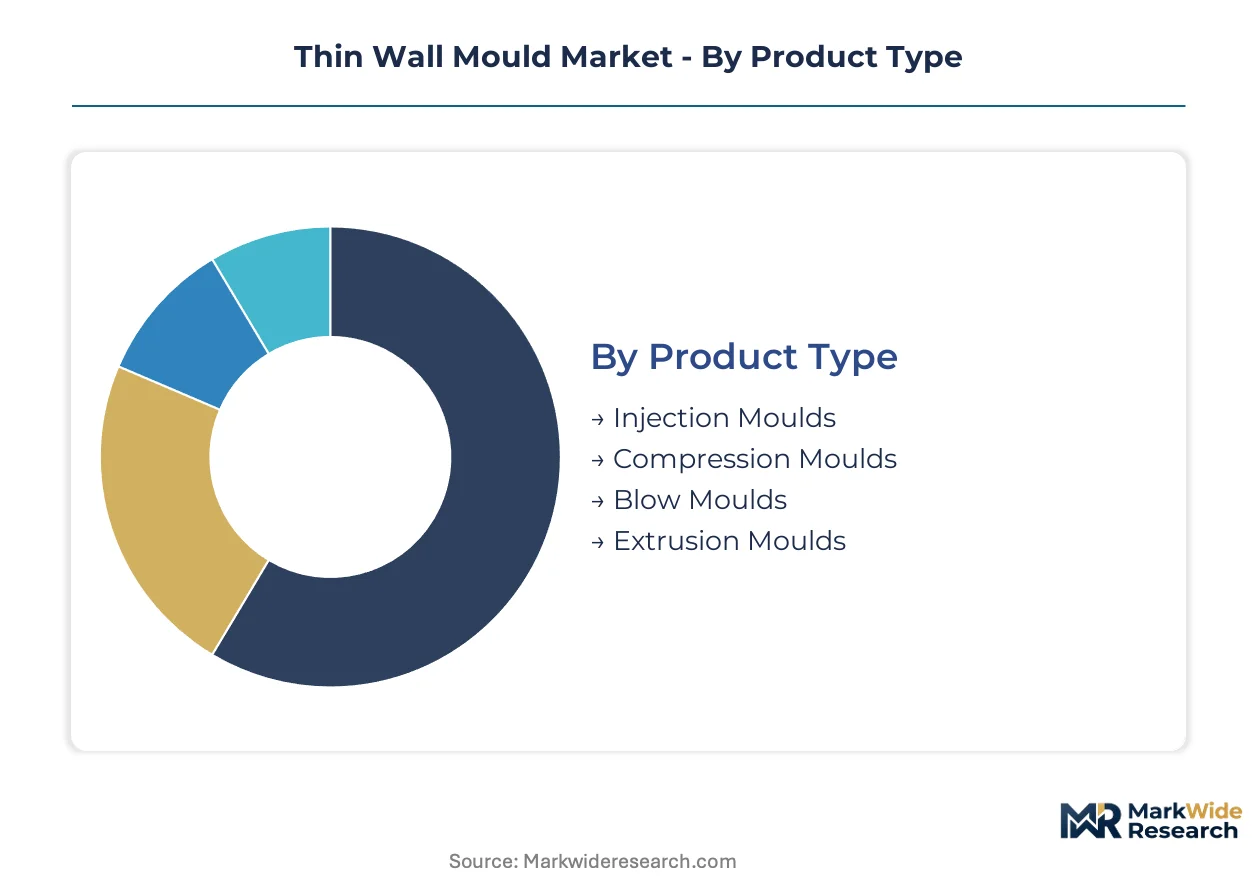
Thin wall mould procurement decisions pivot on cycle-time economics, material traceability requirements, and end-use regulatory exposure. Buyers prioritize tooling configurations that amortize capital costs across billion-unit volumes while satisfying evolving chemical disclosure mandates.
Product Type:
Tool selection hinges on fill-rate engineering tolerance and cavitation scalability for target resin systems.
- Injection Moulds:High-speed fill-rate engineering above 500 millimetres per second enables sub-0.8 millimetre wall thicknesses in polypropylene dairy containers. Dairy and food service packagers in Germany and the Netherlands deploy 96- to 128-cavity configurations to compress per-unit tooling amortization.
- Compression Moulds:Specialized for thermoset applications requiring dimensional stability under thermal stress. Automotive interior component manufacturers specify these for dashboard carriers where heat resistance outweighs cycle-time priority.
- Blow Moulds:Serve hollow-body packaging applications with moderate barrier requirements. Personal care and household chemical sectors specify these for bottle geometries.
- Extrusion Moulds:Deployed for continuous profile thin wall sections in automotive trim and appliance housings. Chinese appliance OEMs in Guangdong province qualify local fabricators to reduce lead times.
Injection Moulds lead on scale; Compression Moulds lead on momentum in automotive lightweighting applications.
Material:
Flow characteristics and regulatory clearance status dominate material specification workflows across converter operations.
- Thermoplastic:Broad category encompassing engineered polymers with melt flow indices optimized for thin wall geometries. FDA and EU REACH compliance documentation requirements are consolidating supplier selection toward certified resin providers.
- Polypropylene:Dominates food packaging applications due to superior flow properties and compatibility with high-cavitation tooling. Post-industrial recycled grades with verified chain-of-custody command price premiums in European markets.
- Polyethylene:Selected for flexible thin wall applications requiring impact resistance. Consumer goods manufacturers specify these for snap-fit closures and living hinge designs.
- Polystyrene:Retains position in transparent disposable food service items where optical clarity and cost minimization outweigh durability requirements. Discounters in France and the UK mandate sustainability scorecard validation for these specifications.
Polypropylene captures the highest volume allocation; post-industrial recycled grades are expanding most quickly under extended producer responsibility frameworks.
End User:
Regulatory exposure and volume predictability shape converter investment in dedicated tooling capacity.
- Packaging:Thin wall dairy containers and ready-meal trays drive billion-unit demand concentrations. EU Packaging and Packaging Waste Regulation documentation requirements are forcing lifecycle impact disclosure at mould specification stage.
- Consumer Goods:Electronics housings and personal care items demand aesthetic surface finish combined with structural integrity. OEMs in Zhejiang province localize supply chain qualification to reduce tariff exposure.
- Automotive Parts:EV manufacturers specify thin wall structural components to offset battery mass. Dashboard carriers and door panels represent emerging demand outside commoditized food packaging segments.
- Electronics:Miniaturized housings for mobile devices and wearables require precision tolerance control. Domestic appliance OEMs in China concentrate demand in Guangdong tooling clusters.
Packaging dominates absolute volume; Automotive Parts demonstrate the steepest expansion trajectory as EV lightweighting accelerates.
Manufacturing Stage:
Capital allocation timing and risk mitigation strategies vary across the production lifecycle.
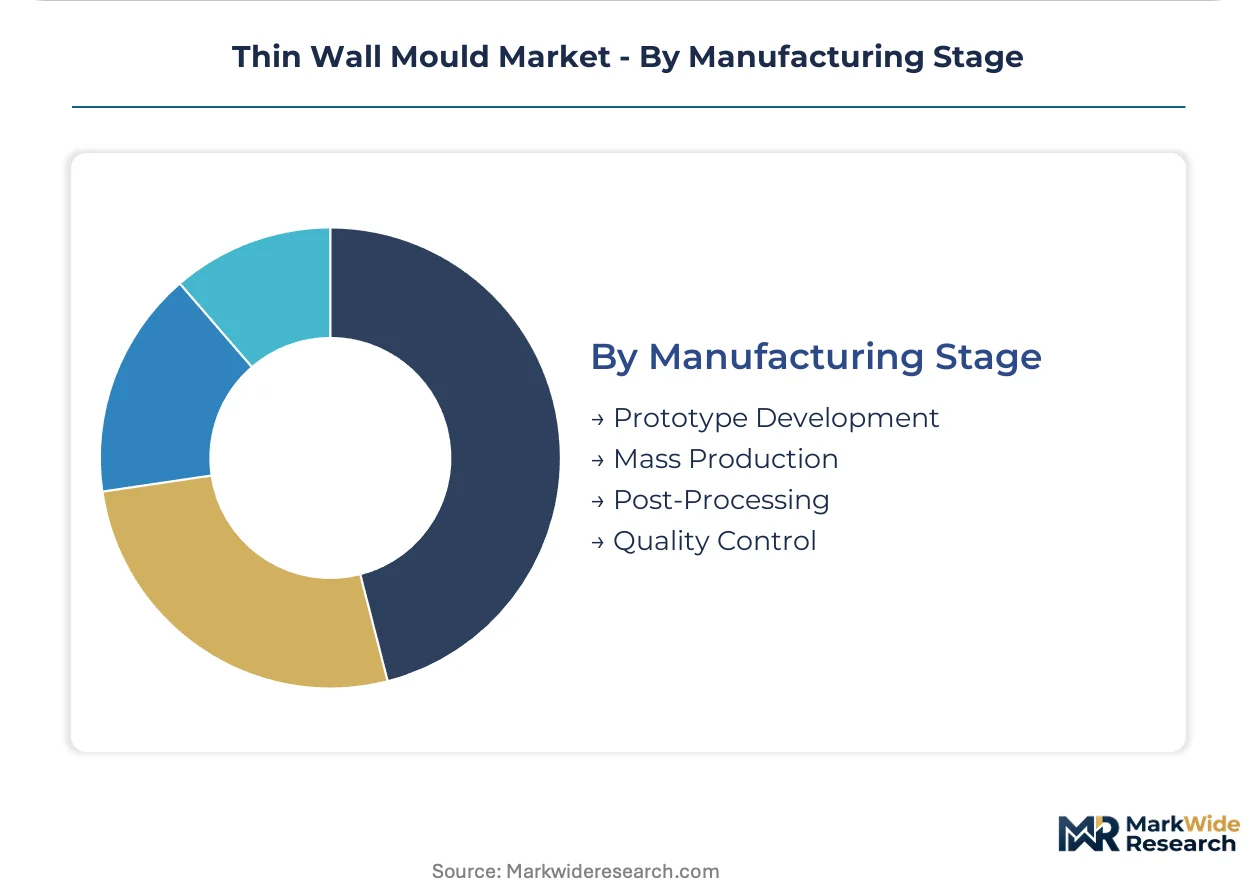
- Prototype Development:Rapid tooling iterations validate thin wall feasibility before mass production commitment. Additive-manufactured conformal cooling channel prototypes enable 15-20% cycle time optimization before hard tooling investment.
- Mass Production:High-cavitation systems amortize tooling costs across extended production runs. Food packagers achieve unit economics through 96- to 128-cavity polypropylene dairy container systems.
- Post-Processing:Automated trim and stack operations integrate with mould design to minimize secondary handling. European converters invest in inline quality systems to satisfy retailer sustainability scorecard requirements.
- Quality Control:In-mould sensor integration enables real-time dimensional monitoring during high-speed fill operations. REACH Article 33 substance disclosure mandates extend to surface treatments and contact materials validation.
Mass Production commands the largest capital deployment; Prototype Development is gaining share fastest as digital specification platforms compress procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thin wall mould fabrication originated in German precision tooling shops during the 1970s, establishing quality benchmarks that persist in today's high-cavitation dairy container systems. The industry now spans three continents with distinct regulatory and supply chain configurations shaping regional competitive positions.
Germany
Precision dairy packaging converters in Bavaria and Baden-Württemberg deploy 128-cavity injection systems for billion-unit annual volumes. REACH Article 33 substance disclosure mandates force comprehensive SVHC screening across all contact materials. The Stuttgart tooling cluster concentrates specialized hot runner integration expertise that emerging manufacturing regions struggle to replicate.
China
Domestic appliance OEMs in Guangdong province and electronics manufacturers in Zhejiang province localize mould qualification to compress lead times and mitigate tariff exposure. SAMR's GB standards for food contact materials operate on approval timelines misaligned with EU REACH cycles, forcing parallel dossier preparation. Shenzhen and Dongguan tooling clusters now supply high-cavitation systems for regional consumer goods production.
United States
Food service packagers in the Midwest and Southeast specify thin wall containers under FDA food contact regulations with stricter documentation than historical norms. The EPA's emerging attention to per- and polyfluoroalkyl substances influences surface treatment selection in mould specification. Chicago and Detroit industrial corridors host tooling fabricators serving automotive interior lightweighting programs for EV manufacturers.
Netherlands
Dairy converters in North Brabant adopt conformal cooling channel geometries to achieve 15-20% cycle time reductions on polypropylene containers. The EU Packaging and Packaging Waste Regulation proposal extends producer accountability to mould specification choices, compelling lifecycle impact documentation. Eindhoven's advanced manufacturing ecosystem supports metal additive manufacturing integration into high-cavitation mould bases.
India
Food packaging converters in Maharashtra and Gujarat qualify thin wall systems for domestic dairy and ready-meal segments under FSSAI regulations. The PLI scheme for specialty chemicals indirectly supports precision tooling material supply chains. Mumbai-Pune industrial corridor fabricators increasingly serve regional appliance OEMs seeking localized mould procurement.
Thin Wall Mould Market Competitive Environment
The competitive structure tilts toward vertically integrated resin-to-tooling providers capable of certifying full material provenance under tightening disclosure rules. Three archetypes dominate: multi-national packaging conglomerates with captive mould fabrication, specialized German-Austrian precision tooling houses with multi-decade IP accumulation, and emerging Asian fabricators leveraging geographic proximity to appliance and electronics OEMs. Competitive moves concentrate on supplier base consolidation to reduce documentation fragmentation and qualification timeline compression through digital specification platforms.
Within the integrated packaging tier, Berry Global Inc. and Greiner Packaging International exemplify archetypes combining resin sourcing control with mould design validation. Otto Männer GmbH represents the precision tooling house category with German engineering lineage. These three occupy positions reflecting distinct strategic bets: captive supply chain control versus specialized high-cavitation engineering versus regional proximity to demand concentration.
| Leading Market Players |
|---|
| Berry Global Inc. |
| EVCO Plastics |
| Otto Männer GmbH |
| Mold-Tek Packaging |
| Greiner Packaging International |
| Dahl-Tech, Inc. |
| BEWI |
| Matrix Tool |
| Holly Plastic Parts |
| Others |
Value Chain & Pricing Dynamics
REACH Article 33 substance disclosure thresholds gate both qualified thin wall mould supply and premium-tier pricing access, forcing converters to consolidate supplier bases toward vertically integrated resin-to-tooling providers capable of certifying full material provenance. European dairy packagers now pay documentation premiums for 128-cavity systems with verified SVHC screening, while standard-tier fabricators without traceability systems face margin compression from fixed-price contract exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified material traceability systems from conventional tooling and commodity-grade alternatives. Premium tiers command documentation premiums through REACH-compliant SVHC screening and post-industrial recycled polypropylene compatibility, while price differentiation stems from cavitation scale and thermal management sophistication. Pricing pressure stems from engineering resin volatility that converters cannot fully pass through in fixed-price packaging contracts. Discounters and supermarket chains in France and the UK exhibit highest price sensitivity through sustainability scorecard mandates, whereas automotive EV programs demonstrate lowest sensitivity due to lightweighting value capture.
Supply Chain Analysis
Refurbishment flows for high-cavitation hot runner manifolds create secondary supply channels that extend tooling lifecycle and compress effective replacement demand. Precision thin wall mould fabrication concentrates in Germany, Austria, and China, with Guangdong and Zhejiang clusters serving domestic appliance OEMs. Raw material dependencies rest on specialized tool steel grades, precision-machined hot runner components, and certified polypropylene resin streams. Single-source vulnerability concentrates among German and Austrian specialist shops with multi-decade IP accumulation in 128-cavity dairy systems. Distribution runs through direct converter relationships for high-cavitation configurations and digital specification platforms for standard cavity ranges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin wall mould economics present margin-expansion pathways through cycle-time compression via conformal cooling channel adoption and premium-tier pricing for certified material traceability systems. Converters capturing 15-20% cycle reductions command pricing power under tightening EU Packaging and Packaging Waste Regulation documentation requirements.
For Market Incumbents: Acquire specialized hot runner integration expertise to defend against emerging Asian fabricators compressing qualification timelines. Consolidate supplier bases to reduce REACH documentation fragmentation while investing in metal additive manufacturing capacity for conformal cooling channel production. Capacity expansion in Guangdong tooling clusters captures China's supply chain localization momentum among domestic appliance OEMs. For New Entrants and Emerging Players: Launch via direct-to-moulder digital platforms targeting mid-volume food service packagers bypassing traditional distributor networks. White-space concentration exists in automotive interior lightweighting for EV dashboard carriers, where barrier-to-entry from food-packager qualification timelines does not apply. Post-industrial recycled polypropylene-compatible mould designs open European sustainability-focused segments with less incumbent saturation. For Investors and Strategic Acquirers: Roll-up economics work for precision tooling houses with multi-decade IP accumulation because 18-24 month food packager qualification timelines protect installed base revenue. Long-term viability hinges on positioning for extended producer responsibility framework expansion beyond current EU coverage. Monitor SAMR GB standard harmonization progress with EU REACH cycles as inflection indicator for parallel dossier preparation cost structures affecting exporter profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Sourcing | Captures margin control under REACH substance disclosure mandates while securing post-industrial recycled polypropylene supply. |
| Metal Additive Manufacturing Adoption | Enables conformal cooling channel geometries that compress cycle times 15-20% on polypropylene dairy containers. |
| Digital Specification Platform Launch | Compresses procurement cycles from 12 weeks to 48 hours for standard cavity configurations targeting mid-volume converters. |
| Automotive Lightweighting Capacity Expansion | Diversifies revenue beyond commoditized food packaging into EV structural component programs with higher margin retention. |
| Certified Material Traceability System Investment | Creates first-mover advantage under EU Packaging and Packaging Waste Regulation lifecycle impact documentation requirements. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with mould procurement managers at dairy converters, hot runner system engineers, automotive Tier 1 supplier sourcing leads, and digital platform operators with secondary validation. Secondary sources included customs and trade data for tooling imports, ECHA REACH substance database filings, SEC 10-K disclosures from integrated packaging conglomerates, and SAMR GB standard approval records. Bottom-up modelling of cavity configuration demand and top-down triangulation against resin consumption patterns anchored value estimates.
Segment-weighting applied product type, material grade, end-use vertical, and manufacturing stage dimensions across the projection horizon. Injection mould share, polypropylene flow characteristic compatibility, and high-cavitation system penetration shaped analytical framework construction. CAGRs derived from tooling investment cycles, OEM localization patterns, and regulatory compliance cost trajectory modelling. Forecast inputs incorporated SAMR-EU regulatory timeline misalignment effects and conformal cooling adoption curves from German and Dutch dairy converter pilots.
Forecast precision tightens around the base case; tail outcomes carry wider variance under propylene monomer supply disruption scenarios and accelerated fibre-based packaging substitution in single-serve dairy segments. Practitioners should monitor ECHA SVHC candidate list expansion velocity and China's dual carbon goal implementation stringency for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Plumbing Fixtures Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
Advanced Building Materials Market
Building & Construction Materials
Plastic Formwork Market
Building & Construction Materials
Glass Tiles Market
Building & Construction Materials
North America Concrete Cellulose Fiber Reinforcement Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
EMEA Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Wood Panel Market
Building & Construction Materials
Sheet Piling Market
Building & Construction Materials
Foldable Container House Market
Building & Construction Materials
Global Anchors and Grouts Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
India Particle Board Market