
 Recording Chart Paper Market | 2026-2036
Recording Chart Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Recording Chart Paper Market Outlook
The capability gap between integrated paper-coating operations and merchant converters is unwinding competitive stability across the sector. Cardinal Health leverages its hospital supply chain control to secure long-term thermal paper contracts. Kokusai Chart Co. anchors its position through precision coating technology for medical charting grades. Graphic Controls LLC specializes in continuous-form products for industrial monitoring equipment.
Recording chart paper comprises thermally sensitive or pre-printed graph substrates engineered with defined basis weights, coating chemistries, and dimensional tolerances for analog or digital recording instruments. Thermal paper dominates clinical applications where direct imaging eliminates ink systems, while analytical paper retains share in research labs requiring manual data annotation. Roll formats lead volume due to compatibility with bedside monitors and process control recorders, though sheet demand persists in educational testing environments where individual worksheets support standardized protocols.
FDA medical device regulations mandate archival-grade traceability for patient monitoring outputs, while EPA protocols require tamper-evident documentation in environmental compliance reporting. ISO 14155 standards for clinical investigation records further shape product specifications across export markets. Stakeholders must monitor how digital charting adoption in healthcare systems reshapes volume requirements without eliminating redundant paper backup mandates.
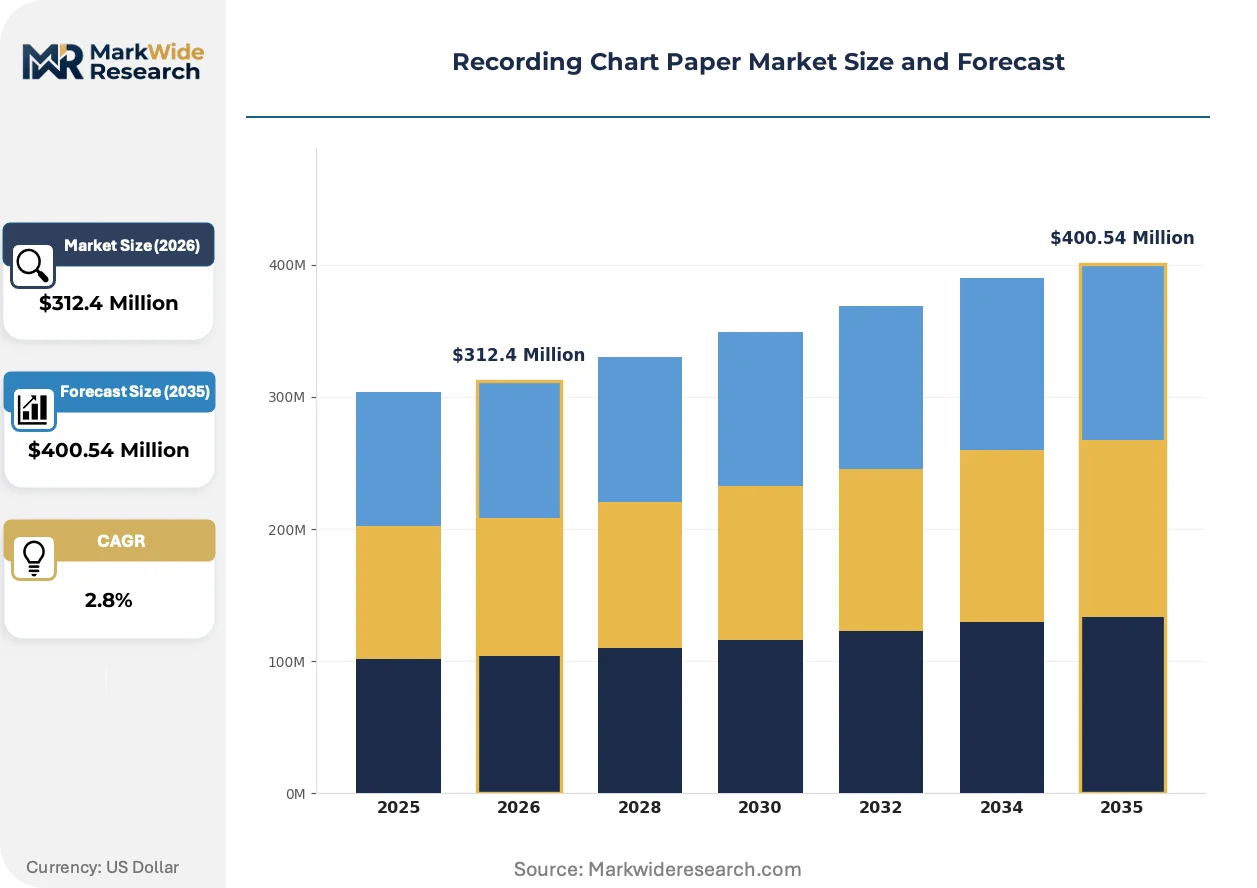
Market Dynamics
Digital charting adoption in hospital systems is decomposing volume assumptions while FDA backup mandates preserve baseline demand, creating a bifurcated demand structure where thermal coating specialists compete on archival-grade specifications.
Growth Catalysts
- FDA 21 CFR Part 11 archival mandates:Patient monitoring outputs require tamper-evident paper trails that thermal recording formats satisfy. Hospital systems in the United States maintain dual documentation protocols.
- Continuous process manufacturing expansion:Pharmaceutical batch release documentation drives analytical-grade chart consumption. FDA process analytical technology guidelines reinforce paper traceability.
- Environmental compliance monitoring:EPA air quality surveillance networks deploy continuous emissions monitoring systems. Industrial facilities in Germany and Japan generate recurring roll-format demand.
Market Restraints
- Bisphenol A coating chemistry restrictions:ECHA substance evaluation pressures thermal paper formulations. Converter margins compress under reformulation R&D burdens.
- Merchant converter supply concentration:Three coating specialists control precision medical-grade supply. Buyers face single-source risk for FDA-validated substrates.
- Digital display substitution in industrial HMI:Touchscreen process visualization eliminates redundant paper recorders. Food processing plants accelerate screen-based operator interfaces.
Strategic Opportunities
- India clinical trial documentation expansion:CDSCO good clinical practice enforcement drives chart paper demand. Contract research organizations localize sourcing.
- ISO 14155 export certification alignment:European clinical investigation standards create specification premiums. Coaters validating to medical device regulation capture margin.
- Phenol-free thermal chemistry convergence:Bisphenol S and Pergafast alternatives mature simultaneously. Early adopters secure regulatory-ready product pipelines.
Industry Challenges
- Coating technician skill scarcity:Precision thermal layer application requires specialized calendering expertise. Training pipelines lag medical-grade capacity expansion.
- FDA 510(k) companion diagnostic timeline:New thermal formulations trigger extended device validation cycles. Coaters absorb documentation costs without guaranteed volume.
- Legacy recorder fleet compatibility:Decades-old bedside monitors constrain substrate dimensional tolerances. Manufacturers maintain obsolete format production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Recording Chart Paper Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $400.54 Million |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermal Paper, Graph Paper, Analytical Paper, Multi-Functional Paper End User: Medical Facilities, Educational Institutions, Research Labs, Automation Industry Format: Rolls, Sheets, Pads, Continuous Forms Application: Medical Charting, Educational Testing, Industrial Monitoring, Environmental Analysis |
| Companies Covered | Cardinal Health, Precision Charts Inc., Thomas Scientific, Merck KGaA, Tele-Paper Malaysia, Pirrone SRL, Kokusai Chart Co., Graphic Controls LLC, Dart Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Recording Chart Paper Market Strategic Shifts
Thermal chemistry reformulation and digital-paper hybrid protocols are restructuring competitive advantage around regulatory pre-certification rather than commodity scale.
Next-generation phenol-free thermal coatings is decomposing the bisphenol A supply base. Hospital procurement groups in Germany and Japan are accelerating qualification timelines. Coaters with validated BPS-free formulations are capturing preference premiums while legacy chemistry specialists face reformulation cliffs.
REACH substance restriction proposals are forcing coating chemistry transparency across European supply chains. ECHA harmonized classification obligations now extend to thermal paper import declarations. Medical device distributors are demanding full material disclosure from Japanese and US coating operations serving EU clinical markets.
Consolidated health system procurement is compressing supplier rosters to single-source thermal paper contracts. Group purchasing organizations in the United States are unbundling chart paper from broader medical supply agreements. Cardinal Health and similar distributors are capturing category management roles that displace direct mill relationships.
Recording Chart Paper Market Segmentation
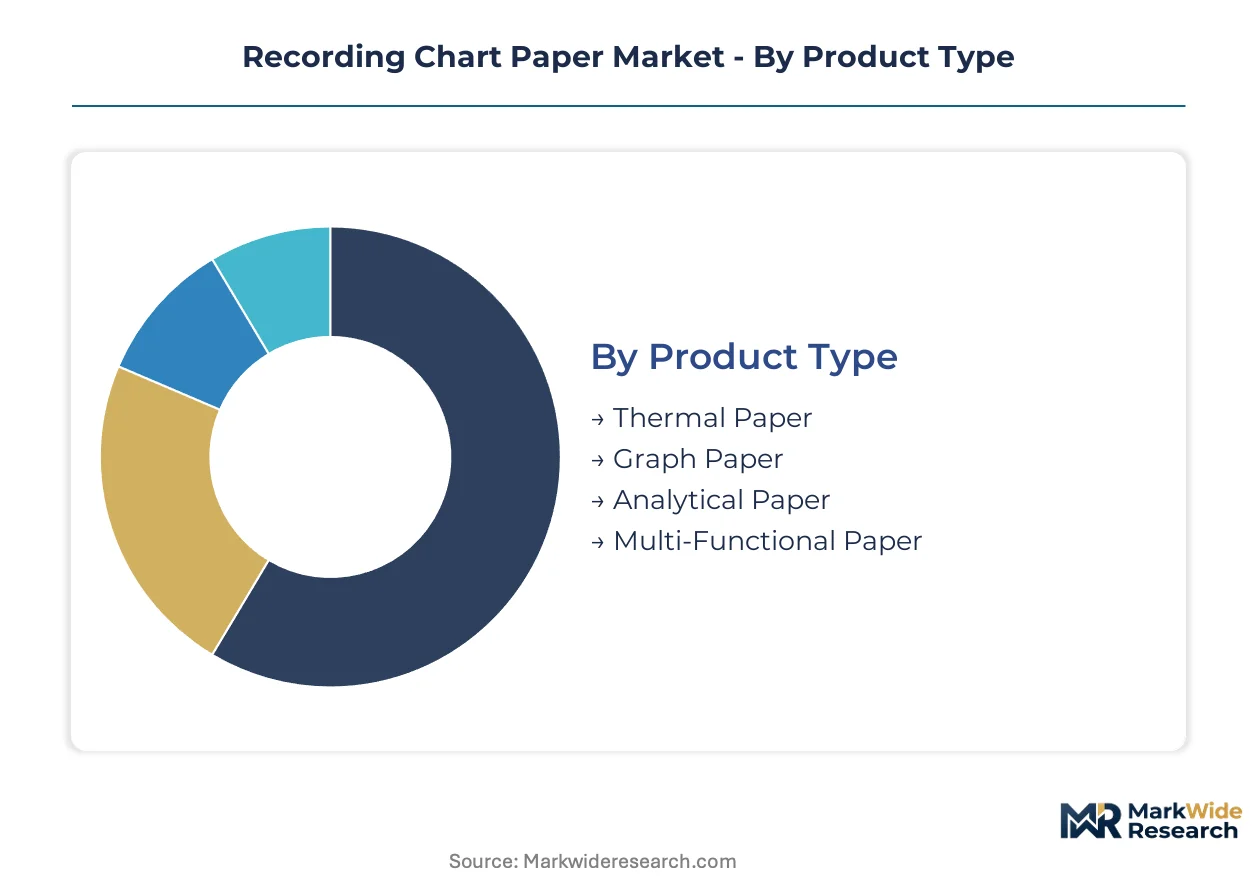
Thermal coating chemistry and FDA archival mandates create divergent margin pools across product categories. Hospital procurement consolidation rewards validated suppliers while digital substitution pressures commodity formats.
Product Type:
Premium margins concentrate in medical-grade thermal substrates where coating precision determines regulatory acceptance.
- Thermal Paper:Leuco dye-based coatings with phenol-free chemistry variants dominate bedside monitors and process recorders. FDA 21 CFR Part 11 mandates in the United States preserve demand for tamper-evident thermal outputs despite EMR expansion.
- Analytical Paper:Pre-printed grid substrates with defined basis weights support manual data annotation in pharmaceutical batch release documentation. Continuous process manufacturing in Germany generates recurring consumption for validated analytical grades.
- Graph Paper:Standard grid substrates serve educational testing and research applications with lower specification barriers.
- Multi-Functional Paper:Hybrid coatings compatible with multiple imaging technologies address legacy instrument fleets in industrial settings.
The dominant share belongs to Thermal Paper, while Analytical Paper is closing the gap fastest.
End User:
Procurement scale and validation requirements separate hospital system contracts from fragmented academic purchasing.
- Medical Facilities:Group purchasing organizations in the United States consolidate thermal paper contracts through distributors like Cardinal Health. Dual documentation protocols mandate redundant paper backup alongside digital charting systems.
- Automation Industry:Continuous emissions monitoring systems in Japanese industrial clusters generate roll-format demand for environmental compliance reporting. EPA protocol adherence requires tamper-evident documentation.
- Research Labs:Academic and pharmaceutical research maintains analytical paper consumption for manual data verification.
- Educational Institutions:Standardized testing protocols drive sheet-format demand with price-sensitive procurement.
Medical Facilities command the largest volume position, though Automation Industry demand is expanding most quickly.
Format:
Roll production economies and legacy instrument compatibility shape competitive positioning across dimensional specifications.
- Rolls:Continuous substrates compatible with bedside monitors and process control recorders dominate clinical and industrial volume. Decades-old installed base constrains dimensional tolerance requirements.
- Continuous Forms:Fan-folded formats serve industrial data loggers and environmental monitoring networks in German manufacturing facilities.
- Sheets:Individual worksheets support standardized educational testing protocols with lower technical specifications.
- Pads:Bound sheet formats address portable instrumentation and field research applications.
Rolls maintain entrenched volume leadership, while Continuous Forms gain traction in process manufacturing documentation.
Application:
Regulatory stringency tiers separate medical archival mandates from industrial compliance and educational protocols.
- Medical Charting:Patient monitoring outputs require ISO 14155-aligned traceability for clinical investigation records. Japanese hospital systems enforce stringent coating chemistry disclosure under import declaration rules.
- Industrial Monitoring:Pharmaceutical batch release and process analytical technology documentation drives analytical-grade consumption. FDA guidelines reinforce paper traceability in continuous manufacturing.
- Environmental Analysis:EPA air quality surveillance networks deploy continuous emissions monitoring with recurring roll demand.
- Educational Testing:Standardized worksheet protocols persist in assessment environments with limited technical barriers.
Medical Charting retains the highest value concentration, with Industrial Monitoring showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in German hospital systems demonstrate the lowest price elasticity, absorbing specification premiums for REACH-compliant thermal substrates, while educational procurement in India operates at the highest sensitivity, prioritizing cost over archival-grade chemistry.
United States
FDA 21 CFR Part 11 mandates for patient monitoring backup documentation sustain thermal paper demand across hospital systems. Group purchasing organizations consolidate contracts through distributors, compressing supplier rosters toward single-source relationships. The Cleveland Clinic and Mayo Clinic clusters in Ohio and Minnesota enforce stringent coating chemistry disclosure protocols.
Germany
Continuous process manufacturing in pharmaceutical hubs drives analytical-grade chart consumption for batch release documentation. ECHA substance evaluation pressures under REACH force reformulation toward phenol-free thermal chemistry. The Rhine-Main industrial corridor hosts precision coating operations serving EU clinical investigation markets.
Japan
METI import declaration rules and PMDA medical device traceability requirements tighten paper documentation standards. Environmental compliance monitoring networks deploy continuous emissions systems with recurring roll demand. The Kanto region around Tokyo concentrates bedside monitor manufacturing and hospital system procurement.
India
CDSCO good clinical practice enforcement drives chart paper demand from contract research organizations localizing sourcing. Price-sensitive educational testing procurement dominates sheet-format consumption with lower technical barriers. Maharashtra and Karnataka host expanding clinical trial documentation operations serving multinational pharma sponsors.
United Kingdom
NHS procurement consolidation shifts thermal paper purchasing toward framework agreements with validated EU coaters. ISO 14155-aligned clinical investigation records sustain premium-grade demand from research hospitals. The Greater Manchester and London health clusters maintain dual documentation protocols alongside EMR expansion.
Recording Chart Paper Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with coating precision and regulatory pre-certification determining competitive position. Hospital supply chain distributors leverage category management roles to displace direct mill relationships. Three archetypes dominate: integrated health supply distributors, precision coating specialists, and merchant converters serving industrial instrumentation. Competitive moves concentrate on strategic partnerships for regulatory validation and geographic expansion into clinical trial growth markets.
Among Japan-based specialists, Kokusai Chart Co. exemplifies the precision coating archetype through its focus on medical charting grades. Cardinal Health occupies a position within the integrated distributor tier, leveraging hospital supply chain control for contract consolidation. Graphic Controls LLC represents the industrial instrumentation specialist segment, with its concentration on continuous-form products for process monitoring equipment.
| Leading Market Players |
|---|
| Cardinal Health |
| Precision Charts Inc. |
| Thomas Scientific |
| Merck KGaA |
| Tele-Paper Malaysia |
| Pirrone SRL |
| Kokusai Chart Co. |
| Graphic Controls LLC |
| Dart Technologies |
| Others |
Value Chain & Pricing Dynamics
Phenol-free thermal chemistry substitution in coating formulations is simultaneously shifting supply geography toward REACH-compliant production hubs in Germany and Japan while compressing pricing economics for legacy bisphenol A converters facing reformulation R&D burdens.
Pricing Analysis
After-sales service contracts for FDA-validated thermal paper supply anchor lifetime value capture in hospital procurement relationships. Three-tier pricing structure across medical-grade certified, industrial-standard, and educational-economy levels stratifies the market, with FDA 21 CFR Part 11 archival certification commanding substantial premiums over commodity formats. Cost compression in standard thermal grades is intensifying because merchant converter supply concentration limits buyer leverage. Educational procurement in India exhibits the highest price sensitivity, while German hospital systems absorb specification premiums for ECHA-compliant substrates with minimal elasticity.
Supply Chain Analysis
Japan and Germany anchor precision thermal coating operations serving medical-grade chart paper demand, while the United States hosts integrated health supply distributors controlling hospital procurement channels. Leuco dye chemistries, phenol-free developers, and specialty base papers constitute critical input dependencies. Single-source vulnerability concentrates in FDA-validated substrate supply where three coating specialists dominate precision medical-grade production. Distribution runs through group purchasing organizations and health system distributors rather than direct mill relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The recording chart paper market functions as a defensive-moat story where regulatory entrenchment—specifically FDA archival mandates and REACH chemistry compliance—creates durable barriers against digital substitution and commodity competition.
For Market Incumbents: Shield market position through backward integration into phenol-free coating chemistry production and captive supply of REACH-compliant substrates. The bisphenol A reformulation cliff threatens merchant converters lacking validated alternative chemistries. Capacity addition in Germany and Japan secures proximity to highest-value hospital procurement clusters. For New Entrants and Emerging Players: Phenol-free thermal chemistry technical service gaps where incumbent coaters under-serve contract research organizations in India present accessible white-space targets. CDSCO good clinical practice enforcement drives localized documentation demand with lower certification barriers than FDA-validated supply. A technical service partnership model with multinational pharma sponsors offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed precision coating specialists holding ISO 14155 export certification. Long-term viability hinges on regulatory chemistry entrenchment rather than volume scale. The priority acquisition archetype combines phenol-free formulation validation with established hospital distributor relationships. The signal to watch is ECHA substance restriction proposal advancement accelerating reformulation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Phenol-Free Chemistry Validation | ECHA REACH compliance secures premium positioning in German hospital procurement. |
| ISO 14155 Export Certification | European clinical investigation standards unlock margin capture in research hospital segments. |
| Hospital System Partnership | Group purchasing organization alignment displaces direct mill relationships in United States. |
| Backward Integration into Coating | In-house thermal layer production insulates margins from merchant converter supply risk. |
| CDSCO Compliance Localization | India clinical trial documentation expansion addresses contract research organization sourcing needs. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) device filings, ECHA substance evaluation databases, and hospital procurement contract disclosures. Primary interviews engaged thermal coating R&D directors, health system GPO contracts managers, biomedical equipment engineers, and pharmaceutical quality assurance leads. Secondary validation drew from EPA emissions monitoring protocol documentation, ISO 14155 clinical investigation standards, and customs trade data for thermal paper substrate flows. Bottom-up volume modeling triangulated against top-down market sizing across product and regional segments.
Segmentation dimensions modeled include coating chemistry tier, end-use application, format specification, and regional regulatory cluster. CAGRs were derived through trend extrapolation of hospital digital charting adoption rates, industrial process monitoring equipment deployment, and environmental compliance monitoring network expansion. Industry-specific forecast inputs incorporated FDA backup documentation mandate stability and ECHA bisphenol A restriction proposal timelines across the analysis window.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11 archival requirements and REACH substance evaluation protocols; material policy shifts in these regimes would require re-modeling. Specific risks include accelerated digital charting adoption eliminating redundant paper backup mandates, or ECHA chemistry restrictions outpacing phenol-free formulation maturity. Recalibration cycles align with material shifts in regulatory proposal advancement and hospital procurement consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
GCC Stone Paper Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Softwood Pulp Market
Paper Products
Office Printing Papers Market
Paper Products
Insulation Paper Market
Paper Products
Acrylic Paper Market
Paper Products
Medical Grade Paper Market
Paper Products
Unbleached Kraft Pulp Market
Paper Products
Pharma Grade Paper Market
Paper Products
Africa Tissue Paper Market
Paper Products
Middle East and Africa Decor Paper Market
Paper Products
Ceramic Paper Market
Paper Products
Unbleached Hardwood Kraft Pulp Market
Paper Products
GCC Paper Products Market
Paper Products
Woodfree Paper Market
Paper Products
Saturated Kraft Paper Market